

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hydrogen Sulfide Scavengers Market: Inside the 3.44% CAGR Upside to 2032

The Hydrogen Sulfide Scavengers Market: Navigating Growth, Regulation, and Chemical Innovation
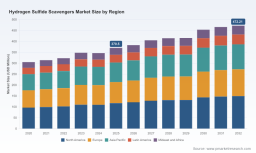
Hydrogen sulfide remains one of the most persistent operational and safety hazards across oil and gas production, gas processing, and wastewater treatment. The compounds corrosive nature, toxicity, and tendency to form metal sulfides make its control a non-negotiable requirement for compliant and efficient operations. Against this backdrop, the global market for hydrogen sulfide scavengers has settled into a measured but steady growth trajectory, expanding from approximately 305 million USD in 2020 to an estimated 370.5 million USD in 2025, with projections reaching roughly 472 million USD by 2032. The implied compound annual growth rate of 3.44 percent over the 2025 to 2032 forecast window reflects a market that is maturing rather than exploding, driven less by explosive volume demand and more by regulatory tightening, operational optimization, and incremental chemical innovation.
For executives and investors, the central takeaway is that this is not a high-growth novelty segment but a stable, regulation-anchored specialty chemicals market with meaningful margin potential for players who can differentiate on performance, safety, and total cost of ownership. The challenge lies in recognizing where the growth pockets are forming, which product architectures are gaining ground, and how leading suppliers are repositioning themselves in a landscape marked by fragmented demand, supply chain friction, and increasingly stringent emission controls.
Market Structure and Core Challenges
The market's evolution over the 2020 to 2025 period tells a story of resilience amid volatility. Revenue growth from 305.21 million USD in 2020 to 347.92 million USD in 2023, followed by a modest contraction to 346.36 million USD in 2024 before rebounding to 370.5 million USD in 2025, underscores how external shocks can temporarily disrupt even essential chemical supply chains. That 2024 dip, while relatively small in percentage terms, signals the market's sensitivity to raw material availability and pricing, particularly for triazine-based formulations that dominate high-volume applications. The rebound in 2025 suggests that demand fundamentals remain intact and that operators are unwilling to delay H2S control investments given the safety and compliance stakes involved.
Several structural challenges define the current inflection point. First, raw material dependency and supply chain vulnerability continue to shape pricing dynamics and product availability. The market relies heavily on precursor chemicals such as ethylene oxide and related intermediates for triazine-based scavengers. A plant incident in 2023 triggered shortages and price increases for these formulations, a disruption that rippled through procurement cycles well into 2025. This fragility has forced operators and suppliers alike to reconsider single-source dependencies and to evaluate alternative chemistries that can reduce exposure to precursor volatility.
Second, regulatory fragmentation across regions creates a complex compliance environment. In the United States, the Toxic Substances Control Act and related EPA and OSHA mandates increase the compliance burden for facilities handling sour streams, while Bureau of Safety and Environmental Enforcement rules under 30 CFR 250.490 require operators on the U.S. Outer Continental Shelf to maintain H2S scavengers on facilities and deploy them upon detection. In Europe, Directive 2016/2284 sets emission limits that drive H2S control requirements across industrial applications. In the Middle East and Africa, GSO ISO 8819:2013 provides regional standards for H2S treatment processes. These overlapping requirements mean that a one-size-fits-all product strategy is rarely sufficient; suppliers must navigate differing thresholds, testing protocols, and documentation expectations across jurisdictions.
Third, the market must balance performance against cost and environmental considerations. Traditional triazine-based scavengers offer effective H2S removal but can generate sludge, introduce nitrogen-containing byproducts, and carry higher handling costs in certain applications. The industry is increasingly asking whether alternative chemistries can deliver comparable or superior performance with reduced waste, lower corrosion risk, or easier integration into existing processes. This tension between proven reliability and the desire for cleaner, more efficient solutions is reshaping product selection criteria at the operational level.
The Demand Side: Where Growth Is Concentrated
H2S scavenging demand is anchored by three core application areas: oil industry operations, gas industry processing, and wastewater treatment. These segments collectively represent the bulk of market volume, with oil and gas applications historically dominating due to the prevalence of sour production streams and the high cost of downtime or safety incidents when H2S is not adequately controlled. Gas processing facilities face similar pressures, particularly where sales gas must meet pipeline specifications that impose strict H2S limits. Wastewater treatment represents a growing adjacent demand source, where H2S control intersects with odor management, corrosion prevention, and regulatory compliance for industrial and municipal effluent handling.
What ties these applications together is not just the presence of H2S but the operational consequences of failing to manage it. In production environments, H2S contributes to sulfide stress cracking, iron sulfide scale formation, and equipment fouling, all of which increase maintenance costs and reduce throughput. In gas transmission, failure to meet pipeline specifications can result in rejected volumes, fines, or the need for costly downstream cleanup. In water systems, H2S generates odors, accelerates corrosion in concrete and metal infrastructure, and poses worker safety risks in confined spaces. These cost and risk drivers ensure that H2S scavenging remains a priority even in capital-constrained cycles, because the alternative is often more expensive in the long run.
The market segmentation by type reflects a meaningful split between regenerative and non-regenerative approaches. Non-regenerative scavengers, which react with H2S to form stable compounds that are then disposed of or treated downstream, account for a larger share of current demand. Regenerative systems, which capture and release H2S for subsequent processing or reuse, appeal in contexts where continuous treatment, waste minimization, or resource recovery is prioritized. The relative balance between these two architectures is not static; it shifts with application requirements, operating economics, and the availability of disposal or recycling pathways.
Key Drivers Shaping the Market
Several forces are converging to shape the next phase of market development. Understanding these drivers is essential for identifying where investment, product development, and commercial strategy should be directed.
Technological Innovation and Performance Differentiation
Product innovation is moving beyond generic H2S removal toward application-specific formulations that address multiple operational pain points simultaneously. Recent product introductions illustrate this trajectory. In June 2025, Clariant introduced SCAVTREAT 1173, a gas phase hydrogen sulfide scavenger, expanding its portfolio for gaseous streams. The following month, the company released SCAVTREAT 13964, an H2S scavenger based on glycol derivatives in organic solvents, signaling a push toward alternative chemical architectures that may offer advantages in selectivity, handling, or compatibility with specific process conditions. These releases reflect a broader industry pattern: suppliers are investing in targeted formulations rather than relying solely on established triazine platforms.
Baker Hughes has similarly emphasized performance validation and cost reduction through real-world case studies. In July 2025, the company published a case study demonstrating that its PETROSWEET H2S scavenger reduced H2S levels in sales gas by 60 percent, enabling the operator to meet pipeline specifications and increase production revenue. In May 2025, a separate case study highlighted how the same product cut treatment costs in multiple contact tower applications. These examples underscore a shift in how suppliers justify value: not merely by stating that a product removes H2S, but by quantifying the downstream impact on revenue, compliance, and operating expense.
SLB contributed its own performance narrative in June 2025, releasing a case study on subsea injection of a proprietary H2S scavenger that reduced schmoo deposits and significantly lowered cost. This application highlights the growing relevance of H2S control in subsea and offshore environments, where access constraints, safety considerations, and deposit management create unique challenges. The ability to inject scavengers subsea and achieve measurable deposit reduction points to a niche where specialized formulations and delivery methods can command premium positioning.
Regulatory Pressure as a Structural Demand Driver
Regulation is not merely a compliance checkbox; it is a persistent demand anchor that shapes procurement behavior, product specification, and geographic prioritization. The U.S. regulatory framework, encompassing TSCA and EPA/OSHA mandates, increases the baseline requirement for effective H2S control across production and processing facilities. BSEE rules add a layer of operational obligation for offshore facilities, making scavenger availability and deployment a regulatory expectation rather than an optional best practice. In Europe, emission limits under Directive 2016/2284 sustain demand for H2S control across industrial applications, while GSO ISO 8819:2013 provides a regional standard that influences procurement specifications in the Middle East and Africa.
Hydrogen Sulfide Removal Market
For suppliers, this regulatory patchwork creates both opportunity and complexity. Products that can demonstrate compliance with multiple regional standards, provide robust documentation, and offer consistent performance across varying H2S concentrations and flow conditions gain a competitive advantage. Conversely, suppliers that treat regulation as a secondary concern risk losing specification share to competitors who position their products explicitly around compliance assurance and audit readiness.
Supply Chain Realities and the Push for Alternatives
The 2023 plant incident that disrupted ethylene oxide and related precursor supplies exposed a structural vulnerability in the triazine-based scavenger supply chain. The resulting shortages and price increases in 2025 reinforced the need for diversification, whether through alternative chemistries, multi-source procurement, or reformulated products that reduce dependency on constrained intermediates. This dynamic is accelerating interest in non-triazine options, including nitrogen-free formulations and glycol-derivative-based scavengers, as operators and suppliers seek to insulate operations from single-point failures in the raw material chain.
Cost structure evolution is also influenced by the total cost of treatment, not just the price per unit of scavenger. Factors such as dosing efficiency, sludge generation, corrosion impact, handling requirements, and waste disposal costs all contribute to the economic equation. Products that reduce overall treatment burden, even at a higher unit price, can win on total cost of ownership. This is particularly relevant in applications where downtime, equipment damage, or compliance penalties carry heavy financial consequences.
Competitive Landscape and Strategic Positioning
The hydrogen sulfide scavengers market is moderately concentrated, with the top three companies holding approximately 27.5 percent of revenue and the top five reaching roughly 39.8 percent. This concentration level indicates a market where leading players command meaningful share but where a long tail of specialized and regional suppliers retains relevance, particularly in niche applications, local service requirements, and cost-sensitive segments. The presence of large energy service and chemical companies alongside focused specialty chemical firms creates a dynamic where competition plays out across multiple dimensions: technical performance, application expertise, regulatory support, supply reliability, and total cost of ownership.
Baker Hughes and SLB, both headquartered in Houston, represent the energy services end of the spectrum. Baker Hughes has built its offering around PETROSWEET and SULFIX H2S scavenger solutions targeting crude oil, intermediates, refined products, and processing systems. Its recent case study activity emphasizes measurable outcomes—H2S reduction to meet pipeline specs, treatment cost reductions in contact towers, and subsea deposit control—positioning its products around demonstrated operational value rather than chemistry alone. SLB's liquid H2S scavenger portfolio includes triazine and nitrogen-free options for sour production streams, corrosion control, and HSE hazard management. Its subsea case study reinforces a strategy centered on solving hard-to-reach, high-consequence applications where performance and safety integration are paramount.
Clariant, based in Muttenz, Switzerland, brings a specialty chemicals perspective through its SCAVTREAT line, which addresses hydrogen sulfide, iron sulfide, sulfide scale, and oxygen control in gases and liquids. The 2025 introductions of SCAVTREAT 1173 and SCAVTREAT 13964 illustrate a focus on expanding the application envelope and exploring alternative chemical bases, such as glycol derivatives in organic solvents. This approach positions Clariant as a player investing in formulation breadth and application flexibility, appealing to operators seeking tailored solutions for specific gas or liquid streams.
Merichem Company, also headquartered in Houston, occupies a distinct position with its regenerable H2S scavengers via LO-CAT and EcoTreat technologies for sour gas streams. Regenerable systems appeal where continuous treatment, waste reduction, or resource recovery economics justify the higher complexity and capital considerations. This positions Merichem in a segment where lifecycle economics and sustainability considerations can outweigh lower upfront simplicity.
Other notable participants include SUEZ in Paris, with chemical solutions for H2S removal in water treatment and industrial applications; NuGenTec in the United States, offering triazine-based and non-triazine formulations; Dorf-Ketal in Mundra, Gujarat, India, with its MAXSCAV line for refinery and petrochemical process chemicals; Halliburton in Houston, providing production chemicals and H2S treatment solutions for oil and gas operations; Arkema in Colombes, France, with specialty chemicals and solutions for H2S control; ChemTreat in Glen Allen, Virginia, focusing on water treatment chemicals including H2S scavengers; Caradan Chemicals International in the United States, with H2S scavenger products for oil and gas applications; Paqell in the Netherlands, offering chemical solutions for H2S scavenging in industrial settings; and Nalco Water in Naperville, Illinois, with water treatment and H2S control products. This breadth of participants reflects a market where application specialization, regional presence, and service capabilities often matter as much as chemistry alone.
The competitive landscape is evolving along several axes. Consolidation pressure exists, particularly as larger energy service and chemical companies seek to strengthen their production chemicals portfolios and capture cross-selling opportunities across drilling, completion, production, and processing services. At the same time, fragmentation persists because H2S scavenging requirements vary widely by geography, application, H2S concentration, flow conditions, and regulatory context. New entrants and regional specialists can find room by focusing on underserved applications, localized service, or alternative chemistries that address specific pain points such as nitrogen-free requirements, reduced sludge generation, or improved compatibility with particular process environments.
Forward Trends and Commercial Implications
Looking ahead to the 2026 to 2032 window, several trends are likely to shape market direction and commercial opportunity.
PW Consulting Automotive & Machinery Research Center
Trend One: Performance Validation Becomes a Competitive Mandate
As operators face tighter margins and heightened compliance scrutiny, the ability to quantify the impact of H2S scavenging on revenue protection, cost reduction, and safety outcomes will increasingly differentiate suppliers. Case studies, field data, and application-specific performance benchmarks will move from marketing support to core competitive assets. Suppliers that invest in rigorous validation, transparent reporting, and customer-specific economic modeling will be better positioned to defend specification share and justify premium positioning. For buyers, this trend means that product selection will increasingly hinge on demonstrated outcomes in comparable applications rather than on generic claims.
Mma Triazine H2S Scavengers Market
Trend Two: Chemistry Diversification Accelerates in Response to Supply and Regulation
The precursor disruptions affecting triazine-based scavengers, combined with evolving regulatory expectations around waste, emissions, and handling, will continue to drive interest in alternative chemistries. Nitrogen-free formulations, glycol-derivative-based options, and regenerative systems are likely to gain traction in segments where their performance, safety, or waste profile aligns with operator priorities. This diversification does not imply the obsolescence of established chemistries; triazine-based products remain effective and widely used. Rather, it expands the decision space, giving operators more options to match chemistry to application constraints and risk tolerance. Suppliers that can offer a balanced portfolio, supported by clear guidance on when each chemistry is appropriate, will capture more specification opportunities across a wider range of conditions.
Trend Three: Application Expansion Beyond Traditional Oil and Gas Core
While oil and gas production and gas processing remain the dominant demand centers, adjacent applications in wastewater treatment, industrial effluent handling, and subsea or offshore operations are likely to contribute a growing share of demand. In water treatment, H2S control intersects with odor management, infrastructure protection, and regulatory compliance, creating opportunities for chemistries and delivery methods tailored to aqueous environments. In subsea and offshore settings, the combination of access difficulty, safety criticality, and deposit management creates niche demand for specialized injection and performance assurance approaches. These application expansions do not require a wholesale shift in market structure; they represent incremental growth pockets where focused product development and application expertise can yield disproportionate returns.
Potential risks and uncertainties temper this outlook. Raw material volatility could recur if precursor supply chains remain fragile, affecting pricing and availability for certain chemistries. Regulatory divergence across regions could increase compliance costs and complicate product standardization, particularly for multinational operators managing assets across multiple jurisdictions. Economic cycles in oil and gas investment could influence the pace of new project development and the willingness to adopt newer or more expensive chemistries, even when long-term benefits are clear. Finally, the performance claims surrounding alternative chemistries will need to withstand field validation; products that overpromise on H2S removal, corrosion control, or waste reduction risk reputational damage and specification loss if real-world results fall short.
Strategic Implications for Decision-Makers
For manufacturers and suppliers, the imperative is to build portfolios and capabilities that align with where value is being created. This means investing in application-specific formulation development, expanding evidence-based validation programs, and ensuring that product lines cover both established and emerging chemistry options. Suppliers should also evaluate supply chain resilience, including multi-source sourcing for critical precursors and formulation flexibility that can adapt to raw material constraints. Differentiation will increasingly come from the ability to reduce total treatment cost and risk, not just from the chemistry itself.
For investors, the market offers a profile of steady, regulation-anchored demand with selective pockets of faster growth tied to application expansion and chemistry innovation. The moderate concentration level suggests that market leadership is attainable but not guaranteed, and that success depends on execution in product development, service, and commercial positioning rather than on scale alone. Due diligence should focus on demonstration of field-validated performance, exposure to alternative chemistries and regenerative options, geographic and application diversification, and supply chain robustness. Companies that can show measurable impact on customer revenue, compliance, and operating cost will command stronger competitive positions and more resilient demand.
For procurement and operations leaders, the priority is to move beyond unit price comparisons and evaluate total cost of ownership across dosing efficiency, sludge and waste handling, corrosion impact, handling safety, and compliance documentation. Specification decisions should incorporate application-specific performance data, supplier validation records, and supply reliability considerations, particularly given past precursor disruptions. Where possible, operators should maintain flexibility in chemistry selection, allowing them to adapt to supply conditions, regulatory changes, and evolving operational requirements without compromising H2S control.
The hydrogen sulfide scavengers market is at a point where steady growth, regulatory anchoring, and chemical innovation intersect. Understanding the nuances of product architecture, application economics, and competitive positioning is essential for capturing value in this segment. For those seeking deeper segmentation data, company-level benchmarks, and customized scenario analysis to inform specific investment or procurement decisions, comprehensive market research reports provide the detailed intelligence needed to move from strategic direction to execution.
For detailed analysis of this topic, please visit the official page: Hydrogen Sulfide Scavengers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com