
Blogs
Commercial Decorative Lighting Market: Beyond 5.45% CAGR, the Real Growth Drivers
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Decorative Lighting Market
1. Market Landscape and Core Challenges
The commercial decorative lighting market has transitioned from a supplementary design element to a central component of built-environment strategy. Revenue reached an estimated $17.9 billion in 2025, expanding from $12.5 billion in 2020. The trajectory indicates a compound annual growth rate of 5.45 percent through 2032, with projected valuation approaching $25.9 billion. Growth is no longer linear; it is increasingly shaped by overlapping forces of aesthetic demand, technological maturation, and macroeconomic volatility. Industry participants navigating this environment must recognize that scale alone will not guarantee resilience. The market’s structure favors operators who can align design innovation with supply-chain agility and regulatory compliance.
Three structural challenges define the current inflection point. First, raw material cost pressure is reshaping margin economics. Aluminum and copper prices climbed notably in 2025, with Chinese aluminum spot rates surpassing 21,000 RMB per ton. Because raw inputs typically represent 70 to 80 percent of operating expenses in LED lighting manufacturing, cost volatility flows directly into fixture pricing and contract negotiations. Second, trade policy adjustments have amplified input costs. Higher U.S. tariffs on steel and aluminum imports throughout 2025 have forced manufacturers to either absorb expenses, renegotiate supplier terms, or pass costs downstream. Third, the convergence of decorative aesthetics with connected lighting systems is accelerating, but integration complexity is rising. Buyers expect visually compelling fixtures that also deliver dimming precision, daylight responsiveness, and network compatibility, raising the bar for engineering and certification resources.
These pressures are reshaping competitive expectations. Firms that rely on static product lines or fragmented sourcing face compression in profitability, while those that treat decorative lighting as a performance-driven design category are better positioned to capture premium placements. The market’s next phase will reward operators who can decouple value creation from raw material exposure and translate design intent into reliable, specification-friendly outcomes.
2. Key Demand Drivers Shaping Market Direction
Technology innovation continues to redefine the commercial decorative segment. LED performance has moved beyond baseline efficiency to embrace refined color rendering, thermal management, and form-factor flexibility. Contemporary product releases emphasize advanced LED performance paired with updated aesthetics, allowing decorative fixtures to meet hospitality and retail expectations without sacrificing energy targets. Additive manufacturing is also gaining traction in niche architectural applications, enabling faster prototyping and customized geometries that traditional tooling struggles to achieve. These advances shorten development cycles and expand the visual vocabulary available to specifiers.
Christmas Lights and Christmas Decorations Market
Policy and regulatory dynamics are simultaneously redirecting procurement priorities. Energy codes and sustainability mandates are pushing commercial projects toward fixtures that combine visual impact with measurable performance. The regulatory environment favors connected systems that support scheduling, occupancy response, and centralized monitoring. At the same time, trade measures on steel and aluminum imports have altered cost calculations for manufacturers, making material strategy a competitive variable rather than a back-office concern. Companies are responding by diversifying supplier bases, re-evaluating bill-of-materials architecture, and emphasizing designs that reduce dependency on tariff-sensitive inputs.
Demand-side behavior has shifted decisively. Retail and hospitality operators continue to treat lighting as a brand-expression tool, using decorative luminaires to influence dwell time, atmosphere, and perceived quality. Office environments are integrating decorative elements to support hybrid work identity and occupant well-being, while public and institutional projects increasingly specify fixtures that balance visual character with lifecycle efficiency. The result is broader specification activity across application types, with buyers evaluating decorative lighting not as an accessory but as part of a holistic spatial strategy.
Supply-chain and cost-structure adjustments are reinforcing these trends. Because raw materials account for the majority of manufacturing operating expenses, firms are prioritizing design-for-manufacturability, component commonality, and inventory planning that can absorb commodity swings. Recent trade show showcases and product launches illustrate how manufacturers are aligning outdoor decorative formats, interior pendants, and architectural wall units with both aesthetic refinement and production efficiency. The overall effect is a market where design differentiation and cost discipline must advance together.
3. Competitive Landscape and Leadership Strategies
The competitive environment remains moderately consolidated, with leading players holding meaningful share while specialized manufacturers compete on design authority and application expertise. Broad-portfolio providers compete through scale, specification support, and integrated product ecosystems. Their advantage lies in offering commercial indoor and outdoor decorative and architectural luminaires under established brand frameworks, enabling project teams to consolidate sourcing and simplify specification. Global lighting leaders extend this model with connected systems, energy-efficient fixtures, and wide geographic reach, positioning decorative lighting as part of broader professional solutions.
Design-focused manufacturers pursue a different path. Firms specializing in decorative and architectural LED fixtures concentrate on pendants, chandeliers, track, recessed, and commercial-grade formats tailored for hospitality, retail, and office settings. Their differentiation typically comes from refined proportions, material credibility, and close collaboration with architects and interior designers. Another segment of the market emphasizes high-end architectural and decorative lighting for interiors and exteriors, particularly retail and hospitality environments, where visual precision and finish quality drive specification decisions. Additional players bring decorative high-bay, cylinder, and architectural luminaires to commercial projects, with some exploring 3D-printed lighting approaches that open new pathways for custom forms and faster iteration.
Strategic positioning among leaders reflects a clear divide between breadth and depth. Large portfolios win when projects require multi-product consistency, broad availability, and integrated support. Niche specialists win when design intent is specific, finishes must be exact, and the project team values curated aesthetics over catalog convenience. Recent market activity reinforces both paths. New contemporary releases have expanded portfolios with refined aesthetics and advanced LED performance for commercial and hospitality spaces. Outdoor decorative introductions, including lantern-style LED post-top fixtures, highlight growing interest in streetscape, plaza, and entry-zone aesthetics. Major expos have also showcased architectural and decorative products aimed at commercial applications, signaling sustained demand for visually led yet performance-aligned solutions.
PW Consulting Automotive & Machinery Research Center
Market evolution is likely to continue along two tracks. Consolidation will remain attractive for buyers seeking procurement simplicity, warranty alignment, and specification continuity. At the same time, fragmentation will persist where design differentiation, regional taste, and custom architectural requirements create room for specialized entrants. New participants can gain traction by targeting underserved application niches, leveraging agile manufacturing, or combining decorative credibility with connected-function capabilities. The competitive edge will increasingly belong to firms that can articulate a clear design language while managing material exposure and specification complexity.
4. Future Trends and Commercial Implications
Over the next three to five years, decorative lighting in commercial environments is likely to move toward stronger integration between visual design and intelligent performance. Fixtures will be expected to do more than define a style; they will need to support adaptive dimming, tunable output where appropriate, and compatibility with broader building systems. This shift creates opportunities for manufacturers that can embed control readiness without compromising aesthetic integrity, and for specifiers who can standardize decorative families across multiple zones while preserving flexibility.
A second trend will be continued pressure on input costs and the resulting emphasis on material strategy. Because raw materials dominate manufacturing expense structures, firms that secure diversified sourcing, optimize component selection, and design for manufacturability will hold a cost advantage. Opportunities will emerge for product lines that maintain visual premium perception while reducing exposure to volatile metals and tariff-sensitive inputs. This also favors modular architectures that allow finish variation without redesigning core luminaire platforms.
A third trend involves application-driven customization across retail, hospitality, office, and public environments. Specification activity is broadening as buyers treat decorative lighting as part of spatial identity rather than a decorative afterthought. This opens room for tailored solutions in entry sequences, feature ceilings, retail display areas, and exterior pedestrian zones. The uncertainty lies in policy continuity, commodity pricing, and the pace at which connected-system standards mature. Firms that prepare for variation rather than assume stability will navigate these shifts more effectively. The commercial opportunity is clear: operators that align design credibility with performance reliability and supply resilience can capture higher-value placements and repeat specification cycles.
5. Strategic Actions for Decision Makers
Manufacturers should prioritize design platforms that can adapt to material volatility without abandoning aesthetic quality. That means investing in modular fixtures, control-ready internals, and sourcing strategies that reduce dependency on any single metal or import pathway. Leaders should also treat decorative lighting as a specification relationship business, strengthening collaboration with architects, designers, and facility teams so that product credibility translates into repeat project inclusion.
LED Lighting Market
Investors should evaluate exposure to both design differentiation and cost discipline. Companies with strong portfolio breadth may benefit from consolidation and specification simplification, while specialized players may offer attractive positioning if they serve high-value hospitality, retail, or architectural segments with clear finish and form advantages. Due diligence should examine raw-material sensitivity, tariff exposure, and the ability to integrate connected features without eroding margin.
Procurement leaders and specifier organizations should look beyond catalog variety and assess how decorative fixtures perform across lifecycle expectations, maintenance access, and control integration. Standardizing families where possible can reduce project risk, while reserving bespoke selections for feature zones can preserve design impact. Given the speed of product releases, trade-show activity, and shifting trade policy, timely access to detailed segment data and tailored scenario planning can improve sourcing decisions and reduce specification friction. For teams seeking deeper segmentation, competitive benchmarking, and customized strategic options, the full commercial decorative lighting market report provides expanded data and decision-ready breakdowns.
For detailed analysis of this topic, please visit the official page: Commercial Decorative Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Germacrene D Market 5.02% CAGR: Why Fragrance Demand Drives $29.3M Growth by 2032
By pmarketresearch, 2026-09-18
Germacrene D Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global market for Germacrene D has demonstrated consistent expansion over the past five years, moving from approximately $16.5 million in 2020 to an estimated $20.8 million in 2025. This trajectory reflects a compound annual growth rate of 5.02 percent, with projections indicating the market will reach $29.3 million by 2032. The steady upward curve underscores growing industrial reliance on specialized sesquiterpenes across multiple application verticals. However, beneath these aggregate figures lies a complex landscape shaped by supply chain vulnerabilities, regulatory evolution, and shifting consumer expectations.
One of the most pressing challenges facing market participants is the convergence of raw material volatility and sustainability mandates. Germacrene D is primarily sourced as a sesquiterpene from essential oils of plants such as Solidago canadensis or produced via microbial fermentation from renewable sugar-based feedstocks. Both pathways carry distinct risk profiles. Botanical extraction is subject to agricultural yield fluctuations, climate variability, and land-use constraints, while fermentation-based routes demand capital-intensive bioreactor infrastructure and face scaling bottlenecks. Companies must navigate these dual supply realities while maintaining cost competitiveness and meeting increasingly stringent environmental standards.
A second critical inflection point involves the tightening regulatory framework governing fragrance and flavor ingredients. Recent safety assessments have clarified the risk profile of Germacrene D, with a 2024 evaluation concluding no genotoxicity or skin sensitization concerns at current declared fragrance use levels. While this provides regulatory certainty, it also raises the bar for documentation, traceability, and compliance verification. Suppliers must invest in robust quality management systems and maintain alignment with evolving standards such as EU Regulation (EC) No 1334/2008 and US CFR 101.22 for natural flavor use. The burden of compliance disproportionately affects smaller manufacturers, potentially accelerating market consolidation.
A third structural challenge lies in balancing purity requirements across divergent application segments. The market spans natural extract grades with specified purity levels alongside high-purity reagent grades used in research and specialized formulations. Each grade demands distinct production protocols, validation procedures, and customer engagement models. Manufacturers that attempt to serve both segments without clear operational segmentation risk margin erosion, quality inconsistencies, or brand positioning conflicts. The ability to cleanly separate production streams and communicate value propositions to different buyer personas has become a decisive competitive factor.
Key Drivers of Market Evolution
Technological Innovation and Fermentation Breakthroughs
Advancements in microbial fermentation have fundamentally altered the supply dynamics of Germacrene D. Fermentation-based production enables consistent output independent of seasonal agricultural cycles, reduces reliance on land-intensive crop cultivation, and aligns with circular economy principles when paired with renewable sugar feedstocks. Several industry participants have demonstrated that carefully optimized bioprocesses can achieve purity levels suitable for flavor and fragrance applications while maintaining certifications such as kosher, halal, and pesticide-free status. These capabilities expand the addressable market by offering formulators a reliable, scalable alternative to botanical extraction, particularly in regions where agricultural supply chains face disruption or where traceability requirements are intensifying.
Beyond production methods, downstream formulation technologies are also shaping demand. The integration of Germacrene D into complex fragrance architectures requires precise understanding of its olfactory profile, stability characteristics, and interaction with other aroma chemicals. Suppliers that invest in application labs, sensory evaluation capabilities, and technical support services create stickier customer relationships and command premium positioning. This shift from commoditized molecule supply to integrated solution provision represents a meaningful margin opportunity for organizations willing to build technical depth.
Regulatory Clarity and Certification Momentum
Regulatory developments have moved from ambiguous risk discussions to more definitive safety conclusions, providing a foundation for confident commercialization. The affirmation of a FEMA GRAS number and compliance with major food and fragrance regulations reduce barriers to adoption in end-use products. Concurrently, certification renewals and expansions, such as the renewal of kosher certification for fermentation-derived Germacrene D through early 2026, signal ongoing commitment to dietary and religious compliance standards that matter to global brand owners.
These regulatory and certification dynamics are not merely compliance exercises; they function as market access enablers. Multinational consumer goods companies require ingredient suppliers to demonstrate harmonized compliance across multiple jurisdictions. Suppliers that proactively maintain and document certifications across EU, US, and international frameworks reduce friction in the procurement process and become preferred partners for large-scale formulation projects. The regulatory environment thus rewards completeness and transparency over speed-to-market alone.
Demand-Side Shifts Toward Natural and Sustainable Ingredients
Consumer and brand preferences continue to gravitate toward natural-origin and sustainably sourced ingredients. In the fragrance and personal care sectors, this trend drives formulators to seek sesquiterpenes that can deliver characteristic woody-spicy, minty, or herbal notes while meeting clean-label expectations. The commercial appeal extends beyond marketing narratives; it influences procurement specifications, supplier qualification criteria, and long-term contract structures. Brands are increasingly willing to pay a premium for ingredients that combine verified natural status with reliable supply and consistent sensory performance.
Parallel demand is emerging from agricultural pheromone applications, where Germacrene D serves as a component in insect attractant and mating disruption formulations. This segment benefits from broader agricultural trends emphasizing reduced synthetic pesticide reliance and integrated pest management strategies. While smaller in absolute terms compared to fragrance and cosmetics, the agricultural pheromone segment offers diversification benefits and growth potential tied to regulatory pressure on conventional agrochemicals and expanding adoption of biocontrol methods.
Supply Chain Restructuring and Cost Dynamics
Cost structures in the Germacrene D market are being reshaped by logistics complexity, energy input requirements, and the economics of scale. Fermentation-based routes, while offering supply stability, involve significant upfront capital expenditure and operational expertise in bioprocess engineering. Botanical extraction pathways face fluctuating input costs tied to crop yields and geographic sourcing constraints. In both cases, organizations that achieve scale, optimize yield per unit of input, and streamline downstream purification can establish meaningful cost advantages.
Farnesene Market
Supply chain resilience has also become a strategic priority. Buyers are increasingly evaluating suppliers not only on price and purity but on geographic diversification, inventory buffering capabilities, and contingency planning. The market concentration, with the top three participants holding a modest share and the top five capturing a slightly larger portion, indicates room for both specialized niche players and larger diversified ingredient companies. This fragmentation creates opportunities for regional suppliers to secure local partnerships while inviting larger entities to pursue selective acquisitions that broaden geographic reach and technical portfolios.
Competitive Landscape and Leading Strategies
Differentiation Through Positioning and Technical Capability
Market participants have adopted distinct strategic postures that reflect their organizational capabilities and target customer segments. Some companies emphasize fermentation-derived natural Germacrene D with comprehensive dietary and regulatory certifications, positioning themselves as reliable partners for flavor and fragrance formulators who require clean-label compliance and consistent supply. This approach combines biotechnological manufacturing with rigorous quality documentation, appealing to brand owners who prioritize transparency and auditability.
Other organizations focus on high-purity reagent and fragrance-grade products packaged for industrial and research use. These suppliers cater to application development, analytical testing, and specialized formulation work, where purity specifications and packaging integrity take precedence over natural-origin claims. By maintaining strict quality controls and offering flexible packaging options, these participants serve a different buyer persona that values technical precision and rapid availability over certification breadth.
Large flavor and fragrance houses with diversified botanical extraction capabilities include Germacrene D within broader portfolios of natural-origin ingredients. Their strategic advantage lies in integrated supply chains, established customer relationships, and the ability to offer formulation guidance alongside raw material supply. For these organizations, Germacrene D is one element of a larger sustainable sourcing narrative, supported by eco-friendly extraction practices and long-standing botanical expertise. Their scale and brand recognition provide credibility with multinational clients, while their portfolio breadth allows cross-selling and formulation synergy.
Recent Strategic Moves and Market Signals
Recent industry activity highlights how participants are sharpening their competitive positioning. A fermentation-based supplier renewed kosher certification for its natural Germacrene D product, reinforcing its commitment to dietary compliance and maintaining eligibility for markets where such certification is a procurement prerequisite. This type of certification maintenance may appear routine, but it signals ongoing operational discipline and protects market access in segments where religious and dietary standards influence purchasing decisions.
A major global fragrance and flavor company introduced a Germacrene D-based fragrance ingredient as part of an expanded natural-origin portfolio. This launch illustrates the use of targeted molecule development to refresh ingredient offerings, respond to formulator demand for specific olfactory profiles, and reinforce sustainability messaging. By embedding Germacrene D within a broader portfolio narrative, the company leverages the molecule's sensory characteristics while aligning with brand-level commitments to natural sourcing.
Another significant move involved a strategic partnership between two ingredient companies to co-develop sustainable fragrance ingredients, including Germacrene D, with an emphasis on resilient natural sourcing. Collaborative development arrangements allow participants to share technical risk, pool botanical or bioprocess expertise, and accelerate time-to-market for improved ingredients. Such partnerships also reflect an industry-wide recognition that sustainability and supply resilience are not easily achieved in isolation; they often require joint investment in sourcing relationships, process optimization, and certification alignment.
Sclareolide Market
Market Structure Evolution
The competitive landscape is undergoing gradual transformation rather than abrupt disruption. Market concentration remains moderate, indicating that no single entity dominates supply and that differentiated positioning can still yield viable market share. Over the forecast horizon, several dynamics are likely to shape structure. Larger ingredient companies may pursue selective acquisitions to fill technical gaps, expand geographic coverage, or bring fermentation capabilities in-house. Specialized manufacturers with unique purity profiles, certification portfolios, or regional sourcing advantages can maintain strong niche positions by serving customers who value specificity over breadth. New entrants with novel bioprocess technologies or alternative feedstock strategies may emerge if they can demonstrate cost parity, regulatory compliance, and scalable production.
The overall trend points toward a market where value creation shifts from volume-only competition to capability-based differentiation. Suppliers that combine reliable production, regulatory completeness, technical support, and sustainability credentials will be better positioned to command favorable terms and build long-term partnerships. Conversely, participants that compete solely on price without clear quality or compliance differentiation may face margin pressure as buyers increasingly weigh total cost of ownership and supply risk.
PW Consulting Chemical & Energy Research Center
Future Trends and Commercial Implications
Convergence of Natural Certification and Biotechnological Scale
Over the next three to five years, the intersection of natural-certification requirements and fermentation scalability will likely become a central theme. As formulators seek ingredients that satisfy both sensory expectations and sustainability mandates, suppliers capable of delivering certified natural-status molecules through reproducible bioprocesses will capture growing demand. The commercial opportunity lies in offering a credible alternative to botanically sourced sesquiterpenes while maintaining documentation that satisfies global regulatory and consumer expectations. Organizations that invest early in process optimization, certification breadth, and supply transparency can establish defensible positions before the segment becomes crowded.
Expansion of Application Diversification
Application diversification represents another meaningful trend. While fragrance and cosmetics continue to anchor demand, agricultural pheromone formulations and specialized research uses provide adjacent growth avenues. The agricultural segment, in particular, benefits from structural shifts toward reduced synthetic pesticide reliance and increased adoption of behavioral pest control methods. Suppliers that develop technical expertise in pheromone formulation requirements, stability testing, and field-performance considerations can extend their reach beyond traditional aroma chemical markets. This diversification also serves as a hedge against cyclicality in consumer-facing fragrance spending, smoothing revenue profiles across economic cycles.
Regulatory and Compliance Sophistication as Competitive Moat
Regulatory sophistication will increasingly function as a competitive moat rather than a baseline requirement. As safety assessments solidify and certification frameworks mature, the ability to maintain harmonized compliance across jurisdictions becomes a differentiator. Buyers will favor suppliers that provide clear documentation, predictable audit outcomes, and proactive engagement with evolving standards. The risk side of this trend involves the possibility of regulatory divergence across regions or the emergence of new substance-specific requirements that challenge existing production or labeling practices. Companies that monitor regulatory developments closely and maintain flexible quality systems will be better prepared to adapt without disrupting customer supply.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient suppliers, the priority is to clarify segment focus and align operational capabilities with the value propositions that matter most to target customers. Companies serving fragrance and flavor formulators should invest in certification maintenance, application support, and supply transparency. Those focused on high-purity reagent or research-grade markets should emphasize quality control rigor, packaging integrity, and technical documentation. In both cases, building a clear narrative around sourcing, production method, and compliance status helps reduce customer uncertainty and supports pricing discipline.
Investors evaluating opportunities in this space should weigh the balance between scale advantages and specialization premiums. Larger diversified ingredient platforms offer portfolio breadth and customer relationships that can absorbGermacrene D within broader sustainable sourcing strategies. Specialized participants with differentiated fermentation capabilities, certification portfolios, or regional sourcing strengths may offer attractive growth profiles if they can demonstrate reproducible quality and market access. Due diligence should examine production scalability, regulatory standing, customer concentration, and the durability of any purity or certification advantages.
For procurement leaders and formulation teams, supplier selection should extend beyond unit price to encompass compliance documentation, supply resilience, technical support, and long-term sourcing strategy. Engaging suppliers that can articulate their production method, certification status, and continuity planning reduces downstream risk and facilitates smoother product development cycles. Early involvement of ingredient suppliers in formulation projects can also surface technical considerations before they become costly redesigns.
Market participants and investors seeking detailed segmentation data, competitive benchmarking, and customized scenario analysis will find value in consulting the complete research report, which provides deeper breakdowns of regional dynamics, purity-grade trends, application-specific demand patterns, and firm-level strategic profiles.
For detailed analysis of this topic, please visit the official page: Germacrene D Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Indirect Gas-fired Make-up Air Unit Market: The 5.3% CAGR Reality Beyond 2032 Forecast
By pmarketresearch, 2026-09-18
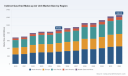
Navigating the Strategic Landscape of the Worldwide Indirect Gas-fired Make-up Air Unit Market
Market Overview and Core Challenges
The global indirect gas-fired make-up air unit market has demonstrated steady expansion over the past half-decade, evolving from a niche HVAC component into a critical infrastructure element for industrial and commercial facilities. Valuation metrics from 2020 through 2025 indicate a consistent upward trajectory, with the market reaching approximately 878 million USD by 2025. Looking ahead, projections suggest continued growth through 2032, driven by replacement cycles, new construction, and retrofit activities. The compound annual growth rate reflects moderate but resilient expansion, signaling a maturing market that is increasingly sensitive to operational efficiency and regulatory compliance rather than pure volume growth.
Despite this positive momentum, the industry stands at a strategic inflection point defined by several persistent challenges. First, the balance between upfront capital expenditure and long-term operational savings remains a friction point for project owners. Indirect gas-fired units offer significant advantages in terms of air quality and combustion safety compared to direct-fired alternatives, but they often carry higher initial costs and complex installation requirements. Decision-makers in commercial and industrial sectors are increasingly scrutinizing total cost of ownership, pushing suppliers to justify premium pricing with demonstrable energy savings and durability.
Second, the regulatory environment is tightening across major regions, particularly regarding ventilation standards and energy efficiency. Compliance is no longer a checkbox exercise but a dynamic requirement that varies by jurisdiction and building type. Facilities managers must navigate a patchwork of codes that dictate airflow rates, combustion safety, and thermal performance. This complexity increases the barrier to entry for smaller players and elevates the value of manufacturers who can provide compliant, pre-engineered solutions that simplify approval processes.
Third, supply chain volatility and raw material fluctuations introduce uncertainty into pricing and lead times. The production of critical components, such as heat exchangers, is subject to commodity price swings and manufacturing capacity constraints. For instance, recent movements in steel markets and the valuation growth of the North America heat exchanger sector highlight how upstream cost pressures can ripple through to finished equipment pricing. These dynamics demand that manufacturers adopt more agile sourcing strategies and potentially pass through cost adjustments while maintaining competitiveness.
Key Drivers of Market Change
Technological Innovation and Performance Enhancement
Advancements in burner technology, heat exchanger design, and control systems are reshaping the value proposition of indirect gas-fired make-up air units. Manufacturers are increasingly offering modular configurations with modulating capabilities, allowing units to adjust output based on real-time demand. This flexibility improves energy efficiency and reduces fuel consumption during partial-load conditions, which is a significant consideration for facilities with variable ventilation needs. High-efficiency heat exchangers maximize thermal transfer while minimizing the footprint of the equipment, addressing space constraints in mechanical rooms and rooftop installations. Furthermore, integration with building management systems and advanced controls enables precise management of temperature, humidity, and air quality, aligning with broader trends toward smart building infrastructure.
Building Dedicated Outdoor Air System Market
Recent product documentation releases from leading companies underscore a focus on usability and comprehensive system integration. For example, updated start-up guides and installation manuals now include detailed control specifications and variable air volume options, reflecting an industry-wide emphasis on making complex systems easier to commission and operate. These documentation improvements support the adoption of indirect gas-fired technology by reducing the technical burden on contractors and facility staff, thereby accelerating deployment in commercial kitchens, industrial spaces, and institutional settings.
PW Consulting
Policy and Regulatory Environment
Regulatory frameworks are acting as both a constraint and a catalyst for market growth. Standards governing gas-fired equipment safety and performance, such as those maintained by ASHRAE and ANSI, provide the baseline for product certification and ensure consistent quality across regions. However, local building codes are increasingly embedding stricter ventilation and energy efficiency requirements. In California, for instance, the 2025 Building Energy Efficiency Standards, effective for permits applied on or after January 1, 2026, include strengthened mechanical system and ventilation mandates that directly impact HVAC equipment selection. Such regulations push facility owners toward compliant, higher-performance units that can meet elevated standards without compromising indoor air quality or thermal comfort.
The regulatory landscape also favors indirect-fired systems over direct-fired alternatives in applications where combustion byproducts must be fully isolated from the supplied air. This dynamic reinforces demand in sensitive environments such as healthcare facilities, food processing plants, and commercial kitchens, where air quality and safety are paramount. Manufacturers that proactively design for compliance and can navigate regional code variations gain a distinct competitive edge, as they reduce the risk and delay associated with permitting and inspection.
Demand-Side Shifts in Commercial and Industrial Sectors
Changes in how buildings and factories operate are altering ventilation requirements and, consequently, the demand for make-up air units. In industrial manufacturing, processes that generate heat, moisture, or airborne contaminants require reliable replacement air to maintain safe working conditions and operational efficiency. The trend toward decentralization and flexible manufacturing layouts means that ventilation systems must be adaptable and scalable. Similarly, in commercial buildings, the emphasis on occupant health and indoor environmental quality has elevated the importance of dedicated outdoor air systems and well-controlled make-up air solutions. Post-pandemic awareness has reinforced the link between ventilation and health, prompting asset owners to prioritize systems that deliver consistent, filtered, and tempered air.
Institutional and healthcare facilities represent another growing segment where precise air handling is critical. These environments often have stringent requirements for temperature stability, humidity control, and filtration to support infection control and patient comfort. Indirect gas-fired units that offer optional DX cooling and heat recovery capabilities are well-positioned to meet these demands. The convergence of health, safety, and comfort priorities is expanding the addressable market beyond traditional industrial applications, creating new revenue streams for manufacturers that can tailor solutions to diverse end-user needs.
Supply Chain and Cost Structure Dynamics
The cost structure of indirect gas-fired make-up air units is influenced by multiple factors, including raw material prices, manufacturing efficiency, and logistics. The health exchanger market, a key component segment, has seen valuation growth that reflects both demand and cost pressures. Volatility in steel and other metals can affect production costs, while regional manufacturing capacity and supply chain resilience determine lead times and delivery reliability. Companies that invest in localized production, strategic inventory management, and diversified supplier bases are better equipped to mitigate disruptions and maintain competitive pricing.
Moreover, the value of service and support is becoming more pronounced in the overall cost equation. Customers increasingly expect comprehensive documentation, technical assistance, and long-term maintenance support as part of the purchase. This shift means that total value is not solely determined by equipment price but by the reliability of the entire lifecycle offering. Manufacturers that can deliver consistent quality, timely support, and clear operational guidance reduce the hidden costs of ownership, making their products more attractive in a cost-conscious market.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated competitive environment, with a mix of specialized manufacturers and broader HVAC conglomerates. Leading companies differentiate themselves through product specialization, regional presence, and solution-oriented approaches. Greenheck, for example, offers a broad range of indirect gas-fired make-up air units with high-efficiency furnaces and modulating options, catering to commercial and industrial applications with capacities spanning thousands of CFM. Their focus on detailed installation and operation documentation highlights a commitment to supporting proper deployment and long-term performance, which resonates with contractors and facility managers seeking reliability.
Modine HVAC provides a portfolio of indoor and outdoor indirect-fired systems designed for tempered outdoor air delivery in commercial and industrial buildings. Their product lines include power-vented and separated combustion options, allowing them to address diverse installation constraints and ventilation requirements. Trane contributes with rugged, compact units suitable for both indoor and outdoor use, emphasizing durability and versatile heating, cooling, and ventilating capabilities. AbsolutAire specializes in ventilation systems for contaminant control, positioning its make-up air units as integral components for industrial and commercial environments where air quality management is critical.
Wall Mounted Gas Boiler Market
Regional players and specialized manufacturers also play important roles. Halton, based in Finland, offers ETL-listed indirect-fired units for commercial kitchens, industrial spaces, and institutional facilities, with options for DX cooling and heat recovery, aligning with the growing demand for multifunctional systems. Accurex focuses on commercial kitchen environments with horizontally firing burners designed to maximize heat exchanger life, addressing a specific pain point in high-use settings. AAON and Applied Air contribute packaged dedicated outdoor air systems and ventilation solutions that integrate indirect gas-fired heating, appealing to customers seeking consolidated, engineered solutions. Cambridge Air Solutions distinguishes itself with patented low-fire start technology and stainless steel burners, emphasizing performance and longevity in commercial and industrial applications.
The competitive landscape is evolving through a combination of consolidation, specialization, and incremental innovation. Larger HVAC firms may seek to expand their share through acquisitions or by broadening their product portfolios to cover more segments, while niche players often compete on technical expertise, custom engineering, and responsive service. New entrants face high barriers due to the need for certification, established distribution networks, and the trust of specifiers and contractors. However, opportunities exist for companies that can introduce differentiated features, such as enhanced efficiency, smart controls, or modular designs that simplify installation and retrofit. Market dynamics are also shaped by the emphasis on documentation and support; companies that provide clear, up-to-date guidance and maintain robust customer education efforts reduce adoption friction and strengthen their position with end-users.
Future Trends and Commercial Opportunities
Over the next three to five years, the indirect gas-fired make-up air unit market is likely to be shaped by a few interconnected trends. First, efficiency and integration will become even more central to value creation. As energy costs and sustainability goals gain prominence, facilities will prioritize units that deliver precise air handling with minimal waste. Manufacturers that combine high-efficiency heat exchangers, modulating burners, and advanced controls with optional cooling and heat recovery will capture demand from customers seeking to optimize both comfort and operating expenses. The ability to integrate seamlessly with broader building management ecosystems will be a key differentiator, enabling data-driven operation and predictive maintenance.
Second, regulatory harmonization and code evolution will continue to influence product design and market access. As more regions adopt stringent ventilation and energy standards, there will be increased demand for pre-compliant solutions that reduce the complexity of permitting and commissioning. Companies that invest in certification, regional compliance mapping, and flexible product platforms will be well-positioned to serve markets where codes are tightening. This trend also favors partnerships with engineering firms and contractors who can specify compliant systems early in the design process, locking in market share before construction begins.
Third, the market may see gradual consolidation as larger players acquire specialized firms to expand their geographic reach or technical capabilities, while smaller manufacturers focus on niche applications where they can command premium positioning. Supply chain resilience will remain a strategic priority, with companies diversifying sourcing and investing in inventory buffers to manage raw material volatility. For commercial opportunities, the strongest growth potential lies in retrofit projects where existing systems need upgrading to meet new codes or improve efficiency, as well as in sectors like healthcare and institutional facilities where air quality requirements are intensifying. However, risks include potential economic slowdowns that could delay capital projects, as well as the possibility of alternative technologies gaining traction if they offer comparable performance at lower cost. Manufacturers and investors should monitor these dynamics and align their strategies with the segments and regions where demand momentum is most robust.
Strategic Actions for Decision-Makers
For manufacturers, the priority should be to deepen differentiation through efficiency, control integration, and lifecycle support. Investing in product platforms that can be configured for a wide range of applications while maintaining compliance with evolving codes will help capture share across commercial, industrial, and institutional end-users. Emphasis on documentation, training, and post-sale support can reduce adoption barriers and build long-term customer relationships, which are increasingly valuable in a market where total cost of ownership matters more than initial price.
For investors, attention should focus on companies with strong technical capabilities, diversified end-user exposure, and resilient supply chains. Evaluating how well a company navigates regulatory changes and raw material fluctuations can provide insight into its ability to sustain margins and growth. Opportunities may also exist in segments where retrofit demand and code-driven upgrades create recurring revenue streams, particularly in regions where ventilation standards are tightening.
For procurement and facility management teams, the focus should be on aligning equipment selection with operational goals and compliance requirements from the outset. Engaging with suppliers early to ensure that proposed systems meet current and anticipated codes can streamline approval processes and avoid costly redesigns. Considering total cost of ownership, including energy efficiency, maintenance needs, and support availability, will lead to better long-term outcomes than focusing solely on upfront price.
Staying ahead in this market requires access to detailed segmentation data, regional dynamics, and competitive intelligence that go beyond high-level trends. Comprehensive research provides the granularity needed to make informed decisions about product development, market entry, procurement strategy, and investment allocation. For those seeking deeper insights, exploring the full range of analysis on the worldwide indirect gas-fired make-up air unit market can reveal the specific opportunities and risks that matter most to your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Indirect Gas-fired Make-up Air Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Breath Out Filters Market: Why 5.78% CAGR and ICU Demand Reshape Growth
By pmarketresearch, 2026-09-18
The Worldwide Breath Out Filters Market: Strategic Trends and the Next Phase of Growth
The global breath out filters market has entered a distinct phase of recalibration. Following a pronounced contraction in the 2022–2023 period, volume and revenue trajectories have stabilized, with the market poised to expand from approximately $975 million in 2025 toward a projected $1.44 billion by 2032. This recovery is underpinned by a compound annual growth rate of 5.78 percent across the forecast horizon, signaling steady but measured momentum rather than speculative acceleration. The trajectory reflects a sector transitioning from pandemic-era urgency to a normalized, protocol-driven purchasing environment where infection control, respiratory circuit integrity, and cost efficiency coexist as purchase criteria.
Behind the headline growth lies a market that is structurally maturing. Demand is increasingly tied to clinical workflow optimization, regulatory compliance, and the economics of extended circuit use, rather than emergency procurement cycles. Manufacturers and procurement teams alike are navigating a landscape where filtration performance standards are high, single-use protocols are strictly enforced, and reimbursement frameworks reward infection prevention strategies that reduce downstream complications. This shift has redefined how value is created and captured across the supply chain.
Several structural challenges are shaping the market's near-term evolution. First, the tension between filtration efficiency and breathing resistance continues to drive engineering trade-offs. High-performance hydrophobic media and electrostatic configurations deliver bacterial and viral removal rates exceeding 99.999 percent, but maintaining low resistance across varied clinical scenarios requires precise media engineering and consistent quality control. Any degradation in performance or perceived respiratory burden can influence clinician adoption and procurement specifications.
Fabric Filter Market
Second, regulatory and compliance complexity is intensifying. Breath out filters for anesthesia and respiratory care operate as Class II medical devices in major markets, requiring conformity to standardized connector dimensions, quality management systems, and individual testing protocols during manufacturing. Changing regulatory expectations, combined with the operational constraints of single-patient use, demand rigorous documentation and supply chain traceability. Companies that cannot demonstrate consistent compliance across production batches risk delays in market access and heightened scrutiny from procurement and infection control teams.
Third, cost pressure and procurement rationalization are reshaping purchasing behavior. Hospitals and respiratory care providers are increasingly optimizing circuit configurations to extend safe usage windows, often applying fresh patient-side filters per patient while managing machine-side components according to clinical protocols. This approach supports infection control objectives while controlling consumable spend, but it also raises the bar for suppliers to justify total cost of ownership rather than unit price alone. In this environment, differentiation depends on clinical reliability, workflow compatibility, and demonstrable support for extended-circuit protocols.
Market concentration reflects the maturity of the competitive field, with a modest level of consolidation among established players. This concentration provides some stability in supply and technical expertise, but it also creates space for targeted entrants that address niche clinical needs or regional procurement dynamics. The interplay between scale incumbents, specialized manufacturers, and emerging device companies is producing a landscape where strategic positioning matters as much as filtration performance.
Key Drivers Shaping Market Direction
Engineering Advances in Filtration Media and Circuit Integration
The most consequential driver of market evolution is the continued refinement of filtration media and its integration into breathing circuit architectures. Modern exhalation filters rely on hydrophobic media, pleated membrane structures, or electrostatic formulations to achieve high bacterial and viral removal efficiency while retaining 100 percent liquid-borne contaminant retention. These characteristics are not merely technical specifications; they directly support clinical objectives such as reducing cross-contamination in exhalation pathways, protecting ventilator components from airborne microorganisms, and enabling safer circuit reuse under controlled protocols.
Innovation is increasingly focused on balancing performance with usability. Manufacturers are developing filter configurations that minimize breathing resistance, simplify connection to tapered connectors compliant with recognized standards, and adapt to both dry and humidified respiratory support scenarios. The integration of exhalation filters with water traps, resuscitator circuits, and anesthesia systems illustrates a broader trend: filters are no longer viewed as isolated consumables but as integral elements of infection control workflows. This perspective is reflected in recent regulatory clearances for disposable expiratory filters and water trap combinations designed for ventilator breathing circuits, signaling that device ecosystems are becoming more tightly integrated.
Regulatory Expectations and Infection Control Protocols
Regulatory and standards-based expectations continue to shape product design, market access, and procurement decisions. Breath out filters for anesthesia and respiratory care must align with standardized connector dimensions and are generally classified as Class II medical devices, requiring premarket clearance pathways or equivalent conformity under medical device regulations. Quality management expectations, including adherence to recognized medical device quality systems, are now baseline requirements rather than differentiators. Manufacturers that maintain regulatory-registered facilities and conduct integrity and efficiency testing during production are better positioned to navigate procurement verification and post-market surveillance requirements.
Beyond compliance, clinical protocols are amplifying demand for filters that support extended circuit use without compromising safety. Infection control frameworks in hospitals increasingly emphasize patient-side filter replacement per patient, enabling circuits to be managed for longer durations under defined conditions. This protocol-driven approach encourages purchasing behavior that values filtration reliability, consistency, and documentation, especially in intensive care and surgical environments where circuit integrity is critical. The alignment between product design and protocol support is becoming a meaningful source of competitive advantage.
Demand-Side Shifts in Critical Care and Respiratory Support
Demand is being reshaped by broader trends in critical care capacity, respiratory support adoption, and the operational economics of healthcare delivery. Hospitals and care providers are prioritizing infection prevention in mechanical ventilation and anesthesia environments, where exhalation pathways can transmit airborne microorganisms if not properly filtered. As a result, breath out filters are embedded in procurement strategies that aim to reduce cross-contamination risk, protect equipment, and support standardized respiratory care workflows.
The residential and long-term care segment also contributes to demand diversification. Home healthcare and long-term care settings are expanding their use of respiratory support technologies, creating incremental demand for filters that are compatible with portable and durable devices. Recent clearances for portable oxygen concentrators that incorporate outlet filter components highlight how filtration elements are becoming part of broader respiratory device systems rather than standalone consumables. This convergence broadens the addressable market and introduces new purchasing dynamics, particularly where device makers and filter suppliers must coordinate on performance and compatibility.
Supply Chain, Material Constraints, and Cost Structure Dynamics
Cost structure and material availability remain influential drivers, particularly for products that depend on specialized hydrophobic media and precision-manufactured connector systems. The need for pleated membrane or electrostatic media with high efficiency ratings creates dependency on controlled material supply and consistent manufacturing processes. Any disruption in raw material sourcing or validation capacity can affect production continuity and lead times, which in turn influences procurement planning and inventory strategy for healthcare providers.
At the same time, procurement economics are pushing suppliers to demonstrate value beyond filtration specifications. Hospitals and distributors are increasingly interested in formats that reduce waste, simplify handling, and align with existing circuit configurations. Single-patient use requirements further constrain product design, since cleaning, sterilization, or reprocessing is not appropriate and may increase breathing resistance or leave residuals. This operational reality reinforces the importance of manufacturing consistency, clear instructions for use, and reliable supply commitments. Suppliers that can deliver predictable quality at scale, while supporting protocol-based usage, are better equipped to secure long-term purchasing relationships.
Competitive Landscape and Leadership Strategies
Established Players and Differentiated Positioning
The competitive field is anchored by a mix of large medical device manufacturers and specialized filtration companies, each pursuing distinct value propositions. Pentair's engineered filtration division has built a reputation around inspiratory and expiratory breathing circuit filters for ventilators and anesthesia applications, emphasizing bacteria and viral removal efficiencies above 99.999 percent, HEPA disposable devices, and respiratory filter capsules in multiple configurations. FDA registration and quality system certification underpin its market positioning, reinforcing trust among procurement teams that require documented compliance and consistent performance.
PW Consulting
Intersurgical offers a broad portfolio of electrostatic and pleated membrane breathing filters designed for anesthesia, critical care, and respiratory circuits, with product lines aimed at preventing cross-contamination in exhalation pathways. Its strategy centers on breadth of configuration and clinical familiarity, enabling it to serve diverse circuit setups and institutional preferences. Dräger contributes a strong presence in the operating room and intensive care settings through electrostatic filters and filter/HME combinations that protect ventilators from exhaled airborne microorganisms, aligning product design with equipment protection and infection control objectives.
Pall Corporation, now part of Cytiva, supplies a well-known range of breathing system filters with high airborne bacterial and viral removal efficiency and liquid-borne retention characteristics, used in anesthesia and respiratory care across patient-side and machine-side applications. Its positioning is reinforced by detailed performance documentation and validation practices, which support procurement verification and clinical confidence. GE HealthCare focuses on disposable single-patient-use anesthesia breathing circuit filters and humidifying membrane exchange filters compatible with its anesthesia platforms, leveraging system compatibility to strengthen attachment within installed equipment bases.
Regional and specialized manufacturers add further diversity. Mercury Medical, Smiths Medical, Medtronic, Fisher & Paykel Healthcare, and Flexicare each address specific clinical and circuit needs, from resuscitator and in-line filtration to humidified respiratory support and exhalation filter assemblies. Their strategies often center on product fit, responsiveness, and targeted clinical applications, allowing them to compete effectively in segments where performance, compatibility, or service expectations are highly specific. Recent regulatory clearances for portable oxygen concentrator outlet filters and disposable expiratory filter and water trap combinations illustrate how both established and emerging players are expanding the functional boundaries of filtration within respiratory device systems.
Strategic Themes Across the Competitive Field
Across these companies, several strategic themes are evident. First, performance claims are increasingly tied to documented validation and regulatory conformity, making traceability and testing discipline central to market access. Second, product portfolios are expanding from standalone filters to integrated circuit components, including water traps and device-specific configurations, reflecting the growing importance of workflow compatibility. Third, geographic reach remains uneven, with strong positions in North America and Europe and growing activity in Asia Pacific, Latin America, and the Middle East and Africa, where procurement patterns, clinical infrastructure, and regulatory pathways differ.
Market evolution is likely to feature both consolidation and differentiation. Larger players may seek to broaden their respiratory care portfolios through product adjacency or targeted acquisitions, while smaller manufacturers may compete on specialized media designs, regional service relationships, or device compatibility. New entrants are expected to focus on niche use cases, such as portable respiratory devices, specific circuit configurations, or cost-optimized formats that still meet clinical performance thresholds. The result will be a competitive environment where scale, technical documentation, and clinical integration all influence share dynamics.
For customers, this landscape creates both optionality and complexity. Procurement teams must evaluate not only filtration efficiency and compatibility but also supply reliability, regulatory standing, and alignment with infection control protocols. Manufacturers, in turn, must balance portfolio breadth with the ability to demonstrate consistent performance across configurations, regions, and clinical scenarios. Strategic leadership will increasingly depend on the capacity to integrate filtration performance with device ecosystems, protocol support, and supply chain resilience.
Future Trends and Strategic Implications
Trend One: Integration of Filters into Respiratory Device Ecosystems
Over the next three to five years, breath out filters are likely to become more tightly embedded within respiratory device systems rather than treated as purely interchangeable consumables. This trend is already visible in device designs that incorporate outlet filter elements and disposable expiratory filter combinations with water traps. As device manufacturers coordinate more closely with filtration suppliers, compatibility, serviceability, and performance validation will become integrated considerations. For suppliers, this opens opportunities to influence design early and secure attachment within approved device configurations. For procurement, it raises the importance of lifecycle planning, including availability of compatible replacements and support for device-specific infection control protocols.
Trend Two: Protocol-Driven Purchasing and Extended Circuit Management
Clinical protocols that support extended circuit use under controlled conditions are expected to strengthen demand for filters that enable safe per-patient replacement and reliable exhalation path protection. This protocol-driven model favors products with consistent filtration efficiency, clear usage guidance, and supply stability. It also reinforces the value of documentation that demonstrates compliance with quality management expectations and individual testing during manufacture. Commercial opportunity lies in helping institutions standardize circuit management practices while reducing variability in consumable performance. The associated risk is that any inconsistency in supply or perceived performance can disrupt protocol adherence and prompt re-evaluation of vendors.
Trend Three: Regional Expansion and Divergent Procurement Models
Growth will likely remain geographically uneven, with North America and Europe sustaining mature, protocol-guided demand, while Asia Pacific, Latin America, and the Middle East and Africa expand as respiratory care capacity and device adoption increase. In emerging settings, procurement models may prioritize affordability, device compatibility, and local service availability alongside performance requirements. Suppliers that can adapt product formats, documentation, and supply arrangements to regional expectations are better positioned to capture share without compromising clinical standards. The key uncertainty is the pace of infrastructure development and the consistency of regulatory enforcement across markets, which can affect both adoption speed and competitive entry.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Prioritize documented performance consistency and regulatory readiness as the foundation of commercial trust. Invest in media engineering that maintains high efficiency while keeping breathing resistance within clinically acceptable ranges, and ensure product documentation clearly supports single-patient use protocols. Where possible, align filter designs with device ecosystems and circuit configurations to improve attachment and reduce substitution risk. Build supply resilience for specialized media and connector components, since procurement teams increasingly view availability and lot consistency as part of total value.
For Investors and Strategic Partners
Focus on companies that combine validated filtration performance with integration into respiratory device workflows and credible compliance documentation. Evaluate exposure to protocol-driven demand in intensive care, anesthesia, and respiratory support, as well as the potential for portable and home-care device expansion. Consider whether portfolio breadth, regional reach, and supply chain discipline are sufficient to sustain positioning as procurement becomes more selective and cost-aware. Monitor regulatory and reimbursement developments that influence extended circuit use, since these can shift demand patterns and purchasing criteria.
For Procurement and Infection Control Leaders
Treat breath out filters as part of a broader infection control and circuit management strategy rather than a simple line-item expense. Validate compatibility with existing breathing circuits and ventilators, confirm single-patient use guidance, and assess supplier consistency in testing and documentation. Where extended circuit protocols are used, ensure that filter performance and replacement practices align with institutional infection control objectives. Request evidence of quality management conformity and individual integrity or efficiency testing to support procurement verification and reduce variability across batches.
The strategic importance of breath out filters will continue to rise as respiratory care becomes more protocol-driven, device-integrated, and regionally diverse. Decision-makers who understand the interplay between filtration performance, regulatory conformity, workflow compatibility, and supply reliability will be best positioned to manage risk and capture value. For organizations seeking a deeper view of segment dynamics, regional patterns, and company-level positioning, a comprehensive research report can provide the detailed breakdowns and scenario analysis needed to translate these trends into concrete strategy.
Air Filters Market
For detailed analysis of this topic, please visit the official page: Worldwide Breath Out Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Slim Drapery Motors Market: Why 11.3% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-18
Navigating the Global Slim Drapery Motors Market: Strategic Trends and Commercial Opportunities
Market Context and Core Challenges
The worldwide slim drapery motors market has matured rapidly over the past five years, moving from a niche automation segment to a core component of modern interior environments. Between 2020 and 2025, total market revenue expanded from approximately 202 million USD to 346 million USD, reflecting sustained demand for discreet, code-compliant window treatments. Forward projections indicate continued momentum, with revenue expected to reach 383 million USD in 2026 and climb toward 732 million USD by 2032. This trajectory translates to a compound annual growth rate of 11.32 percent, signaling that slim drapery motors are no longer an optional upgrade but a structural element of residential and commercial interior ecosystems.
Built In Electric Curtains Market
Despite this growth trajectory, the industry faces several inflection points that will shape competitive outcomes in the near term. The first challenge centers on standardization and interoperability. As smart-home protocols evolve and building management systems demand tighter integration, manufacturers must reconcile differing wireless standards, control architectures, and mounting requirements. Fragmentation increases development costs and complicates retrofit projects, where installers must navigate mixed hardware environments without compromising aesthetics or performance.
The second challenge lies in balancing form factor constraints with functional expectations. Slim motors must remain unobtrusive while supporting heavier fabric loads, longer travel distances, and frequent cycling. This creates engineering tension around battery capacity, torque delivery, thermal management, and noise levels. Products that over-index on compactness risk sacrificing reliability, while those that prioritize load capacity can undermine the discreet installation value proposition that defines the category.
The third challenge is regulatory and safety-driven adoption pressure. Stricter child-safety expectations and energy performance mandates in building codes are accelerating the shift away from corded treatments toward motorized, cordless alternatives. While this creates tailwinds, it also raises compliance complexity for manufacturers and specifiers who must verify that products meet evolving regional requirements without delaying project timelines.
Worldwide Slim Wallet Market
Key Demand Drivers
Technology Innovation and Wireless Architecture
Technological progress is reshaping what slim drapery motors can deliver in both residential and commercial settings. The shift toward battery-powered and DC-driven designs has reduced dependence on in-wall wiring, enabling cleaner retrofits and faster installation cycles. Compact Li-ion platforms now support extended run times and hundreds of operational cycles per charge, while brushless motor designs improve efficiency and reduce acoustic output. These gains matter because drapery automation is increasingly evaluated not only on movement precision but also on everyday usability, including quiet operation, manual override capability, and seamless compatibility with surrounding hardware.
Wireless control has become equally important. Integration with Zigbee, Wi-Fi, and broader smart-home ecosystems allows end users to synchronize drapery movement with lighting, climate, and security functions. The expansion of interoperable protocols is lowering the friction of adding motorized window treatments to existing environments, especially in luxury residential projects and hospitality venues where aesthetic consistency and centralized control are priorities. As a result, product differentiation is moving beyond motor performance alone toward system-level compatibility, calibration ease, and software-supported user experiences.
Policy, Safety Rules, and Building Code Influence
Regulatory dynamics are acting as a powerful adoption catalyst. Child-safety requirements and energy-related building mandates are encouraging specifiers to favor cordless motorized treatments over traditional corded systems. This is particularly relevant in settings where occupant safety, maintenance standards, and long-term energy performance must be documented and verified. At the same time, the same regulatory environment raises the bar for product validation, installation documentation, and ongoing compliance. Companies that design with these expectations in mind gain an advantage in tender processes and specification pipelines, especially when projects involve public-facing or multi-family buildings.
Demand-Side Shifts in Residential and Commercial Sectors
Consumer and enterprise behavior is reinforcing demand from both ends of the market. In high-end residential spaces, buyers increasingly view motorized drapery as part of a broader automation and wellness narrative, where light control, privacy, and room ambiance are managed with minimal visual intrusion. In commercial and hospitality environments, the emphasis is on repeatability, durability, and integration with facility operations. Hotels, offices, and luxury retail spaces value motorized treatments that support consistent presentation, reduce manual handling, and fit within broader building management strategies. This dual demand profile broadens the addressable market but also requires manufacturers to tune product portfolios to very different usage patterns and performance expectations.
Supply Chain and Cost Structure Considerations
Cost structures are being redefined by material choices and installation labor dynamics. Slim drapery motors typically rely on compact DC or battery components and lightweight aluminum or polymer tracks that support discreet behind-panel installation. These design choices can reduce visible hardware and simplify integration, but they also place pressure on component sourcing and manufacturing precision. At the same time, wire-free and battery-powered configurations can lower installation labor by reducing the need for electrician-supported wiring in retrofit scenarios. The resulting labor savings are becoming a meaningful part of the commercial case for automation, especially in renovation projects where minimizing disruption is a priority. However, volatility in battery materials, electronics, and precision mechanical parts can still affect margin stability and time-to-market for new models.
Competitive Landscape and Leading Strategies
The market is not yet dominated by a single archetype. Instead, it features a mix of automation specialists, window-treatment brands, and component-oriented manufacturers pursuing different routes to value. One clear pattern is that leadership is increasingly defined by system integration rather than motor specifications alone. Companies that pair reliable motor hardware with compatible tracks, control ecosystems, and installation-friendly design are better positioned to win in specification-driven projects and repeat retrofit work.
Several firms illustrate this strategic diversity. Rowley Company emphasizes behind-panel installation in traverse systems with options supporting either battery or AC power, targeting users who need a compact motor that integrates cleanly with existing drapery hardware. Somfy has pushed into high-end wireless applications with Zigbee-enabled drapery motors designed for heavier fabric loads and discreet placement, while also connecting to smart-home platforms and professional control ecosystems. Hunter Douglas brings scale and channel strength through motorized drapery solutions and hardware integration, particularly in settings where branded automation and interior design alignment matter. BTX Intelligent Fashion focuses on customizable drapery systems with Li-ion motors, electronic limits, and auto-calibration, reflecting an emphasis on performance tuning and installer-friendly setup. Silent Gliss positions around premium motorized tracks and quiet brushless motors for heavier or higher installations, appealing to specifiers who prioritize finish quality and building management compatibility. Meanwhile, manufacturers such as Misdar and Dooya extend the competitive field with smart connectivity options across residential and commercial applications, often competing on integration flexibility and cost-effective connectivity features.
PW Consulting
Recent product and availability moves reinforce how quickly the category is evolving. In early 2026, Somfy highlighted a wire-free Zigbee drapery motor for luxury applications, showcasing wireless control, higher load capacity, and retrofit-friendly installation in a high-end context. Around the same time, a coordinated availability announcement extended that motor into a motorized line aimed at preserving aesthetics while adding automation. In 2025, another key player updated its drapery system lineup with improved Li-ion motor performance, stronger load handling, and auto-calibration features, indicating an ongoing race to improve cycle life, setup simplicity, and power consistency. These developments point to a market where feature upgrades are increasingly intertwined with installation practicality and ecosystem compatibility.
Looking at the broader structure, market concentration remains moderately consolidated, with the top firms capturing a meaningful share of revenue while leaving substantial room for specialized players. This balance creates two parallel dynamics. First, larger brands can leverage distribution, specification relationships, and cross-product integration to defend share in high-visibility projects. Second, smaller and regionally focused manufacturers can compete by targeting particular end uses, price points, or technical niches such as retrofit-friendly wireless controls, battery endurance, or custom track compatibility. The likely trajectory is not outright consolidation alone, but continued differentiation as companies choose between scale-oriented integration and specialized value propositions.
Future Trends and Strategic Implications
Over the next three to five years, slim drapery motors are likely to move further into the center of integrated interior and building automation rather than remaining standalone accessories. One key trend is the deepening of wireless interoperability. As specifiers and end users expect smoother connections across smart-home and commercial control platforms, motors that support widely adopted protocols and predictable integration behavior will gain preference. This will reward companies that invest in stable communication performance, straightforward pairing, and maintenance-friendly diagnostics rather than only promoting feature count.
A second trend is the continued refinement of battery and DC-powered designs for both retrofit and new construction. Installation labor savings, cleaner aesthetics, and cordless safety benefits will keep wire-free options relevant, but competition will intensify around real-world endurance, charging convenience, and reliable torque delivery across varying fabric weights. Products that can demonstrate consistent performance in demanding cycles, while remaining easy to install and recalibrate, are likely to earn stronger repeat-specification momentum.
A third trend is the growing importance of application-specific tuning. Residential luxury, commercial hospitality, and customized track systems do not share identical requirements, and winners will be those who tailor load capacity, noise profile, control granularity, and integration depth to each context. This creates opportunities for manufacturers to build focused portfolios rather than relying on a single universal offering. At the same time, uncertainty remains. Protocol fragmentation, component cost volatility, and shifting building-code interpretation could slow adoption in some regions or project types, especially where specifiers must balance performance, compliance, and installed cost.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product development with system-level appeal. That means treating motor performance, track compatibility, wireless reliability, and installation simplicity as a single value equation. Roadmaps that improve cycle life, reduce setup complexity, and support smoother integration with common control environments will be better positioned for specification wins and repeat business. It is equally important to prepare for regulatory-driven demand by ensuring that safety and compliance considerations are built into design and documentation from the outset.
For investors, the market suggests a preference for companies with clear differentiation in wireless integration, battery endurance, or application-specific hardware, rather than undifferentiated motor production alone. Due diligence should examine not just product features but also channel access, retrofit suitability, and the ability to serve both residential luxury and commercial hospitality demand without diluting execution focus. Businesses that can scale integration capability while managing component cost risk are likely to capture more durable share.
For procurement and specification teams, the most effective approach is to evaluate slim drapery motor solutions based on installed performance rather than catalog specifications alone. Key considerations should include load consistency across the full travel range, acoustic profile in occupied spaces, compatibility with existing or planned control systems, and the practical effort required for installation and maintenance. Projects that clarify these requirements early tend to avoid rework and achieve more predictable outcomes.
Given the speed of product launches, protocol evolution, and regulatory influence in this category, close monitoring of detailed segmentation, company-level positioning, and regional demand patterns can make a meaningful difference in strategy execution. A deeper review of the full market dataset and competitive profiles can help decision makers translate these trends into specific product, sourcing, and investment choices.
For detailed analysis of this topic, please visit the official page: Worldwide Slim Drapery Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Air Intake Resonator Market: What the 6.85% CAGR Reveals About 2032 Growth
By pmarketresearch, 2026-09-18
Strategic Outlook: Navigating the Air Intake Resonator Market (2026–2032)
Market Overview and Core Challenges
The global air intake resonator market is characterized by steady, predictable growth driven by the broader automotive production landscape. Between 2020 and 2025, the market expanded from approximately $612.45 million to $812.4 million, reflecting a compound annual growth rate (CAGR) of 6.85% through the forecast period ending in 2032. This trajectory suggests a mature but evolving sector where volume growth is increasingly tied to technological refinement rather than raw unit production alone. By 2032, the market is projected to reach $1,291.2 million, indicating significant headroom for value creation despite the commoditization risks inherent in component manufacturing.
Regionally, the market weight is shifting. While North America and Europe remain substantial contributors with established OEM relationships, the Asia Pacific region currently represents the largest revenue share. This distribution highlights the dependency on manufacturing hubs in China, India, and Southeast Asia, where vehicle production volumes continue to outpace Western markets. However, reliance on these regions introduces exposure to supply chain volatility and varying regulatory timelines.
Three critical challenges define the current inflection point for industry stakeholders. First, the transition toward electrification complicates demand forecasting. While internal combustion engine (ICE) vehicles continue to dominate the global fleet, the long-term shift toward EVs threatens the traditional volume base for intake resonators, which are primarily designed for air-cooled combustion processes. Manufacturers must decide whether to pivot designs for hybrid applications or consolidate around ICE production in emerging markets where EV adoption lags.
PW Consulting Automotive & Machinery Research Center
Second, regulatory pressure is intensifying. Emission standards, particularly the EU Euro 7 framework, are expected to drive investment in advanced air intake systems that optimize combustion efficiency and reduce NOx and particulate emissions. Compliance is no longer optional but requires material and design changes that impact cost structures. Third, cost pressures from raw materials are reshaping bidding dynamics. The industry is seeing a divergence in material selection, where cost-effective polymers compete with high-performance engineering plastics, forcing suppliers to balance performance requirements against margin erosion.
Key Drivers of Market Dynamics
Several interconnected factors are propelling the market forward, creating both opportunities and constraints for participants. Understanding these drivers is essential for aligning product development and supply chain strategies with future demand.
Technological Innovation and Material Science
Material selection has become a primary battleground for performance differentiation. The industry is witnessing a dual-track development where glass-fiber-reinforced polyamides (PA6/PA66) continue to dominate premium turbocharged intake applications due to superior thermal resistance up to 220°C. These materials are critical for modern engines that operate at higher temperatures and pressures to meet efficiency targets. Conversely, polypropylene (PP) used in intake components offers a 15-20% cost reduction versus polyamide (PA) but is limited to lower temperature applications around 130-140°C. This cost-performance trade-off creates a segmentation opportunity where suppliers can target budget-conscious OEMs with PP solutions while retaining high-margin contracts with premium brands requiring PA-grade durability.
Innovation is not limited to materials. In-line resonators are capturing a larger share of the type segmentation compared to side branch resonators, reflecting a design preference for compact integration that minimizes engine bay footprint without sacrificing noise reduction. This shift aligns with the industry trend toward downsized, high-efficiency engines where packaging space is at a premium.
Policy and Regulatory Environment
Regulatory frameworks are acting as a forced catalyst for product upgrades. The anticipated implementation of EU Euro 7 emission standards is expected to drive investment in advanced air intake systems optimizing combustion efficiency and reducing NOx and particulate emissions. Unlike previous standards that focused heavily on tailpipe outputs, Euro 7 places greater emphasis on real-world driving emissions and durability, requiring intake systems that maintain performance consistency over the vehicle's lifespan. This regulatory shift benefits suppliers capable of engineering resonators that manage airflow turbulence and temperature more precisely, as inconsistent intake flow can lead to inefficient combustion and higher emissions.
In parallel, noise pollution regulations in urban centers are reinforcing the acoustic function of resonators. As cities impose stricter noise limits, OEMs are increasingly specifying resonators that contribute to overall vehicle sound signature management, extending the component's value proposition beyond mere engine protection.
Demand-Side Shifts and Consumer Behavior
Consumer preferences are bifurcating the market. On one end, the mainstream passenger car segment continues to drive the majority of volume, with buyers increasingly sensitive to fuel efficiency and engine smoothness. Resonators that contribute to quieter, more refined engine operation are becoming standard expectations rather than optional upgrades. On the other end, the performance aftermarket segment is showing renewed vigor. High-performance enthusiasts and modifications for trucks and SUVs are creating niche demand for resonator designs that balance airflow enhancement with sound tuning.
Recent product launches illustrate this demand divergence. In April 2025, K&N Engineering introduced NextGen Air Intake Systems for trucks and SUVs delivering horsepower gains, signaling sustained interest in performance-oriented intake upgrades. Similarly, in May 2025, Dinan released the LCI X3 M40i / X4 M40i Cold Air Intake with performance enhancements, targeting specific luxury performance models. These releases demonstrate that even as OEM volumes face long-term electrification risks, the aftermarket channel remains a viable growth vector for companies with strong brand recognition and engineering credibility.
Supply Chain and Cost Structure Evolution
Supply chain resilience has moved from a back-office concern to a strategic priority. The concentration of manufacturing in Asia Pacific means that geopolitical tensions, logistics disruptions, or regional policy changes can ripple through global availability. Suppliers are responding by diversifying supplier bases and exploring near-shoring options for critical components. Additionally, the cost structure is heavily influenced by polymer pricing volatility. The ability to switch between PP and PA based on application requirements provides a lever for cost management, but this requires flexible production lines and precise engineering validation to ensure material substitution does not compromise performance.
Cost pressures are also reshaping the competitive landscape. Companies that can achieve scale efficiencies while maintaining material flexibility are better positioned to protect margins during periods of raw material inflation. The market concentration, with the top three players holding a combined share of 38.5% and the top five at 52.7%, indicates that scale matters, but niche specialization can still command premium pricing.
Competitive Landscape and Leading Strategies
The market is defined by a mix of global Tier-1 suppliers, specialized automotive component manufacturers, and aftermarket performance leaders. Each segment employs distinct strategies to capture value, reflecting different risk tolerances and customer relationships.
Strategic Positioning of Key Players
MANN+HUMMEL stands out as a global leader in filtration solutions, designing and manufacturing air intake systems and resonators integrated into air cleaner housings for passenger cars, heavy-duty, and industrial applications. Their strategy centers on noise reduction and performance optimization, leveraging a broad portfolio that spans multiple vehicle segments. By integrating resonators directly into air cleaner housings, MANN+HUMMEL reduces separate component complexity for OEMs, offering a value proposition based on systems integration and reliability.
Röchling Automotive specializes in air intake systems with high-frequency resonators for optimized sound and performance. Their focus on integrating resonators, ducts, and filtration components for OEM automotive propulsion systems positions them as a solutions provider rather than a commodity parts supplier. This integration capability allows Röchling to capture higher margins by solving multi-functional requirements such as acoustic tuning, airflow management, and filtration in a unified design.
Toyoda Gosei manufactures air cleaner hoses with resonators and noise-absorbing air intake ducts to reduce engine intake noise while providing clean air for engine efficiency. Their approach emphasizes noise absorption and efficiency, catering to OEMs that prioritize refined engine characteristics. As a Japanese manufacturer, Toyoda Gosei benefits from strong relationships with domestic automakers and suppliers, though they face competition from European and North American players expanding into Asian markets.
Worldwide Automotive Air Filter Housing Market
Magna International provides comprehensive powertrain and vehicle engineering including air intake systems and components as part of broader automotive solutions for OEMs. Magna's scale and engineering breadth allow them to offer air intake resonators as part of a larger package, which can be attractive to OEMs seeking single-source accountability for complex vehicle subsystems. This holistic approach differentiates Magna from component-only suppliers.
Automotive Air Intake Manifold Market
K&N Engineering occupies a unique position as an aftermarket performance leader, offering cold air intake systems, some incorporating or compatible with resonator designs for enhanced airflow and sound. Their strength lies in brand loyalty among performance enthusiasts and a direct-to-consumer channel that bypasses traditional OEM supply chains. K&N's ability to deliver horsepower gains and sound enhancement makes them a benchmark for aftermarket quality, creating a halo effect that can influence OEM specifications indirectly.
Market Evolution and Competitive Trends
The competitive landscape is evolving through a combination of consolidation among large players and differentiation among specialists. The market concentration indicates that scale advantages are significant, encouraging mergers and partnerships that expand geographic reach and product portfolios. However, the presence of strong niche players like K&N Engineering suggests that specialization in performance or specific vehicle segments remains viable.
New entrants face high barriers due to the need for engineering validation, OEM qualification processes, and established supply chain relationships. However, companies that can innovate in material science or acoustic engineering may find opportunities to disrupt traditional supplier relationships, particularly if they can demonstrate clear advantages in cost or performance. The recent product activity from Dinan and K&N highlights that the aftermarket remains a dynamic space where innovation cycles are faster than in the OEM channel, providing a testing ground for new designs and materials.
Strategic differentiation is increasingly tied to material flexibility and regulatory compliance capabilities. Suppliers that can seamlessly switch between PP and PA grades based on application requirements, while meeting Euro 7 and noise standards, are better equipped to win contracts across diverse OEM segments. The ability to offer integrated solutions that combine resonators with filtration and ducting is also becoming a key differentiator, as OEMs seek to reduce assembly complexity and weight.
Future Trends and Commercial Opportunities
Looking toward the 2026–2032 horizon, several trends will shape the market's trajectory and create distinct commercial opportunities for prepared stakeholders.
Trend 1: Hybrids as a Bridge for Resonator Demand
The transition to full electrification will not be uniform across all markets. Hybrid vehicles, which retain ICE components alongside electric drivetrains, will sustain demand for air intake resonators in regions where full EV infrastructure is slow to develop. This creates a medium-term opportunity for suppliers to design resonators optimized for hybrid-specific operating conditions, such as frequent start-stop cycles and varied load demands. Manufacturers that can demonstrate improved durability and efficiency for hybrid applications will capture value from OEMs extending the life of ICE technology in hybrid platforms.
Trend 2: Material Innovation Driving Margin Recovery
As cost pressures persist, material innovation will be a critical lever for margin recovery. The divergence between PP and PA applications suggests that suppliers with expertise in material optimization can offer tiered solutions that match cost to performance requirements. Opportunities exist for companies that can develop novel composites or recycling pathways that reduce material costs while maintaining thermal and acoustic performance. Additionally, the push for sustainability may drive demand for resonators made from recycled polymers or bio-based materials, particularly in European markets where OEMs face pressure to reduce the carbon footprint of their supply chains.
Trend 3: Acoustic Performance as a Differentiator
Noise regulations and consumer expectations for refined vehicle acoustics will elevate the resonator's role beyond functional airflow management. Suppliers that can deliver precise acoustic tuning, reducing specific frequency bands associated with engine noise while maintaining airflow efficiency, will gain a competitive edge. This trend opens opportunities for collaboration with acoustic engineering firms or the development of proprietary tuning algorithms that optimize resonator design for specific engine families. The integration of resonators with active noise cancellation systems or variable geometry designs could further enhance value propositions for premium vehicle segments.
Risk Factors and Uncertainties
Despite these opportunities, risks remain. The pace of EV adoption could accelerate faster than anticipated in key markets, compressing the timeline for ICE component demand. Raw material costs could spike due to supply constraints or geopolitical events, squeezing margins for suppliers unable to pass costs through. Regulatory changes could also introduce new compliance requirements that increase engineering costs or delay product launches. Finally, the aftermarket segment, while dynamic, is subject to cyclical consumer spending and may not fully offset declines in OEM volumes if electrification progresses rapidly.
Strategic Actions for Decision Makers
Navigating the air intake resonator market requires aligned strategies across manufacturing, investment, and procurement functions. The following recommendations address the core priorities for each stakeholder group.
For Manufacturers and Suppliers
- Invest in material flexibility and engineering validation. Develop production capabilities that can efficiently switch between PP and PA grades based on customer requirements. Validate performance across temperature ranges to maximize application coverage while controlling costs.
- Strengthen hybrid and performance aftermarket capabilities. As ICE volumes face long-term headwinds, expand design expertise for hybrid-specific resonators and deepen aftermarket partnerships to capture growth from performance enthusiasts and modification markets.
- Align with regulatory roadmaps. Proactively engineer solutions that meet Euro 7 and emerging noise standards. Early compliance reduces qualification delays and positions suppliers as trusted partners for OEMs facing stringent emission targets.
For Investors and Strategic Partners
- Evaluate scale versus specialization. Assess potential targets based on their ability to leverage scale efficiencies while maintaining differentiated capabilities in material science, acoustic tuning, or aftermarket channels. Companies with both breadth and niche strength are better positioned to withstand margin pressures.
- Monitor regional shifts. Track production and demand trends in Asia Pacific, where volume growth is strongest, and assess exposure to supply chain risks. Investments in diversified manufacturing footprints or near-shoring capabilities can mitigate disruption risks.
- Consider aftermarket dynamics. Recognize that aftermarket performance brands can provide resilient revenue streams and brand visibility even as OEM volumes fluctuate. Partnerships or acquisitions in this space can offer growth avenues independent of traditional supply chain cycles.
For Procurement and OEM Stakeholders
- Prioritize suppliers with integrated solutions. Evaluate partners that can combine resonators with filtration and ducting to reduce assembly complexity and weight. Integrated offerings can lower total system cost and improve quality control.
- Develop material strategy aligned with application needs. Work with suppliers to match PP and PA materials to specific temperature and performance requirements, optimizing cost without compromising durability or compliance.
- Engage early in regulatory planning. Collaborate with suppliers to anticipate Euro 7 and noise regulation impacts, ensuring that intake system designs are validated well before mandatory implementation dates to avoid production delays.
The air intake resonator market is at a point where steady growth intersects with technological and regulatory change. Stakeholders who align their strategies with material innovation, hybrid demand, and acoustic differentiation will be best positioned to capture value through the forecast period. For deeper segmentation data, regional breakdowns, and customized strategic scenarios, access to comprehensive market intelligence is essential to refine these insights and support precise decision-making.
For detailed analysis of this topic, please visit the official page: Air Intake Resonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Processed Seafood Market 2026: Why 5.12% CAGR and Asia Pacific Lead the Global Expansion
By pmarketresearch, 2026-09-18
Global Processed Seafood Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Scale, Trajectory, and Core Challenges
The global processed seafood market has demonstrated consistent expansion over the past five years, with total revenue reaching approximately $60.79 billion in 2025. The sector is projected to grow from $63.68 billion in 2026 to $86.11 billion by 2032, reflecting a compound annual growth rate of 5.12 percent. This trajectory signals a maturing but still dynamic industry where volume growth intersects with value creation through processing sophistication, branding, and supply chain optimization.
Regional distribution reveals a heavily Asia-Pacific-weighted landscape, followed by Europe and North America as substantial mature markets. Latin America and the Middle East and Africa collectively represent smaller but increasingly relevant consumption and sourcing corridors. Processing formats remain anchored by frozen seafood, which commands the largest share, while canned and smoked-dried segments provide complementary value propositions across retail and foodservice channels. Product-wise, fish-based processed goods dominate, with crustaceans and mollusks forming meaningful secondary categories that cater to specific culinary and convenience preferences.
Despite the favorable growth baseline, the industry faces several structural challenges that will define competitive outcomes over the forecast period:
Raw material cost volatility and supply uncertainty. Fishery and aquaculture commodity prices have been trending upward, with the FAO Fish Price Index averaging 127.4 points in March 2026, an 8.4 percent increase compared to March 2025. Salmon and shrimp prices have shown particularly notable rises. Simultaneously, USDA projections indicate that fish and seafood prices in the food-at-home category will increase faster than the 20-year historical average in 2026. For processors, this translates into margin compression risk unless pricing strategies, long-term supply contracts, and product mix adjustments are actively managed.
Traceability, compliance, and quality assurance pressures. Regulatory expectations around seafood traceability are intensifying. New FSMA traceability requirements apply to certain seafood on the Food Traceability List, mandating additional records for aquaculture farms and processing facilities to enable rapid identification and removal of contaminated products. In parallel, the Global Dialogue on Seafood Traceability launched a public consultation in March 2026 on an updated standard planned for release in July 2026, moving toward a commodity-agnostic modular approach applicable to processed seafood. These developments raise the compliance burden but also create differentiation opportunities for operators that can demonstrate robust, verifiable supply chain integrity.
Geopolitical and trade friction amid resilient demand. Tariffs, bans, and freight risks have introduced uncertainty into cross-border seafood flows. Yet global seafood trade is expected to continue growing into 2025 and 2026 without an anticipated reduction in key U.S. imports. This resilience suggests that demand fundamentals remain strong, but the operating environment is becoming more complex, requiring diversified sourcing, flexible logistics, and proactive regulatory monitoring.
These challenges are not merely headwinds; they are shaping a market where operational excellence, transparency, and strategic sourcing will separate outperformers from laggards.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Dynamics
Several interconnected forces are accelerating change in the processed seafood sector. Understanding how these drivers interact is essential for prioritizing investment and capability-building decisions.
Technological Innovation and Processing Breakthroughs
Processing technology continues to improve product quality, shelf life, and value addition. Advanced freezing methods, controlled atmosphere packaging, and automated portioning are enabling producers to deliver convenience-oriented products that meet retail and foodservice specifications while reducing waste. In smoked and dried categories, precision smoking and dehydration technologies are enhancing consistency and flavor profiles, supporting premiumization in niche markets.
Traceability technology is another critical frontier. Digital record-keeping, lot-level tracking, and modular traceability frameworks are becoming operational necessities rather than optional enhancements. The shift toward commodity-agnostic traceability standards will likely accelerate adoption of interoperable systems that can be applied across fish, crustaceans, and mollusks, reducing the friction of managing multiple compliance regimes. For processors, technology investment is increasingly tied to market access: buyers and regulators are demanding verifiable provenance, and systems that can produce auditable records quickly will confer a competitive advantage.
Policy and Regulatory Environment
Regulatory dynamics are reshaping both cost structures and market entry conditions. Beyond traceability, short weighting enforcement has gained visibility. FDA released results from its 2022-2024 testing program on frozen seafood products for short weighting as part of ongoing compliance efforts, signaling sustained regulatory focus on accurate product representation. For processors, this underscores the importance of weight integrity, packaging accuracy, and internal quality controls.
Import eligibility and establishment compliance also remain critical. A 2025 recall of ineligible frozen Siluriformes fish products imported from Vietnam due to establishment ineligibility for U.S. export illustrates the consequences of non-compliance in supplier qualification. Similarly, recalls of frozen shrimp products associated with potential cesium-137 contamination concerns from specific processors highlight the sensitivity of safety and contamination risk management. These events reinforce that supplier vetting, facility audits, and risk-based monitoring are integral to maintaining market access and brand trust.
Demand-Side Shifts in Consumer and Business Behavior
Consumer preferences continue to tilt toward convenience, protein-rich diets, and products with clear quality and sustainability narratives. Processed seafood benefits from these trends because it offers ready-to-cook, ready-to-eat, and portion-controlled formats that fit modern meal planning. In foodservice, consistent supply, predictable specifications, and ease of preparation are valued highly, favoring processors that can deliver reliable, value-added products at scale.
At the same time, traceability and transparency are increasingly influencing purchase decisions. Retail and foodservice buyers are responding to consumer expectations by requiring suppliers to provide credible documentation on origin, handling, and compliance. This creates a reinforcing cycle: demand for transparent products pressures processors to invest in traceability, which in turn enables more confident purchasing by downstream customers.
Supply Chain and Cost Structure Evolution
Supply chain resilience has become a strategic priority. The combination of rising commodity prices, freight volatility, and trade friction is pushing processors to diversify sourcing, strengthen supplier relationships, and optimize inventory and logistics. Long-term contracts with aquaculture producers, strategic partnerships with wild-catch operators, and investment in cold chain infrastructure are becoming common responses to reduce exposure to price spikes and disruption.
Cost structures are also being reshaped by compliance and technology investments. While traceability systems and enhanced quality controls add upfront costs, they can reduce the risk of recalls, protect market access, and support premium positioning. The net effect is a shift from pure cost minimization toward total cost of ownership thinking, where reliability, compliance, and brand protection are weighted alongside unit production costs.
PW Consulting
Competitive Landscape: Strategic Positioning and Market Evolution
The processed seafood market is characterized by a moderately concentrated structure, with the top three players holding approximately 18.45 percent and the top five around 24.12 percent of total revenue. This level of concentration suggests that while large global players command meaningful scale, significant space remains for regional specialists, niche value-added producers, and emerging entrants that can differentiate through product innovation, sourcing advantage, or service model.
Leading companies are pursuing distinct strategic positions:
- Global integrated processors with strong branding. Thai Union Group and Maruha Nichiro Corporation exemplify operators with broad portfolios spanning canned tuna, frozen seafood, and value-added products. Their scale, worldwide supply chain capabilities, and brand portfolios enable them to serve diverse markets and channel requirements. Recent developments reinforce this orientation: Mitsubishi Corporation increased its stake in Thai Union to 20 percent in August 2025 to strengthen business alliance in global seafood operations, highlighting the strategic value of capital partnerships that bolster international reach and operational synergies.
- Aquaculture-focused salmon and whitefish leaders. Mowi ASA, Lerøy Seafood Group, and Cooke Inc. are positioned around farmed salmon and related processed products, with Mowi operating as the world’s largest salmon farming and processing company. Their advantage lies in controlling key parts of the value chain from production to processing, supporting consistent supply, quality management, and responsiveness to retailer and foodservice specifications. Austevoll Seafood ASA and Royal Greenland add further depth in farmed and cold-water seafood processing, broadening the geographic and species footprint of this cohort.
- Regional value-added specialists. High Liner Foods and Trident Seafoods demonstrate focused strategies in North American markets. High Liner Foods completed the acquisition of leading U.S. seafood brands Mrs. Paul’s and Van de Kamp’s from Conagra Brands in June 2025, strengthening its value-added frozen seafood portfolio and expanding its branded retail presence. Trident Seafoods specializes in wild-caught Alaskan seafood with extensive frozen and canned processed offerings, leveraging regional sourcing reputation and product familiarity.
- Broad international portfolios and regional distributors. Companies such as Nippon Suisan Kaisha, Kyokuyo Co. Ltd., Pacific Seafood Group, and Bolton Group illustrate the diversity of models across integrated procurement and processing, Pacific Northwest distribution focus, and European/international market portfolios. Nissui’s emphasis on global supply chains for frozen and highly-processed marine foods, and Boltton’s portfolio orientation in European and international markets, reflect the importance of channel reach and product breadth in serving varied customer bases.
Market structure is evolving along several axes. Consolidation is evident in branded retail and value-added segments, where acquisitions strengthen portfolio depth and channel leverage. At the same time, differentiation is intensifying around traceability, quality assurance, and sourcing credentials, creating room for companies that can credibly demonstrate superior compliance and product integrity. New entrants and smaller regional players can compete by specializing in particular species, processing methods, or local market relationships, especially where large players’ scale advantages are less decisive. The overall trend is toward a layered landscape: large integrators competing on scale, brand, and supply chain breadth; mid-tier and regional specialists competing on focus, responsiveness, and niche credibility; and traceability-conscious operators competing on transparency and risk management.
Forward Outlook: Trends Shaping the Next Three to Five Years
Looking ahead to 2032, several trends are likely to define the market’s evolution and the allocation of commercial opportunity.
Traceability becomes a market-access baseline. As traceability standards mature and FSMA requirements take full effect for listed seafood, the ability to produce modular, auditable, commodity-agnostic records will transition from differentiator to baseline expectation. Processors that invest early in interoperable systems and supplier data integration will be better positioned to serve demanding retail and foodservice buyers, while those lagging may face increasing friction in qualification and retention. The commercial opportunity lies not only in compliance but in using traceability as a trust signal that supports premium positioning and stronger customer relationships.
Value-added and convenience formats capture incremental growth. Frozen seafood will likely remain the largest processing format, but growth will be disproportionately driven by value-added products that reduce preparation effort, offer consistent portioning, and align with channel needs. Acquisitions such as High Liner Foods’ expansion of its branded U.S. portfolio indicate thatstrategic owners are betting on branded, value-added frozen seafood as a growth lever. Processors that can combine quality, convenience, and credible sourcing narratives are well placed to capture share in retail and foodservice.
Price volatility and supply diversification become strategic capabilities. With commodity prices trending above historical norms and trade friction persisting, the ability to manage input costs through diversified sourcing, forward contracting, and product mix flexibility will be a critical capability. Processors that can shift among species, origins, and formats in response to price signals, while maintaining quality and compliance, will protect margins more effectively. The risk is that operators with concentrated sourcing or rigid cost structures face disproportionate exposure to price spikes and disruption.
These trends point to a market where resilience, transparency, and value addition are increasingly intertwined. The upside is meaningful for operators that align capabilities with these directions; the downside risk is concentrated in businesses that remain dependent on single-source sourcing, minimal compliance investment, and undifferentiated product offerings.
Actionable Guidance for Decision Makers
For manufacturers and processors, the priority is to strengthen traceability infrastructure and supplier data integration now, ahead of the July 2026 standard update and the full operationalization of FSMA traceability requirements for listed seafood. Parallel investment in value-added product development, branded portfolio expansion, and diversified sourcing will help capture growth while mitigating input cost volatility. Weight integrity, facility compliance, and contamination risk management should be treated as core operational metrics, not peripheral quality tasks.
For investors, the market’s moderate concentration and ongoing consolidation create opportunities to assess companies with credible scale advantages, strong brand portfolios, and resilient sourcing models. Capital partnerships, such as the increased Mitsubishi stake in Thai Union, signal that strategic alliances are being used to reinforce global operations; similar structures may be relevant for companies seeking to accelerate international reach or technology adoption. Due diligence should weigh traceability readiness, compliance history, and product mix flexibility as indicators of long-term market access and margin stability.
For procurement leaders in retail and foodservice, supplier qualification should place greater weight on verifiable traceability, establishment compliance, and risk-based monitoring. Diversifying the supplier base across regions and species can reduce exposure to tariffs, freight risks, and single-source disruptions, while still capturing the growth expected in global seafood trade. Requiring modular, auditable traceability records and clear documentation on weight and safety compliance will help protect brand integrity and consumer trust.
Processed Vegetable Market
Detailed segment-level data, company-specific benchmarks, and scenario analysis can materially sharpen these decisions. For executives seeking granular breakdowns across regions, processing types, and product categories, as well as customized strategic guidance tailored to specific operating models, an in-depth market report is available for further review.
Processed Cheese Market
For detailed analysis of this topic, please visit the official page: Worldwide Processed Seafood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
AGV Charging System Market: Why 8.45% CAGR and Asia Pacific’s Lead Redefine Investment
By pmarketresearch, 2026-09-18
The AGV Charging System Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The automated guided vehicle charging infrastructure market has transitioned from a peripheral consideration to a central component of intralogistics strategy. The sector expanded from roughly 312 million USD in 2020 to an estimated 613 million USD in 2025, with projections indicating a steady trajectory toward just over 1 billion USD by 2032. This growth reflects annualized expansion of 8.45 percent, a pace that outstrips broader industrial automation adoption and signals a structural shift in how facilities approach material handling power management.
Despite the upward trajectory, the market sits at a critical inflection point. Operators are no longer evaluating charging systems as simple utility attachments. Instead, charging infrastructure is becoming a bottleneck or an accelerant for throughput, depending on design choices. Three challenges define the current landscape.
First, downtime economics have intensified. Warehouse and manufacturing environments now operate under tighter labor constraints and higher throughput expectations, making vehicle idle time directly visible in operational cost. Charging solutions that require prolonged dock occupancy or complex manual alignment create hidden capacity losses that compound across fleets. Second, standardization gaps persist across safety, interoperability, and performance metrics. As automated vehicle deployments scale across mixed fleets and multi-vendor environments, facilities encounter integration friction when charging hardware, communication protocols, and docking behaviors are not aligned. Third, the pace of battery chemistry evolution is outstripping charger design cycles. Higher energy densities, faster charge acceptance, and shifting thermal profiles require charging systems that can adapt without forcing full vehicle redesigns.
These challenges are not isolated technical issues. They shape procurement decisions, vendor selection, and facility planning. Companies that treat charging as an afterthought increasingly discover that power delivery constraints limit automation ROI, while early actors are using charging architecture to differentiate operational flexibility.
Strategic Drivers Reshaping the Market
The expansion of AGV charging infrastructure is being pulled by a combination of technology, regulatory pressure, operational behavior, and cost dynamics. Understanding how these forces interact is essential for anticipating where value will concentrate.
Technology Innovation and Performance Thresholds
Charging technology is moving away from static, long-duration docking toward high-efficiency, flexible power delivery. Inductive and contact-based systems are both advancing, but the strategic question is increasingly about when and where energy is transferred. Opportunities for in-process or short-break charging reduce the need for large battery packs and long charging windows. Award recognition for in-process charging technology in early 2025 highlighted how the industry is rewarding solutions that minimize interruption rather than simply improving charger wattage. At the same time, high-voltage DC connectors and microgrid-enabled fast charging concepts have emerged to support next-generation vehicles with reduced downtime.
Battery-side developments reinforce this shift. Lithium-ion adoption continues to benefit from cost and performance improvements, and charging architectures are being optimized for higher charge rates, including transitions from conventional 1C charging toward 3C surge profiles in suitable applications. This changes the design logic for both stationary and onboard charging units, placing greater importance on thermal management, power conversion efficiency, and control software.
Policy Pressure and Compliance-Driven Adoption
Regulatory expectations are reshaping industrial facility planning. European sustainability targets require industrial operations to move toward carbon neutrality by 2050, with a 55 percent emission reduction milestone by 2030. These targets accelerate interest in efficient charging approaches that reduce energy waste and support broader decarbonization strategies. Wireless and opportunity charging solutions gain relevance here because they can lower mechanical wear, simplify integration into continuous workflows, and support more consistent energy use patterns when deployed thoughtfully.
Safety and interoperability standards are equally influential. Conformance to AGV safety requirements drives demand for charging systems that are not only electrically robust but also integrated into the vehicle’s operational safety logic. In warehouse automation, this means charging infrastructure must align with vehicle behavior, zone design, and risk controls rather than functioning as a standalone utility.
Demand-Side Changes in Logistics and Manufacturing
Operational expectations are changing on the demand side. Facilities are deploying larger fleets of automated vehicles and expecting them to support continuous or near-continuous workflows. This is especially visible in warehousing and logistics, where throughput pressure has made charging strategy part of overall slotting, routing, and shift design. Automotive manufacturing and adjacent industrial sectors are also pushing for more flexible power solutions that can accommodate high-utilization vehicles without expanding floor congestion.
Behaviorally, operators are moving from a “charge when parked” mindset to a “charge where and when it fits the process” mindset. That shift increases interest in solutions that support fast top-ups, autonomous docking, and reduced manual intervention. The commercial implication is that charging systems are being evaluated on process compatibility as much as on electrical performance.
Supply Chain and Cost Structure Evolution
Cost dynamics are improving the feasibility of advanced charging solutions, but they are also reshaping supplier competition. Better lithium-ion economics reduce the penalty of higher-performance batteries, which in turn enables more aggressive charging strategies. However, total cost of ownership calculations now include power conversion efficiency, maintenance exposure, and integration labor. Suppliers that can reduce mechanical wear, simplify installation, or support modular scaling gain an advantage because facilities are looking to avoid hidden operational costs.
Supply chain maturity is also affecting time-to-deployment. As charging modules, connectors, and control systems become more standardized in certain segments, integration complexity can decline. Yet in custom intralogistics environments, bespoke engineering remains a significant value driver, especially where high-current delivery, custom docking, or mixed-vehicle environments are involved.
Competitive Dynamics and Differentiated Playbooks
The market features a diverse set of participants spanning specialist charging providers, industrial power companies, and broader automation integrators. Rather than competing on a single dimension, leading players are defining advantage through technology focus, deployment scale, integration depth, and regional footprint.
Wireless inductive specialists have positioned themselves around continuous operation and reduced mechanical wear. Wiferion, for example, has built recognition around inductive systems designed for opportunity charging, with recent industry acknowledgment for in-process charging technology. The strategic appeal is clear: if vehicles can charge without precise mechanical engagement or extended stationary periods, facilities can reduce downtime and maintenance overhead. VAHLE takes a complementary angle with conductive contacts and shuttle charging systems, emphasizing high-current fast charging and custom integration in intralogistics. This reflects a different bet: that robust contact-based infrastructure remains essential where high power, predictability, and integration with existing floor systems matter most.
Other participants compete on scale and ecosystem breadth. Delta Electronics has emphasized a large deployed base across industrial vehicles and AGVs, presenting its charging portfolio as part of a broader mobility and automation offering. This scale narrative matters because it suggests maturity in manufacturing, support, and multi-vehicle compatibility. Micropower Group focuses on high-frequency battery chargers for AGV applications, including onboard and stationary units with support for lithium-ion and opportunity charging, targeting flexibility on both the hardware and application side. EnerSys leans into integrated battery and charging solutions, framing power delivery as part of reliable industrial automation rather than as a standalone hardware category.
In Asia, several firms emphasize precision docking, non-contact power transfer, and system-level integration. Daihen and B&PLUS illustrate the focus on docking and non-contact power supply mechanisms, while Daifuku positions charging within broader material handling automation solutions. Guangdong Titans Intelligent Power highlights autonomous docking and multi-function charging for automated material handling, reflecting an emphasis on customized deployment and functional integration. Vicor Power enters from a different angle with high-efficiency power conversion and charging modules tailored for AGV battery systems, showing how component-level performance can matter as a differentiated layer within broader assemblies.
Recent events illustrate how these positions are being reinforced. Delta Electronics showcased its battery charging portfolio at LogiMAT in early 2026, underscoring the reach of its deployed solutions. Schaltbau advanced high-voltage DC connectors and microgrid concepts for faster charging of next-generation AGVs, pointing toward infrastructure-level enablement beyond individual vehicle charging units. These moves suggest a market that is not only refining vehicle-side charging but also rethinking how power is delivered, distributed, and integrated across facilities.
Looking ahead, the competitive landscape is likely to evolve through both convergence and specialization. Integration-heavy players may absorb more charging functionality into automation platforms, while specialist suppliers may deepen advantage in wireless efficiency, high-current contact systems, or docking precision. New entrants can still compete by targeting specific pain points such as autonomous docking reliability, modular scalability, or plug-and-play interoperability. The most important strategic question is whether a supplier competes as a component vendor, a system enabler, or a process-integrated solution provider.
PW Consulting Automotive & Machinery Research Center
Outlook: Key Trends Over the Next Three to Five Years
The next phase of market development will likely be defined by how charging systems fit into broader operational design rather than by simple capacity increases. Several trends stand out.
One major direction is the rise of charging as an integral workflow element. Facilities will increasingly design routes, staging areas, and vehicle Utilization patterns around short charging windows and opportunity charging points. This creates demand for systems that support autonomous alignment, fast energy transfer, and dependable docking behavior. The commercial opportunity lies in solutions that reduce the operational friction of charging rather than only improving raw power output.
Worldwide Mobile Charging Robot for Electric Vehicle Market
A second trend is the continued blending of contact and wireless approaches. Different applications will favor different methods, but many environments will need hybrid strategies. High-utilization vehicles may benefit from inductive top-ups in flow paths, while fixed docking points may use contact systems for rapid high-power replenishment. Suppliers that can offer interoperable architectures or clearly defined application-specific playbooks will be better positioned than those pushing a single technology in all contexts.
A third trend is infrastructure-level thinking. As charging demand grows, facilities will pay more attention to power distribution, microgrid integration, and centralized energy management. This shifts some value from pure vehicle-side hardware to broader electrical architecture and control software. Companies that can connect charging performance with facility-level energy planning will have an opening to become strategic partners rather than equipment suppliers.
These trends are not without risk. Standardization may lag behind deployment, creating fragmentation and integration cost. Overly aggressive charge-rate expectations could introduce thermal or battery-life constraints if not matched with robust system design. Demand may also vary by region and sector, making broad generalizations risky. The opportunity is strongest where charging strategy is aligned with actual process requirements, fleet composition, and total cost of ownership rather than treated as a one-size-fits-all upgrade.
Strategic Actions for Decision-Makers
For AGV manufacturers and automation integrators, the priority is to treat charging as part of the vehicle and workflow architecture, not as a bolt-on accessory. Design choices around battery size, docking tolerance, charge acceptance, and safety integration will influence customer throughput and maintenance costs. Suppliers that can demonstrate measurable reductions in downtime, simpler installation, or cleaner integration with mixed fleets will differentiate more effectively than those competing only on hardware specifications.
Worldwide Automatic Guided Vehicle Sensing System Market
For investors and corporate strategy teams, the most valuable exposure may come from companies that combine technical differentiation with deployment scalability. Wireless efficiency, high-current contact reliability, power conversion performance, and integration-ready software are all potential value drivers, but the key is whether those capabilities translate into repeatable deployments and lower integration risk. Monitoring how suppliers expand from component or system roles into broader facility-level solutions can provide early signals of competitive momentum.
For procurement and operations leaders, charging decisions should be evaluated against process impact. The right solution depends on vehicle utilization patterns, shift structure, floor layout, and tolerance for manual intervention. Opportunities to reduce idle time, simplify docking, or support opportunity charging in active flow paths can create operational benefits that outweigh raw hardware comparisons. Detailed segment-level data, application-specific benchmarks, and vendor-by-vendor capability mapping can materially improve procurement decisions and reduce implementation risk. For teams planning multi-phase automation rollouts, deeper research into charging architecture options, regional supplier dynamics, and total cost of ownership scenarios can help convert a technical choice into a strategic advantage.
For detailed analysis of this topic, please visit the official page: AGV Charging System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bubble Tea Syrup Market beyond 7.45% CAGR: 5 Strategic Shifts Shaping 2032 Growth
By pmarketresearch, 2026-09-18
Beyond the Boba Cup: Strategic Trends and Commercial Opportunities in the Bubble Tea Syrup Market
Market Snapshot: Navigating a Phase of Maturation and Complexity
The global bubble tea syrup market has entered a defining expansion phase, with total revenue reaching $2,150.0 million in base year 2025. Driven by sustained consumer enthusiasm and the international diffusion of Asian beverage culture, the market is projected to grow at a compound annual growth rate of 7.45%, advancing to an estimated $2,243.73 million in 2026 and reaching $3,555.43 million by 2032. Over the historical period from 2020 through 2025, the sector demonstrated consistent upward momentum, transitioning from a niche novelty to a structured global ingredient category. This trajectory reflects more than simple volume growth; it signals a market that is maturing, professionalizing, and increasingly susceptible to macroeconomic and regulatory forces.
PW Consulting Health Care Research Center
Despite the favorable growth backdrop, industry participants are navigating a period of structural transition. The first critical challenge lies in flavor standardization versus localization. As bubble tea operators scale across diverse cultural contexts, syrup providers must balance consistent taste profiles with regional palates, driving formulation complexity and elevating inventory management costs. The second challenge centers on supply chain fragility. Production depends heavily on sugar, fruit extracts, and natural flavor compounds, all of which remain exposed to agricultural volatility, export restrictions, and logistics bottlenecks. Price fluctuations in these inputs can quickly compress margins, particularly for mid-sized manufacturers operating with limited hedging capacity. The third challenge is the tightening regulatory perimeter. Markets in North America and Europe increasingly demand rigorous food safety certifications, traceability documentation, and compliance testing for imported syrup products. Navigating divergent regulatory frameworks while maintaining competitive lead times has become a prerequisite for sustained market access rather than a back-office compliance exercise.
Together, these dynamics are reshaping how syrup companies prioritize portfolio design, sourcing strategies, and geographic expansion. The market's continued growth is no longer solely a function of rising tea shop openings; it is increasingly determined by which players can align product innovation with supply resilience and regulatory readiness.
Key Demand Drivers: Forces Reshaping the Value Chain
Ingredient Innovation and Formulation Agility
The beverage landscape is shifting away from uniform sweetness profiles toward layered, experience-driven flavor architectures. Syrup manufacturers are responding by investing in multi-stage flavor layering, juicy acid-sugar balances, and texture-enhancing additives that complement tapioca pearls, jellies, and popping toppings. Recent activity in the sector highlights this strategic pivot. Companies are actively showcasing advanced syrup portfolios at major international trade events, using platforms like TUTTOFOOD Milano, IFE London, and the Winter Fancy Food Show San Diego to preview formulations tailored to emerging consumer expectations. These exhibitions have become essential testing grounds for cross-category inspiration, where fruit-forward blends, dessert-inspired reductions, and botanical accents are evaluated for mainstream commercial viability.
Equally significant is the acceleration of functional and health-aligned formulations. Consumer habits are evolving toward reduced-sugar, natural, and functional syrup concepts, including adaptogen-infused flavors and clean-label profiles. Syrup suppliers that embed these attributes early are capturing premium positioning and building loyalty with health-conscious operators. The competitive advantage now lies not just in taste replication but in delivering formulations that align with broader wellness narratives without sacrificing the indulgent experience that defines bubble tea.
Regulatory Pressure as a Catalyst for Quality Infrastructure
Food safety regulations in major Western markets have tightened considerably, requiring extensive testing, certification, and documentation for imported syrups. Rather than treating compliance as a reactive hurdle, leading manufacturers are using regulatory convergence as a driver of operational excellence. Suppliers are building internal quality frameworks that integrate HACCP, ISO, FDA, and Halal standards, creating multi-certified product lines that can cross borders with reduced friction. This shift is also reshaping buyer expectations. Franchise chains and QSR operators now prioritize suppliers who can demonstrate auditable quality processes across multiple jurisdictions, effectively turning regulatory capability into a procurement differentiator.
Cost Structure and Supply Chain Reconfiguration
Raw materials account for roughly 45-55% of operating expenses in bubble tea-related manufacturing, with sweeteners and fruit derivatives representing the largest cost blocks. This concentration makes cost volatility a strategic risk. Industry participants are responding by diversifying sourcing geographies, securing forward contracts for key inputs, and investing in formulation optimization to reduce dependency on price-sensitive commodities. Several manufacturers are also exploring concentrated juice and pulp integration to add perceived value while managing base ingredient costs. The broader effect is a supply chain under structural recalibration, where resilience and cost predictability are becoming as important as flavor performance.
Worldwide Flavor Tea Market
Competitive Landscape: Positioning, Diversification, and Consolidation Signals
The market remains relatively fragmented, with CR3 and CR5 concentration levels at 22.4% and 31.8% respectively. This structure leaves ample room for specialized players while simultaneously encouraging consolidation among manufacturers seeking scale, certification breadth, and geographic reach. Several core companies illustrate the strategic diversity emerging across the competitive field. Taiwan-based Sunnysyrup Food Co., Ltd. leverages more than six decades of manufacturing experience to offer concentrated juice, flavor syrups, popping boba, and full bubble tea ingredient suites, supported by OEM/ODM capabilities. Its active presence at multiple international trade shows reflects a go-to-market strategy centered on showcasing integrated solutions rather than single-ingredient transactions.
Chinese manufacturer Zonegoing Food has built its positioning around bulk boba syrup supply, including caramelized milk and brown sugar varieties, backed by HACCP, ISO, FDA, and Halal certifications. This multi-certification footprint enables cross-border flexibility and supports wholesale and private-label partnerships. Meanwhile, Fanale Drinks differentiates through ingredient transparency, offering flavoring syrups made in Taiwan with up to 25% real fruit juice and pulp, targeting operators seeking premium fruit-forward positioning. On the distribution side, Bossen and Qbubble serve as wholesale gateways, with Qbubble adding training and consultation services to deepen operator relationships beyond ingredient supply. Inspire Food Company has carved out a European leadership role by combining syrups, popping boba, tapioca pearls, and accessories into a single-channel offering, simplifying procurement for regional operators. Possmei extends its Taiwanese manufacturing base through U.S. agents and global distribution, while Yujie Food focuses on bulk syrups, jams, and cane sugar inputs, appealing to cost-sensitive and volume-driven segments.
Bubble Tea Market
The strategic divergence across these players points to a market that is simultaneously consolidating around certification and scale while fragmenting around niche differentiation. Leading manufacturers are moving beyond commodity syrup supply into integrated ingredient ecosystems, technical support, and portfolio depth. New entrants are likely to succeed by targeting underserved flavor specializations, functional claims, or regional compliance readiness rather than competing solely on price. The next phase of competitive evolution will favor companies that can combine formulation agility with reliable export infrastructure and clear brand narratives around quality, flavor authenticity, and operational support.
Future Outlook: Trends Shaping the Next Three to Five Years
Premiumization and Functional Flavor Convergence
Over the next three to five years, the syrup market is likely to see accelerated convergence between premium taste design and functional positioning. Consumers and operators will increasingly expect syrups that deliver layered flavor experiences while aligning with reduced-sugar, natural, or wellness-oriented narratives. This trend creates commercial opportunities for manufacturers who can develop clean-label bases, adaptogen or botanical additives, and fruit-forward formulations that command higher margins without alienating core indulgence buyers. Brands that invest early in R&D around these hybrid profiles will be better positioned to secure premium contracts with expanding tea houses and specialty beverage concepts.
Geographic Expansion in Asia Pacific and North America
Asia Pacific continues to anchor significant demand, supported by cultural familiarity, dense tea house networks, and rapid novelty adoption. North America remains a powerful growth engine driven by mainstream beverage experimentation, QSR integration, and wholesale distribution. Syrup suppliers that build localized portfolio strategies for these regions—adapting flavor intensity, packaging sizes, and certification readiness—can capture disproportionate share during the forecast period. Expansion success will depend less on blanket global offerings and more on region-specific product architectures that match local procurement habits and regulatory expectations.
Operational Resilience as a Competitive Moat
Supply chain volatility and raw material cost sensitivity will continue to reward manufacturers with diversified sourcing, forward procurement discipline, and formulation efficiency. Companies that treat cost resilience as a core capability rather than an operational afterthought will be better equipped to maintain pricing stability and margin protection. At the same time, regulatory divergence across markets will increase the premium on multi-certified production systems. The operational players that can scale while preserving compliance agility will hold a durable advantage, especially as larger franchise and retail buyers consolidate supplier lists around reliability and risk management.
Potential risks include overinvestment in narrowly defined flavor trends that may cycle quickly, escalating input costs that erode pricing power, and regulatory shifts that alter import requirements faster than supplier certification cycles can adapt. Navigating these uncertainties will require scenario-aware portfolio planning and flexible manufacturing footprints.
Strategic Actions for Decision Makers
For syrup manufacturers and ingredient suppliers: prioritize formulation platforms that can scale across premium, reduced-sugar, and functional variants without fragmenting production efficiency. Invest in multi-certification readiness and geographic sourcing diversification to reduce exposure to raw material volatility and import barriers. Use trade show channels and technical consultation services to deepen relationships with operators, turning ingredient supply into a broader operational partnership.
For investors evaluating exposure: focus on companies with credible OEM/ODM capabilities, multi-region certification coverage, and distribution infrastructure that supports export scalability. Favor business models that combine portfolio breadth with clear differentiation in flavor authenticity or functional positioning, as these are likely to command resilience in a fragmented but consolidating market. Monitor consolidation indicators, particularly around certification-driven M&A or regional distribution tie-ups.
For tea house operators, QSR buyers, and procurement teams: treat syrup selection as a strategic input that affects menu differentiation, compliance risk, and margin stability. Prioritize suppliers who can demonstrate consistent quality, regional certification coverage, and portfolio flexibility across fruit, brown sugar, and floral/herbal lines. Negotiate for formulation support and menu co-development where possible, since supplier collaboration can accelerate seasonal launches and reduce time-to-market for new offerings.
For operators, investors, and manufacturers seeking detailed segmentation data, region-specific demand mapping, and tailored scenario planning across the 2026-2032 forecast horizon, PW Consulting's full market research report provides deeper quantitative breakdowns and customized strategic guidance.
For detailed analysis of this topic, please visit the official page: Bubble Tea Syrup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pin Surface Treatment Chemicals Market: Why 6.74% CAGR Predicts 2032's $2.13B Trajectory
By pmarketresearch, 2026-09-18
Strategic Shifts and Commercial Opportunities in the Global Lead Pin Surface Treatment Chemicals Market
Market Landscape and Core Challenges
The global market for lead pin surface treatment chemicals has demonstrated consistent expansion over the past half-decade, reflecting the broader trajectory of advanced electronic packaging and precision metal finishing sectors. Valued at approximately $984 million in 2020, the market has progressed through steady annual increments to reach an estimated $1.35 billion in 2025. Forward projections indicate continued momentum, with the market expected to surpass $1.84 billion by 2030 and approach $2.13 billion by 2032, translating to a compound annual growth rate of roughly 6.74% across the forecast horizon. This growth trajectory is underpinned by persistent demand for reliable surface finishing solutions that enhance conductivity, corrosion resistance, and solderability in complex electronic assemblies.
Structurally, the market exhibits notable regional concentration, with Asia Pacific accounting for the largest share of revenue generation, followed by North America, Europe, Latin America, and the Middle East and Africa. Chemical type segmentation reveals that electroplating solutions dominate the product mix, while cleaning and degreasing agents, de-flashing chemicals, and surface passivation agents collectively represent the remainder of industry spend. Application-wise, integrated circuit packaging and consumer electronics connectors remain the primary demand centers, with automotive electronic components and industrial/telecommunications applications rounding out the core end-use segments. The competitive environment is moderately consolidated, with the top three participants commanding over 40% of total market revenue and the top five firms capturing nearly 57%, indicating that scale, proprietary formulations, and established customer relationships continue to provide meaningful barriers to entry.
Despite this favorable growth backdrop, the industry faces several structural challenges that will define competitive outcomes over the next several years. First, regulatory pressure continues to intensify across major jurisdictions. Stricter environmental legislation, including REACH enforcement and evolving EPA restrictions on hazardous substances, is reshaping formulation requirements. Surface treatment chemistry for lead pins and electronic components must increasingly eliminate or reduce reliance on hexavalent chromium, minimize volatile organic compound emissions, and accommodate lower-toxicity metal alloys. These compliance demands raise formulation complexity and can extend qualification timelines, particularly for high-reliability applications. Second, raw material volatility has become a persistent operational concern. Prices for metal salts, acids, and specialty additives that form the backbone of electroplating baths and cleaning solutions remain subject to geopolitical supply disruptions, energy cost fluctuations, and shifting mining outputs. This creates margin compression risk for producers who cannot pass through cost increases quickly or who lack diversified sourcing strategies. Third, the rapid evolution of electronic packaging architectures is forcing surface treatment suppliers to adapt at a faster pace than historical norms. Miniaturization, high-density interconnect designs, and mixed-material substrates place new demands on plating uniformity, adhesion, and defect control, requiring more frequent process innovation and closer collaboration with equipment manufacturers and end users.
These dynamics create a clear inflection point. Companies that rely on legacy product lines without regulatory or performance upgrades risk gradual share erosion, while those investing in compliant formulations, flexible supply chains, and application-specific engineering support are positioned to capture disproportionate value as customers navigate qualification and compliance transitions.
Key Growth Drivers
Technological Innovation in Surface Finishing Chemistry
One of the most significant accelerants for the market is the ongoing development of advanced plating chemistries and surface treatment processes tailored to the precision requirements of modern electronic components. Electroplating solutions continue to dominate product demand because they deliver the combination of conductivity, solderability, and mechanical protection that lead frames, connectors, and IC packaging structures require. However, the nature of innovation is shifting from incremental performance gains toward multi-functional formulations that simultaneously address corrosion resistance, interfacial adhesion, thermal stability, and environmental compliance.
Recent industry activity illustrates this shift in practice. In February 2026, Technic Inc. showcased surface finishing solutions aimed at complex precision component challenges, including chemistry relevant to electronic component manufacturing for medical device applications. While the demonstration emphasized medical device use cases, the underlying capability set—controlled deposit uniformity, specialty alloy and tin/tin alloy chemistry, and process integration for high-precision substrates—directly parallels demands in lead frame and connector surface treatment. Demonstrations of this type signal that leading suppliers are building application cross-over expertise, using adjacent high-reliability sectors to refine chemistries that can be redeployed into electronic packaging environments with demanding tolerance requirements.
Beyond electroplating, complementary process chemistry is also advancing. Cleaning and degreasing agents, de-flashing chemicals, and surface passivation agents are increasingly specified as integrated pre-treatment and post-treatment steps rather than standalone consumables. This reflects a broader recognition that surface quality is determined by the full process chain. Suppliers that can offer compatible chemistry suites—cleaner, activator, plating bath, and passivation—reduce variability for manufacturing lines and shorten process qualification cycles, which is a meaningful commercial advantage in cost-sensitive, high-volume production environments.
Worldwide Lead Solder Ball Market
Regulatory and Environmental Compliance Pressures
Regulatory developments continue to act as both a constraint and a catalyst. Stringent global environmental regulations, including REACH and EPA restrictions on hazardous substances, are accelerating the transition toward eco-friendly, chrome-free, and lower-VOC surface treatment formulations for electronics applications. For lead pin and lead frame surface treatment specifically, the shift is particularly consequential because traditional brighteners, corrosion inhibitors, and passivation chemistries have historically relied on substances that are increasingly scrutinized.
Compliance is not merely a defensive requirement; it is becoming a competitive differentiator. End users in consumer electronics, automotive electronics, and industrial systems are under their own sustainability and disclosure mandates, which flow down to component suppliers and further to chemical providers. Formulations that reduce hazardous substance exposure, support waste treatment efficiency, and lower energy consumption during bath maintenance are increasingly preferred in supplier selection. As a result, companies that proactively develop and validate compliant chemistries can secure longer qualification cycles, deeper integration into customer process workflows, and a stronger position in regions where regulatory enforcement is most active.
PW Consulting
Demand-Side Shifts in Electronics and Automotive Electronics
Demand-side behavior is being reshaped by three interrelated forces: the proliferation of high-reliability electronic interconnects, the expansion of automotive electronic content, and the continued scaling of consumer electronics connector usage. Integrated circuit packaging remains the largest application driver because surface treatment quality directly affects signal integrity, solder joint reliability, and protection against environmental degradation. As packaging complexity increases, particularly in advanced interconnection schemes and finer pitch layouts, the surface treatment layer becomes more critical to overall assembly yield.
Consumer electronics connectors also sustain robust chemical demand. The ongoing refresh cycle for mobile devices, wearables, and connected peripherals sustains high volumes of connector production, where surface finish consistency influences contact resistance, corrosion life, and mating reliability. Meanwhile, automotive electronic components represent a structurally important growth avenue. Vehicle electrification, advanced driver-assistance systems, and in-vehicle connectivity continue to increase the number and complexity of electronic control units and interconnect assemblies. Automotive-grade requirements for thermal cycling, vibration resistance, and long-term corrosion protection place elevated demands on plating and passivation chemistry, encouraging adoption of higher-performance surface treatment solutions.
Supply Chain Dynamics and Cost Structure Evolution
Cost structure dynamics are evolving as raw material price fluctuations in metal salts, acids, and specialty additives continue to influence production economics for electroplating and cleaning solutions. These inputs are essential to bath chemistry, and price instability can quickly affect gross margins, especially for high-volume commodity-grade products. At the same time, supply chain regionalization is reshaping procurement strategies. Customers are increasingly prioritizing supply continuity and geographic proximity for critical process chemicals, particularly where production facilities are concentrated in Asia Pacific or near major electronics manufacturing clusters.
This environment favors suppliers with diversified input sourcing, inventory buffer strategies, and the ability to offer technical support that helps customers optimize bath life, reuse, and waste handling. The competitive implication is clear: cost leadership alone is becoming less durable, while total cost of ownership advantages—derived from better process stability, fewer defect-related reworks, and reduced compliance risk—can command stronger customer retention.
Competitive Landscape and Leading Strategies
The market’s competitive structure reflects a blend of established specialty chemical manufacturers and regionally focused suppliers with strong application ties. Technic Inc., headquartered in Cranston, Rhode Island, is a prominent participant in specialty electroplating chemistry for lead frames, connectors, and electronic components. Its portfolio emphasis on precious metal and tin/tin alloy solutions for lead frame and LED substrate applications, along with connector-leadframe components, positions the company within the higher-value segment of the market where performance and qualification support matter more than price alone. Technic’s recent trade show participation, highlighting surface finishing solutions for complex precision manufacturing including medical device-related electronic component chemistry, suggests a strategy of extending application expertise across adjacent high-reliability segments, potentially reinforcing technical credibility and cross-industry learning.
MKS | Atotech, based in Berlin, operates with a strong focus on wet chemical process solutions for leadframe and connector applications. Its Puronon family of cleaners, chemical deflashing offerings, and pre-treatment processes tailored for IC lead frames and electronic packaging illustrate a process-integration orientation. Rather than competing solely on chemical formulation, the company appears to emphasize the fit between cleaning, treatment, and plating steps within production lines. This approach can reduce customer friction during process setup and improve consistency, supporting deeper relationships in IC packaging and connector manufacturing environments.
JCU Corporation, headquartered in Tokyo, offers surface treatment chemical products including alkaline electrocleaners, etching agents, and activators specifically intended for IC lead frames and electronic parts plating lines. Its product focus suggests a strong alignment with precision pre-treatment and process cleanliness, an area that is increasingly important as feature sizes shrink and defect sensitivity rises. By concentrating on the early stages of surface preparation, JCU addresses a part of the value chain where small variations can have outsized effects on downstream plating quality and final assembly reliability.
Lead Frames Market
Shanghai Sinyang Semiconductor Materials Co., Ltd. participates in the market through traditional packaging lead pin surface treatment chemicals as part of a broader portfolio spanning wafer processing and semiconductor electronic chemicals. Its positioning reflects the strategic importance of domestic supply in key Asian manufacturing ecosystems. Companies with local formulation, production, and technical service capabilities can gain advantages in responsiveness, logistics, and alignment with regional qualification requirements, particularly where electronics manufacturing activity is densely concentrated.
Nihon Parkerizing Co., Ltd., also based in Tokyo, supplies surface treatment chemicals for cleaning substrates and adding functionality, serving broad industrial applications including electronics and metal components. Its wider application footprint provides diversification across end markets and exposes the company to cross-sector innovation in surface functionality, which may feed back into electronics-specific development over time.
Several strategic themes emerge from this landscape. First, differentiation is increasingly tied to application-specific engineering capability. Companies that can combine formulation expertise with process troubleshooting, qualification support, and technical service are better positioned to defend margins than those competing primarily on product price. Second, the moderately concentrated market structure—where the top three firms capture a sizable share and the top five account for a majority—suggests that scale benefits matter, but they are not insurmountable. Smaller or regionally focused players can succeed by serving niche applications, offering specialized process chemistry, or building strong local service networks. Third, the market appears primed for selective consolidation and portfolio expansion. Larger participants may seek to acquire complementary process chemistries, regional service assets, or formulation capabilities that strengthen their ability to deliver end-to-end solutions. At the same time, new entrants with differentiated technology—such as low-environmental-impact chemistries or advanced deposit control—may find opportunities in segments where incumbents face regulatory or performance transitions.
Future Trends and Commercial Implications
Looking ahead, three trends are likely to shape the market over the next three to five years. The first is the continued expansion of compliance-driven formulation development. As environmental regulations and corporate sustainability expectations tighten, demand will increasingly favor chrome-free, lower-VOC, and otherwise reduced-hazard surface treatment chemistries. This will create commercial opportunities for suppliers that can demonstrate equivalent or superior performance while meeting regulatory and customer disclosure requirements. It will also raise the cost of inaction for companies still dependent on legacy formulations that face longer qualification timelines or sourcing constraints.
The second trend is the growing importance of integrated process chemistry rather than standalone consumables. As lead pin and connector manufacturers seek to reduce variability, improve yield, and accelerate line changeovers, they will favor suppliers that can support the full sequence of cleaning, surface activation, plating, and passivation. This trend favors companies with broader portfolios and stronger technical service depth, and it increases the strategic value of partnerships between chemical suppliers, equipment providers, and end users.
The third trend is the geographic realignment of supply and technical support around major manufacturing hubs. Demand concentration in Asia Pacific will continue to reward suppliers with local formulation, production, and service capabilities, while also encouraging multinational participants to strengthen regional presence and responsiveness. Over time, this may contribute to a more multi-polar competitive structure, where global technology leadership and local execution capability both matter.
Associated risks deserve attention. Raw material price volatility may persist, especially if input supply chains remain exposed to geopolitical disruption or energy cost swings. Regulatory requirements may evolve faster than formulation cycles in some jurisdictions, creating compliance misalignment risk for slower-moving players. In addition, changes in electronic packaging architecture and interconnect design could shift demand patterns between chemical types and application segments more quickly than historical trends would suggest, making portfolio flexibility a critical capability.
Strategic Recommendations for Decision-Makers
For manufacturers and process engineers, the priority is to align surface treatment chemistry choices with both performance targets and compliance trajectories. Selecting formulations with stronger environmental profiles and broader process compatibility can reduce qualification risk and support smoother transitions as regulatory expectations rise. Manufacturers should also evaluate suppliers based on total process support rather than product price alone, since formulation stability, defect reduction, and technical responsiveness often have a larger impact on operating economics than unit cost differences.
For investors and business development teams, the key is to identify companies with durable differentiation in application-specific chemistry, regulatory readiness, and regional service capability. Portfolio breadth, technical service depth, and the ability to integrate cleaning, plating, and passivation solutions are likely to be more predictive of competitive resilience than scale alone. Opportunities may also arise in adjacent high-reliability sectors, where cross-industry learning can accelerate product development for electronics applications.
For procurement and supply chain leaders, diversification of supplier sources and chemistry options can reduce exposure to raw material volatility and single-source qualification risk. Cost management should increasingly account for bath life optimization, waste handling efficiency, and process stability, since these factors influence total ownership cost. As regional manufacturing concentration continues, proximity of supply and local technical support may become more important selection criteria, particularly for high-volume or high-reliability programs.
Given the pace of regulatory change, raw material variability, and application-level demand shifts, detailed and current segmentation data will be essential for precise planning. The full report provides deeper visibility into regional revenue distributions, chemical type and application splits, competitive share dynamics, and scenario-based forecasts that can support more targeted strategic decisions and customized operational planning.
For detailed analysis of this topic, please visit the official page: Worldwide Lead Pin Surface Treatment Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com