

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Global Indirect Gas-fired Make-up Air Unit Market: The 5.3% CAGR Reality Beyond 2032 Forecast

Navigating the Strategic Landscape of the Worldwide Indirect Gas-fired Make-up Air Unit Market
Market Overview and Core Challenges
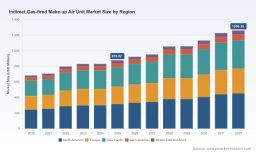
The global indirect gas-fired make-up air unit market has demonstrated steady expansion over the past half-decade, evolving from a niche HVAC component into a critical infrastructure element for industrial and commercial facilities. Valuation metrics from 2020 through 2025 indicate a consistent upward trajectory, with the market reaching approximately 878 million USD by 2025. Looking ahead, projections suggest continued growth through 2032, driven by replacement cycles, new construction, and retrofit activities. The compound annual growth rate reflects moderate but resilient expansion, signaling a maturing market that is increasingly sensitive to operational efficiency and regulatory compliance rather than pure volume growth.
Despite this positive momentum, the industry stands at a strategic inflection point defined by several persistent challenges. First, the balance between upfront capital expenditure and long-term operational savings remains a friction point for project owners. Indirect gas-fired units offer significant advantages in terms of air quality and combustion safety compared to direct-fired alternatives, but they often carry higher initial costs and complex installation requirements. Decision-makers in commercial and industrial sectors are increasingly scrutinizing total cost of ownership, pushing suppliers to justify premium pricing with demonstrable energy savings and durability.
Second, the regulatory environment is tightening across major regions, particularly regarding ventilation standards and energy efficiency. Compliance is no longer a checkbox exercise but a dynamic requirement that varies by jurisdiction and building type. Facilities managers must navigate a patchwork of codes that dictate airflow rates, combustion safety, and thermal performance. This complexity increases the barrier to entry for smaller players and elevates the value of manufacturers who can provide compliant, pre-engineered solutions that simplify approval processes.
Third, supply chain volatility and raw material fluctuations introduce uncertainty into pricing and lead times. The production of critical components, such as heat exchangers, is subject to commodity price swings and manufacturing capacity constraints. For instance, recent movements in steel markets and the valuation growth of the North America heat exchanger sector highlight how upstream cost pressures can ripple through to finished equipment pricing. These dynamics demand that manufacturers adopt more agile sourcing strategies and potentially pass through cost adjustments while maintaining competitiveness.
Key Drivers of Market Change
Technological Innovation and Performance Enhancement
Advancements in burner technology, heat exchanger design, and control systems are reshaping the value proposition of indirect gas-fired make-up air units. Manufacturers are increasingly offering modular configurations with modulating capabilities, allowing units to adjust output based on real-time demand. This flexibility improves energy efficiency and reduces fuel consumption during partial-load conditions, which is a significant consideration for facilities with variable ventilation needs. High-efficiency heat exchangers maximize thermal transfer while minimizing the footprint of the equipment, addressing space constraints in mechanical rooms and rooftop installations. Furthermore, integration with building management systems and advanced controls enables precise management of temperature, humidity, and air quality, aligning with broader trends toward smart building infrastructure.
Building Dedicated Outdoor Air System Market
Recent product documentation releases from leading companies underscore a focus on usability and comprehensive system integration. For example, updated start-up guides and installation manuals now include detailed control specifications and variable air volume options, reflecting an industry-wide emphasis on making complex systems easier to commission and operate. These documentation improvements support the adoption of indirect gas-fired technology by reducing the technical burden on contractors and facility staff, thereby accelerating deployment in commercial kitchens, industrial spaces, and institutional settings.
PW Consulting
Policy and Regulatory Environment
Regulatory frameworks are acting as both a constraint and a catalyst for market growth. Standards governing gas-fired equipment safety and performance, such as those maintained by ASHRAE and ANSI, provide the baseline for product certification and ensure consistent quality across regions. However, local building codes are increasingly embedding stricter ventilation and energy efficiency requirements. In California, for instance, the 2025 Building Energy Efficiency Standards, effective for permits applied on or after January 1, 2026, include strengthened mechanical system and ventilation mandates that directly impact HVAC equipment selection. Such regulations push facility owners toward compliant, higher-performance units that can meet elevated standards without compromising indoor air quality or thermal comfort.
The regulatory landscape also favors indirect-fired systems over direct-fired alternatives in applications where combustion byproducts must be fully isolated from the supplied air. This dynamic reinforces demand in sensitive environments such as healthcare facilities, food processing plants, and commercial kitchens, where air quality and safety are paramount. Manufacturers that proactively design for compliance and can navigate regional code variations gain a distinct competitive edge, as they reduce the risk and delay associated with permitting and inspection.
Demand-Side Shifts in Commercial and Industrial Sectors
Changes in how buildings and factories operate are altering ventilation requirements and, consequently, the demand for make-up air units. In industrial manufacturing, processes that generate heat, moisture, or airborne contaminants require reliable replacement air to maintain safe working conditions and operational efficiency. The trend toward decentralization and flexible manufacturing layouts means that ventilation systems must be adaptable and scalable. Similarly, in commercial buildings, the emphasis on occupant health and indoor environmental quality has elevated the importance of dedicated outdoor air systems and well-controlled make-up air solutions. Post-pandemic awareness has reinforced the link between ventilation and health, prompting asset owners to prioritize systems that deliver consistent, filtered, and tempered air.
Institutional and healthcare facilities represent another growing segment where precise air handling is critical. These environments often have stringent requirements for temperature stability, humidity control, and filtration to support infection control and patient comfort. Indirect gas-fired units that offer optional DX cooling and heat recovery capabilities are well-positioned to meet these demands. The convergence of health, safety, and comfort priorities is expanding the addressable market beyond traditional industrial applications, creating new revenue streams for manufacturers that can tailor solutions to diverse end-user needs.
Supply Chain and Cost Structure Dynamics
The cost structure of indirect gas-fired make-up air units is influenced by multiple factors, including raw material prices, manufacturing efficiency, and logistics. The health exchanger market, a key component segment, has seen valuation growth that reflects both demand and cost pressures. Volatility in steel and other metals can affect production costs, while regional manufacturing capacity and supply chain resilience determine lead times and delivery reliability. Companies that invest in localized production, strategic inventory management, and diversified supplier bases are better equipped to mitigate disruptions and maintain competitive pricing.
Moreover, the value of service and support is becoming more pronounced in the overall cost equation. Customers increasingly expect comprehensive documentation, technical assistance, and long-term maintenance support as part of the purchase. This shift means that total value is not solely determined by equipment price but by the reliability of the entire lifecycle offering. Manufacturers that can deliver consistent quality, timely support, and clear operational guidance reduce the hidden costs of ownership, making their products more attractive in a cost-conscious market.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated competitive environment, with a mix of specialized manufacturers and broader HVAC conglomerates. Leading companies differentiate themselves through product specialization, regional presence, and solution-oriented approaches. Greenheck, for example, offers a broad range of indirect gas-fired make-up air units with high-efficiency furnaces and modulating options, catering to commercial and industrial applications with capacities spanning thousands of CFM. Their focus on detailed installation and operation documentation highlights a commitment to supporting proper deployment and long-term performance, which resonates with contractors and facility managers seeking reliability.
Modine HVAC provides a portfolio of indoor and outdoor indirect-fired systems designed for tempered outdoor air delivery in commercial and industrial buildings. Their product lines include power-vented and separated combustion options, allowing them to address diverse installation constraints and ventilation requirements. Trane contributes with rugged, compact units suitable for both indoor and outdoor use, emphasizing durability and versatile heating, cooling, and ventilating capabilities. AbsolutAire specializes in ventilation systems for contaminant control, positioning its make-up air units as integral components for industrial and commercial environments where air quality management is critical.
Wall Mounted Gas Boiler Market
Regional players and specialized manufacturers also play important roles. Halton, based in Finland, offers ETL-listed indirect-fired units for commercial kitchens, industrial spaces, and institutional facilities, with options for DX cooling and heat recovery, aligning with the growing demand for multifunctional systems. Accurex focuses on commercial kitchen environments with horizontally firing burners designed to maximize heat exchanger life, addressing a specific pain point in high-use settings. AAON and Applied Air contribute packaged dedicated outdoor air systems and ventilation solutions that integrate indirect gas-fired heating, appealing to customers seeking consolidated, engineered solutions. Cambridge Air Solutions distinguishes itself with patented low-fire start technology and stainless steel burners, emphasizing performance and longevity in commercial and industrial applications.
The competitive landscape is evolving through a combination of consolidation, specialization, and incremental innovation. Larger HVAC firms may seek to expand their share through acquisitions or by broadening their product portfolios to cover more segments, while niche players often compete on technical expertise, custom engineering, and responsive service. New entrants face high barriers due to the need for certification, established distribution networks, and the trust of specifiers and contractors. However, opportunities exist for companies that can introduce differentiated features, such as enhanced efficiency, smart controls, or modular designs that simplify installation and retrofit. Market dynamics are also shaped by the emphasis on documentation and support; companies that provide clear, up-to-date guidance and maintain robust customer education efforts reduce adoption friction and strengthen their position with end-users.
Future Trends and Commercial Opportunities
Over the next three to five years, the indirect gas-fired make-up air unit market is likely to be shaped by a few interconnected trends. First, efficiency and integration will become even more central to value creation. As energy costs and sustainability goals gain prominence, facilities will prioritize units that deliver precise air handling with minimal waste. Manufacturers that combine high-efficiency heat exchangers, modulating burners, and advanced controls with optional cooling and heat recovery will capture demand from customers seeking to optimize both comfort and operating expenses. The ability to integrate seamlessly with broader building management ecosystems will be a key differentiator, enabling data-driven operation and predictive maintenance.
Second, regulatory harmonization and code evolution will continue to influence product design and market access. As more regions adopt stringent ventilation and energy standards, there will be increased demand for pre-compliant solutions that reduce the complexity of permitting and commissioning. Companies that invest in certification, regional compliance mapping, and flexible product platforms will be well-positioned to serve markets where codes are tightening. This trend also favors partnerships with engineering firms and contractors who can specify compliant systems early in the design process, locking in market share before construction begins.
Third, the market may see gradual consolidation as larger players acquire specialized firms to expand their geographic reach or technical capabilities, while smaller manufacturers focus on niche applications where they can command premium positioning. Supply chain resilience will remain a strategic priority, with companies diversifying sourcing and investing in inventory buffers to manage raw material volatility. For commercial opportunities, the strongest growth potential lies in retrofit projects where existing systems need upgrading to meet new codes or improve efficiency, as well as in sectors like healthcare and institutional facilities where air quality requirements are intensifying. However, risks include potential economic slowdowns that could delay capital projects, as well as the possibility of alternative technologies gaining traction if they offer comparable performance at lower cost. Manufacturers and investors should monitor these dynamics and align their strategies with the segments and regions where demand momentum is most robust.
Strategic Actions for Decision-Makers
For manufacturers, the priority should be to deepen differentiation through efficiency, control integration, and lifecycle support. Investing in product platforms that can be configured for a wide range of applications while maintaining compliance with evolving codes will help capture share across commercial, industrial, and institutional end-users. Emphasis on documentation, training, and post-sale support can reduce adoption barriers and build long-term customer relationships, which are increasingly valuable in a market where total cost of ownership matters more than initial price.
For investors, attention should focus on companies with strong technical capabilities, diversified end-user exposure, and resilient supply chains. Evaluating how well a company navigates regulatory changes and raw material fluctuations can provide insight into its ability to sustain margins and growth. Opportunities may also exist in segments where retrofit demand and code-driven upgrades create recurring revenue streams, particularly in regions where ventilation standards are tightening.
For procurement and facility management teams, the focus should be on aligning equipment selection with operational goals and compliance requirements from the outset. Engaging with suppliers early to ensure that proposed systems meet current and anticipated codes can streamline approval processes and avoid costly redesigns. Considering total cost of ownership, including energy efficiency, maintenance needs, and support availability, will lead to better long-term outcomes than focusing solely on upfront price.
Staying ahead in this market requires access to detailed segmentation data, regional dynamics, and competitive intelligence that go beyond high-level trends. Comprehensive research provides the granularity needed to make informed decisions about product development, market entry, procurement strategy, and investment allocation. For those seeking deeper insights, exploring the full range of analysis on the worldwide indirect gas-fired make-up air unit market can reveal the specific opportunities and risks that matter most to your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Indirect Gas-fired Make-up Air Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com