

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Slim Drapery Motors Market: Why 11.3% CAGR Through 2032 Changes Everything

Navigating the Global Slim Drapery Motors Market: Strategic Trends and Commercial Opportunities
Market Context and Core Challenges
The worldwide slim drapery motors market has matured rapidly over the past five years, moving from a niche automation segment to a core component of modern interior environments. Between 2020 and 2025, total market revenue expanded from approximately 202 million USD to 346 million USD, reflecting sustained demand for discreet, code-compliant window treatments. Forward projections indicate continued momentum, with revenue expected to reach 383 million USD in 2026 and climb toward 732 million USD by 2032. This trajectory translates to a compound annual growth rate of 11.32 percent, signaling that slim drapery motors are no longer an optional upgrade but a structural element of residential and commercial interior ecosystems.
Built In Electric Curtains Market
Despite this growth trajectory, the industry faces several inflection points that will shape competitive outcomes in the near term. The first challenge centers on standardization and interoperability. As smart-home protocols evolve and building management systems demand tighter integration, manufacturers must reconcile differing wireless standards, control architectures, and mounting requirements. Fragmentation increases development costs and complicates retrofit projects, where installers must navigate mixed hardware environments without compromising aesthetics or performance.
The second challenge lies in balancing form factor constraints with functional expectations. Slim motors must remain unobtrusive while supporting heavier fabric loads, longer travel distances, and frequent cycling. This creates engineering tension around battery capacity, torque delivery, thermal management, and noise levels. Products that over-index on compactness risk sacrificing reliability, while those that prioritize load capacity can undermine the discreet installation value proposition that defines the category.
The third challenge is regulatory and safety-driven adoption pressure. Stricter child-safety expectations and energy performance mandates in building codes are accelerating the shift away from corded treatments toward motorized, cordless alternatives. While this creates tailwinds, it also raises compliance complexity for manufacturers and specifiers who must verify that products meet evolving regional requirements without delaying project timelines.
Worldwide Slim Wallet Market
Key Demand Drivers
Technology Innovation and Wireless Architecture
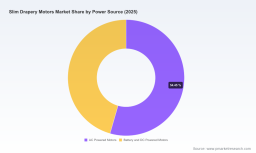
Technological progress is reshaping what slim drapery motors can deliver in both residential and commercial settings. The shift toward battery-powered and DC-driven designs has reduced dependence on in-wall wiring, enabling cleaner retrofits and faster installation cycles. Compact Li-ion platforms now support extended run times and hundreds of operational cycles per charge, while brushless motor designs improve efficiency and reduce acoustic output. These gains matter because drapery automation is increasingly evaluated not only on movement precision but also on everyday usability, including quiet operation, manual override capability, and seamless compatibility with surrounding hardware.
Wireless control has become equally important. Integration with Zigbee, Wi-Fi, and broader smart-home ecosystems allows end users to synchronize drapery movement with lighting, climate, and security functions. The expansion of interoperable protocols is lowering the friction of adding motorized window treatments to existing environments, especially in luxury residential projects and hospitality venues where aesthetic consistency and centralized control are priorities. As a result, product differentiation is moving beyond motor performance alone toward system-level compatibility, calibration ease, and software-supported user experiences.
Policy, Safety Rules, and Building Code Influence
Regulatory dynamics are acting as a powerful adoption catalyst. Child-safety requirements and energy-related building mandates are encouraging specifiers to favor cordless motorized treatments over traditional corded systems. This is particularly relevant in settings where occupant safety, maintenance standards, and long-term energy performance must be documented and verified. At the same time, the same regulatory environment raises the bar for product validation, installation documentation, and ongoing compliance. Companies that design with these expectations in mind gain an advantage in tender processes and specification pipelines, especially when projects involve public-facing or multi-family buildings.
Demand-Side Shifts in Residential and Commercial Sectors
Consumer and enterprise behavior is reinforcing demand from both ends of the market. In high-end residential spaces, buyers increasingly view motorized drapery as part of a broader automation and wellness narrative, where light control, privacy, and room ambiance are managed with minimal visual intrusion. In commercial and hospitality environments, the emphasis is on repeatability, durability, and integration with facility operations. Hotels, offices, and luxury retail spaces value motorized treatments that support consistent presentation, reduce manual handling, and fit within broader building management strategies. This dual demand profile broadens the addressable market but also requires manufacturers to tune product portfolios to very different usage patterns and performance expectations.
Supply Chain and Cost Structure Considerations
Cost structures are being redefined by material choices and installation labor dynamics. Slim drapery motors typically rely on compact DC or battery components and lightweight aluminum or polymer tracks that support discreet behind-panel installation. These design choices can reduce visible hardware and simplify integration, but they also place pressure on component sourcing and manufacturing precision. At the same time, wire-free and battery-powered configurations can lower installation labor by reducing the need for electrician-supported wiring in retrofit scenarios. The resulting labor savings are becoming a meaningful part of the commercial case for automation, especially in renovation projects where minimizing disruption is a priority. However, volatility in battery materials, electronics, and precision mechanical parts can still affect margin stability and time-to-market for new models.
Competitive Landscape and Leading Strategies
The market is not yet dominated by a single archetype. Instead, it features a mix of automation specialists, window-treatment brands, and component-oriented manufacturers pursuing different routes to value. One clear pattern is that leadership is increasingly defined by system integration rather than motor specifications alone. Companies that pair reliable motor hardware with compatible tracks, control ecosystems, and installation-friendly design are better positioned to win in specification-driven projects and repeat retrofit work.
Several firms illustrate this strategic diversity. Rowley Company emphasizes behind-panel installation in traverse systems with options supporting either battery or AC power, targeting users who need a compact motor that integrates cleanly with existing drapery hardware. Somfy has pushed into high-end wireless applications with Zigbee-enabled drapery motors designed for heavier fabric loads and discreet placement, while also connecting to smart-home platforms and professional control ecosystems. Hunter Douglas brings scale and channel strength through motorized drapery solutions and hardware integration, particularly in settings where branded automation and interior design alignment matter. BTX Intelligent Fashion focuses on customizable drapery systems with Li-ion motors, electronic limits, and auto-calibration, reflecting an emphasis on performance tuning and installer-friendly setup. Silent Gliss positions around premium motorized tracks and quiet brushless motors for heavier or higher installations, appealing to specifiers who prioritize finish quality and building management compatibility. Meanwhile, manufacturers such as Misdar and Dooya extend the competitive field with smart connectivity options across residential and commercial applications, often competing on integration flexibility and cost-effective connectivity features.
PW Consulting
Recent product and availability moves reinforce how quickly the category is evolving. In early 2026, Somfy highlighted a wire-free Zigbee drapery motor for luxury applications, showcasing wireless control, higher load capacity, and retrofit-friendly installation in a high-end context. Around the same time, a coordinated availability announcement extended that motor into a motorized line aimed at preserving aesthetics while adding automation. In 2025, another key player updated its drapery system lineup with improved Li-ion motor performance, stronger load handling, and auto-calibration features, indicating an ongoing race to improve cycle life, setup simplicity, and power consistency. These developments point to a market where feature upgrades are increasingly intertwined with installation practicality and ecosystem compatibility.
Looking at the broader structure, market concentration remains moderately consolidated, with the top firms capturing a meaningful share of revenue while leaving substantial room for specialized players. This balance creates two parallel dynamics. First, larger brands can leverage distribution, specification relationships, and cross-product integration to defend share in high-visibility projects. Second, smaller and regionally focused manufacturers can compete by targeting particular end uses, price points, or technical niches such as retrofit-friendly wireless controls, battery endurance, or custom track compatibility. The likely trajectory is not outright consolidation alone, but continued differentiation as companies choose between scale-oriented integration and specialized value propositions.
Future Trends and Strategic Implications
Over the next three to five years, slim drapery motors are likely to move further into the center of integrated interior and building automation rather than remaining standalone accessories. One key trend is the deepening of wireless interoperability. As specifiers and end users expect smoother connections across smart-home and commercial control platforms, motors that support widely adopted protocols and predictable integration behavior will gain preference. This will reward companies that invest in stable communication performance, straightforward pairing, and maintenance-friendly diagnostics rather than only promoting feature count.
A second trend is the continued refinement of battery and DC-powered designs for both retrofit and new construction. Installation labor savings, cleaner aesthetics, and cordless safety benefits will keep wire-free options relevant, but competition will intensify around real-world endurance, charging convenience, and reliable torque delivery across varying fabric weights. Products that can demonstrate consistent performance in demanding cycles, while remaining easy to install and recalibrate, are likely to earn stronger repeat-specification momentum.
A third trend is the growing importance of application-specific tuning. Residential luxury, commercial hospitality, and customized track systems do not share identical requirements, and winners will be those who tailor load capacity, noise profile, control granularity, and integration depth to each context. This creates opportunities for manufacturers to build focused portfolios rather than relying on a single universal offering. At the same time, uncertainty remains. Protocol fragmentation, component cost volatility, and shifting building-code interpretation could slow adoption in some regions or project types, especially where specifiers must balance performance, compliance, and installed cost.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product development with system-level appeal. That means treating motor performance, track compatibility, wireless reliability, and installation simplicity as a single value equation. Roadmaps that improve cycle life, reduce setup complexity, and support smoother integration with common control environments will be better positioned for specification wins and repeat business. It is equally important to prepare for regulatory-driven demand by ensuring that safety and compliance considerations are built into design and documentation from the outset.
For investors, the market suggests a preference for companies with clear differentiation in wireless integration, battery endurance, or application-specific hardware, rather than undifferentiated motor production alone. Due diligence should examine not just product features but also channel access, retrofit suitability, and the ability to serve both residential luxury and commercial hospitality demand without diluting execution focus. Businesses that can scale integration capability while managing component cost risk are likely to capture more durable share.
For procurement and specification teams, the most effective approach is to evaluate slim drapery motor solutions based on installed performance rather than catalog specifications alone. Key considerations should include load consistency across the full travel range, acoustic profile in occupied spaces, compatibility with existing or planned control systems, and the practical effort required for installation and maintenance. Projects that clarify these requirements early tend to avoid rework and achieve more predictable outcomes.
Given the speed of product launches, protocol evolution, and regulatory influence in this category, close monitoring of detailed segmentation, company-level positioning, and regional demand patterns can make a meaningful difference in strategy execution. A deeper review of the full market dataset and competitive profiles can help decision makers translate these trends into specific product, sourcing, and investment choices.
For detailed analysis of this topic, please visit the official page: Worldwide Slim Drapery Motors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com