

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Breath Out Filters Market: Why 5.78% CAGR and ICU Demand Reshape Growth

The Worldwide Breath Out Filters Market: Strategic Trends and the Next Phase of Growth
The global breath out filters market has entered a distinct phase of recalibration. Following a pronounced contraction in the 2022–2023 period, volume and revenue trajectories have stabilized, with the market poised to expand from approximately $975 million in 2025 toward a projected $1.44 billion by 2032. This recovery is underpinned by a compound annual growth rate of 5.78 percent across the forecast horizon, signaling steady but measured momentum rather than speculative acceleration. The trajectory reflects a sector transitioning from pandemic-era urgency to a normalized, protocol-driven purchasing environment where infection control, respiratory circuit integrity, and cost efficiency coexist as purchase criteria.
Behind the headline growth lies a market that is structurally maturing. Demand is increasingly tied to clinical workflow optimization, regulatory compliance, and the economics of extended circuit use, rather than emergency procurement cycles. Manufacturers and procurement teams alike are navigating a landscape where filtration performance standards are high, single-use protocols are strictly enforced, and reimbursement frameworks reward infection prevention strategies that reduce downstream complications. This shift has redefined how value is created and captured across the supply chain.
Several structural challenges are shaping the market's near-term evolution. First, the tension between filtration efficiency and breathing resistance continues to drive engineering trade-offs. High-performance hydrophobic media and electrostatic configurations deliver bacterial and viral removal rates exceeding 99.999 percent, but maintaining low resistance across varied clinical scenarios requires precise media engineering and consistent quality control. Any degradation in performance or perceived respiratory burden can influence clinician adoption and procurement specifications.
Fabric Filter Market
Second, regulatory and compliance complexity is intensifying. Breath out filters for anesthesia and respiratory care operate as Class II medical devices in major markets, requiring conformity to standardized connector dimensions, quality management systems, and individual testing protocols during manufacturing. Changing regulatory expectations, combined with the operational constraints of single-patient use, demand rigorous documentation and supply chain traceability. Companies that cannot demonstrate consistent compliance across production batches risk delays in market access and heightened scrutiny from procurement and infection control teams.
Third, cost pressure and procurement rationalization are reshaping purchasing behavior. Hospitals and respiratory care providers are increasingly optimizing circuit configurations to extend safe usage windows, often applying fresh patient-side filters per patient while managing machine-side components according to clinical protocols. This approach supports infection control objectives while controlling consumable spend, but it also raises the bar for suppliers to justify total cost of ownership rather than unit price alone. In this environment, differentiation depends on clinical reliability, workflow compatibility, and demonstrable support for extended-circuit protocols.
Market concentration reflects the maturity of the competitive field, with a modest level of consolidation among established players. This concentration provides some stability in supply and technical expertise, but it also creates space for targeted entrants that address niche clinical needs or regional procurement dynamics. The interplay between scale incumbents, specialized manufacturers, and emerging device companies is producing a landscape where strategic positioning matters as much as filtration performance.
Key Drivers Shaping Market Direction
Engineering Advances in Filtration Media and Circuit Integration
The most consequential driver of market evolution is the continued refinement of filtration media and its integration into breathing circuit architectures. Modern exhalation filters rely on hydrophobic media, pleated membrane structures, or electrostatic formulations to achieve high bacterial and viral removal efficiency while retaining 100 percent liquid-borne contaminant retention. These characteristics are not merely technical specifications; they directly support clinical objectives such as reducing cross-contamination in exhalation pathways, protecting ventilator components from airborne microorganisms, and enabling safer circuit reuse under controlled protocols.
Innovation is increasingly focused on balancing performance with usability. Manufacturers are developing filter configurations that minimize breathing resistance, simplify connection to tapered connectors compliant with recognized standards, and adapt to both dry and humidified respiratory support scenarios. The integration of exhalation filters with water traps, resuscitator circuits, and anesthesia systems illustrates a broader trend: filters are no longer viewed as isolated consumables but as integral elements of infection control workflows. This perspective is reflected in recent regulatory clearances for disposable expiratory filters and water trap combinations designed for ventilator breathing circuits, signaling that device ecosystems are becoming more tightly integrated.
Regulatory Expectations and Infection Control Protocols
Regulatory and standards-based expectations continue to shape product design, market access, and procurement decisions. Breath out filters for anesthesia and respiratory care must align with standardized connector dimensions and are generally classified as Class II medical devices, requiring premarket clearance pathways or equivalent conformity under medical device regulations. Quality management expectations, including adherence to recognized medical device quality systems, are now baseline requirements rather than differentiators. Manufacturers that maintain regulatory-registered facilities and conduct integrity and efficiency testing during production are better positioned to navigate procurement verification and post-market surveillance requirements.
Beyond compliance, clinical protocols are amplifying demand for filters that support extended circuit use without compromising safety. Infection control frameworks in hospitals increasingly emphasize patient-side filter replacement per patient, enabling circuits to be managed for longer durations under defined conditions. This protocol-driven approach encourages purchasing behavior that values filtration reliability, consistency, and documentation, especially in intensive care and surgical environments where circuit integrity is critical. The alignment between product design and protocol support is becoming a meaningful source of competitive advantage.
Demand-Side Shifts in Critical Care and Respiratory Support
Demand is being reshaped by broader trends in critical care capacity, respiratory support adoption, and the operational economics of healthcare delivery. Hospitals and care providers are prioritizing infection prevention in mechanical ventilation and anesthesia environments, where exhalation pathways can transmit airborne microorganisms if not properly filtered. As a result, breath out filters are embedded in procurement strategies that aim to reduce cross-contamination risk, protect equipment, and support standardized respiratory care workflows.
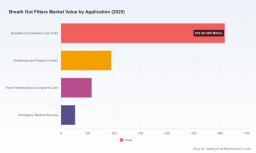
The residential and long-term care segment also contributes to demand diversification. Home healthcare and long-term care settings are expanding their use of respiratory support technologies, creating incremental demand for filters that are compatible with portable and durable devices. Recent clearances for portable oxygen concentrators that incorporate outlet filter components highlight how filtration elements are becoming part of broader respiratory device systems rather than standalone consumables. This convergence broadens the addressable market and introduces new purchasing dynamics, particularly where device makers and filter suppliers must coordinate on performance and compatibility.
Supply Chain, Material Constraints, and Cost Structure Dynamics
Cost structure and material availability remain influential drivers, particularly for products that depend on specialized hydrophobic media and precision-manufactured connector systems. The need for pleated membrane or electrostatic media with high efficiency ratings creates dependency on controlled material supply and consistent manufacturing processes. Any disruption in raw material sourcing or validation capacity can affect production continuity and lead times, which in turn influences procurement planning and inventory strategy for healthcare providers.
At the same time, procurement economics are pushing suppliers to demonstrate value beyond filtration specifications. Hospitals and distributors are increasingly interested in formats that reduce waste, simplify handling, and align with existing circuit configurations. Single-patient use requirements further constrain product design, since cleaning, sterilization, or reprocessing is not appropriate and may increase breathing resistance or leave residuals. This operational reality reinforces the importance of manufacturing consistency, clear instructions for use, and reliable supply commitments. Suppliers that can deliver predictable quality at scale, while supporting protocol-based usage, are better equipped to secure long-term purchasing relationships.
Competitive Landscape and Leadership Strategies
Established Players and Differentiated Positioning
The competitive field is anchored by a mix of large medical device manufacturers and specialized filtration companies, each pursuing distinct value propositions. Pentair's engineered filtration division has built a reputation around inspiratory and expiratory breathing circuit filters for ventilators and anesthesia applications, emphasizing bacteria and viral removal efficiencies above 99.999 percent, HEPA disposable devices, and respiratory filter capsules in multiple configurations. FDA registration and quality system certification underpin its market positioning, reinforcing trust among procurement teams that require documented compliance and consistent performance.
PW Consulting
Intersurgical offers a broad portfolio of electrostatic and pleated membrane breathing filters designed for anesthesia, critical care, and respiratory circuits, with product lines aimed at preventing cross-contamination in exhalation pathways. Its strategy centers on breadth of configuration and clinical familiarity, enabling it to serve diverse circuit setups and institutional preferences. Dräger contributes a strong presence in the operating room and intensive care settings through electrostatic filters and filter/HME combinations that protect ventilators from exhaled airborne microorganisms, aligning product design with equipment protection and infection control objectives.
Pall Corporation, now part of Cytiva, supplies a well-known range of breathing system filters with high airborne bacterial and viral removal efficiency and liquid-borne retention characteristics, used in anesthesia and respiratory care across patient-side and machine-side applications. Its positioning is reinforced by detailed performance documentation and validation practices, which support procurement verification and clinical confidence. GE HealthCare focuses on disposable single-patient-use anesthesia breathing circuit filters and humidifying membrane exchange filters compatible with its anesthesia platforms, leveraging system compatibility to strengthen attachment within installed equipment bases.
Regional and specialized manufacturers add further diversity. Mercury Medical, Smiths Medical, Medtronic, Fisher & Paykel Healthcare, and Flexicare each address specific clinical and circuit needs, from resuscitator and in-line filtration to humidified respiratory support and exhalation filter assemblies. Their strategies often center on product fit, responsiveness, and targeted clinical applications, allowing them to compete effectively in segments where performance, compatibility, or service expectations are highly specific. Recent regulatory clearances for portable oxygen concentrator outlet filters and disposable expiratory filter and water trap combinations illustrate how both established and emerging players are expanding the functional boundaries of filtration within respiratory device systems.
Strategic Themes Across the Competitive Field
Across these companies, several strategic themes are evident. First, performance claims are increasingly tied to documented validation and regulatory conformity, making traceability and testing discipline central to market access. Second, product portfolios are expanding from standalone filters to integrated circuit components, including water traps and device-specific configurations, reflecting the growing importance of workflow compatibility. Third, geographic reach remains uneven, with strong positions in North America and Europe and growing activity in Asia Pacific, Latin America, and the Middle East and Africa, where procurement patterns, clinical infrastructure, and regulatory pathways differ.
Market evolution is likely to feature both consolidation and differentiation. Larger players may seek to broaden their respiratory care portfolios through product adjacency or targeted acquisitions, while smaller manufacturers may compete on specialized media designs, regional service relationships, or device compatibility. New entrants are expected to focus on niche use cases, such as portable respiratory devices, specific circuit configurations, or cost-optimized formats that still meet clinical performance thresholds. The result will be a competitive environment where scale, technical documentation, and clinical integration all influence share dynamics.
For customers, this landscape creates both optionality and complexity. Procurement teams must evaluate not only filtration efficiency and compatibility but also supply reliability, regulatory standing, and alignment with infection control protocols. Manufacturers, in turn, must balance portfolio breadth with the ability to demonstrate consistent performance across configurations, regions, and clinical scenarios. Strategic leadership will increasingly depend on the capacity to integrate filtration performance with device ecosystems, protocol support, and supply chain resilience.
Future Trends and Strategic Implications
Trend One: Integration of Filters into Respiratory Device Ecosystems
Over the next three to five years, breath out filters are likely to become more tightly embedded within respiratory device systems rather than treated as purely interchangeable consumables. This trend is already visible in device designs that incorporate outlet filter elements and disposable expiratory filter combinations with water traps. As device manufacturers coordinate more closely with filtration suppliers, compatibility, serviceability, and performance validation will become integrated considerations. For suppliers, this opens opportunities to influence design early and secure attachment within approved device configurations. For procurement, it raises the importance of lifecycle planning, including availability of compatible replacements and support for device-specific infection control protocols.
Trend Two: Protocol-Driven Purchasing and Extended Circuit Management
Clinical protocols that support extended circuit use under controlled conditions are expected to strengthen demand for filters that enable safe per-patient replacement and reliable exhalation path protection. This protocol-driven model favors products with consistent filtration efficiency, clear usage guidance, and supply stability. It also reinforces the value of documentation that demonstrates compliance with quality management expectations and individual testing during manufacture. Commercial opportunity lies in helping institutions standardize circuit management practices while reducing variability in consumable performance. The associated risk is that any inconsistency in supply or perceived performance can disrupt protocol adherence and prompt re-evaluation of vendors.
Trend Three: Regional Expansion and Divergent Procurement Models
Growth will likely remain geographically uneven, with North America and Europe sustaining mature, protocol-guided demand, while Asia Pacific, Latin America, and the Middle East and Africa expand as respiratory care capacity and device adoption increase. In emerging settings, procurement models may prioritize affordability, device compatibility, and local service availability alongside performance requirements. Suppliers that can adapt product formats, documentation, and supply arrangements to regional expectations are better positioned to capture share without compromising clinical standards. The key uncertainty is the pace of infrastructure development and the consistency of regulatory enforcement across markets, which can affect both adoption speed and competitive entry.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Prioritize documented performance consistency and regulatory readiness as the foundation of commercial trust. Invest in media engineering that maintains high efficiency while keeping breathing resistance within clinically acceptable ranges, and ensure product documentation clearly supports single-patient use protocols. Where possible, align filter designs with device ecosystems and circuit configurations to improve attachment and reduce substitution risk. Build supply resilience for specialized media and connector components, since procurement teams increasingly view availability and lot consistency as part of total value.
For Investors and Strategic Partners
Focus on companies that combine validated filtration performance with integration into respiratory device workflows and credible compliance documentation. Evaluate exposure to protocol-driven demand in intensive care, anesthesia, and respiratory support, as well as the potential for portable and home-care device expansion. Consider whether portfolio breadth, regional reach, and supply chain discipline are sufficient to sustain positioning as procurement becomes more selective and cost-aware. Monitor regulatory and reimbursement developments that influence extended circuit use, since these can shift demand patterns and purchasing criteria.
For Procurement and Infection Control Leaders
Treat breath out filters as part of a broader infection control and circuit management strategy rather than a simple line-item expense. Validate compatibility with existing breathing circuits and ventilators, confirm single-patient use guidance, and assess supplier consistency in testing and documentation. Where extended circuit protocols are used, ensure that filter performance and replacement practices align with institutional infection control objectives. Request evidence of quality management conformity and individual integrity or efficiency testing to support procurement verification and reduce variability across batches.
The strategic importance of breath out filters will continue to rise as respiratory care becomes more protocol-driven, device-integrated, and regionally diverse. Decision-makers who understand the interplay between filtration performance, regulatory conformity, workflow compatibility, and supply reliability will be best positioned to manage risk and capture value. For organizations seeking a deeper view of segment dynamics, regional patterns, and company-level positioning, a comprehensive research report can provide the detailed breakdowns and scenario analysis needed to translate these trends into concrete strategy.
Air Filters Market
For detailed analysis of this topic, please visit the official page: Worldwide Breath Out Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com