

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Commercial Decorative Lighting Market: Beyond 5.45% CAGR, the Real Growth Drivers

Strategic Trends and Commercial Opportunities in the Decorative Lighting Market
1. Market Landscape and Core Challenges
The commercial decorative lighting market has transitioned from a supplementary design element to a central component of built-environment strategy. Revenue reached an estimated $17.9 billion in 2025, expanding from $12.5 billion in 2020. The trajectory indicates a compound annual growth rate of 5.45 percent through 2032, with projected valuation approaching $25.9 billion. Growth is no longer linear; it is increasingly shaped by overlapping forces of aesthetic demand, technological maturation, and macroeconomic volatility. Industry participants navigating this environment must recognize that scale alone will not guarantee resilience. The market’s structure favors operators who can align design innovation with supply-chain agility and regulatory compliance.
Three structural challenges define the current inflection point. First, raw material cost pressure is reshaping margin economics. Aluminum and copper prices climbed notably in 2025, with Chinese aluminum spot rates surpassing 21,000 RMB per ton. Because raw inputs typically represent 70 to 80 percent of operating expenses in LED lighting manufacturing, cost volatility flows directly into fixture pricing and contract negotiations. Second, trade policy adjustments have amplified input costs. Higher U.S. tariffs on steel and aluminum imports throughout 2025 have forced manufacturers to either absorb expenses, renegotiate supplier terms, or pass costs downstream. Third, the convergence of decorative aesthetics with connected lighting systems is accelerating, but integration complexity is rising. Buyers expect visually compelling fixtures that also deliver dimming precision, daylight responsiveness, and network compatibility, raising the bar for engineering and certification resources.
These pressures are reshaping competitive expectations. Firms that rely on static product lines or fragmented sourcing face compression in profitability, while those that treat decorative lighting as a performance-driven design category are better positioned to capture premium placements. The market’s next phase will reward operators who can decouple value creation from raw material exposure and translate design intent into reliable, specification-friendly outcomes.
2. Key Demand Drivers Shaping Market Direction
Technology innovation continues to redefine the commercial decorative segment. LED performance has moved beyond baseline efficiency to embrace refined color rendering, thermal management, and form-factor flexibility. Contemporary product releases emphasize advanced LED performance paired with updated aesthetics, allowing decorative fixtures to meet hospitality and retail expectations without sacrificing energy targets. Additive manufacturing is also gaining traction in niche architectural applications, enabling faster prototyping and customized geometries that traditional tooling struggles to achieve. These advances shorten development cycles and expand the visual vocabulary available to specifiers.
Christmas Lights and Christmas Decorations Market
Policy and regulatory dynamics are simultaneously redirecting procurement priorities. Energy codes and sustainability mandates are pushing commercial projects toward fixtures that combine visual impact with measurable performance. The regulatory environment favors connected systems that support scheduling, occupancy response, and centralized monitoring. At the same time, trade measures on steel and aluminum imports have altered cost calculations for manufacturers, making material strategy a competitive variable rather than a back-office concern. Companies are responding by diversifying supplier bases, re-evaluating bill-of-materials architecture, and emphasizing designs that reduce dependency on tariff-sensitive inputs.
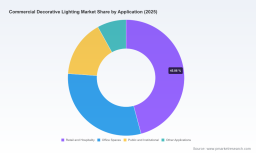
Demand-side behavior has shifted decisively. Retail and hospitality operators continue to treat lighting as a brand-expression tool, using decorative luminaires to influence dwell time, atmosphere, and perceived quality. Office environments are integrating decorative elements to support hybrid work identity and occupant well-being, while public and institutional projects increasingly specify fixtures that balance visual character with lifecycle efficiency. The result is broader specification activity across application types, with buyers evaluating decorative lighting not as an accessory but as part of a holistic spatial strategy.
Supply-chain and cost-structure adjustments are reinforcing these trends. Because raw materials account for the majority of manufacturing operating expenses, firms are prioritizing design-for-manufacturability, component commonality, and inventory planning that can absorb commodity swings. Recent trade show showcases and product launches illustrate how manufacturers are aligning outdoor decorative formats, interior pendants, and architectural wall units with both aesthetic refinement and production efficiency. The overall effect is a market where design differentiation and cost discipline must advance together.
3. Competitive Landscape and Leadership Strategies
The competitive environment remains moderately consolidated, with leading players holding meaningful share while specialized manufacturers compete on design authority and application expertise. Broad-portfolio providers compete through scale, specification support, and integrated product ecosystems. Their advantage lies in offering commercial indoor and outdoor decorative and architectural luminaires under established brand frameworks, enabling project teams to consolidate sourcing and simplify specification. Global lighting leaders extend this model with connected systems, energy-efficient fixtures, and wide geographic reach, positioning decorative lighting as part of broader professional solutions.
Design-focused manufacturers pursue a different path. Firms specializing in decorative and architectural LED fixtures concentrate on pendants, chandeliers, track, recessed, and commercial-grade formats tailored for hospitality, retail, and office settings. Their differentiation typically comes from refined proportions, material credibility, and close collaboration with architects and interior designers. Another segment of the market emphasizes high-end architectural and decorative lighting for interiors and exteriors, particularly retail and hospitality environments, where visual precision and finish quality drive specification decisions. Additional players bring decorative high-bay, cylinder, and architectural luminaires to commercial projects, with some exploring 3D-printed lighting approaches that open new pathways for custom forms and faster iteration.
Strategic positioning among leaders reflects a clear divide between breadth and depth. Large portfolios win when projects require multi-product consistency, broad availability, and integrated support. Niche specialists win when design intent is specific, finishes must be exact, and the project team values curated aesthetics over catalog convenience. Recent market activity reinforces both paths. New contemporary releases have expanded portfolios with refined aesthetics and advanced LED performance for commercial and hospitality spaces. Outdoor decorative introductions, including lantern-style LED post-top fixtures, highlight growing interest in streetscape, plaza, and entry-zone aesthetics. Major expos have also showcased architectural and decorative products aimed at commercial applications, signaling sustained demand for visually led yet performance-aligned solutions.
PW Consulting Automotive & Machinery Research Center
Market evolution is likely to continue along two tracks. Consolidation will remain attractive for buyers seeking procurement simplicity, warranty alignment, and specification continuity. At the same time, fragmentation will persist where design differentiation, regional taste, and custom architectural requirements create room for specialized entrants. New participants can gain traction by targeting underserved application niches, leveraging agile manufacturing, or combining decorative credibility with connected-function capabilities. The competitive edge will increasingly belong to firms that can articulate a clear design language while managing material exposure and specification complexity.
4. Future Trends and Commercial Implications
Over the next three to five years, decorative lighting in commercial environments is likely to move toward stronger integration between visual design and intelligent performance. Fixtures will be expected to do more than define a style; they will need to support adaptive dimming, tunable output where appropriate, and compatibility with broader building systems. This shift creates opportunities for manufacturers that can embed control readiness without compromising aesthetic integrity, and for specifiers who can standardize decorative families across multiple zones while preserving flexibility.
A second trend will be continued pressure on input costs and the resulting emphasis on material strategy. Because raw materials dominate manufacturing expense structures, firms that secure diversified sourcing, optimize component selection, and design for manufacturability will hold a cost advantage. Opportunities will emerge for product lines that maintain visual premium perception while reducing exposure to volatile metals and tariff-sensitive inputs. This also favors modular architectures that allow finish variation without redesigning core luminaire platforms.
A third trend involves application-driven customization across retail, hospitality, office, and public environments. Specification activity is broadening as buyers treat decorative lighting as part of spatial identity rather than a decorative afterthought. This opens room for tailored solutions in entry sequences, feature ceilings, retail display areas, and exterior pedestrian zones. The uncertainty lies in policy continuity, commodity pricing, and the pace at which connected-system standards mature. Firms that prepare for variation rather than assume stability will navigate these shifts more effectively. The commercial opportunity is clear: operators that align design credibility with performance reliability and supply resilience can capture higher-value placements and repeat specification cycles.
5. Strategic Actions for Decision Makers
Manufacturers should prioritize design platforms that can adapt to material volatility without abandoning aesthetic quality. That means investing in modular fixtures, control-ready internals, and sourcing strategies that reduce dependency on any single metal or import pathway. Leaders should also treat decorative lighting as a specification relationship business, strengthening collaboration with architects, designers, and facility teams so that product credibility translates into repeat project inclusion.
LED Lighting Market
Investors should evaluate exposure to both design differentiation and cost discipline. Companies with strong portfolio breadth may benefit from consolidation and specification simplification, while specialized players may offer attractive positioning if they serve high-value hospitality, retail, or architectural segments with clear finish and form advantages. Due diligence should examine raw-material sensitivity, tariff exposure, and the ability to integrate connected features without eroding margin.
Procurement leaders and specifier organizations should look beyond catalog variety and assess how decorative fixtures perform across lifecycle expectations, maintenance access, and control integration. Standardizing families where possible can reduce project risk, while reserving bespoke selections for feature zones can preserve design impact. Given the speed of product releases, trade-show activity, and shifting trade policy, timely access to detailed segment data and tailored scenario planning can improve sourcing decisions and reduce specification friction. For teams seeking deeper segmentation, competitive benchmarking, and customized strategic options, the full commercial decorative lighting market report provides expanded data and decision-ready breakdowns.
For detailed analysis of this topic, please visit the official page: Commercial Decorative Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com