
Blogs
Blood and Fluid Warmer Market: How 7.85% CAGR and Critical Care Demand Are Redefining Growth
By pmarketresearch, 2026-09-21
Market Intelligence Brief: Strategic Trends and Commercial Opportunities in the Blood and Fluid Warmer Market
The blood and fluid warmer market has moved from a niche clinical niche to a strategically important segment within broader patient temperature management and infusion therapies. Driven by rising surgical volumes, stricter perioperative thermal management standards, and a shift toward portable, high-flow warming solutions, the sector is entering a phase of disciplined growth rather than speculative expansion. Market size reached approximately USD 1.29 billion in the base year before progressing to an estimated USD 2.17 billion by the end of the forecast horizon, with a compound annual growth rate of 7.85 percent. This trajectory reflects steady demand expansion, but it also masks structural shifts in how devices are engineered, regulated, reimbursed, and positioned across care settings. For executives, investors, and procurement leaders, the opportunity lies not in assuming uniform growth, but in understanding where differentiation, compliance readiness, and real-world clinical adoption will separate winners from the rest.
Market Profile and Defining Challenges
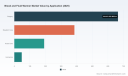
The overall market has expanded consistently from 2020 through the base year, with acceleration evident in the most recent periods. Growth is not evenly distributed across product types, clinical applications, or geographies, even though high-level splits point to clear concentration patterns. Intravenous warming systems remain the largest product category, reflecting the long-standing clinical imperative to warm fluids during transfusions, massive resuscitation, and high-volume infusion. Patient and surface warming systems also contribute meaningfully, underscoring how fluid warming is increasingly evaluated within a broader thermoregulation strategy rather than as a standalone device class. By care setting, surgical environments continue to anchor demand, while newborn care and acute care represent substantial and growing use cases. Regional dynamics show a mature, high-volume base in North America, followed by a sizable European footprint, with Asia-Pacific, Latin America, and the Middle East and Africa collectively representing a smaller but strategically important growth pool. Concentration metrics indicate a moderately consolidated environment, with the top three players holding roughly 42.5 percent of revenue and the top five approaching 58.2 percent, leaving room for specialized entrants and regional champions to compete on niche performance, portability, and workflow integration.
Against this backdrop, three challenges define the current market inflection point.
- Clinical precision and safety are now central purchase criteria, not secondary features. Fluid warming devices must deliver consistent temperature control across variable flow rates while minimizing risks such as air emboli, under-warming, or overheating. Regulatory scrutiny around labeling, performance specifications, and air-in-line risks has raised the compliance bar, making verification, documentation, and post-market monitoring essential parts of commercial viability.
- Workflow integration and portability are reshaping purchasing logic. Hospitals and emergency teams increasingly prefer solutions that can be deployed quickly, fit within limited clinical space, and integrate with existing infusion and fluid management workflows. This shifts competition away from basic heating capability toward usability, battery performance, flow range, and compatibility with high-acuity scenarios.
- Reimbursement clarity and procurement efficiency influence adoption velocity. Changes in coding status and hospital outpatient payment mechanics can alter the financial calculus for facilities evaluating warming systems, particularly in outpatient, emergency, and high-throughput surgical environments. Commercial teams therefore need to understand not only clinical evidence but also the administrative and reimbursement pathways that determine how quickly a device can be justified and deployed.
Core Demand Drivers Shaping the Market
The market’s direction is being pulled by interacting forces across technology, regulation, demand behavior, and cost structure. Each driver has practical implications for product strategy and commercial planning.
Technology Innovation and Performance Gaps
Innovation is moving beyond basic heating elements toward systems that combine flow adaptability, air detection, portability, and material safety. Recent developments illustrate how device makers are responding to performance requirements in specific use cases. One notable example is the clearance of a moderate-to-high flow blood and fluid warmer with automatic air detection, signaling that air-in-line protection and flow range are becoming baseline expectations rather than differentiators only in premium products. Another clearance focused on pediatric use, highlighting how smaller patient populations and lower flow requirements create distinct engineering challenges and open targeted commercial pathways. At the same time, device materials and manufacturing quality remain under scrutiny, with attention to components such as coated heating chambers and testing protocols aligned to recognized standards. These details matter because clinicians and procurement teams increasingly evaluate the entire system, not just the warming function in isolation.
Regulatory and Guideline Environment
Guideline updates and safety communications are reshaping how facilities think about active warming. Updated perioperative guidance has reinforced the importance of active temperature management, including fluid warming, which supports more consistent adoption in surgical and acute care pathways. Equally important, ongoing safety communications related to air-in-line and embolism risks with infusion pumps, fluid warmers, and rapid infusers continue to influence device design expectations and hospital vigilance. Rather than slowing the market, these dynamics tend to reward manufacturers that can demonstrate robust risk mitigation, clear labeling, and credible post-market documentation. For commercial leaders, regulatory readiness is becoming a market access advantage because it reduces adoption friction in risk-averse procurement environments.
Worldwide Peritoneal Dialysis Bag Warmer Market
Demand-Side Behavior and Care Setting Evolution
Clinical demand is expanding beyond traditional operating room settings. Emergency, trauma, newborn, and acute care teams are increasingly seeking warming options that can be mobilized quickly and used across variable flow conditions. Portable and battery-capable systems are particularly relevant where immediate access matters and where reliance on fixed infrastructure may limit responsiveness. This shift changes the purchasing conversation: it is less about buying a warming device for a single department and more about equipping multiple care points with solutions that fit fast-paced workflows. The practical effect is greater interest in devices that can support both high-flow resuscitation and lower-flow maintenance scenarios without forcing clinicians to switch between disconnected systems.
Supply Chain, Cost Structure, and Commercial Execution
Cost pressures and supply chain reliability remain important but are now intertwined with product complexity. Devices with more advanced sensing, air detection, and portability requirements require disciplined component sourcing and quality assurance. At the same time, procurement groups are under pressure to reduce total cost of ownership, standardize wherever possible, and avoid device proliferation that complicates training and maintenance. The result is a market where value is increasingly defined by the combination of clinical performance, training burden, service reliability, and compliance support. Manufacturers that can present a complete operational case, not just a hardware specification, are better positioned to win recurring adoption and repeat purchases.
Competitive Landscape and Strategic Positioning
The competitive field includes large diversified healthcare companies, specialized device manufacturers, and regional players with focused product lines. Profiles span companies offering integrated fluid warming within broader portfolios, portable systems designed for emergency and transport use, and engineered solutions emphasizing battery operation, flow range, or compact design. This mix creates a multi-layered market in which some competitors compete on scale, distribution, and cross-product integration, while others compete on portability, specialized clinical scenarios, and rapid deployment.
Differentiation Paths Among Leading Players
Several strategic positions are visible across the field.
- Portfolio integration plays: Some companies embed blood and fluid warming within wider fluid management, infusion, or critical care offerings. The advantage is cross-selling leverage, existing clinical relationships, and the ability to present a coordinated solution rather than a standalone device. The challenge is maintaining product-level excellence and responsiveness when warming is one component among many priorities.
- Specialized portable and high-flow solutions: Other players focus on compact, battery-powered, or high-flow devices built for emergency, trauma, and transport contexts. Their edge comes from mobility, quick setup, and performance in scenarios where fixed systems are impractical. These offerings can win strong loyalty in specific departments but must demonstrate durable reliability and regulatory compliance to scale.
- Niche engineering and targeted clearances: A subset of manufacturers builds differentiation around specific use cases, such as pediatric applications, air detection, or moderate-to-high flow performance. Targeted clearances can open distinct customer segments and provide a clearer value proposition to clinicians who need validated performance for a defined population or workflow.
Market Evolution: Consolidation, Fragmentation, and Entry Dynamics
The market appears likely to evolve along parallel tracks. Incumbent positions are supported by installed bases, regulatory histories, and distribution reach, which creates some resilience at the top of the market. At the same time, the breadth of clinical needs and the importance of specialized features prevent full commoditization. New entrants and smaller specialists can gain traction by solving concrete workflow problems, particularly where portability, air-in-line safety, and flow versatility matter most. M&A or partnership activity may increase as larger players seek to fill capability gaps in portability, digital integration, or specific clinical indications. For investors and strategic planners, the key question is not whether the market is consolidating in a simple sense, but where value is being created: in scale, in engineering specificity, or in the operational compatibility of the device with real clinical environments.
Forward-Looking Trends and Associated Opportunities
Looking across the current data and recent developments, three trends are likely to shape the next three to five years.
Infant Radiant Warmer Market
Trend 1: Performance Standardization Will Raise the Entry Bar
Air detection, flow adaptability, temperature consistency, and labeling clarity are becoming more central to purchasing decisions. As these capabilities become expected rather than exceptional, the practical barriers to entry rise. Devices that cannot demonstrate reliable performance across stated flow ranges, or that carry unresolved labeling or specification issues, face heightened scrutiny. The commercial opportunity lies in building compelling, verifiable performance narratives that reduce adoption risk for hospital teams and procurement groups. Manufacturers that treat compliance and performance documentation as part of the product story, not a back-office task, will likely see faster evaluation cycles and stronger trust from clinical buyers.
Trend 2: Portable, Multi-Scenario Warming Will Expand Beyond Traditional Settings
Demand is broadening into emergency, trauma, newborn, and acute care workflows where rapid deployment and flexibility matter. This creates opportunities for systems that can serve more than one clinical scenario without sacrificing safety or usability. Battery operation, compact form factors, and compatibility with varied infusion setups are likely to become increasingly important in procurement evaluations. Companies that design for these scenarios with clinically credible performance and clear practical advantages can capture share in segments where conventional warming solutions are less convenient. The risk is that portability claims outpace real-world reliability, so field validation and service support will be decisive.
Trend 3: Reimbursement and Guideline Alignment Will Influence Adoption Speed
Changes in coding status and payment mechanics, alongside stronger guideline emphasis on active warming, are likely to affect how quickly facilities adopt or expand warming programs. While these factors do not determine clinical value, they influence purchasing timelines, budget justification, and the administrative burden of adopting new devices. Commercial strategies that account for reimbursement pathways and guideline alignment can reduce friction and improve forecasting accuracy. At the same time, uncertainty remains because payment policy and institutional procurement behavior can shift, and any delay in reimbursement clarity can slow adoption even when clinical interest is strong.
Across these trends, the most durable commercial opportunities belong to organizations that can connect technical performance with operational fit. That means designing for the realities of busy clinical environments, providing evidence and documentation that support procurement decisions, and preparing for a market where safety, portability, and workflow compatibility are evaluated together rather than in isolation.
Strategic Actions for Decision Makers
Different audiences will extract value from the market in different ways. The following actions are most relevant for manufacturers, investors, and procurement or clinical leadership teams.
PW Consulting
For Manufacturers and Product Strategy Teams
- Prioritize verifiable differentiation. Build product narratives around flow range, air detection, portability, and material and labeling integrity, backed by clear documentation that procurement and clinical teams can evaluate quickly.
- Design for multi-scenario use where possible. Devices that can serve both higher-flow and lower-flow needs, or that fit emergency and inpatient contexts alike, reduce the need for multiple product acquisitions and simplify training.
- Treat regulatory and reimbursement readiness as commercial infrastructure. Maintain robust post-market processes, clear labeling, and an understanding of payment and coding developments so that market access is not delayed by avoidable administrative friction.
For Investors and Corporate Development Teams
- Focus on adoption readiness rather than headline growth alone. Assess whether a company’s technology fits real workflows, whether it has credible safety and compliance posture, and whether its distribution and service model can sustain repeat business.
- Watch for capability gaps that larger portfolios may want to fill. Solutions with strong portability, specialized flow performance, or validated pediatric or emergency use cases may attract interest from broader healthcare portfolios seeking to strengthen temperature management offerings.
- Factor reimbursement and guideline dynamics into valuation assumptions. Adoption speed can be influenced by coding status, payment updates, and institutional procurement cycles, so these elements should be part of scenario planning.
For Procurement, Clinical, and Hospital Leadership
- Evaluate total operational fit, not just warming capability. Consider setup time, staff training burden, compatibility with existing infusion workflows, service reliability, and how well the device supports both routine and high-acuity scenarios.
- Align device selection with guideline expectations and internal safety protocols. Preference for solutions that support active temperature management and address known risks such as air-in-line concerns can simplify internal justification and reduce clinical risk.
- Use evidence and post-market documentation as part of the evaluation process. Clear specifications, reliable labeling, and transparent performance claims help reduce uncertainty and support consistent adoption across departments.
The blood and fluid warmer market is moving toward a more disciplined, performance-driven phase in which growth is real but increasingly dependent on compliance readiness, workflow fit, and credible differentiation. For leaders evaluating entry, expansion, or procurement decisions, the most valuable intelligence is the kind that connects market size and trend direction to the specific operational realities of each purchase environment. Detailed segmentation data, company-level profiles, regulatory timelines, reimbursement mechanics, and region- and application-specific demand patterns can sharpen those decisions significantly. For teams that need that level of granularity, the full research report provides deeper breakdowns and tailored guidance to support planning with more precision.
For detailed analysis of this topic, please visit the official page: Blood and Fluid Warmer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Short Fiber Reinforced Thermoplastic Market: Why the 2032 $3.8M Outlook Changes Strategy
By pmarketresearch, 2026-09-21
Navigating the Short Fiber Reinforced Thermoplastic Composite Market: Strategic Trends and Commercial Opportunities
Market Landscape: Growth Trajectory Amid Structural Shifts
The short fiber reinforced thermoplastic composite market has established itself as a critical materials ecosystem, bridging the gap between traditional unreinforced polymers and heavier, more complex continuous fiber solutions. Over the historical period from 2020 through 2025, the sector demonstrated consistent expansion, reflecting steady adoption across manufacturing verticals that prioritize weight reduction, mechanical performance, and processing efficiency. The market’s evolution from a niche engineering substitute to a mainstream component material underscores a fundamental shift in how designers approach lightweighting and structural optimization.
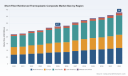
Looking ahead to the forecast horizon of 2026 through 2032, the market is projected to sustain a compound annual growth rate of approximately 4.52 percent, culminating in a total revenue base that will meaningfully outpace the starting valuation of the current cycle. This growth trajectory is not merely a continuation of historical momentum; it is being reshaped by material science breakthroughs, regulatory pressures favoring recyclable and lightweight structures, and a recalibration of supply chain priorities. The convergence of these forces is creating a market that rewards players who can balance cost efficiency with tailored performance characteristics.
Despite the positive outlook, the industry faces several structural challenges that will define competitive outcomes over the next few years. First, the tension between fiber loading optimization and processability remains a persistent bottleneck. Short fiber composites offer significant stiffness and strength improvements over neat thermoplastics, yet achieving high fiber loadings without compromising melt flow, surface finish, or cycle time requires sophisticated compounding expertise and sometimes costly processing adaptations. Manufacturers must navigate this trade-off carefully, particularly when end-users demand both performance and cost parity with unreinforced alternatives.
Second, raw material volatility and feedstock availability continue to inject uncertainty into cost structures. The prices of glass and carbon fibers, as well as the engineering resins that serve as polymer matrices, are subject to fluctuations driven by energy costs, capacity constraints, and regional supply dynamics. These variables complicate long-term pricing strategies and can compress margins for compounders and converters who lack vertical integration or long-term supply agreements.
Third, the market is experiencing a gradual but decisive shift toward sustainability-driven material selection. While short fiber reinforced thermoplastics inherently offer recyclability advantages over thermoset composites, the industry must still address end-of-life processing, fiber recovery, and the environmental footprint of virgin fiber production. Regulatory frameworks and corporate sustainability targets are increasingly mandating verifiable lifecycle benefits, pushing material developers to innovate in bio-based reinforcements, recycled fiber integration, and design-for-disassembly principles.
Key Drivers Reshaping the Market
Technological Innovation and Material Performance Breakthroughs
The pace of compounding and formulation technology has accelerated, enabling more precise control over fiber length distribution, dispersion quality, and interfacial bonding between fiber and matrix. Advances in twin-screw extrusion, reactive compatibilization, and surface treatment chemistries are allowing manufacturers to push fiber loadings higher while maintaining manageable viscosity profiles. These improvements translate directly into parts that can replace metal components or continuous fiber assemblies in applications where absolute maximum strength is less critical than balanced stiffness-to-weight ratios and high-volume producibility.
Equally important is the evolution of multi-material and hybrid reinforcement strategies. Formulators are increasingly blending glass and carbon short fibers, or combining synthetic fibers with natural reinforcements, to tune cost and performance curves for specific use cases. This customization capability is expanding the addressable market beyond traditional heavy-duty structural components into sectors that previously relied on metal insertion molding or unreinforced engineering plastics. The ability to dial in mechanical, thermal, and dimensional stability characteristics at the compound level is turning short fiber reinforced thermoplastics into a more versatile design tool rather than a single-purpose material class.
Policy and Regulatory Environment as a Catalyst
Regulatory momentum is converging on two fronts that directly benefit short fiber reinforced thermoplastic composites: lightweighting mandates and sustainability requirements. In transportation and industrial equipment, efficiency standards continue to tighten, compelling OEMs to reduce mass without sacrificing safety or durability. Short fiber reinforced thermoplastics offer a practical pathway to weight reduction through part consolidation, thinner wall designs, and substitution of heavier metals, all while retaining compatibility with high-volume injection molding and extrusion processes.
On the sustainability side, policies promoting circular economy practices and extended producer responsibility are reshaping procurement criteria. Unlike thermoset composites, thermoplastic matrices can theoretically be reprocessed, and short fibers do not inherently preclude recycling streams. However, achieving credible circularity claims requires clear data on recyclability, fiber recovery economics, and the performance of recycled-content compounds. Regulatory pressure is therefore pushing both material suppliers and end-users to invest in lifecycle assessment, standardized testing, and transparent reporting, which in turn elevates the strategic value of compounds that can demonstrably reduce environmental impact without compromising functional requirements.
Demand-Side Shifts in End-Use Markets
Demand is being reshaped by a broader design philosophy shift toward multi-material architectures and smart component optimization. Engineers are increasingly selecting materials based on localized performance needs rather than defaulting to a single material across an entire assembly. This approach favors short fiber reinforced compounds in applications where ribbing, boss features, and moderate load-bearing requirements can be met efficiently without the cost and complexity of continuous fiber layup or metal machining. The result is a growing emphasis on application-specific compound design, where mechanical properties, moisture resistance, thermal stability, and surface appearance are tailored to the part’s functional environment.
At the same time, sectors such as transportation, electrical and electronics, and consumer goods are driving volume growth through different mechanisms. Transportation continues to be a dominant demand center as vehicle platforms pursue mass reduction and corrosion resistance. Electrical and electronics applications are benefiting from the need for flame-retardant, dimensionally stable, and lightweight housing and connector materials. Consumer goods and industrial equipment manufacturers are exploring short fiber reinforced thermoplastics for durability and aesthetic improvements in high-wear components. This diversified demand base reduces dependence on any single vertical and provides a buffer against cyclical downturns in individual sectors.
Supply Chain Reconfiguration and Cost Structure Evolution
Supply chain dynamics are undergoing a structural reorientation as manufacturers reassess resilience, proximity, and total cost of ownership. The post-pandemic emphasis on supply security has encouraged regionalization of compounding and conversion capacity, reducing reliance on distant supply nodes and shortening lead times for custom formulations. This trend favors compounders with flexible production assets and strong technical service capabilities, as they can respond more rapidly to design changes, pilot runs, and localized demand fluctuations.
Cost structures are also being reshaped by the interplay between resin pricing, fiber costs, and processing efficiency. While engineering resins such as polyamide and polybutylene terephthalate command premium pricing relative to commodity grades, their ability to deliver higher thermal and mechanical performance can justify the added material cost when part consolidation and metal replacement are achieved. Similarly, the choice between glass and carbon fiber reinforcement creates a spectrum of cost-performance options, allowing formulators to align material economics with the criticality of the application. Companies that can optimize fiber-matrix compatibility, minimize scrap rates, and integrate compounding with downstream conversion are gaining a meaningful cost advantage in a market where margin preservation is increasingly tied to process excellence rather than raw material arbitrage alone.
Thermoplastic Composites Market
Competitive Landscape and Strategic Positioning
The market is characterized by a moderate concentration, with a handful of established compounders and specialty material suppliers capturing a meaningful share of differentiated, higher-performance formulations. Leading players have built their positions not simply on volume, but on technical depth, application engineering support, and the ability to deliver consistent quality across complex short fiber reinforced systems. The most successful companies treat compounding as a service capability, working closely with molders and design engineers to match fiber type, loading, and matrix selection to the functional, regulatory, and economic requirements of each part.
A representative group of companies illustrates the diversity of strategic approaches. One major U.S.-based manufacturer focuses on a broad portfolio of short fiber reinforced formulations with fiber loadings ranging from 10 to 50 percent, spanning commodity and engineering resins intended for semi-structural components. This breadth allows the company to serve a wide range of customers who need ready-to-process compounds with predictable behavior across multiple resin systems. Its competitive advantage lies in offering a library of standardized yet customizable options that reduce development time for parts requiring moderate reinforcement without the lead time of fully bespoke formulations.
A German producer takes a more bespoke approach, engineering tailor-made thermoplastic composites across a spectrum of fibers including glass, carbon, aramid, and natural fibers, and extending up to high-performance polymer matrices. This strategy positions the company in applications where standard compounds are insufficient and where performance, chemistry compatibility, or extreme environmental resistance dictate a custom solution. Its differentiation stems from deep formulation expertise and the ability to adjust fiber-matrix interactions for demanding conditions, making it a preferred partner for engineering teams that require precise control over material behavior.
A U.S.-based supplier specializing in short glass fiber reinforced compounds, offering chopped and milled glass fibers in a range of lengths across commodity and engineering thermoplastics, emphasizes structural and high-performance part solutions. This focus on controlled fiber geometry and consistent dispersion supports applications where predictable mechanical output and processing stability are critical. The company’s positioning reflects a practical, application-oriented approach that appeals to manufacturers seeking reliable reinforcement without the need for extensive material re-engineering.
The competitive environment is evolving along multiple vectors. Consolidation activity is expected to intensify as larger players pursue capability expansion, geographic reach, and access to specialized formulation know-how. At the same time, market differentiation is becoming more granular; companies are unlikely to win on price alone because the value proposition increasingly depends on engineering support, consistent quality, and the ability to solve application-specific challenges. New entrants and niche specialists may find openings in high-growth subsegments that require uncommon fiber combinations, bio-based or recycled content, or exceptional processing characteristics for advanced molding technologies. Ultimately, the market is moving toward a structure where scale provides cost leverage, but technical service and formulation agility determine customer loyalty and premium positioning.
Future Outlook: Trends and Commercial Implications
The next three to five years are likely to be defined by a tightening integration between material design and application engineering. Short fiber reinforced thermoplastic composites will increasingly be specified as part of optimized multi-material systems rather than as standalone replacements. This will elevate the importance of simulation-driven material selection, where finite element analysis and process modeling guide fiber loading, orientation, and matrix choice before tooling is committed. Suppliers that offer validated data packages, application notes, and process window guidance will be better positioned to shorten development cycles and reduce the risk of redesign.
PW Consulting Chemical & Energy Research Center
Sustainability and circularity will shift from aspirational goals to procurement requirements. Buyers will increasingly request evidence of recyclability, recycled content, and reduced carbon intensity, and materials that can integrate recovered fibers or bio-derived reinforcements without sacrificing performance will capture premium interest. Commercial opportunities will emerge for compounders that can deliver certified, drop-in sustainable formulations compatible with existing molds and processing equipment, thereby removing the friction that often accompanies material substitution. There is also potential in design-for-disassembly architectures, where short fiber reinforced thermoplastics are selected specifically because they can be separated and reprocessed more readily than thermoset counterparts.
A third trend is the continued expansion of processing versatility, particularly around high-speed injection molding, extrusion, and hybrid manufacturing flows. Improved fiber length control and dispersion will allow molders to produce parts with more consistent mechanical properties and fewer defects, expanding the range of geometries that can be economically molded. This trend opens opportunities in sectors that value part complexity and consolidation, such as under-the-hood automotive components, electronic housings, and industrial equipment where weight, durability, and cost must be balanced simultaneously. The risk is that processing windows can become narrower as fiber loadings and matrix performance increase, so the commercial winners will be those that pair advanced compounds with clear processing guidance and technical support.
Potential risks include raw material cost spikes, especially if fiber or resin supply tightens in key regions, and regulatory divergence that complicates global product rollouts. Another uncertainty lies in the pace of recycling infrastructure development; if post-industrial and post-consumer recovery systems do not scale in line with material adoption, circularity claims may remain limited to closed-loop or industrial scrap scenarios, constraining the breadth of sustainability-driven demand. Companies that diversify fiber and resin sources, invest in application-specific validation, and build transparent sustainability data will be better insulated against these uncertainties.
Strategic Actions for Decision-Makers
For Manufacturers and Compounders
Prioritize formulation agility as a core competitive asset. The ability to rapidly adjust fiber type, length, loading, and surface treatment in response to application requirements will differentiate suppliers in a market where standard compounds face increasing price scrutiny. Investing in compounding process control, dispersion quality, and consistent lot-to-lot performance will reduce customer risk and strengthen repeat business. Manufacturers should also expand technical service capabilities so that material recommendations are tied directly to part design, processing conditions, and end-use environment, not merely to generic property tables.
Develop a clear sustainability roadmap that connects material choices to verifiable lifecycle benefits. This includes exploring recycled and bio-based fiber options, documenting recyclability and recovery pathways, and aligning product offerings with the procurement criteria that OEMs and industrial buyers are beginning to enforce. A credible sustainability position can become a differentiator in bids where performance is comparable but environmental attributes influence selection.
For Investors
Focus on companies that combine scale with technical differentiation rather than volume alone. In a market where margin preservation depends on formulation expertise, application support, and process efficiency, businesses that can command premium pricing through value-added services are more resilient than undifferentiated commodity players. Pay attention to capabilities in high-performance matrices, hybrid fiber systems, and sustainable content, as these are likely to command stronger demand in segments pursuing lightweighting and circularity simultaneously.
Assess supply chain resilience and geographic positioning as part of the investment thesis. Regional compounding assets, diversified feedstock access, and strong customer technical relationships reduce exposure to logistics disruptions and price volatility. Investors should also evaluate the breadth of application exposure, since a diversified demand base provides stability when individual verticals face cyclical pressure or regulatory shifts.
Worldwide Advanced Thermoplastic Composite Market
For Procurement and Sourcing Leaders
Treat short fiber reinforced thermoplastic selection as a system-level decision rather than a simple material swap. Engage early with compounders and converters to align fiber loading, matrix choice, and processing parameters with part geometry, performance targets, and cost objectives. Early collaboration reduces the risk of suboptimal properties, rework, or processing bottlenecks that can erode the apparent cost advantage of a reinforcement strategy.
Require transparent data on processing windows, mechanical consistency, and sustainability attributes. Specification documents should encompass not only baseline mechanical properties but also tolerance to processing variation, moisture sensitivity where relevant, and available recycled or bio-based content options. Building these requirements into procurement criteria encourages suppliers to compete on overall value, including reliability and lifecycle performance, rather than on unit price alone.
For organizations seeking a more detailed segmentation view, competitive benchmarking, and tailored scenario planning across specific resin systems, fiber types, applications, and regional dynamics, the full PW Consulting research report provides the granular data and customized guidance needed to translate these strategic themes into concrete decisions.
For detailed analysis of this topic, please visit the official page: Short Fiber Reinforced Thermoplastic Composite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the HFC Refrigerant Market
The hydrofluorocarbon (HFC) refrigerant market is entering a period of complex transformation, driven by tightening regulatory frameworks, evolving technological standards, and shifts in global demand patterns. As of 2025, the market operates with a revenue baseline of approximately USD 5.65 billion, having grown from around USD 3.8 billion in 2020 at a compound annual growth rate of 6.25 percent through the forecast horizon extending to 2032. This trajectory reflects a sector that continues to expand in absolute terms, even as it faces structural pressures that will reshape how refrigerants are produced, allocated, and consumed. The market is not shrinking; it is recalibrating. Understanding the mechanics of that recalibration is essential for executives, investors, and procurement leaders who must align their operations with the next phase of industry evolution.
PW Consulting
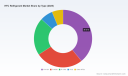
The concentration of market activity among a small group of established players underscores the capital-intensive and technically specialized nature of refrigerant production. The top three participants command roughly 78.5 percent of market revenue, while the top five collectively account for approximately 95 percent. This level of concentration suggests that access to compliant production capacity, regulatory expertise, and established distribution channels remains a significant barrier. It also indicates that pricing power, product diversification, and strategic partnerships will likely play an outsized role in determining which organizations can sustain growth as the regulatory landscape tightens and raw material dynamics fluctuate.
Market Sizing and Trajectory Context
From a macroeconomic perspective, the HFC refrigerant market has demonstrated consistent expansion over the past half-decade, with revenue moving from 3.8 billion in 2020 to 5.65 billion in 2025. Projections for the coming years indicate continued growth, with revenue expected to reach 6.26 billion in 2026, 6.55 billion in 2027, and 6.76 billion in 2028. The trajectory accelerates modestly through the end of the decade, reaching 7.23 billion in 2029, 7.57 billion in 2030, 7.95 billion in 2031, and 8.45 billion in 2032. A 6.25 percent compound annual growth rate across the 2026 to 2032 forecast period signals that demand will remain resilient, particularly in cooling-intensive applications, even as regulatory mechanisms systematically reduce the availability of high-global-warming-potential compounds.
Worldwide Freon Refrigerant Market
This growth pattern should not be interpreted as a simple continuation of past trends. The composition of demand is shifting, the cost structure of production is becoming more volatile, and regulatory compliance is adding new layers of operational complexity. Organizations that treat the market as a static volume play risk misallocating capital and missing the strategic inflection points that will define competitive positioning over the next several years.
Core Challenges and Inflection Points
Three structural challenges are converging to create a pivotal moment for the HFC refrigerant sector. The first is the regulatory mandate to reduce production and consumption of high-GWP HFCs. Under the AIM Act framework, an 85 percent reduction in production and consumption is required by 2036, with application-specific allowances renewed through 2030 and reporting requirements for 2025 data due by March 31, 2026. This phasedown schedule forces manufacturers, equipment builders, and end users to plan around a shrinking pool of conventional refrigerants, while simultaneously managing transition timelines for alternative formulations.
The second challenge lies in the tightening of operational compliance at the equipment level. Effective January 1, 2026, EPA Subsection H rules require leak inspection and repair protocols for HFC systems containing 15 pounds or more of refrigerant, with GWP limits of 300 for systems over 200 pounds. The EPA HFC Leak Repair and Management Rule (Subsection H) came into effect in January 2026, imposing leak detection and repair requirements on HFC-containing appliances meeting the threshold. This rule changes the economics of refrigerant use by increasing maintenance obligations, raising the cost of compliance, and making leak prevention a material factor in total cost of ownership.
The third challenge is the volatility and upward pressure in raw material costs. Chinese hydrofluoric acid prices rose with an annual average increase of 12.52 percent in 2025, supported by stable costs and peak-season refrigerant demand. HFC refrigerant spot market prices remained firm at elevated levels in April 2026 amid subdued trading activity. These cost dynamics compress margins for producers and increase procurement risk for buyers, particularly when combined with supply chain strains that have already triggered significant price adjustments in specific product lines. A notable example occurred in April 2025, when a leading manufacturer announced a 42 percent price increase on R-454B refrigerant cylinders due to supply chain strains and regulatory transitions. This type of pricing movement illustrates how regulatory transition pressure and logistics constraints can combine to create abrupt cost shocks for end users.
Key Drivers of Market Change
The trajectory of the HFC refrigerant market is being shaped by a tightly interconnected set of drivers that span technology, regulation, demand behavior, and supply chain economics. Understanding these drivers in isolation is insufficient; their interaction is what determines where value will be created and where risk will accumulate.
Technological Innovation and Formulation Shifts
The push toward lower-GWP formulations has accelerated the development and commercialization of refrigerant blends and alternative chemistries that can operate within existing or slightly modified equipment architectures. Manufacturers are increasingly focused on HFC-32 blends, R-454B, and other intermediate-GWP options that offer a pragmatic balance between performance, safety, and regulatory compliance. One recent example of this dynamic is the May 2025 commercial arrangement between Arkema and Honeywell, which strengthened Arkema’s range of lower-GWP refrigerants through expanded access to HFO blends for HVACR applications while supporting the HFC phasedown. This type of portfolio expansion allows equipment manufacturers and service providers to access compliant alternatives without waiting for entirely new production ecosystems to mature.
From a strategic standpoint, the innovation frontier is not solely about replacing one molecule with another. It is about building product portfolios that can adapt to regional regulatory variation, application-specific performance requirements, and evolving safety classifications. Companies that can offer a graduated pathway—from current HFCs to lower-GWP blends and ultimately to next-generation alternatives—will be better positioned to retain customer relationships across multiple transition cycles.
Policy and Regulatory Environment
Regulatory pressure is the single most consequential driver in the current market cycle. The combination of an 85 percent phasedown target by 2036, application-specific allowance renewals through 2030, and the new leak detection and repair obligations creates a multi-layered compliance environment. The EPA’s proposed rule to address stranded high-GWP HFC inventory extends compliance deadlines, with effects on food retail refrigeration equipment use extended to 2032. This extension provides temporary relief for certain end-use sectors, but it also prolongs the coexistence of legacy and transitional refrigerants, complicating procurement planning and inventory management.
For industry participants, regulation is no longer a distant compliance issue. It is an active determinant of pricing, availability, and product design. Reporting obligations for 2025 data due by March 31, 2026 add a transparency layer that increases visibility into production and consumption patterns, which in turn can influence allowance allocation and market expectations. Organizations that integrate regulatory tracking into their strategic planning will be better equipped to anticipate allowance constraints, adjust product roadmaps, and avoid reactive procurement decisions.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand for cooling and refrigeration continues to grow, driven by rising ambient temperatures, expanded cold-chain requirements, and the electrification of heating and cooling in both residential and commercial segments. Air conditioning remains the largest application category, followed by refrigeration and a smaller share of other applications. This demand base provides a structural floor for refrigerant consumption, even as the mix of refrigerants used shifts toward lower-GWP options.
At the same time, end users are becoming more sensitive to total cost of ownership, including maintenance, leak management, and regulatory compliance. The new leak inspection and repair protocols for systems with 15 pounds or more of refrigerant make it more expensive to operate high-GWP systems without rigorous maintenance discipline. As a result, equipment buyers and facility operators are increasingly weighing refrigerant choice against serviceability, downtime risk, and long-term compliance exposure. This behavioral shift favors suppliers and equipment manufacturers that can demonstrate reliable performance, clear compliance pathways, and lower-risk operating profiles.
Supply Chain and Cost Structure Dynamics
Cost pressures are being amplified by raw material movements and logistics constraints. The 12.52 percent annual average increase in Chinese hydrofluoric acid prices in 2025 reflects a broader environment where key inputs are subject to seasonal demand spikes and cost stability on the upstream side, while downstream demand remains strong. At the same time, HFC refrigerant spot market prices held firm at elevated levels in April 2026 despite subdued trading activity, indicating that pricing is being supported by structural factors rather than short-term speculation.
Supply chain strains have also manifested in sharp price increases for specific transitional refrigerants. The 42 percent price increase on R-454B cylinders announced in April 2025 highlights how regulatory transition demand, combined with constrained supply and logistics friction, can produce rapid cost escalation. For procurement teams, this underscores the importance of forward visibility into allowance allocations, production capacity, and regional price dynamics. For producers, it reinforces the value of diversified feedstock strategies, flexible manufacturing footprints, and stronger customer contracting approaches that can buffer against short-term volatility.
Competitive Landscape and Leading Strategies
The HFC refrigerant market is dominated by a concentrated group of global chemical and industrial companies, complemented by a set of equipment-focused and specialty producers that play important roles in specific channels. The strategic positioning of these players reveals a landscape where portfolio breadth, regulatory agility, and partnership networks are becoming as important as raw production capacity.
Worldwide Refrigerant Cylinder Market
Strategic Positioning of Core Players
Honeywell International Inc., based in Charlotte, North Carolina, is a leading producer of HFC refrigerants through its Solstice line and HFC-32 blends for HVAC and refrigeration systems. Its strategic emphasis on lower-GWP formulations and blend technology positions it as a bridge supplier during the transition from legacy HFCs to next-generation options. The company’s April 2025 price adjustment on R-454B cylinders reflects both the realities of supply chain strain and the pricing leverage that can emerge when compliant transitional products are in high demand.
The Chemours Company, headquartered in Wilmington, Delaware, is a major supplier of HFC refrigerants under its Freon and Opteon brands, with a clear focus on R-410A alternatives and blends. Chemours’ brand heritage and broad distribution relationships give it significant visibility across multiple end markets, while its blend-oriented portfolio supports customers seeking compliance pathways that can be implemented with relatively modest equipment modifications.
Arkema S.A., based in Colombes, France, provides HFC-32 and low-GWP HFC refrigerants for commercial and industrial refrigeration applications. Its May 2025 commercial arrangement with Honeywell demonstrates a strategy of expanding access to HFO blends and lower-GWP options without requiring full vertical integration of every technology pathway. This partnership model allows Arkema to widen its offering while participating in the broader phasedown trajectory.
Daikin Industries Ltd., headquartered in Osaka, Japan, is both a manufacturer and supplier of HFC refrigerants, including R-32 and R-454B for air conditioning and heat pump systems. Daikin’s vertical integration across equipment and refrigerant supply gives it a distinctive ability to align refrigerant development with system design, which can reduce transition friction for customers and create a more controlled path to compliance.
Carrier Corporation, based in Palm Beach Gardens, Florida, produces and distributes HFC refrigerants and refrigerant-containing HVAC equipment systems. Its equipment-centric orientation means that refrigerant strategy is tightly linked to product roadmaps, service networks, and customer migration plans. Trane Technologies plc, located in Davidson, North Carolina, supplies HFC refrigerants for commercial refrigeration and HVAC systems, with a similar emphasis on application-specific solutions and service compatibility.
Iofina Chemical, based in Maryland, remains an active producer of HFC refrigerants under EPA production for export allowances, reflecting the continued importance of trade dynamics and regulatory allowances in shaping global supply. Linde plc, headquartered in Wicklow, Ireland, supplies HFC refrigerants and related industrial gases for refrigeration and HVAC applications, leveraging its broader industrial gas infrastructure to support integrated supply and logistics across multiple end-use channels.
Market Structure Evolution
The market is likely to continue evolving along three tracks. First, consolidation pressure will persist among producers with undifferentiated assets or limited access to compliant portfolios, while companies with strong blend technology, regulatory expertise, and global distribution will be better positioned to capture share. Second, differentiation will increasingly center on transition readiness: the ability to supply intermediate-GWP blends, support leak management compliance, and provide application-specific guidance will become more valuable than commodity volume alone. Third, new entry will remain challenging due to concentration, capital intensity, and regulatory complexity, but selective partnerships, licensing arrangements, and regional niche plays can still create meaningful footholds.
In this environment, competitive advantage will depend less on asserting scale for its own sake and more on demonstrating the ability to navigate phasedown schedules, manage input cost volatility, and deliver reliable compliance pathways. The companies that can combine product flexibility with regulatory foresight and supply chain resilience will be the ones that shape the next phase of market development.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to define the market’s evolution and create distinct commercial opportunities for organizations that respond proactively.
Trend 1: Accelerated Migration to Intermediate and Lower-GWP Blends
The combination of phasedown targets, allowance constraints, and leak management requirements will drive a faster shift toward intermediate-GWP blends and lower-GWP alternatives in both air conditioning and refrigeration. This migration will create opportunities for suppliers that can offer clear formulation pathways, consistent quality, and application-specific support. It will also create opportunities for equipment manufacturers that align product lines with compliant refrigerants and simplify the transition for end users. The commercial value here lies in reducing transition risk: customers will pay a premium for clarity, reliability, and a credible path through the regulatory timeline.
Trend 2: Compliance-Driven Service and Lifecycle Value
The EPA Subsection H leak detection and repair requirements, together with GWP limits for larger systems, will make maintenance and leak prevention central to the economics of refrigerant use. This shifts the competitive focus from initial product price to lifecycle performance, service quality, and compliance assurance. Providers that integrate refrigerant supply with leak management guidance, inspection protocols, and repair support can capture additional value while helping customers avoid regulatory exposure. Over time, this may lead to more bundled offerings that combine refrigerant, equipment, and service components into a single compliance-oriented solution.
Trend 3: Regional Divergence and Strategic Sourcing
Regulatory timelines, allowance structures, and raw material dynamics will not move uniformly across regions. Asia Pacific is expected to continue representing a substantial share of market revenue, while North America and Europe will be shaped by their own phasedown schedules and compliance frameworks. Latin America and the Middle East and Africa will remain smaller but potentially fast-moving in specific application segments. This regional divergence will reward organizations that can tailor sourcing, product mix, and compliance strategy to local conditions rather than applying a single global template. Strategic sourcing relationships, allowance-aware procurement, and region-specific product planning will become important differentiators.
Risks and Uncertainties
Several uncertainties could alter this trajectory. If regulatory timelines are adjusted further, or if allowance allocation mechanisms create unexpected shortages, price volatility could intensify and disrupt procurement plans. If raw material costs continue to rise, margins may be squeezed and end-user adoption of transitional products could slow in price-sensitive segments. If leak management compliance proves more costly or operationally complex than anticipated, some customers may delay transitions or seek alternative solutions that reduce exposure. Finally, the coexistence of legacy, transitional, and next-generation refrigerants could create fragmentation in service practices and supply chains, increasing complexity for multi-site operators and distributors.
Strategic Recommendations for Decision Makers
For manufacturers, the priority should be to build transition-ready portfolios that span current HFCs, intermediate blends, and lower-GWP options, while investing in regulatory tracking and compliance support capabilities. Product roadmaps should be aligned not just with technology development but with phasedown schedules, application-specific rules, and leak management obligations. Supply chain resilience should be strengthened through feedstock diversification, flexible production planning, and forward visibility into allowance and export dynamics.
For investors, the market offers exposure to a sector that is growing in absolute terms but undergoing significant structural change. The most compelling opportunities are likely to be found in companies with differentiated blend technology, strong compliance orientation, and the ability to serve high-value applications with lower transition risk. Due diligence should focus on regulatory exposure, allowance dependency, raw material sensitivity, and the strength of customer relationships in segments where compliance and service quality matter most.
For procurement and supply chain leaders, the most important action is to move from reactive purchasing to forward-looking planning. This means mapping refrigerant needs against phasedown timelines, understanding leak management obligations for relevant systems, and building sourcing strategies that account for regional price divergence and supply constraints. Long-term agreements, diversified supplier bases, and early engagement with compliance requirements can reduce exposure to sudden price shocks and availability gaps.
As the HFC refrigerant market continues to evolve, the organizations that succeed will be those that treat regulatory change, cost dynamics, and technology transition as interconnected strategic variables rather than isolated operational issues. For decision makers seeking a more granular view of segmentation dynamics, regional variations, and customized scenario planning, the full research report provides deeper data and tailored analysis to support implementation.
For detailed analysis of this topic, please visit the official page: HFC Refrigerant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PMSM Market to Hit $28.81B by 2032: Why 7.7% CAGR Signals a Strategic Shift
By pmarketresearch, 2026-09-21
The PMSM Market at a Strategic Inflection Point: Trends, Challenges, and Where Value Is Created
The global landscape for Permanent Magnet Synchronous Motors (PMSM) has shifted from a niche technology segment to a foundational power transmission architecture across multiple industries. Over the 2020–2025 cycle, the market expanded from approximately $12.5 billion to $17.18 billion, reflecting a steady compound annual growth trajectory that analysts project to continue through 2032. At a 7.7 percent CAGR, the segment is expected to reach roughly $28.81 billion by the end of the forecast period, signaling a structural expansion rather than a temporary cyclical surge. This growth is not distributed uniformly across regions, motor configurations, or end-use sectors, and that unevenness is where competitive advantage is being forged. Executives evaluating capacity allocation, portfolio strategy, or capital deployment should recognize that the PMSM market is entering a phase where efficiency mandates, raw material dynamics, and application-specific performance requirements are converging to reshape demand patterns.
Dc Permanent Magnet Motor Market
Market Scale, Concentration, and the Shape of the Opportunity
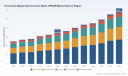
The headline figures point to a market that has more than doubled its baseline in just over a decade, but the strategic story lies in the composition of that growth. Asia Pacific continues to anchor the largest share of revenue, reflecting the concentration of manufacturing capacity, electrification investment, and industrial modernization in the region. North America and Europe follow, each drawing strength from distinct demand engines: North America benefits from industrial automation modernization and a rapidly scaling electric mobility ecosystem, while Europe's growth is tightly coupled to energy efficiency directives and advanced manufacturing reshoring. Latin America and the Middle East and Africa represent smaller but strategically relevant footprints, often tied to infrastructure modernization, emerging industrial bases, and selective mobility programs. Across motor types, interior permanent magnet designs command the largest revenue share, a reflection of their dominance in applications demanding high power density, precise control, and compact packaging. Surface-mounted variants and other specialized configurations maintain meaningful positions in segments where thermal management, cost structure, or manufacturability favor alternative layouts. In terms of applications, electric vehicles represent the most visible growth vector, but industrial automation, robotics, conveyors, compressors, and precision motion control systems collectively account for a substantial and steadier portion of demand. The market is moderately concentrated, with the top three players capturing roughly 45 percent of revenue and the top five approaching 60 percent, a structure that suggests scale advantages, technology portfolios, and service ecosystems matter, but there remains meaningful space for differentiated specialists and regional champions.
Key Challenges and Strategic Inflection Points
Three challenges define the current operating environment for PMSM suppliers and downstream buyers. First, the economics of rare earth permanent magnets create a persistent cost and supply risk. Neodymium-iron-boron (NdFeB) magnets constitute over 90 percent of material costs in production for many PMSM designs, and the manufacturing capacity for sintered NdFeB magnets is heavily concentrated in a single geography. This concentration introduces exposure to export controls, pricing volatility, and logistics disruptions, making magnet sourcing a strategic variable rather than a routine procurement activity. Second, the market is navigating a mismatch between standardized motor offerings and the growing demand for application-specific optimization. As vehicles, industrial equipment, and precision machinery demand higher efficiency at partial loads, faster dynamic response, and tighter integration with power electronics and control software, generic motor configurations are losing relevance in premium segments. Third, the industry is facing a regulatory and standards environment that is accelerating adoption but also raising the bar for validation, lifecycle efficiency, and traceability. Energy and resource-saving PMSM and synchronous reluctance motor systems are entering commercial mass production, and efficiency mandates across industrial and automotive applications are reinforcing the shift toward high-performance synchronous architectures. The inflection point is clear: the companies that can decouple performance from raw material intensity, align product roadmaps with regulatory trajectories, and deliver integrated solutions rather than isolated motor units will capture disproportionate value.
Key Drivers Reshaping the PMSM Market
Technology Innovation and the Push for Higher Efficiency at Lower Material Intensity
Innovation in PMSM design is increasingly focused on achieving competitive power density and efficiency without proportionally increasing rare earth content. Advances in rotor topology, magnetization patterns, thermal management, and winding architecture are enabling manufacturers to optimize torque ripple, reduce losses at partial load, and improve controllability. These improvements matter because many real-world applications do not operate at peak load; they cycle through variable speeds, frequent starts and stops, and partial-load conditions where efficiency and responsiveness determine total cost of ownership. At the same time, the integration of motors with inverters, sensors, and control firmware is becoming a differentiator. A motor that performs well in isolation may underdeliver in a system where torque control, thermal limits, and communication latency intersect. As a result, engineering leadership is shifting from component-level specifications to system-level performance, and suppliers that can co-design motors with power electronics and control strategies are gaining an edge in high-value applications. The recent push toward energy- and resource-saving PMSM and synchronous reluctance motor systems entering commercial mass production illustrates this direction: performance is being redesigned to align with both efficiency mandates and material constraints.
Policy and Regulatory Tailwinds Reinforcing Adoption Across Sectors
Regulation is acting as both a demand catalyst and a design constraint. In industrial contexts, efficiency standards and corporate sustainability targets are driving retrofits and new equipment purchases toward motor systems that reduce energy consumption across duty cycles. In mobility, electrification mandates and emissions frameworks are accelerating the replacement of legacy drivetrain architectures with permanent magnet synchronous solutions that offer precise torque control and compact packaging. Compliance is no longer a checkpoint at the end of development; it is increasingly embedded in product architecture decisions, from material selection to thermal design to lifecycle documentation. This regulatory environment rewards companies that can demonstrate measurable efficiency gains, maintain consistent quality across batches, and provide evidence of performance under real operating conditions. It also raises the stakes for suppliers that rely on fragmented design approaches or inconsistent validation, because the cost of non-compliance or underperformance is rising across both industrial and automotive pipelines.
PW Consulting
Demand-Side Shifts in Mobility and Industrial Automation
On the demand side, two broad behavioral shifts are reshaping the market. Electric vehicle platforms are moving from early adoption to mainstream scaling, but the motor requirements within that segment are diversifying. Different vehicle classes, duty profiles, and packaging constraints are creating a need for motors that balance power density, cost, thermal robustness, and manufacturability. Meanwhile, industrial buyers are prioritizing automation that reduces labor dependency, improves throughput consistency, and supports energy-conscious operation. Robotics, precision motion control, conveyors, compressors, and machine tools are all seeing renewed investment in motor systems that can deliver accurate positioning, rapid acceleration, and efficient operation across variable loads. The common thread is a preference for motors that are not only efficient at peak performance but also dependable and controllable in dynamic operating conditions. This is shifting purchasing criteria from price-per-unit toward total system value, including integration ease, lifecycle serviceability, and compatibility with control and automation architectures.
Supply Chain Realities and Cost Structure Pressures
The cost structure of PMSM production is increasingly defined by magnet availability, processing capacity, and the ability to manage volatility without eroding margins. Because rare earth magnets account for such a large share of material cost, procurement strategy has become a core competitive lever. Suppliers are exploring multiple routes to resilience: diversifying magnet sources where possible, designing for reduced rare earth intensity, improving recycling and recovery pathways, and standardizing components to reduce variability. At the same time, manufacturing footprint decisions are being influenced by the location of downstream demand, the cost of energy and labor, and the need to be close to customers for customization and service. The practical effect is that scale alone is no longer the sole determinant of advantage. Companies that can combine disciplined material management with flexible manufacturing and strong supplier relationships are better positioned to protect margins through cycles of demand growth and input volatility.
Competition Landscape: Positioning, Differentiation, and the Evolution of Advantage
How Leading Players Are Building Defensible Positions
The competitive field in the PMSM market includes established industrial conglomerates, specialized motion control manufacturers, automotive-adjacent suppliers, and regional players with strong local execution. A defining feature of the leaders is the breadth of their portfolios paired with the depth of their application expertise. Large multinational suppliers typically compete by offering integrated solutions that span motors, drives, control software, and service support, which reduces integration risk for customers and creates switching costs that protect recurring revenue. Their advantage often lies in the ability to standardize core motor architectures while tailoring performance through control strategies, packaging, and optional features. This approach allows them to serve multiple verticals without fragmenting their engineering base too thinly.
Specialized and regional players compete in a different way. Rather than pursuing breadth, they focus on specific performance niches, hygiene-sensitive environments, compact applications, or regional service requirements where responsiveness and customization matter more than scale. Their differentiation often comes from mastering a narrow set of requirements exceptionally well, whether that is high-precision motion, harsh-environment reliability, cost-efficient manufacturability for a particular motor form factor, or close collaboration with local system integrators. The recent product activity in the sector reflects these divergent strategies. For example, Yaskawa Electric Corporation launched the MOTOMAN-HD7 and HD8 servo systems designed for hygienic environments, an indication that application-specific robustness and compliance with stringent cleanliness requirements are becoming valued differentiators in selected industrial and life sciences contexts. In mobility, Nidec Corporation signaled its intent to unveil next-generation mobility technologies, including advanced motors, at a major industry exhibition, reinforcing the continued focus on drivetrain performance, packaging, and integration as competitive battlegrounds. Mitsubishi Electric Corporation also received recognition for its railcar motor system, an example of how synchronous motor solutions are being validated in demanding transportation applications where reliability, efficiency, and lifecycle performance are closely scrutinized.
Strategic Positioning and the Role of Integration
The most resilient positions in this market are built on integration and system-level value creation. Suppliers that can deliver not only a motor but also the accompanying control logic, thermal strategy, and service model reduce the complexity burden for end users and increase the likelihood that their products become embedded in long-lived deployments. This is especially relevant in industrial automation, where downtime costs and retrofit complexity influence purchasing decisions, and in mobility, where packaging constraints and performance consistency shape platform choices. In contrast, companies that compete primarily on component price without differentiation in control, reliability, or service face greater exposure to margin pressure and substitution risk. As efficiency mandates tighten and application demands become more specific, the premium on integration capability is likely to increase, favoring players that can orchestrate the interaction between motor, drive, and control layers.
Consolidation, Fragmentation, and the Role of New Entrants
The market's moderate concentration suggests room for both consolidation and fragmentation depending on the segment. In high-volume, standardized applications, scale advantages in manufacturing, procurement, and distribution can drive consolidation, as larger players capture efficiencies and downstream customers prefer fewer, more capable suppliers. In specialized segments, fragmentation can persist or even intensify, because the value lies in solving distinct technical challenges rather than in pure volume. New entrants are most likely to succeed when they address a clearly defined performance gap, such as lower rare earth dependence, improved thermal behavior in a specific duty cycle, or a control architecture that simplifies integration for a particular customer segment. The strategic implication is that market share movements will not be uniform. Growth will be redistributed toward firms that align their capabilities with the most valuable application requirements, while undifferentiated offerings face increasing pressure from both incumbents and targeted newcomers.
Forward Outlook: Trends to Watch and Where the Opportunities Lie
Trend 1: Efficiency as a System Property, Not Just a Motor Specification
Over the next three to five years, PMSM value will increasingly be defined by system-level efficiency across real operating profiles rather than peak-rated performance alone. Buyers in industrial and mobility applications will continue to prioritize motors that maintain strong efficiency at partial loads, respond quickly to control inputs, and integrate cleanly with power electronics and automation software. This trend creates opportunities for suppliers that can offer configurable performance, application-tuned control strategies, and documentation that supports compliance and lifecycle planning. It also raises the importance of validation under representative conditions, because efficiency claims that look strong on paper but underperform in the field will erode trust and purchasing preference.
Trend 2: Material Strategy Becomes a Competitive Capability
The rare earth dependency embedded in many PMSM designs will keep material strategy in the foreground. Companies that can reduce magnet intensity without sacrificing critical performance attributes, manage supply relationships intelligently, and explore recovery or substitution pathways where technically and economically feasible will gain resilience. This is not solely a cost issue; it is also a risk management and continuity issue. In periods of pricing volatility or policy change, the ability to maintain consistent output and margin can distinguish winners from laggards. Opportunities here include design optimization that preserves torque and efficiency with smarter magnet placement, improved recycling loops, and procurement models that reduce exposure to single-source bottlenecks.
Trend 3: Application-Specific Solutions Gain Premium Positioning
As the market matures, the most attractive margins are likely to shift toward applications where motors must meet specialized requirements. Hygiene-sensitive industrial environments, high-precision motion control, demanding transportation duty cycles, and compact mobility architectures are all examples where tailored engineering can command premium positioning. The commercial launch of servo systems designed for hygienic environments and continued activity in mobility technology exhibitions point to this direction. Suppliers that invest in understanding the operating context, regulatory constraints, and lifecycle needs of specific segments can build defensible niches, while those that rely on broad, undifferentiated portfolios may find themselves competing primarily on price in more commoditized parts of the market.
Portable Permanent Magnet Pump Market
Risks and Uncertainties to Monitor
Several uncertainties could shape the trajectory of the market. Input availability and pricing for rare earth materials remain volatile, and any disruption can affect cost structures and time-to-market for new designs. Regulatory timelines and efficiency standards may accelerate adoption in some regions while creating compliance complexity in others, especially where validation requirements differ across jurisdictions. Competitive intensity may increase as incumbents deepen integration capabilities and new entrants target specific niches, which could pressure margins in segments that fail to differentiate. Finally, demand growth in electric vehicles and industrial automation is subject to broader macroeconomic conditions, investment cycles, and the pace of electrification adoption in different geographies. Executives should treat these variables as integral to planning rather than peripheral risks, because they affect sourcing, product roadmaps, and the timing of capacity decisions.
Actionable Implications for Decision-Makers
For Manufacturers and Product Leaders
Align engineering roadmaps with system-level value rather than motor-only specifications. Prioritize designs that perform well across variable duty cycles, integrate readily with control and power electronics, and offer flexibility for application-specific customization. Strengthen material strategy by evaluating magnet intensity, sourcing diversification, and recovery pathways as core design parameters. Where possible, build modular architectures that allow performance to be tuned through control and packaging instead of relying solely on changes in magnet content. This approach can improve resilience while preserving the ability to serve both standardized and specialized segments.
For Investors and Capital Allocators
Focus on companies that demonstrate a credible path to combining efficiency, integration, and material resilience. Scale matters, but in this market it is most valuable when paired with application expertise and the ability to deliver total system performance. Differentiated niches in hygiene-sensitive environments, precision motion, mobility packaging constraints, and other high-specification applications can offer stronger margin potential than undifferentiated volume plays. Pay attention to how suppliers manage rare earth exposure and whether they have clear strategies for continuity, cost control, and product evolution. The winners are likely to be those that can convert technical capability into embedded, long-lived deployments.
For Procurement and Operations Leaders
Shift evaluation criteria toward total cost of ownership, integration effort, and lifecycle reliability. A lower upfront price can be offset by higher integration cost, poorer partial-load efficiency, or greater service complexity. Where critical applications are concerned, prioritize suppliers that can provide consistent validation, predictable service support, and clear documentation of performance under representative conditions. Diversify sourcing where feasible to reduce exposure to single-point material or manufacturing risks, and consider long-term collaboration with suppliers that demonstrate a strong plan for managing magnet-related volatility. Procurement decisions made with system value in mind tend to reduce downstream risk and improve operational predictability.
The strategic picture for the PMSM market is one of durable growth shaped by efficiency mandates, material constraints, and application diversification. The companies that will capture the most value are those that treat the motor as part of a broader system, build resilience into material and supply decisions, and tailor performance to the real operating conditions their customers face. For decision-makers looking to move from high-level trends to segment-level detail, the full research report provides a deeper breakdown of subsegments, regional demand patterns, competitive positioning, and scenario-based implications that can inform capacity, sourcing, and portfolio choices.
For detailed analysis of this topic, please visit the official page: Permanent Magnet Synchronous Motor (PMSM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Image Editing Software Market 2026: Beyond the 6.98% CAGR Growth Story
By pmarketresearch, 2026-09-21
The Image Editing Software Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The image editing software market has evolved from a niche desktop utility into a core component of digital content infrastructure, with global revenue reaching USD 206.85 million in 2025 and projected to expand to USD 335.5 million by 2032. The sector is on a steady growth trajectory, underpinned by a compound annual growth rate of 6.98 percent across the 2026-2032 forecast period, reflecting sustained demand for visual asset creation, modification, and optimization across professional and consumer segments. Historical momentum from 2020 through 2025 has been characterized by consistent expansion, with the market moving past the USD 145 million mark at the start of the cycle and steadily climbing as digital content workflows became deeply embedded in marketing, media, e-commerce, and individual creator economies.
Despite the favorable trajectory, the industry is confronting a set of structural challenges that are reshaping competitive dynamics and forcing players to rethink value delivery. First, the rapid integration of generative artificial intelligence is compressing traditional differentiation. Tools that once competed on feature depth, precision, and workflow specialization are now being benchmarked against AI-assisted editing capabilities that lower the skill threshold and accelerate output velocity. This shift is not merely a feature arms race; it is redefining what customers consider essential versus optional, and it is altering willingness to pay across segments.
Second, the subscription and licensing model continues to mature, creating both revenue stability and friction. Continuous access, cloud synchronization, and frequent update cycles have become table stakes for professional and mid-market users, yet pricing sensitivity remains acute in price-conscious regions and among solo creators. The balance between recurring monetization and perceived value is increasingly delicate, particularly as alternative licensing approaches and one-time purchase models regain relevance in certain niches.
Third, the market is navigating an open-source versus commercial software tension that is more nuanced than a simple price competition. Free and community-driven alternatives have improved markedly in stability, interface design, and compatibility, narrowing the functional gap for a broad range of editing tasks. This progression is not erasing commercial demand, but it is raising the bar for what paid solutions must deliver in terms of speed, integration, and advanced creative control.
For executives and investors, these challenges are not purely headwinds. They are signals of where value is migrating: toward workflow efficiency, intelligent automation, ecosystem lock-in, and specialized high-precision tools. Companies that treat these pressures as isolated product issues risk missing the broader reallocation of buyer expectations and spending patterns.
Key Drivers Reshaping the Market
Several interlocking forces are propelling the market forward, and their combined effect is more consequential than any single trend. Understanding how these drivers interact is essential for anticipating where growth will concentrate and which bets will pay off.
Technology Innovation and AI-Enabled Workflows
Generative and assistive AI has moved from experimental novelty to foundational capability in image editing. Modern tools now embed functions such as intelligent object removal, content-aware fills, style transfer, automated retouching, and template-driven composition directly into the editing interface. This reduces the time required to produce polished visual assets and widens the addressable user base by lowering technical barriers. The commercial implication is significant: software providers that can fuse AI features with predictable, repeatable workflows are gaining traction with both professional users seeking efficiency and casual users seeking quality without steep learning curves. The trajectory is not simply about adding more AI features; it is about orchestrating them into coherent, reliable editing experiences that fit into broader content pipelines.
Video Editing Software Market
Policy and Regulatory Environment
As image editing tools become more capable and more embedded in commercial content creation, questions around authenticity, provenance, and responsible use are gaining prominence. Regulatory attention to synthetic media, copyright safeguards, and disclosure norms is intensifying in several markets, indirectly influencing product roadmaps and go-to-market strategies. Software vendors are increasingly expected to provide controls for tracking edits, managing asset rights, and ensuring compliance with platform and jurisdictional requirements. This environment favors providers that can offer not just editing power but also governance-friendly features, auditability, and clear usage policies. In practical terms, trust and transparency are becoming part of the product value proposition rather than afterthoughts.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is expanding beyond traditional photography and graphic design into a broader set of visual content needs. Enterprises require rapid production of marketing assets, social media imagery, product visuals, and localized creative variations, while individual creators and small businesses seek affordable tools that can deliver professional-looking results without complex setups. This dual demand is pushing the market toward flexible delivery models. Users increasingly expect cross-device access, collaborative workflows, and the ability to move seamlessly between desktop, browser, and mobile contexts. The result is a widening emphasis on accessibility, speed, and integration, with buyers prioritizing tools that reduce context switching and align with existing content stacks.
PW Consulting Information & Electronics Research Center
Cost Structure and Supply-Side Dynamics
The economics of software delivery continue to shift. Development and maintenance costs remain significant, but distribution and update mechanisms have become more efficient, especially for cloud-connected and web-based solutions. At the same time, the broader software publishing ecosystem in adjacent areas such as design, editing, and rendering has experienced notable growth, reflecting the expanding value of digital creative tools and the talent required to build and support them. Cost pressures are not only about development expense; they also relate to the investment needed to sustain competitive AI capabilities, compatibility across formats, and frequent interface and performance improvements. Providers that can manage these costs while preserving feature quality and reliability are better positioned to defend margins and fund ongoing innovation.
Competitive Dynamics and Strategic Positioning
The market is defined by a mix of established commercial vendors, focused niche players, and increasingly capable open-source alternatives. Competitive advantage is no longer determined solely by the breadth of editing tools; it now hinges on workflow design, integration, reliability, and the ability to align product strategy with clear user segments.
Adobe Systems Inc. remains a central force in the space, anchored by a portfolio that spans professional editing, consumer-facing tools, and increasingly sophisticated generative AI capabilities. Its strategic strength lies in combining a familiar, deeply adopted editing environment with a continuous delivery model that keeps tools current and connected to broader creative ecosystems. The company’s recent emphasis on enhanced generative features, templates, and simplified workflows illustrates a deliberate push to serve both advanced users and those seeking quicker, guided editing paths. This dual-track approach helps sustain relevance across professional and mainstream audiences while reinforcing recurring engagement.
Corel Corporation maintains a differentiated position through vector and photo editing tools that appeal to users prioritizing design flexibility and standalone editing workflows. Its value proposition is rooted in practical creative control and a product family that serves both commercial and individual users. Serif (Europe) Ltd. has reinforced its relevance by offering standalone professional tools with a strong focus on performance and direct purchase appeal, and its decision to make a combined photo, vector, and layout application freely available broadened accessibility while preserving a professional-grade feature set. This move highlights a strategic willingness to reshape reach and adoption patterns without abandoning the core professional audience.
Other players illustrate how specialization and targeted positioning can sustain relevance. ACD Systems International Inc. and ON1, Inc. continue to serve professional and enthusiast segments with tools oriented toward efficient photo editing and batch processing. CyberLink Corporation bridges photo editing with broader multimedia capabilities, while Skylum Software emphasizes AI-assisted photo enhancement. ZONER, Inc. and Capture One ApS represent more focused offerings that cater to specific workflow needs, including RAW processing and studio-oriented editing. GNU Image Manipulation Program Team maintains a globally recognized open-source alternative, and its recent version releases have underscored steady improvements in stability, interface design, and usability, reinforcing the competitive pressure on commercial products to justify premium positioning through tangible workflow and performance advantages.
The broader competitive landscape is evolving along several axes. Consolidation pressure exists where integrated ecosystems and cross-product synergies can reduce churn and increase switching costs. At the same time, fragmentation persists as specialized tools continue to thrive for high-precision, domain-specific use cases. New entrants and open-source projects are not merely mimicking legacy tools; they are increasingly offering modern interfaces, better compatibility, and lighter-touch installation experiences that appeal to users who value simplicity and transparency. The net effect is a market where incumbents must defend their positions through continuous innovation and ecosystem strength, while challengers can win by serving underserved workflows or by offering a more streamlined, cost-effective experience.
For decision makers, the key takeaway is that market leadership is increasingly a function of how well a vendor balances breadth, depth, ease of use, and trust. Product features alone are no longer enough; the surrounding experience—updates, compatibility, integration, and clarity of licensing—plays a decisive role in adoption and retention.
Forward-Looking Trends and Commercial Implications
Looking ahead to the next three to five years, the market is likely to be shaped by a small number of high-impact trends that will influence product strategy, pricing, and partnership decisions.
One major trend is the deepening integration of AI as a collaborative layer rather than a standalone feature. Editing tools will increasingly act as co-pilots that suggest edits, automate repetitive tasks, and adapt to user intent, while still leaving creative control in human hands. The commercial opportunity here lies in building workflows that are both faster and more predictable, especially for teams that need to produce large volumes of visual assets with consistent quality. Companies that can demonstrate measurable time savings, reduced rework, and reliable output will have a compelling case across professional and enterprise segments.
A second trend is the continued expansion of cross-platform and browser-based editing as users expect fluid movement between devices and environments. This is not just about convenience; it is about fitting image editing into broader content operations where assets are created, reviewed, and deployed across multiple systems. The opportunity is for providers that can deliver consistent performance, seamless syncing, and integration with existing digital asset management and publishing tools. usability and interoperability will become stronger differentiators, especially for buyers evaluating total workflow value rather than isolated editing features.
A third trend is the growing importance of authenticity, rights management, and responsible use as edited and AI-assisted imagery becomes more prevalent in commercial and public-facing content. Software that offers clearer audit trails, asset provenance support, and configurable controls will be better positioned in environments where compliance and brand safety matter. This creates an opening for providers that can align product capabilities with governance needs, particularly in enterprise and regulated use cases.
These trends carry risk as well. Overreliance on AI features without corresponding attention to accuracy, consistency, and user control can erode trust. Pricing and licensing models that fail to align with perceived value may accelerate churn or push users toward alternatives. And as open-source and free tools continue to improve, commercial vendors will need to articulate a clearer reason for premium investment, whether through speed, precision, ecosystem integration, or specialized capabilities. The Uncertain factor is not whether these dynamics will intensify, but how quickly different segments will adopt new expectations and how sensitive they will be to price and complexity.
Actionable Guidance for Decision Makers
The most effective responses to these shifts depend on the role a stakeholder plays in the market. The following recommendations focus on practical priorities rather than generic advice.
- For software vendors and product leaders, prioritize workflow coherence over feature volume. AI and automation should be embedded in ways that make everyday editing faster, more reliable, and easier to learn, while preserving advanced control for users who need it. Investment should also extend to compatibility, performance, and update reliability, because these factors increasingly determine retention and referral in crowded markets.
- For investors and strategic buyers, focus on differentiation that is defensible in the face of AI democratization and open-source improvement. The most resilient opportunities are likely in segments where precision, speed, integration, or governance create meaningful switching costs. Watch for companies that can combine strong user experience with ecosystem reach and a licensing model that aligns with customer value, as these are the characteristics most likely to support durable growth.
- For procurement teams and enterprise buyers, evaluate tools against total workflow impact rather than feature checklists. Consider how well a solution integrates with existing content processes, how quickly teams can become productive, and whether licensing and update policies create predictable operating costs. Weigh the trade-offs between comprehensive commercial platforms and specialized or lower-cost alternatives based on actual usage patterns, quality requirements, and internal skill levels.
The image editing software market is large enough and dynamic enough that generic assumptions can lead to missed opportunities. Detailed segmentation data, regional demand patterns, application-level revenue splits, and company-level positioning can materially sharpen strategy, whether the goal is product planning, market entry, partnership evaluation, or investment selection. Readers seeking a more granular view of market size by segment, competitive mapping, and forward scenarios can access the full research report for deeper detail and tailored interpretation.
Education Software Market
For detailed analysis of this topic, please visit the official page: Image Editing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Radiation Shielding Textile Market: Why 5.1% CAGR and Asia Pacific’s 32% Share Redefine Growth
By pmarketresearch, 2026-09-21
Radiation Shielding Textile Market: Strategic Trends & Commercial Opportunities (2026–2032)
Market Landscape & Core Challenges
The global market for radiation shielding textiles is navigating a phased expansion, with revenue scaling from approximately $70 million in 2020 toward a $130 million horizon by 2032. This trajectory reflects a compound annual growth rate of roughly 5.1% across the 2026–2032 forecasting window, signaling steady rather than explosive momentum. The market’s maturation is less about raw volume growth and more about structural refinement: demand is shifting from generic protective coveralls toward engineered, application-specific textiles that balance shielding performance, ergonomics, and compliance readiness.
Worldwide Anti Radiation Clothing Market
Several structural challenges complicate this progression. First, the tension between shielding effectiveness and wearable practicality remains unresolved for many end-use scenarios. High-attenuation materials often carry weight, stiffness, or thermal discomfort penalties that limit adoption in prolonged-contact applications, particularly in healthcare and specialized industrial settings. Second, regulatory complexity is accelerating material substitution cycles. Restrictions on certain chemical substances in textiles, combined with tightening requirements for personal protective equipment certification, are forcing manufacturers to validate not only shielding performance but also chemical safety and durability under repeated use. Third, input cost volatility is reshaping margin architectures. Fluctuations in base metals and specialty concentrates feed directly into the cost structures of metallized and blended shielding fabrics, while trade policy shifts have introduced new friction into cross-border sourcing and finished-goods distribution.
For decision-makers, the immediate implication is clear: the market is moving from a commodity-adjacent phase toward a performance-differentiated phase. Companies that treat shielding textiles as a spec-driven engineering problem rather than a volume play will capture disproportionate value as procurement teams standardize on verified durability, certification status, and lifecycle cost.
Key Drivers Reshaping the Market
Materials Innovation and Functional Differentiation
Material architecture is the most visible lever of competitive differentiation. Metal fiber blended fabrics continue to anchor a significant share of the market because they offer an established balance of conductivity, washability, and manufacturability. Metallised fabrics, particularly silver-plated and metal-coated variants, remain central for electromagnetic shielding in technical textiles and electromagnetic compatibility applications. At the same time, lead-free and lightweight shielding approaches are gaining strategic relevance, especially where ionizing radiation protection intersects with ergonomics and repeated occupational exposure. The commercial appeal of these innovations is not merely technical; it is operational. Textiles that maintain shielding integrity through repeated flexing, laundering, and environmental exposure reduce replacement frequency and simplify compliance documentation, which matters increasingly in regulated procurement environments.
Regulatory and Certification Pressures as a Market Filter
Regulation is functioning as both a constraint and a competitive filter. In the European market, restrictions on certain substances in clothing, textiles, and footwear have raised the bar for chemical compliance in shielded products, while broader chemical action plans are extending scrutiny toward technical textiles and associated surface treatments. Parallel certification requirements for personal protective equipment are pushing manufacturers to substantiate claims with reproducibility data rather than laboratory benchmarks alone. This dynamic favors firms that can assemble a credible documentation package—material composition, durability evidence, and application-specific validation—because procurement and risk functions increasingly treat certification as a gatekeeping criterion rather than a back-office detail.
Demand-Side Shifts in Occupational and Medical Settings
Demand patterns are being reshaped by how protective textiles are used day to day. In medical environments, there is growing emphasis on localized shielding solutions that reduce dose exposure without imposing the burden of full-body garments for every procedure. This has encouraged development of targeted protection devices and modular textile systems that can be deployed where exposure risk is concentrated. Beyond healthcare, industrial users continue to seek shielding materials that integrate into existing workflows without disrupting dexterity, ventilation, or maintenance routines. At the consumer-adjacent end, interest in maternity and general anti-radiation apparel has expanded awareness of shielding textiles, though commercial scale in that segment depends heavily on perceived benefit, affordability, and repeat-purchase dynamics. Across these settings, the common thread is a preference for solutions that marry protection with usability.
Supply Chain Economics and Input Cost Exposure
Cost structure is becoming a strategic variable rather than a background condition. Stabilized pricing across lead markets has provided some predictability for traditional shielding inputs, but that stability does not extend uniformly to all materials. Sharp increases in tungsten concentrate pricing illustrate how quickly input economics can shift for alternative high-density shielding paths, affecting the feasibility of specific formulations and pushing teams to reassess blending ratios, sourcing diversification, and inventory planning. At the same time, tariff escalations on textiles and related imports in major markets have raised the effective cost of cross-border supply chains, prompting manufacturers to reconsider where value-added processing occurs and how finished goods are routed. The result is a market in which resilient sourcing strategies and regional production flexibility are becoming part of the competitive advantage set.
Competitive Landscape & Leading Strategies
The competitive field is moderately concentrated, with the largest players collectively accounting for a meaningful but not suffocating share of revenue. That structure leaves room for specialized innovators while rewarding established manufacturers that can scale certification, consistency, and application engineering. A few strategic positions stand out.
- Swiss Shield AG has built its position around high-tech yarns and cotton/polyester fabric systems designed for high-frequency electromagnetic radiation shielding, with product lines spanning garments, home textiles, and industrial applications. Its strategic emphasis appears to be on embedding shielding capability into familiar textile substrates, which can simplify integration for downstream manufacturers and reduce adoption friction.
- Shieldex focuses on metallized silver-plated fabrics and conductive textiles available in woven, knitted, and nonwoven forms, targeting technical textiles and electromagnetic compatibility applications. This breadth of fabric construction supports customization for different performance and handling requirements, which is valuable in application-driven procurement.
- Radiation Shield Technologies (RST) occupies a distinctive niche as the sole producer of a lead-free, lightweight radiation protection fabric designed for ionizing radiation shielding in full-body suits, blankets, vests, and tents. Its differentiation rests on material uniqueness and the ability to offer an alternative to conventional heavy shielding approaches, which can be compelling where weight, comfort, and portability influence adoption.
- Texray AB has positioned itself around textile-based radiation protection devices for medical professionals, supported by regulatory certifications and recent durability validation. Independent scientific study results have highlighted resistance to high numbers of flex cycles and substantial additional dose reduction in medical applications, reinforcing a value proposition centered on long-service performance rather than single-use protection logic.
- Joyncleon addresses lightweight maternity and general anti-radiation apparel using high-performance fabrics, illustrating how shielding textiles can extend into consumer-facing apparel categories where comfort, style, and accessibility shape purchase decisions.
- Metal Textiles contributes metal-coated and metallized fabric capabilities for radiation and electromagnetic shielding, reinforcing the broader ecosystem of metallization-based solutions that serve industrial and technical use cases.
The strategic throughline across these players is differentiation through either material architecture, application specialization, or validation depth. Companies that compete mainly on specification sheets are vulnerable to those that can demonstrate durable field performance and maintain compliance readiness across jurisdictions. One notable recent development underscores this direction: Texray AB’s 2025 certification-related progress, including study-confirmed durability against extensive flex cycling and up to 97% additional dose reduction in medical applications, signals how performance evidence can strengthen positioning in regulated, high-stakes settings.
Looking ahead, the competitive landscape is likely to evolve along two tracks. On one hand, consolidation may accelerate among manufacturers that can combine material expertise with compliance, distribution, and application support. On the other, new entrants may emerge around targeted niches—localized medical shielding, lightweight alternatives for specific occupational tasks, or specialized electromagnetic shielding for technical textiles—where incumbents are less optimized. The dividing line will be whether a company can offer a repeatable, verifiable solution that fits into a procurement process, not merely a promising material concept.
Outlook & Emerging Opportunities, 2026–2032
The next several years are likely to be defined by three interlocking trends.
1. From shielding presence to shielding performance. Demand will increasingly center on textiles that prove durable under real use conditions, not just on initial attenuation numbers. Products that can demonstrate repeated flex endurance, wash stability, and consistent performance after deployment will command stronger preference in medical, industrial, and military-adjacent settings. The commercial opportunity lies in building product narratives around lifecycle value: fewer replacements, more predictable protection, and simpler audit trails for compliance teams.
2. Material substitution and formulation arbitrage. As regulatory expectations tighten and input costs move unevenly across metals and concentrates, manufacturers that can adjust formulations without sacrificing core performance will gain flexibility. This creates opportunities for blended systems, alternative metal choices, and lead-free options where they can meet shielding and usability thresholds. The flip side is supply-chain risk: pricing swings in key inputs can quickly alter cost competitiveness, so scenario planning and multi-source sourcing will matter more than in a stable-commodity environment.
PW Consulting Health Care Research Center
3. Application-led segmentation rather than blanket categories. Buyers are likely to adopt more granular purchasing logic, selecting textiles by end-use rather than by broad category. Medical localized protection, industrial electromagnetic compatibility, and lightweight occupational shielding each present different engineering and certification requirements. Companies that organize product lines around these use cases—and support them with relevant documentation and integration guidance—are better positioned to capture share in higher-value segments.
Potential risks and uncertainties should be factored into planning. Certification pathways can shift, especially where chemical restrictions and PPE requirements evolve. Trade policy volatility can alter landed costs and redirect sourcing strategies, particularly for manufacturers dependent on cross-border material flows or finished-goods distribution. Durability claims, if not substantiated consistently, can become a liability in regulated procurement. Finally, where consumer-facing shielding products rely heavily on perceived rather than measured benefit, adoption may be sensitive to competitive alternatives and price expectations.
Worldwide Fibers and Electromagnetic Shielding Market
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product development with verifiable durability and compliance readiness. Engineering effort should be directed toward formulations and fabric constructions that hold up under repeated flex, laundering, and operational stress, because those attributes increasingly influence purchasing decisions in regulated settings. It is equally important to prepare documentation that supports certification and procurement review, since the ability to demonstrate reproducible performance can be as valuable as the raw shielding specification. Diversification of input sourcing and regional manufacturing flexibility will help manage cost and trade-related disruptions.
For investors, attention should focus on companies with defensible differentiation in either material architecture, application specialization, or validation depth. Business models that depend on undifferentiated volume in a moderately concentrated market face more competition and thinner margins, while those tied to certified, application-specific solutions have stronger moats. Due diligence should assess input cost exposure, regulatory preparedness, and the credibility of durability claims, because these variables will shape profitability as the market moves from early expansion toward more performance-driven competition.
For procurement and end-user organizations, the practical move is to define shielding requirements by application and to evaluate suppliers against a broader scorecard that includes durability evidence, certification status, chemical compliance, and total cost of ownership. Selecting textiles on the basis of initial attenuation alone can leave exposure to premature degradation, replacement costs, and compliance gaps. Establishing internal acceptance criteria for field performance and documentation will improve consistency across purchases and reduce downstream risk.
As the radiation shielding textile market continues to refine its value proposition around performance, compliance, and application fit, the companies and buyers that act on those priorities early are best positioned to capture the upside of the forecast period. For teams that need a deeper, segment-level view of sizing, competitive positioning, regional dynamics, and material-cost exposure to guide planning, the full PW Consulting market report provides the detailed data foundation and tailored strategic options to support those decisions.
For detailed analysis of this topic, please visit the official page: Radiation Shielding Textile Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laminated Tubes Market Beyond the 6.5% CAGR: Key Drivers Shaping 2032 Growth
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Laminated Tubes Market
The global laminated tubes market has demonstrated steady, compounding growth over the past five years, with revenue expanding from $1,345.0 million in 2020 to $1,810.0 million in 2025. Forward projections indicate this trajectory will continue through the forecast period of 2026-2032, reaching $2,800.0 million by the end of the decade. The implied compound annual growth rate of 6.5% reflects more than baseline demographic expansion; it signals a structural transition where laminated tubes are increasingly evaluated not merely as dispensing packages, but as functional components within product performance, regulatory compliance, and sustainability narratives.
Leadership teams across personal care, oral care, pharmaceuticals, and food and beverage sectors are navigating a landscape where packaging decisions directly influence formulation integrity, brand positioning, and supply chain risk exposure. The market's expansion is not uniform. It is concentrated around innovation cycles, regulatory inflection points, and geographic rebalancing that reward manufacturers and brand owners who align capacity investments with material science breakthroughs. Understanding where growth concentrates, what constraints will harden, and which competitive moves are gaining traction is essential for strategic planning in the near to medium term.
Market Landscape and Emerging Pressure Points
The laminated tubes market operates with moderate concentration, where the top three players capture approximately 26.8% of revenue and the top five reach about 32.6%. This structure indicates a competitive environment with a stable core of established manufacturers and sufficient space for regional specialists and technology-driven entrants to differentiate. Growth has been consistent year over year, with 2024 revenue reaching $1,701.4 million and 2025 closing at $1,810.0 million. The momentum continues into 2026 at $1,955.44 million, reflecting sustained demand across core application categories and incremental gains from higher-value barrier solutions.
Several structural tensions are defining the current phase of market development. First, the cost architecture of laminated tubes remains inherently higher than conventional single-material alternatives. Multilayer construction, specialty adhesives, and barrier films such as aluminum foil or engineered resins create a production cost premium typically 15-20% above standard polyethylene tubes. When resin prices experienced 30-40% spikes between 2021 and 2023 due to supply chain bottlenecks, the margin pressure on laminated tube manufacturers intensified, forcing a sharper focus on value engineering, procurement discipline, and pricing strategies that justify premium positioning through performance and compliance.
Second, regulatory momentum is reshaping design assumptions. Packaging legislation in major markets is moving from voluntary guidelines toward enforceable standards that link material composition, recyclability, and recycled content to market access. This shift places laminated tube manufacturers and brand owners under pressure to reconcile barrier performance with end-of-life compatibility, particularly in regions where existing recycling infrastructure is calibrated for simpler polymer streams.
Third, the market is encountering a capability gap between high-volume standard production and the growing demand for customized, high-resolution printed, and functionally specialized tubes. As brands seek packaging that supports premium positioning, tamper evidence, anti-counterfeiting, and differentiated dispensing experiences, manufacturers that can deliver consistent quality at scale while accommodating shorter runs and tailored specifications are gaining strategic relevance.
Drivers Reshaping Market Trajectory
Material Innovation and Barrier Performance
Technology advancement remains the most direct engine of market growth. Laminated tube value is increasingly derived from the ability to combine barrier protection, lightweighting, and recyclability in a single structure. High-barrier aluminum-based laminate tubes continue to command significant share because they protect oxygen-sensitive and moisture-sensitive formulations, but innovation is expanding the functional envelope of plastic barrier solutions as well. Recent product launches demonstrate that barrier performance is no longer treated as a fixed attribute; it is being re-engineered for compatibility with recycling streams while retaining the protective characteristics demanded by oral care, cosmetics, and pharmaceutical applications.
Examples include the introduction of recyclable high-barrier laminate tubes designed for oral care and cosmetics, the debut of mono-material recyclable barrier tubes with sensory and aesthetic differentiation, and the integration of anti-counterfeiting features directly into multilayer tube structures through holographic films. These developments matter commercially because they allow brand owners to defend formulation quality and consumer trust without defaulting to conventional aluminum structures that may face recyclability friction in certain jurisdictions. For manufacturers, the ability to offer differentiated barrier solutions is increasingly a revenue driver rather than a compliance checkbox.
Regulatory and Policy Dynamics
Policy environments are accelerating design transitions. In Europe, packaging regulation is moving toward enforceable recycled content thresholds and harmonized recyclability grading. Flexible packaging is subject to mandates requiring at least 35% recycled plastic content by 2030, which compels laminated tube producers and their customers to adapt structures for recyclability in existing polyethylene streams. Enforcement of single-use plastics requirements since mid-2024 has reinforced expectations around tethered closures and mono-material orientation, further accelerating the shift away from complex multi-layer laminates where recycling compatibility is limited.
Laminate Tube Packaging Market
By 2026, technical implementing acts are expected to impose harmonized recyclability grades, creating a more predictable but stricter evaluation framework. Manufacturers that rely on laminated films incompatible with existing recycling systems face increased redesign exposure, while those with mono-material or certified recyclable platforms gain a compliance advantage. This regulatory trajectory is not solely a European phenomenon; it influences global supply chains as multinational brand owners standardize packaging architectures across regions to reduce complexity and risk. The strategic implication is clear: regulatory readiness is becoming a market entry and retention factor, especially in premium personal care and pharmaceutical segments.
Demand-Side Evolution in Consumer and B2B Behavior
Consumer and enterprise demand is pulling laminated tube markets in two complementary directions. On the consumer side, expectations around sustainability, authenticity, and premium experience are influencing purchasing decisions in oral care and cosmetics. Tubes are no longer invisible carriers; they communicate brand values through finish, dispensing feel, and perceived environmental responsibility. On the B2B side, pharmaceutical and personal care manufacturers are seeking packaging that supports product integrity, regulatory documentation, and supply reliability. High-barrier laminated tubes serve these needs by protecting active ingredients, enabling stable shelf life, and providing a platform for controlled dispensing.
This dual demand pattern is expanding the commercial relevance of specialized tube formats. Oral care remains a particularly strong application category, benefiting from high usage frequency, brand loyalty, and format familiarity. Cosmetics and personal care continue to drive demand for customizable prints, premium tactile qualities, and functional closures. Pharmaceuticals and healthcare-related applications contribute steady demand where barrier protection and compliance documentation are critical. The underlying trend is that laminated tubes are being selected for a wider set of performance criteria, which raises the stakes for manufacturers that cannot deliver consistent quality, traceability, and specialized features.
Supply Chain Economics and Cost Structure Realignment
Cost dynamics are a persistent determinant of competitive positioning. Laminated tube economics are shaped by resin pricing, aluminum foil costs, adhesives, and multilayer processing complexity. The resin price volatility experienced during 2021-2023 illustrated how quickly input cost swings can compress margins, particularly for producers with limited ability to pass through costs or re-engineer structures for efficiency. As markets stabilize, the strategic focus is shifting toward cost resilience rather than short-term price hedging alone.
Capacity expansion is one response. Investments in automated production lines in key manufacturing hubs are increasing throughput and reducing per-unit labor intensity, which helps offset structural cost premiums. At the same time, manufacturers are pursuing lightweighting, material optimization, and hybrid technologies that preserve barrier performance while reducing overall material usage. These moves are not only about margin protection; they are increasingly tied to sustainability messaging and recyclability performance, creating a link between cost efficiency and market acceptance.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a mix of global manufacturers with broad application coverage and regional specialists with strong customization or cost advantages. A handful of scaled players set the pace on innovation and capacity, while a wider field competes through regional service, printing quality, pharmaceutical compliance capabilities, and application-specific expertise. Strategic differentiation is increasingly tied to three dimensions: recyclable barrier technology, capacity scale with automation, and the ability to support premium branding through high-resolution graphics and custom formats.
Several leaders illustrate how these dimensions are being pursued. Essel Propack Limited has built a broad manufacturing footprint with facilities across multiple countries and a focus on high-volume aluminum and plastic barrier tubes spanning oral care, cosmetics, food, and pharmaceutical products. Its recent investment of approximately $35 million in automated production lines reflects a strategy centered on capacity growth and operational efficiency in a major manufacturing region. Albea S.A. has positioned itself around recyclable tube platforms with advanced barrier technologies, including high-barrier recyclable laminate solutions intended for oral care and cosmetics. This emphasis on recyclability and barrier performance aligns with the regulatory and consumer pressures shaping European and global markets.
Amcor Limited has emphasized ultra-lightweight and post-consumer resin-based laminated tubes for personal care and pharmaceutical use, with a stronger narrative around circular packaging models and targeted market launches in Europe. Huhtamaki Oyj has moved into paper-based bio-barrier laminated tubes for personal care and cosmetics, supported by recyclability certifications, signaling a bet on alternative material pathways that reduce dependence on conventional plastics and aluminum in specific applications. Berry Global Group, Inc. has invested in patented hybrid technology designed to support high-resolution, premium graphic laminated tubes for cosmetic and pharmaceutical applications, reinforcing a premiumization and visual differentiation angle. Hoffmann Neopac AG has focused on recyclable mono-material barrier tubes with pharmaceutical-grade manufacturing standards, expanding capacity in North America and introducing sensory-oriented recyclable barrier options for cosmetics.
Beyond these global players, regional manufacturers play an important role in the market's architecture. Asian producers frequently serve cosmetics, skincare, and personal care demand with custom aluminum and plastic barrier tubes and strong printing capabilities, while North American and European specialists often compete on pharmaceutical compliance, documentation support, and premium healthcare-oriented formats. This diversity means that competitive advantage is not simply a function of scale. It is increasingly determined by the ability to match the right material platform, regulatory posture, and service model to the application.
The market structure suggests continued differentiation rather than rapid consolidation. The top firms maintain a meaningful but not dominant share, enabling niche leaders to thrive where they offer clear functional or compliance advantages. At the same time, the pace of technology introduction and regulatory change is raising the bar for new entrants and smaller players. Manufacturers without recyclable platforms, reliable barrier performance, or scaling automation may find it harder to compete in premium segments, while those able to deliver specialized print quality, anti-counterfeiting features, or pharmaceutical documentation may capture value in higher-margin niches.
Forward Outlook: Trends Shaping the Next Three to Five Years
The next phase of laminated tube market development is likely to be shaped by the interaction of recyclability mandates, premiumization, and manufacturing efficiency. Three trends stand out.
Recyclable barrier architectures will become a baseline expectation in key markets. As harmonized recyclability grading and recycled content requirements take hold, the market will increasingly reward tube structures that balance protection with compatibility in existing recycling streams. This will intensify redesign activity for multi-layer laminates and create durable demand for mono-material and certified recyclable solutions. The commercial opportunity is not limited to compliance; recyclable barrier tubes can support brand narratives and procurement requirements that are becoming standard in multinational purchasing decisions.
Laminated Steel Market
Premium differentiation will expand through graphics, sensory design, and security features. High-resolution printing, hybrid graphic technologies, and integrated anti-counterfeiting features are moving from specialty projects to broader commercial relevance. Brands in cosmetics and oral care are using packaging to reinforce premium positioning and consumer trust, while pharmaceutical and personal care buyers are looking for solutions that reduce risk and support product authenticity. Manufacturers that can deliver these features consistently at scale will capture higher-value demand.
Capacity growth will concentrate where automation and material access align. Investments in automated lines and regional production expansion are likely to continue, particularly in markets that combine cost efficiency with strong application demand. This will improve throughput and cost resilience but will also raise the operational standard for competitiveness. Suppliers that remain dependent on labor-intensive processes or lack material and printing specialization may face margin compression and reduced access to premium programs.
These trends carry uncertainty. Regulatory timelines and enforcement intensity may vary by region, affecting how quickly recyclable structures become commercially mandatory. Resin and aluminum pricing can still disrupt margins if supply constraints re-emerge. In addition, alternative packaging formats and refill systems may influence demand patterns in certain categories, particularly where brand owners pursue circularity through reusable or reduced-packaging models. The net effect is that growth will persist, but the allocation of that growth will increasingly favor players who can integrate material science, regulatory readiness, and premium execution.
Strategic Actions for Decision Makers
For manufacturers and packaging suppliers: Prioritize recyclable barrier platforms and mono-material pathways that align with regulated markets and multinational buyer expectations. Invest in automation and line flexibility to reduce unit costs while accommodating custom formats, high-resolution graphics, and shorter runs. Strengthen capabilities in anti-counterfeiting, sensory differentiation, and documentation support for pharmaceutical and healthcare applications, where compliance and traceability command premium value.
PW Consulting
For investors evaluating exposure to laminated tube value chains: Focus on companies with credible recyclable technology roadmaps, diversified application coverage, and capacity expansion tied to automation rather than purely incremental volume. Monitor regulatory milestones that affect recyclability grading and recycled content thresholds, since these will influence which product architectures gain or lose market access. Assess regional manufacturing footprints for cost resilience, material access, and proximity to high-growth application demand.
For brand owners, procurement teams, and R&D leaders: Treat laminated tube selection as a strategic variable rather than a procurement commodity. Align packaging architecture with formulation sensitivity, shelf-life requirements, brand positioning, and regional compliance obligations. Engage suppliers that can demonstrate recyclable design compatibility, consistent barrier performance, and the ability to support premium graphics or security features where relevant. Build sourcing strategies that balance cost, compliance, and differentiation, recognizing that premium packaging value is increasingly tied to sustainability credibility and product protection.
Detailed segment-level data, regional demand patterns, and company-specific capability comparisons can materially sharpen these decisions. Access to comprehensive research and customized insights helps leadership teams validate assumptions, size opportunities more precisely, and anticipate regulatory or competitive shifts before they affect sourcing or investment choices. For organizations seeking a fuller picture of the laminated tubes market, deeper analysis and tailored recommendations are available through the complete research report.
For detailed analysis of this topic, please visit the official page: Laminated Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Zinc Sulfate Market: How the 6.8% CAGR and Asia Pacific Growth Redefine Strategy
By pmarketresearch, 2026-09-21
The Zinc Sulfate Market at a Crossroads: Strategic Trends and Commercial Opportunities
The global zinc sulfate market is entering a phase of structural expansion, driven by converging demand across agriculture, life sciences, and industrial applications. With revenues reaching approximately 1,780 million in 2025 and a projected compound annual growth rate of 6.8 percent through 2032, the sector is moving beyond cyclical commodity fluctuations into a period defined by geographic rebalancing, product specialization, and regulatory tightening. Asia Pacific now anchors the majority of volume, while Europe and North America maintain higher value-share positions tied to pharmaceutical-grade and food-safety specifications. The market is not uniformly expanding; growth is concentrating in segments where purity, traceability, and supply reliability command premium pricing. For executives and investors, the opportunity lies in understanding where value is shifting and which operational capabilities will separate winners from commoditized suppliers.
The market structure reflects moderate concentration, with the top three players capturing just over forty percent of revenue and the top five approaching fifty-three percent. This leaves meaningful room for regional specialists, contract manufacturers, and new entrants that can align product grades with regulatory pathways and end-user certification requirements. The balance between scale and specialization will define competitive outcomes over the next several years. Companies that treat zinc sulfate as a single commodity are increasingly exposed to margin compression, while those that segment by application, hydration state, and quality assurance are building defensible positions in higher-margin channels.
Market Landscape and Core Challenges
A Market Defined by Volume Growth and Specification Differentiation
The revenue trajectory from 2020 through 2025 shows steady expansion, with a notable acceleration in 2024 before stabilizing at a higher base in 2025. The forward curve suggests continued growth, but the path is uneven across hydration states and end-use channels. Monohydrate forms the largest share of revenue, reflecting its broad industrial and specialty use, while anhydrous and hydrated variants serve more application-specific roles. The agrochemical channel remains the largest demand pool, drawing on zinc sulfate as a micronutrient supplement and soil amendment, while pharmaceuticals, water treatment, and animal nutrition contribute smaller but strategically important revenue streams that often carry stricter quality and documentation requirements.
This mix matters because growth in one channel does not automatically translate into margin expansion. Agrochemical volume can be price-sensitive and logistics-driven, while pharmaceutical and food-adjacent applications reward consistency, certification, and testing capability. The market’s center of gravity is therefore shifting not only by geography but by the economic value attached to specification control. Suppliers that can reliably bridge bulk demand and high-purity demand are positioned to capture more of the value chain.
Key Challenges and Turning Points
Three structural challenges are reshaping strategic planning across the sector.
-
Raw material and energy cost volatility. Sulfuric acid is a core input for zinc sulfate production, and regional disruptions have periodically pushed input costs higher for sulfate-based trace minerals and related chemical lines. When feedstock costs rise faster than contractual pass-through mechanisms, producers face margin pressure unless they have secured long-term agreements, optimized process efficiency, or shifted toward higher-specification grades that better absorb cost increases. This dynamic is especially relevant for producers operating in regions exposed to Middle East supply instability and for manufacturers that rely on imported acid or upstream zinc intermediates.
-
Regulatory compliance as a barrier and a differentiator. Matched to evolving safety data sheet requirements, registration dossier maintenance, and food-safety database inclusion, compliance is no longer a back-office function. It is increasingly a commercial prerequisite. Producers serving export markets must navigate REACH-related documentation, quality-assurance databases, and testing protocols that differ by destination. A company’s ability to maintain current documentation and demonstrate traceability can determine whether it wins or loses regulated tenders. In practical terms, regulatory readiness is becoming a source of competitive advantage rather than a baseline cost.
-
Supply continuity and operational resilience. Force majeure events, plant maintenance, and logistics bottlenecks can interrupt supply faster than demand adjusts. Recent operational restarts at major European sites illustrate how quickly availability can be restored after disruptions, but they also underline the importance of contingency planning for customers that depend on steady grades and reliable delivery. For buyers, this creates a premium on dual sourcing, inventory strategy, and supplier transparency. For producers, it reinforces the need for robust maintenance planning, clear communication during outages, and alternative routing for key customers.
Together, these challenges push the market toward a more differentiated operating environment. The winners will be those who convert compliance, continuity, and cost discipline into trust-based customer relationships rather than treating them as isolated risk management tasks.
Core Drivers Shaping the Market
Technology and Process Innovation
Innovation in zinc sulfate production is less about radical chemistry and more about precision, efficiency, and grade control. Higher-purity monohydrate and heptahydrate offerings depend on tighter processing controls, consistent crystallization, and reliable analytical verification. In a market where end-users increasingly compare suppliers on documented purity and batch-to-batch consistency, testing capability becomes a strategic asset. Laboratories that achieve recognized accreditation for chemical testing strengthen their ability to support pharmaceutical, food-safety, and high-purity industrial applications. This is not simply a quality function; it is a market-access enabler.
Process improvements that reduce variability, lower energy intensity, and improve yield also matter because they directly affect cost structure and the ability to compete in regulated segments. Where producers can demonstrate both consistent output and credible test documentation, they can defend pricing in channels where specification risk is costly to the buyer. In effect, technology is becoming a commercial signal as much as an operational one.
Policy and Regulatory Environment
Regulatory dynamics are tightening the practical definition of market participation. Safety data sheet updates aligned with REACH obligations, active registration dossier monitoring, and food-safety database registrations all contribute to a landscape where documentation is part of the product. For exporters and multinational buyers, this means that compliance maturity varies by supplier and by region, and those variations influence sourcing decisions.
The regulatory environment also shapes the pace at which new capacity can be commercialized and how easily suppliers can enter specific channels. Registration, notification, and certification pathways differ across pharmaceutical, food, and industrial applications, and the cost of navigating them can be substantial. Companies that invest early in maintaining current filings and transparent documentation can shorten sales cycles in regulated markets and reduce the risk of disqualification during procurement reviews.
Demand-Side Shifts in Agriculture and Life Sciences
Demand is being shaped by two distinct but important dynamics. In agriculture, zinc deficiency management and crop nutrition strategies continue to support demand for zinc sulfate as a micronutrient source, but purchasing behavior is increasingly informed by formulation compatibility, solubility, and application reliability. In life sciences and animal nutrition, demand is growing more slowly in volume terms but more decisively in value terms, because these channels require higher-grade material and stronger documentation. The rise of certified API-oriented supply chains and specialized pharmaceutical-grade sourcing has created a separate demand layer in which compliance and traceability matter as much as price.
This divergence means that aggregate demand growth can mask very different commercial realities. Volume-led buyers may focus on logistics and cost, while specification-led buyers focus on certification, purity, and supply continuity. Suppliers that understand this split can avoid the trap of competing on a single metric and instead design product lines, service models, and commercial terms around the needs of each channel.
Supply Chain and Cost Structure Evolution
The cost structure of zinc sulfate is sensitive to sulfuric acid prices, zinc feedstock availability, energy costs, and freight dynamics. Regional instability in the Middle East has periodically lifted sulfuric acid prices, raising production costs for zinc sulfate and related sulfate-based trace minerals. This is not a temporary inconvenience; it is a reminder that sulfate chemistry remains exposed to upstream volatility. Companies with diversified sourcing, long-term feedstock contracts, or integrated operations have a structural edge when input markets tighten.
At the same time, the supply chain is becoming more regionalized in practice. While Asia Pacific remains a major volume center, buyers in Europe and North America often prioritize proximity, reduced transit risk, and established regulatory documentation. That creates opportunities for producers with manufacturing footprints in or near key markets, as well as for exporters that can demonstrate reliable logistics and full regulatory alignment. Supply chain strategy is increasingly a market-access strategy.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market features a mix of large-scale European producers, specialized U.S. suppliers, and India-based manufacturers serving pharmaceutical, industrial, and export channels. This diversity matters because each group competes on a different set of strengths.
-
Europe’s scale producers emphasize large-volume capability, broad application coverage, and food-safety and quality-assurance positioning. Their strategic advantage lies in scale, established customer relationships, and the ability to supply multiple hydration states and industrial grades. Recent operational restarts at major sites show how quickly scale producers can recover supply and reaffirm market position after disruptions, reinforcing their role as reliability anchors for industrial and specialty buyers.
-
U.S.-based specialty suppliers compete through grade specificity and application alignment. High-purity testing accreditation and product forms suited to pharmaceuticals, food, and high-purity industrial use allow these players to serve channels where specification matters more than bulk price. Their value proposition is increasingly tied to documented quality, responsive service, and the ability to support regulated procurement requirements.
-
Middle East and export-oriented suppliers combine manufacturing access with export reach, often bridging European or other production bases with distribution into international markets. Their strategic relevance comes from logistics flexibility and the ability to serve buyers seeking geographic diversification or alternative sourcing pathways.
-
India-based pharmaceutical and API-linked manufacturers are positioned around regulatory filings, international certifications, and export-ready compliance documentation. Their differentiation often rests on certifications that support pharmaceutical and regulated industrial sales, enabling them to participate in channels where documentation and audit readiness are essential.
The common thread across these groups is that scale alone is no longer enough. The most resilient players combine capacity with specification control, regulatory readiness, and the ability to maintain supply during disruptions. Where those capabilities align, suppliers can move up the value chain into channels that reward reliability and documentation.
PW Consulting
Market Structure Evolution: Consolidation, Fragmentation, and New Entry
The market is not consolidating in a simple, uniform way. Concentration is moderate, which means a few major players hold meaningful share, but the long tail of regional and specialized suppliers remains commercially relevant. Over time, the structure is likely to evolve along two tracks. In bulk and price-sensitive channels, scale, logistics efficiency, and feedstock cost management will push toward consolidation among the most efficient producers. In regulated and high-purity channels, fragmentation may persist or even deepen, because access depends on certification, testing, and documentation rather than volume alone.
Sodium Sulfate Market
New entry will be most viable where suppliers can bring a clear regulatory or specification advantage, a regional logistics benefit, or a process advantage that reduces variability and cost. Pure commodity entry without differentiation is harder to sustain, especially when input costs fluctuate and buyers increasingly screen suppliers on compliance and continuity. The more interesting opportunities lie in targeted entry into pharmaceutical-grade, food-adjacent, or specialty industrial niches where the purchase decision is shaped by risk reduction rather than lowest unit price.
Future Trends and Commercial Implications
Trend One: Specification and Compliance as Market Moats
Over the next three to five years, the practical cost of entering regulated channels will remain high, and the value of proven documentation will increase. Suppliers that maintain current safety data sheet alignment, keep registration dossiers active, and hold recognized test accreditation will find it easier to secure contracts in pharmaceutical, food-safety, and specialty industrial applications. The commercial implication is clear: documentation and testing capability will increasingly function as a market moat. Companies that treat these capabilities as strategic assets can expect stronger customer retention, better pricing resilience, and broader access to higher-margin demand.
Trend Two: Regional Rebalancing and Supply-Side Diversification
Demand will continue to grow, but the geography of value capture will shift as buyers prioritize supply continuity, regulatory alignment, and freight reliability. Asia Pacific will remain a volume anchor, but European and North American demand may increasingly favor suppliers with regional production, strong logistics, and established regulatory standing. For manufacturers, this creates pressure to decide whether to compete primarily on volume, on proximity, or on specification. For buyers, it creates an incentive to diversify sourcing rather than depend on a single region or a single supplier profile. The broader implication is that resilience will be priced into sourcing decisions more explicitly than in the past.
Trend Three: Input Volatility Will Reward Integrated and Contract-Secured Producers
Sulfuric acid and upstream zinc economics will continue to influence margins, especially when geopolitical instability affects feedstock prices. Producers with long-term sourcing, integrated operations, or flexible cost-pass-through structures will be better positioned to maintain profitability during input shocks. The commercial opportunity here is not simply cost reduction; it is the ability to offer reliable pricing and consistent availability when competitors are distracted by cost volatility. In uncertain input markets, predictability becomes a selling point.
Risks and Uncertainties to Watch
Several uncertainties could alter the trajectory. Regulatory requirements may tighten further in specific end-use channels, raising the compliance burden for exporters and smaller producers. Input cost swings could compress margins for suppliers without contract protection or process efficiency. Demand in agriculture may be sensitive to crop economics, weather patterns, and fertilizer price cycles, introducing volatility into the largest volume channel. Finally, operational disruptions at major sites can temporarily reshape regional availability, rewarding suppliers with backup capacity and transparent communication. These risks are manageable, but they require proactive planning rather than reactive adjustment.
Actionable Guidance for Decision Makers
For Manufacturers and Producers
-
Align product portfolios with the economic logic of each channel. Maintain bulk-grade capability for volume demand, but invest in the documentation, testing, and grade control needed to serve pharmaceutical, food-safety, and specialty industrial buyers. The highest-margin growth is often in segments where specification reduces customer risk.
-
Treat regulatory readiness as a commercial function. Keep safety data sheets, registration filings, and quality-assurance records current and accessible. Buyers increasingly screen for compliance during sourcing decisions, and documentation gaps can become lost sales even when price and capacity look attractive.
-
Build input resilience into operations and commercial terms. Where possible, secure feedstock arrangements, improve process efficiency, and design pricing mechanisms that can withstand periodic sulfuric acid volatility without eroding customer trust.
For Investors and Strategic Buyers
-
Assess suppliers on more than capacity. The most durable value often sits with companies that combine reliable output with recognized testing, regulatory alignment, and the ability to maintain supply through disruptions. In regulated channels, these attributes can matter more than headline volume.
-
Look for structural advantages in specification control and certification. Producers with strong documentation and accreditation are better positioned to expand into higher-margin demand and to retain customers when input costs or supply conditions become turbulent.
-
Monitor regional diversification as a sourcing signal. In a market where availability can shift quickly, suppliers with multiple production bases, export flexibility, or strong logistics footprints offer more predictable access than single-point dependencies.
For Procurement and Supply Chain Leaders
-
Diversify by specification and region, not only by supplier name. Separate bulk-grade sourcing from high-purity or regulated-grade sourcing so that supply strategy matches end-use risk. A single sourcing model rarely fits both agrochemical volume and pharmaceutical-grade requirements.
-
Incorporate compliance and continuity into supplier evaluation. Review documentation currency, testing accreditation, and operational resilience alongside price. In practice, the cheapest option can become expensive if it fails a regulatory check or disrupts production.
-
Plan for input-driven price variability. Use contract structures, inventory buffers, or dual sourcing to reduce exposure to sulfuric acid volatility and regional logistics shocks. Predictable availability can be worth a premium when production continuity is at stake.
Why Deeper Intelligence Matters Now
The zinc sulfate market is growing, but growth is not uniform, and the value of that growth depends on where a company sits in the value chain. The most important decisions in the next few years will concern specification strategy, regulatory readiness, feedstock resilience, and sourcing diversification. Aggregate market size and CAGR tell part of the story, but they do not reveal which hydration states, applications, regions, or compliance pathways will generate the strongest returns for a particular business model.
For decision makers who need to move from broad market direction to actionable targeting, the next step is to examine the segmentation detail, competitive benchmarking, and scenario-based supply analysis that sit beneath the headline trends. A more granular view of regional demand patterns, product-grade economics, and supplier capability gaps can clarify where to invest, where to source, and where to defend position. Access to the full research report enables that level of precision, providing the detailed breakdowns and customization needed to translate strategic insight into operational decisions.
Magnesium Sulfate Market
For detailed analysis of this topic, please visit the official page: Zinc Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Interior Design Market: Why 6.5% CAGR and $331B by 2032 Changes Everything
By pmarketresearch, 2026-09-21
The Interior Design Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Context and Structural Challenges
The global interior design market has maintained a steady upward trajectory over the past half-decade, with total revenue expanding from approximately USD 157.5 billion in 2020 to an estimated USD 211.5 billion in 2025. The forward outlook points to continued expansion through 2032, supported by a projected compound annual growth rate of 6.5 percent. While the headline figures convey resilience, the underlying composition tells a more nuanced story. Residential-driven demand accounts for the largest share of value, commercial and institutional segments together form a substantial second pillar, and regional activity spans mature markets in North America and Europe alongside fast-growing corridors across Asia Pacific, Latin America, and the Middle East and Africa. This breadth provides a foundation of diversified demand, but it also masks pockets of volatility that are reshaping how firms plan capacity, pricing, and channel strategy.
The first structural challenge is cost volatility across materials and labor. Escalating input prices and tariff-driven distortions have placed margin pressure on manufacturers and contractors alike, while also complicating budgeting for end clients. Professional bodies have flagged rising material costs and widespread tariffs as factors that are directly reshaping demand for interior design services and product pricing, with independent analysis of recent trade actions estimating a meaningful per-home cost impact for builders that ripples through furnishing supply chains. At the same time, labor market tightness—paired with elevated housing prices in several regions—has made it harder for practices to scale project delivery without compressing fees or stretching timelines. For executives, the operational question is no longer whether costs will fluctuate, but how to build pricing architecture, sourcing flexibility, and service models that can absorb shocks without eroding client trust.
The second challenge is the shifting regulatory and credentialing landscape. Interest in formalizing the profession has accelerated, with a growing number of states considering legislation related to licensing or registration of interior design practitioners, and one state reaching a milestone as the thirtieth to regulate the profession following a sunset review. These developments affect liability exposure, permissible scope of work, and competitive differentiation across jurisdictions. Firms that rely on unlicensed staff or cross-border service delivery must anticipate uneven rule sets, while brands that invest in credentialed talent can turn compliance into a trust signal. The practical implication is that market access, insurance requirements, and partnership structures are becoming more localized and more consequential than in prior cycles.
The third challenge is fragmentation in how value is captured. Despite the presence of category-leading companies, the top three operators account for roughly 18 percent of revenue and the top five for about 22 percent, indicating a broadly distributed market with room for consolidation as well as for niche specialization. That dispersion creates both opportunity and risk: it allows agile entrants to win in specific use cases or geographies, but it also means that price competition, channel conflict, and brand dilution can emerge quickly when demand softens. Leaders that convert scale into service depth, proprietary product systems, and integrated delivery tend to outperform in mixed cycles, while undifferentiated players face margin erosion.
Together, these dynamics create a market that is growing in aggregate yet demanding more discipline at the micro level. Executives should read the growth trajectory not as an invitation to expand indiscriminately, but as a reason to prioritize resilience, credentialing readiness, and strategic focus in the segments where they can sustain advantage.
2. Core Drivers Reshaping Demand and Supply
Technology and Digital Enablement
Digital workflows are moving from support functions to core value drivers. Generative design, parametric specification tools, and integrated visualization platforms are compressing the time from concept to approval, which is particularly valuable in residential and commercial projects where client decision cycles can be protracted. More importantly, these tools are enabling firms to standardize repeatable elements while customizing high-impact spaces, improving both margin and client satisfaction. The same technologies support better inventory synchronization for product suppliers by aligning design intent with manufacturable options, reducing rework and last-minute substitutions. The practical takeaway is that technology investment is increasingly a margin and speed story: the firms that can deliver fast, high-fidelity options and keep specification accuracy high are winning a larger share of wallet in complex projects.
Policy and Regulatory Dynamics
Policy is becoming a more direct lever on demand and operating costs. Trade actions and material tariffs have altered the economics of building and furnishing products, pushing some procurement teams to re-evaluate sourcing footprints and specs. Regulatory attention to professional credentials is also changing the playing field, raising the stakes for firms that deliver design services under varying legal regimes. Rather than treating these as external noise, leading organizations are incorporating policy scenarios into their planning: they diversify supplier bases to reduce concentration risk, align service offerings with recognized credentials where regulation is tightening, and prepare documentation and compliance processes that can be scaled across jurisdictions. In short, policy predictability is now an asset to be managed, and the firms that institutionalize scenario planning around it are better positioned to protect margins when rules shift.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user priorities are evolving in ways that favor service-led value over transactional transactions. In residential contexts, homeowners and developers increasingly seek cohesive design systems that balance aesthetics, durability, and lifecycle cost, particularly as housing affordability pressures shape renovation versus move-up decisions. In commercial and institutional settings, organizations are recalibrating spaces for hybrid work, wellness, accessibility, and brand experience, which expands the scope of interior work beyond fit-out to include adaptive reuse and spatial programming. Awards, trade shows, and curated showcases continue to influence taste formation and accelerate the adoption of new styles, materials, and crafts; the steady cadence of global events across North America, Europe, and Asia underscores how quickly preference cycles can move and how important timely exposure is for brands aiming to stay relevant. For operators, the implication is that design value must be demonstrated through outcomes—usability, durability, speed, and emotional resonance—rather than through decoration alone.
Supply Chain and Cost Structure Realignment
The cost structure of interior products and services is being rebalanced by a combination of input volatility, logistics constraints, and labor economics. Builders and suppliers are absorbing higher baseline costs on key inputs, which cascades into product pricing and project budgets, while shortages of skilled labor raise the cost of execution and extend delivery windows. In response, many organizations are shifting toward regionalized sourcing, modular product platforms, and pre-configured systems that simplify installation and reduce on-site variability. Vertical integration is gaining renewed attention in certain categories because it can tighten quality control and improve lead-time reliability, though it also requires capital discipline and careful capacity planning. The strategic signal is clear: resilience and repeatability are becoming as important as design novelty, and supply chain choices are increasingly a competitive differentiator.
3. Competitive Landscape and Leading Strategies
Strategic Positioning of Key Participants
Several established players illustrate distinct routes to advantage in a fragmented market. Legacy-oriented product houses have leaned into brand portfolios that span heritage and contemporary aesthetics, allowing them to serve multiple price tiers while preserving prestige equity. Their strategic edge lies in breadth of offering—wallpapers, fabrics, ancillary interior products, and coordinated collections—that simplifies specification for designers and trade partners, and in the ability to refresh lines without abandoning recognizable franchises. Luxury lifestyle retailers, by contrast, compete on curation, service, and aspirational positioning, extending across furniture, textiles, lighting, bathware, and décor through multiple brand channels. Their advantage is the integration of high-end product with design advice and an experiential retail environment that supports higher price points and deeper client relationships. Vertically integrated furniture manufacturers combine custom-crafted production with design services and North American manufacturing, using that model to control lead times, quality, and cost-to-serve while offering complimentary design support that raises switching costs for customers. Large-scale flooring and interior panel producers anchor broad application coverage across furniture, cabinetry, and residential and commercial use, leveraging scale in materials and manufacturing to compete on specification frequency, consistency, and supply reliability.
Differentiation and Scope Decisions
Across these models, differentiation tends to emerge from a few recurring choices. The first is the depth of integration between product and service. Companies that pair specification-grade products with design assistance, installation guidance, or project coordination capture more of the project value and reduce the likelihood of substitution. The second is the balance between breadth and focus. Broad portfolios enable cross-selling and specifier convenience, but focused systems can command stronger loyalty in key segments if they solve a clear problem—durability, maintenance, speed of installation, or style cohesion. The third is the degree of vertical control. In an environment of cost and labor pressure, manufacturers with direct oversight of critical steps can protect quality and timing, while more decentralized players must invest in supplier governance and transparent communication to achieve similar outcomes. The practical lesson is that advantage rarely comes from a single attribute; it comes from a coherent system that aligns brand promise, product capability, service model, and supply discipline.
Evolution of the Market Structure
The competitive map is evolving along three lines. Consolidation is plausible where scale improves purchasing power, speeds innovation cycles, and expands distribution reach, particularly if larger players can integrate design services or channel access that smaller firms cannot easily replicate. Differentiation is intensifying in parallel, as segments such as sustainable interiors, wellness-focused spaces, and regionally specific aesthetics create demand for specialized expertise and materials, opening space for firms that can credibly claim depth in a niche. New entrants and adjacent players continue to test the boundaries of the market, using digital storefronts, direct-to-consumer channels, and subscription-style services to reach customers outside traditional trade paths. These movements do not point to a single end state; rather, they suggest a market in which the center will hold for broad-line players with strong systems, while edges will become more dynamic as specialists and digital-native models gain traction. Executives should therefore plan for a landscape that remains contested, with advantage determined by the clarity of positioning and the reliability of execution.
PW Consulting Information & Electronics Research Center
4. Forward Outlook: Trends and Commercial Implications (Next 3–5 Years)
Service-Integrated Product Systems Will Gain Share
Over the next few years, demand is likely to tilt toward offerings that combine repeatable product platforms with embedded design and specification support. Clients in both residential and commercial settings are seeking speed, certainty, and coherence, and they are willing to pay a premium when a solution reduces coordination risk and installation variability. Brands that can present curated systems—complete with sample libraries, digital specification tools, and clear installation sequences—will be better placed to capture project budgets and to defend margins against commoditization. The commercial opportunity lies in packaging: creating modular, specifiable systems that scale across use cases while retaining enough flexibility to meet local preferences. The risk is execution complexity, because systems that are too rigid can alienate designers, while systems that are too loose fail to deliver the promised consistency.
Credentialing and Compliance as Competitive Filters
The regulatory momentum around professional licensing and registration is expected to continue shaping how services are delivered and how firms are evaluated. As more jurisdictions formalize requirements, credentialed practitioners and organizations will gain an advantage in projects where liability, safety, and code interaction matter, and will be better positioned to partner with architects, contractors, and public-sector clients. This trend creates an opportunity for firms to use compliance as a trust asset, particularly in institutional and commercial work. The uncertainty is uneven adoption: if rules vary widely across regions, multi-market operators will need to maintain flexible staffing and documentation practices, and smaller firms may face higher relative compliance burdens. Executives should treat credentialing strategy as part of market access planning rather than as a back-office concern.
Industrial Design Market
Sustainability and Lifecycle Value Move From Messaging to Specification
Sustainability is becoming a practical filter in procurement, driven by a combination of client expectations, event-led trend diffusion, and a growing appetite for transparency in materials and processes. Dedicated showcases and trade events that emphasize sustainable interiors, alongside broader industry gatherings, indicate that eco-conscious design is moving from a marketing theme to a specification criterion, especially in commercial and institutional projects where operating costs and reputational risk are salient. The commercial implication is that firms able to provide clear, verifiable information on material sourcing, durability, maintenance, and end-of-life options can win preference in selection processes and reduce perceived risk for buyers. The caveat is that credibility matters: claims that cannot be substantiated may erode trust quickly, and the cost of verification can be a barrier for smaller suppliers unless they align with recognized standards or partner with testing and certification bodies.
5. Strategic Implications for Decision-Makers
For manufacturers and product suppliers, the priority is to reduce variability and increase specifiability. That means investing in modular platforms and coordinated collections that simplify selection for designers, expanding digital tools that connect design intent to manufacturable options, and hardening supplier governance to manage input volatility and lead-time risk. Where vertical integration is feasible, it should be pursued with clear attention to capital efficiency and capacity utilization; where it is not, stronger transparency and contingency planning with upstream partners become essential. The goal is to make it easier for the market to choose your products repeatedly, which in turn supports more predictable demand and better pricing power.
For investors, the most attractive exposure is likely to be found where service depth, credentialing readiness, and supply resilience compound rather than where growth is pursued through breadth alone. Categories and platforms that can demonstrate repeat specification, high switching costs through design services, and credible sustainability credentials are better positioned to sustain margins across cycles. Due diligence should focus on the operating model behind the headline momentum: how pricing responds to input shocks, how lead times are controlled, and how the firm plans for a more fragmented regulatory environment. Capital that supports operational discipline and credible differentiation is more likely to outperform than capital that simply chases segment tailwinds.
Worldwide Marine Interiors Market
For procurement and design leadership, the strategic task is to convert volatility into a negotiation advantage by diversifying sourcing, favoring specifiable systems that reduce rework, and aligning project timelines with realistic labor and material availability. Building internal criteria that reward durability, maintenance ease, and verifiable sustainability can lower total cost of ownership and reduce the risk of reactive substitutions. At the same time, keeping a close watch on regulatory changes in relevant jurisdictions will help avoid eligibility or liability surprises as projects scale across regions.
Keeping pace with a market that is both expanding and fragmenting requires current, granular visibility into how segments, regions, and company strategies are evolving together. Detailed segmentation data, competitive benchmarks, and tailored scenario planning can turn broad trends into concrete choices about where to invest, what to standardize, and which risks to hedge. Readers seeking a fuller picture of the subsegments, regional nuances, and company-level dynamics underpinning this analysis can access the complete research report for deeper data and customized recommendations.
For detailed analysis of this topic, please visit the official page: Interior Design Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Passenger Boarding Bridge Market: How Asia Pacific Drives 6.98% CAGR to $3.22B
By pmarketresearch, 2026-09-21
Navigating the Passenger Boarding Bridge Market: Strategic Trends and Commercial Opportunities for 2026–2032
The passenger boarding bridge market is experiencing a period of structured expansion, driven by sustained airport infrastructure investment and gradual technological upgrades across terminals worldwide. Valued at approximately USD 2,030 million in 2025, the market has grown from around USD 1,400 million in 2020, reflecting a compound annual growth rate of 6.98 percent through the forecast horizon of 2032. By the end of the projection period, market size is expected to approach USD 3,224 million, indicating a shift from cyclical replacement cycles toward smarter, more integrated gate equipment. This trajectory is not merely about capacity addition; it reflects evolving ground-handling philosophies, fleet modernization, and a growing emphasis on operational reliability under tighter regulatory and sustainability expectations. For manufacturers, airport operators, and investors, the market presents a landscape where historical performance patterns intersect with structural changes in technology, procurement policy, and design preferences.
The Asia Pacific region continues to represent the largest revenue pool, supported by high-volume terminal expansion, new hub development, and intense competition to improve passenger throughput and turnaround efficiency. Europe and North America remain significant contributors, with growth increasingly shaped by modernization programs, fleet optimization, and the replacement of aging bridge inventories rather than pure volume expansion. Movable boarding bridges continue to hold a substantial share of market activity, reflecting their flexibility in dynamic gate configurations and their suitability for airports managing mixed aircraft fleets and variable operational layouts. In parallel, apron-drive configurations have maintained a strong presence, while nose-loader, over-the-wing, T-bridge, and commuter variants serve more specialized deployment scenarios where aircraft geometry, terminal spacing, or regional operational constraints dictate equipment selection. On the technology side, electro-mechanical systems have been steadily displacing hydraulic alternatives, driven by lower energy consumption, reduced maintenance burdens, and improved alignment with long-term operational efficiency goals.
Alongside these structural dynamics, three challenges are shaping strategic decision-making across the value chain. First, airports are balancing capital expenditure constraints with the need to modernize aging gate equipment that must handle larger aircraft, higher passenger volumes, and more frequent service cycles. Second, procurement policy is becoming more complex, particularly in markets where regulatory frameworks, local content expectations, and grant-linked requirements influence sourcing decisions and supplier eligibility. Third, the transition toward more energy-efficient and digitally integrated bridge systems is creating pressure on suppliers to demonstrate total cost of ownership advantages rather than relying solely on upfront price competitiveness. These factors are not isolated; they interact with each other and with regional demand patterns, making it increasingly important for participants to align product roadmaps with operational realities and procurement environments.
Core Drivers Reshaping the Market
Technology innovation is one of the most visible forces altering buyer expectations and supplier positioning. Electro-mechanical boarding bridges are gaining traction over hydraulic designs because they offer measurable reductions in energy use and long-term maintenance intensity. This shift is not simply a preference for newer architectures; it reflects a broader operational logic in which airports and ground handlers are evaluating lifecycle costs more carefully, especially where energy prices, labor availability, and service intervals affect total operating economics. Automated docking features, improved safety systems, and more responsive control interfaces are also becoming differentiators, allowing operators to reduce manual intervention, improve turnaround predictability, and support higher gate utilization. As these capabilities mature, the market is gradually rewarding suppliers that can integrate mechanical reliability with system-level intelligence rather than selling bridge hardware in isolation.
Policy and regulatory environments are acting as another important catalyst. Public funding programs and airport infrastructure grants are channeling capital into bridge replacement and installation projects, particularly in markets where aging gate infrastructure has become a constraint on capacity and service quality. In the United States, for example, substantial grant allocations have been directed toward airport improvement programs that include passenger boarding bridge replacements and installations across a broad set of airports. This type of support can accelerate project timelines and broaden the pool of funded modernization activity. At the same time, procurement rules are introducing additional layers of complexity. Project-specific Buy American waivers issued in 2025 and 2026 for certain boarding bridge projects illustrate how regulatory compliance and sourcing flexibility can intersect, creating both opportunities and eligibility constraints for suppliers. The practical implication is that policy support is expanding demand in specific segments, but it also requires participants to navigate funding conditions, documentation requirements, and local content expectations with precision.
Demand-side behavior is changing as well, shaped by airport capacity strategies and passenger experience priorities. Commercial airports remain the dominant application setting because they handle the highest traffic volumes and the broadest mix of aircraft types, making boarding bridge performance a direct factor in gate throughput and passenger flow. Airports are increasingly treating boarding bridges not as passive connectors between terminal and aircraft, but as active components of the gate ecosystem, where reliability, turnaround speed, and compatibility with evolving aircraft interiors influence customer satisfaction and operational planning. Regional airports, by contrast, tend to prioritize simpler deployment economics, durability, and maintainability, often favoring solutions that can serve limited gate configurations without excessive complexity. These differing demand profiles mean that product positioning, service offerings, and financing approaches must be tailored to the operational realities of each airport segment rather than applied uniformly.
PW Consulting Automotive & Machinery Research Center
Supply chain and cost structures are adding further nuance to market dynamics. Steel-walled designs have retained a strong share of sales due to their ruggedness, lower initial cost, and compatibility with a wide range of climatic and operational conditions. This preference underscores a pragmatic approach among many buyers, especially where durability and first-cost control remain decisive. At the same time, the broader shift toward electro-mechanical platforms is gradually reshaping component sourcing, maintenance planning, and service models. Suppliers that can manage raw material exposure, standardize high-demand configurations, and provide predictable lifecycle support are better positioned to navigate cost pressure while preserving margin stability. The market is therefore rewarding a blend of engineering robustness and operational predictability, particularly in environments where project timelines, installation complexity, and long-term service commitments influence winning bids.
Competitive Landscape and the Evolution of Winning Strategies
The competitive field includes a mix of established global suppliers and specialized operators with distinct regional footprints and product emphases. Several companies have built their positioning around integrated gate infrastructure capabilities, combining boarding bridge systems with automated docking, ground support equipment, or broader terminal interface solutions. Others differentiate by focusing on refurbed equipment, component-level innovation, or airport-specific delivery track records that emphasize installation reliability and after-sales support. The strategic common thread among stronger players is a move toward solution-oriented value propositions: rather than competing primarily on unit price, leading suppliers are aligning their offerings with gate performance, maintenance efficiency, compatibility with aircraft mixes, and the ability to support both new installations and lifecycle refurbishment.
A notable aspect of the current landscape is the way recent project activity and exhibition presence reinforce market positioning. Suppliers that maintain visible engagement with airport operators through project deliveries and industry events are better able to demonstrate execution capability and keep their product roadmaps aligned with procurement realities. For instance, the delivery and installation of multiple passenger boarding bridges at a major terminal expansion project illustrates how targeted installations can validate a supplier’s ability to support capacity growth while meeting airport-specific integration requirements. Similarly, continued participation in major airport trade events allows suppliers to showcase complete bridge systems alongside individual components, signaling both system-level competence and flexibility for partial upgrades or component replacement. These activities matter because airport procurement is often influenced by demonstrated project experience, local installation capability, and the supplier’s ability to support the asset over its service life.
Market concentration remains relatively high, indicating that a limited number of participants command a significant share of revenue. This concentration creates a competitive environment where scale, global installation experience, product breadth, and service networks can serve as meaningful barriers. At the same time, the market is not closed to focused entrants or specialists that can address specific airport needs, such as refurbishment, component innovation, sustainability-oriented upgrades, or regional deployment expertise. As a result, the landscape is evolving through a combination of consolidation among larger players and targeted competition from firms with differentiated technical or commercial approaches. Suppliers that can combine engineering consistency with strong service execution, and that can adapt to regulatory and funding conditions in key markets, are likely to strengthen their position over the forecast period.
Worldwide Military Floating Bridge Market
Looking Ahead: Trends That Will Shape the Next Three to Five Years
One of the clearest forward-looking trends is the continued migration from hydraulic to electro-mechanical boarding bridges as operators prioritize energy efficiency and reduced maintenance exposure. This transition is likely to accelerate where airports face pressure to manage operating costs, improve sustainability performance, and standardize equipment across multiple gates. The commercial opportunity lies not only in new installations but also in retrofit and upgrade pathways that allow airports to modernize existing assets without full replacement. Suppliers that can offer credible conversion strategies, predictable service outcomes, and compatible control architectures will be well placed to capture demand across both new builds and refurbishment cycles.
A second trend is the growing importance of automated docking, safety systems, and gate-level integration as airports seek more predictable turnaround performance and reduced manual handling risk. As these capabilities become more standardized, differentiation may shift toward reliability under high utilization, interoperability with airport operating systems, and the ability to support mixed aircraft configurations without sacrificing deployment speed. This creates opportunities for suppliers that can package mechanical performance with digital control features in a way that aligns with airport operational planning. The risk, however, is that over-engineering or complexity could raise installation costs and maintenance burdens, particularly for regional airports that value simplicity and durability over advanced automation.
A third trend concerns the influence of funding mechanisms and procurement policy on project visibility and supplier eligibility. Infrastructure grants and airport improvement programs are expected to keep replacement and modernization activity active in several key markets, but the rules attached to such funding can vary by project and location. Where local content expectations or Buy American-type conditions apply, suppliers may need to demonstrate supply chain compliance, domestic sourcing pathways, or partner-based delivery models to remain competitive. This dynamic creates both opportunity and uncertainty. It can open doors for suppliers with the right compliance posture and installation footprint, while simultaneously constraining participation for firms that cannot meet localized procurement requirements. Participants should therefore treat policy and funding environments as strategic variables, not background conditions, and build procurement readiness into their commercial planning.
Strategic Actions for Decision-Makers
For manufacturers and equipment suppliers, the priority is to strengthen total-cost positioning rather than compete solely on initial price. This means investing in electro-mechanical architectures where they are gaining acceptance, standardizing high-demand configurations such as steel-walled designs that continue to dominate sales for practical reasons, and building service models that support both new installations and refurbishment. Suppliers should also map their compliance and sourcing capabilities against the funding and procurement rules that shape key airport projects, since eligibility can be as important as technical performance in winning bids. Differentiation is increasingly tied to demonstrated installation execution, component reliability, and the ability to support airports through the full asset lifecycle.
For investors, the market offers a profile of steady growth with selective opportunities in modernization, automation, and refurbishment-driven demand. The most attractive exposure is likely to come from participants that can balance scale with segment-specific relevance, maintain strong service and installation capabilities, and adapt product offerings to shifting technology preferences. Investors should pay close attention to how suppliers position themselves against regulatory and funding conditions, because project-level policy changes can influence order timing, market access, and margin dynamics. Monitoring which companies are strengthening their presence through project deliveries, trade engagement, and component-level innovation can provide early signals about competitive momentum.
For airport operators and procurement teams, the strategic focus should be on aligning bridge selection with operational priorities and lifecycle economics. Where gate utilization, turnaround consistency, and energy cost matter most, electro-mechanical solutions with automated docking and improved safety features may deliver value beyond upfront price. Where durability, simplicity, and first-cost control are paramount, steel-walled configurations and proven mechanical designs remain compelling. Procurement planning should also account for installation complexity, local service availability, and any funding-related eligibility requirements that may affect supplier selection. A structured evaluation framework that integrates technical performance, maintenance expectations, and regulatory conditions will support more resilient purchasing decisions.
For decision-makers seeking more detailed segmentation data, regional considerations, and project-level dynamics, deeper intelligence can provide the granularity needed to translate these trends into concrete plans. The Passenger Boarding Bridge Market Landscape 2026–2032 and related PW Consulting research materials are available for teams that require more detailed breakdowns across type, model, technology, structure, application, and regional demand patterns, along with customized guidance for specific market or procurement scenarios.
Worldwide Airport Furniture Market
For detailed analysis of this topic, please visit the official page: Passenger Boarding Bridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com