

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Radiation Shielding Textile Market: Why 5.1% CAGR and Asia Pacific’s 32% Share Redefine Growth

Radiation Shielding Textile Market: Strategic Trends & Commercial Opportunities (2026–2032)
Market Landscape & Core Challenges
The global market for radiation shielding textiles is navigating a phased expansion, with revenue scaling from approximately $70 million in 2020 toward a $130 million horizon by 2032. This trajectory reflects a compound annual growth rate of roughly 5.1% across the 2026–2032 forecasting window, signaling steady rather than explosive momentum. The market’s maturation is less about raw volume growth and more about structural refinement: demand is shifting from generic protective coveralls toward engineered, application-specific textiles that balance shielding performance, ergonomics, and compliance readiness.
Worldwide Anti Radiation Clothing Market
Several structural challenges complicate this progression. First, the tension between shielding effectiveness and wearable practicality remains unresolved for many end-use scenarios. High-attenuation materials often carry weight, stiffness, or thermal discomfort penalties that limit adoption in prolonged-contact applications, particularly in healthcare and specialized industrial settings. Second, regulatory complexity is accelerating material substitution cycles. Restrictions on certain chemical substances in textiles, combined with tightening requirements for personal protective equipment certification, are forcing manufacturers to validate not only shielding performance but also chemical safety and durability under repeated use. Third, input cost volatility is reshaping margin architectures. Fluctuations in base metals and specialty concentrates feed directly into the cost structures of metallized and blended shielding fabrics, while trade policy shifts have introduced new friction into cross-border sourcing and finished-goods distribution.
For decision-makers, the immediate implication is clear: the market is moving from a commodity-adjacent phase toward a performance-differentiated phase. Companies that treat shielding textiles as a spec-driven engineering problem rather than a volume play will capture disproportionate value as procurement teams standardize on verified durability, certification status, and lifecycle cost.
Key Drivers Reshaping the Market
Materials Innovation and Functional Differentiation
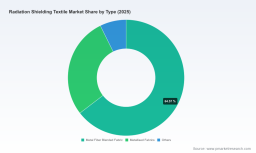
Material architecture is the most visible lever of competitive differentiation. Metal fiber blended fabrics continue to anchor a significant share of the market because they offer an established balance of conductivity, washability, and manufacturability. Metallised fabrics, particularly silver-plated and metal-coated variants, remain central for electromagnetic shielding in technical textiles and electromagnetic compatibility applications. At the same time, lead-free and lightweight shielding approaches are gaining strategic relevance, especially where ionizing radiation protection intersects with ergonomics and repeated occupational exposure. The commercial appeal of these innovations is not merely technical; it is operational. Textiles that maintain shielding integrity through repeated flexing, laundering, and environmental exposure reduce replacement frequency and simplify compliance documentation, which matters increasingly in regulated procurement environments.
Regulatory and Certification Pressures as a Market Filter
Regulation is functioning as both a constraint and a competitive filter. In the European market, restrictions on certain substances in clothing, textiles, and footwear have raised the bar for chemical compliance in shielded products, while broader chemical action plans are extending scrutiny toward technical textiles and associated surface treatments. Parallel certification requirements for personal protective equipment are pushing manufacturers to substantiate claims with reproducibility data rather than laboratory benchmarks alone. This dynamic favors firms that can assemble a credible documentation package—material composition, durability evidence, and application-specific validation—because procurement and risk functions increasingly treat certification as a gatekeeping criterion rather than a back-office detail.
Demand-Side Shifts in Occupational and Medical Settings
Demand patterns are being reshaped by how protective textiles are used day to day. In medical environments, there is growing emphasis on localized shielding solutions that reduce dose exposure without imposing the burden of full-body garments for every procedure. This has encouraged development of targeted protection devices and modular textile systems that can be deployed where exposure risk is concentrated. Beyond healthcare, industrial users continue to seek shielding materials that integrate into existing workflows without disrupting dexterity, ventilation, or maintenance routines. At the consumer-adjacent end, interest in maternity and general anti-radiation apparel has expanded awareness of shielding textiles, though commercial scale in that segment depends heavily on perceived benefit, affordability, and repeat-purchase dynamics. Across these settings, the common thread is a preference for solutions that marry protection with usability.
Supply Chain Economics and Input Cost Exposure
Cost structure is becoming a strategic variable rather than a background condition. Stabilized pricing across lead markets has provided some predictability for traditional shielding inputs, but that stability does not extend uniformly to all materials. Sharp increases in tungsten concentrate pricing illustrate how quickly input economics can shift for alternative high-density shielding paths, affecting the feasibility of specific formulations and pushing teams to reassess blending ratios, sourcing diversification, and inventory planning. At the same time, tariff escalations on textiles and related imports in major markets have raised the effective cost of cross-border supply chains, prompting manufacturers to reconsider where value-added processing occurs and how finished goods are routed. The result is a market in which resilient sourcing strategies and regional production flexibility are becoming part of the competitive advantage set.
Competitive Landscape & Leading Strategies
The competitive field is moderately concentrated, with the largest players collectively accounting for a meaningful but not suffocating share of revenue. That structure leaves room for specialized innovators while rewarding established manufacturers that can scale certification, consistency, and application engineering. A few strategic positions stand out.
- Swiss Shield AG has built its position around high-tech yarns and cotton/polyester fabric systems designed for high-frequency electromagnetic radiation shielding, with product lines spanning garments, home textiles, and industrial applications. Its strategic emphasis appears to be on embedding shielding capability into familiar textile substrates, which can simplify integration for downstream manufacturers and reduce adoption friction.
- Shieldex focuses on metallized silver-plated fabrics and conductive textiles available in woven, knitted, and nonwoven forms, targeting technical textiles and electromagnetic compatibility applications. This breadth of fabric construction supports customization for different performance and handling requirements, which is valuable in application-driven procurement.
- Radiation Shield Technologies (RST) occupies a distinctive niche as the sole producer of a lead-free, lightweight radiation protection fabric designed for ionizing radiation shielding in full-body suits, blankets, vests, and tents. Its differentiation rests on material uniqueness and the ability to offer an alternative to conventional heavy shielding approaches, which can be compelling where weight, comfort, and portability influence adoption.
- Texray AB has positioned itself around textile-based radiation protection devices for medical professionals, supported by regulatory certifications and recent durability validation. Independent scientific study results have highlighted resistance to high numbers of flex cycles and substantial additional dose reduction in medical applications, reinforcing a value proposition centered on long-service performance rather than single-use protection logic.
- Joyncleon addresses lightweight maternity and general anti-radiation apparel using high-performance fabrics, illustrating how shielding textiles can extend into consumer-facing apparel categories where comfort, style, and accessibility shape purchase decisions.
- Metal Textiles contributes metal-coated and metallized fabric capabilities for radiation and electromagnetic shielding, reinforcing the broader ecosystem of metallization-based solutions that serve industrial and technical use cases.
The strategic throughline across these players is differentiation through either material architecture, application specialization, or validation depth. Companies that compete mainly on specification sheets are vulnerable to those that can demonstrate durable field performance and maintain compliance readiness across jurisdictions. One notable recent development underscores this direction: Texray AB’s 2025 certification-related progress, including study-confirmed durability against extensive flex cycling and up to 97% additional dose reduction in medical applications, signals how performance evidence can strengthen positioning in regulated, high-stakes settings.
Looking ahead, the competitive landscape is likely to evolve along two tracks. On one hand, consolidation may accelerate among manufacturers that can combine material expertise with compliance, distribution, and application support. On the other, new entrants may emerge around targeted niches—localized medical shielding, lightweight alternatives for specific occupational tasks, or specialized electromagnetic shielding for technical textiles—where incumbents are less optimized. The dividing line will be whether a company can offer a repeatable, verifiable solution that fits into a procurement process, not merely a promising material concept.
Outlook & Emerging Opportunities, 2026–2032
The next several years are likely to be defined by three interlocking trends.
1. From shielding presence to shielding performance. Demand will increasingly center on textiles that prove durable under real use conditions, not just on initial attenuation numbers. Products that can demonstrate repeated flex endurance, wash stability, and consistent performance after deployment will command stronger preference in medical, industrial, and military-adjacent settings. The commercial opportunity lies in building product narratives around lifecycle value: fewer replacements, more predictable protection, and simpler audit trails for compliance teams.
2. Material substitution and formulation arbitrage. As regulatory expectations tighten and input costs move unevenly across metals and concentrates, manufacturers that can adjust formulations without sacrificing core performance will gain flexibility. This creates opportunities for blended systems, alternative metal choices, and lead-free options where they can meet shielding and usability thresholds. The flip side is supply-chain risk: pricing swings in key inputs can quickly alter cost competitiveness, so scenario planning and multi-source sourcing will matter more than in a stable-commodity environment.
PW Consulting Health Care Research Center
3. Application-led segmentation rather than blanket categories. Buyers are likely to adopt more granular purchasing logic, selecting textiles by end-use rather than by broad category. Medical localized protection, industrial electromagnetic compatibility, and lightweight occupational shielding each present different engineering and certification requirements. Companies that organize product lines around these use cases—and support them with relevant documentation and integration guidance—are better positioned to capture share in higher-value segments.
Potential risks and uncertainties should be factored into planning. Certification pathways can shift, especially where chemical restrictions and PPE requirements evolve. Trade policy volatility can alter landed costs and redirect sourcing strategies, particularly for manufacturers dependent on cross-border material flows or finished-goods distribution. Durability claims, if not substantiated consistently, can become a liability in regulated procurement. Finally, where consumer-facing shielding products rely heavily on perceived rather than measured benefit, adoption may be sensitive to competitive alternatives and price expectations.
Worldwide Fibers and Electromagnetic Shielding Market
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product development with verifiable durability and compliance readiness. Engineering effort should be directed toward formulations and fabric constructions that hold up under repeated flex, laundering, and operational stress, because those attributes increasingly influence purchasing decisions in regulated settings. It is equally important to prepare documentation that supports certification and procurement review, since the ability to demonstrate reproducible performance can be as valuable as the raw shielding specification. Diversification of input sourcing and regional manufacturing flexibility will help manage cost and trade-related disruptions.
For investors, attention should focus on companies with defensible differentiation in either material architecture, application specialization, or validation depth. Business models that depend on undifferentiated volume in a moderately concentrated market face more competition and thinner margins, while those tied to certified, application-specific solutions have stronger moats. Due diligence should assess input cost exposure, regulatory preparedness, and the credibility of durability claims, because these variables will shape profitability as the market moves from early expansion toward more performance-driven competition.
For procurement and end-user organizations, the practical move is to define shielding requirements by application and to evaluate suppliers against a broader scorecard that includes durability evidence, certification status, chemical compliance, and total cost of ownership. Selecting textiles on the basis of initial attenuation alone can leave exposure to premature degradation, replacement costs, and compliance gaps. Establishing internal acceptance criteria for field performance and documentation will improve consistency across purchases and reduce downstream risk.
As the radiation shielding textile market continues to refine its value proposition around performance, compliance, and application fit, the companies and buyers that act on those priorities early are best positioned to capture the upside of the forecast period. For teams that need a deeper, segment-level view of sizing, competitive positioning, regional dynamics, and material-cost exposure to guide planning, the full PW Consulting market report provides the detailed data foundation and tailored strategic options to support those decisions.
For detailed analysis of this topic, please visit the official page: Radiation Shielding Textile Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com