

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Passenger Boarding Bridge Market: How Asia Pacific Drives 6.98% CAGR to $3.22B

Navigating the Passenger Boarding Bridge Market: Strategic Trends and Commercial Opportunities for 2026–2032
The passenger boarding bridge market is experiencing a period of structured expansion, driven by sustained airport infrastructure investment and gradual technological upgrades across terminals worldwide. Valued at approximately USD 2,030 million in 2025, the market has grown from around USD 1,400 million in 2020, reflecting a compound annual growth rate of 6.98 percent through the forecast horizon of 2032. By the end of the projection period, market size is expected to approach USD 3,224 million, indicating a shift from cyclical replacement cycles toward smarter, more integrated gate equipment. This trajectory is not merely about capacity addition; it reflects evolving ground-handling philosophies, fleet modernization, and a growing emphasis on operational reliability under tighter regulatory and sustainability expectations. For manufacturers, airport operators, and investors, the market presents a landscape where historical performance patterns intersect with structural changes in technology, procurement policy, and design preferences.
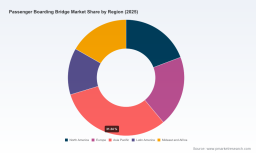
The Asia Pacific region continues to represent the largest revenue pool, supported by high-volume terminal expansion, new hub development, and intense competition to improve passenger throughput and turnaround efficiency. Europe and North America remain significant contributors, with growth increasingly shaped by modernization programs, fleet optimization, and the replacement of aging bridge inventories rather than pure volume expansion. Movable boarding bridges continue to hold a substantial share of market activity, reflecting their flexibility in dynamic gate configurations and their suitability for airports managing mixed aircraft fleets and variable operational layouts. In parallel, apron-drive configurations have maintained a strong presence, while nose-loader, over-the-wing, T-bridge, and commuter variants serve more specialized deployment scenarios where aircraft geometry, terminal spacing, or regional operational constraints dictate equipment selection. On the technology side, electro-mechanical systems have been steadily displacing hydraulic alternatives, driven by lower energy consumption, reduced maintenance burdens, and improved alignment with long-term operational efficiency goals.
Alongside these structural dynamics, three challenges are shaping strategic decision-making across the value chain. First, airports are balancing capital expenditure constraints with the need to modernize aging gate equipment that must handle larger aircraft, higher passenger volumes, and more frequent service cycles. Second, procurement policy is becoming more complex, particularly in markets where regulatory frameworks, local content expectations, and grant-linked requirements influence sourcing decisions and supplier eligibility. Third, the transition toward more energy-efficient and digitally integrated bridge systems is creating pressure on suppliers to demonstrate total cost of ownership advantages rather than relying solely on upfront price competitiveness. These factors are not isolated; they interact with each other and with regional demand patterns, making it increasingly important for participants to align product roadmaps with operational realities and procurement environments.
Core Drivers Reshaping the Market
Technology innovation is one of the most visible forces altering buyer expectations and supplier positioning. Electro-mechanical boarding bridges are gaining traction over hydraulic designs because they offer measurable reductions in energy use and long-term maintenance intensity. This shift is not simply a preference for newer architectures; it reflects a broader operational logic in which airports and ground handlers are evaluating lifecycle costs more carefully, especially where energy prices, labor availability, and service intervals affect total operating economics. Automated docking features, improved safety systems, and more responsive control interfaces are also becoming differentiators, allowing operators to reduce manual intervention, improve turnaround predictability, and support higher gate utilization. As these capabilities mature, the market is gradually rewarding suppliers that can integrate mechanical reliability with system-level intelligence rather than selling bridge hardware in isolation.
Policy and regulatory environments are acting as another important catalyst. Public funding programs and airport infrastructure grants are channeling capital into bridge replacement and installation projects, particularly in markets where aging gate infrastructure has become a constraint on capacity and service quality. In the United States, for example, substantial grant allocations have been directed toward airport improvement programs that include passenger boarding bridge replacements and installations across a broad set of airports. This type of support can accelerate project timelines and broaden the pool of funded modernization activity. At the same time, procurement rules are introducing additional layers of complexity. Project-specific Buy American waivers issued in 2025 and 2026 for certain boarding bridge projects illustrate how regulatory compliance and sourcing flexibility can intersect, creating both opportunities and eligibility constraints for suppliers. The practical implication is that policy support is expanding demand in specific segments, but it also requires participants to navigate funding conditions, documentation requirements, and local content expectations with precision.
Demand-side behavior is changing as well, shaped by airport capacity strategies and passenger experience priorities. Commercial airports remain the dominant application setting because they handle the highest traffic volumes and the broadest mix of aircraft types, making boarding bridge performance a direct factor in gate throughput and passenger flow. Airports are increasingly treating boarding bridges not as passive connectors between terminal and aircraft, but as active components of the gate ecosystem, where reliability, turnaround speed, and compatibility with evolving aircraft interiors influence customer satisfaction and operational planning. Regional airports, by contrast, tend to prioritize simpler deployment economics, durability, and maintainability, often favoring solutions that can serve limited gate configurations without excessive complexity. These differing demand profiles mean that product positioning, service offerings, and financing approaches must be tailored to the operational realities of each airport segment rather than applied uniformly.
PW Consulting Automotive & Machinery Research Center
Supply chain and cost structures are adding further nuance to market dynamics. Steel-walled designs have retained a strong share of sales due to their ruggedness, lower initial cost, and compatibility with a wide range of climatic and operational conditions. This preference underscores a pragmatic approach among many buyers, especially where durability and first-cost control remain decisive. At the same time, the broader shift toward electro-mechanical platforms is gradually reshaping component sourcing, maintenance planning, and service models. Suppliers that can manage raw material exposure, standardize high-demand configurations, and provide predictable lifecycle support are better positioned to navigate cost pressure while preserving margin stability. The market is therefore rewarding a blend of engineering robustness and operational predictability, particularly in environments where project timelines, installation complexity, and long-term service commitments influence winning bids.
Competitive Landscape and the Evolution of Winning Strategies
The competitive field includes a mix of established global suppliers and specialized operators with distinct regional footprints and product emphases. Several companies have built their positioning around integrated gate infrastructure capabilities, combining boarding bridge systems with automated docking, ground support equipment, or broader terminal interface solutions. Others differentiate by focusing on refurbed equipment, component-level innovation, or airport-specific delivery track records that emphasize installation reliability and after-sales support. The strategic common thread among stronger players is a move toward solution-oriented value propositions: rather than competing primarily on unit price, leading suppliers are aligning their offerings with gate performance, maintenance efficiency, compatibility with aircraft mixes, and the ability to support both new installations and lifecycle refurbishment.
A notable aspect of the current landscape is the way recent project activity and exhibition presence reinforce market positioning. Suppliers that maintain visible engagement with airport operators through project deliveries and industry events are better able to demonstrate execution capability and keep their product roadmaps aligned with procurement realities. For instance, the delivery and installation of multiple passenger boarding bridges at a major terminal expansion project illustrates how targeted installations can validate a supplier’s ability to support capacity growth while meeting airport-specific integration requirements. Similarly, continued participation in major airport trade events allows suppliers to showcase complete bridge systems alongside individual components, signaling both system-level competence and flexibility for partial upgrades or component replacement. These activities matter because airport procurement is often influenced by demonstrated project experience, local installation capability, and the supplier’s ability to support the asset over its service life.
Market concentration remains relatively high, indicating that a limited number of participants command a significant share of revenue. This concentration creates a competitive environment where scale, global installation experience, product breadth, and service networks can serve as meaningful barriers. At the same time, the market is not closed to focused entrants or specialists that can address specific airport needs, such as refurbishment, component innovation, sustainability-oriented upgrades, or regional deployment expertise. As a result, the landscape is evolving through a combination of consolidation among larger players and targeted competition from firms with differentiated technical or commercial approaches. Suppliers that can combine engineering consistency with strong service execution, and that can adapt to regulatory and funding conditions in key markets, are likely to strengthen their position over the forecast period.
Worldwide Military Floating Bridge Market
Looking Ahead: Trends That Will Shape the Next Three to Five Years
One of the clearest forward-looking trends is the continued migration from hydraulic to electro-mechanical boarding bridges as operators prioritize energy efficiency and reduced maintenance exposure. This transition is likely to accelerate where airports face pressure to manage operating costs, improve sustainability performance, and standardize equipment across multiple gates. The commercial opportunity lies not only in new installations but also in retrofit and upgrade pathways that allow airports to modernize existing assets without full replacement. Suppliers that can offer credible conversion strategies, predictable service outcomes, and compatible control architectures will be well placed to capture demand across both new builds and refurbishment cycles.
A second trend is the growing importance of automated docking, safety systems, and gate-level integration as airports seek more predictable turnaround performance and reduced manual handling risk. As these capabilities become more standardized, differentiation may shift toward reliability under high utilization, interoperability with airport operating systems, and the ability to support mixed aircraft configurations without sacrificing deployment speed. This creates opportunities for suppliers that can package mechanical performance with digital control features in a way that aligns with airport operational planning. The risk, however, is that over-engineering or complexity could raise installation costs and maintenance burdens, particularly for regional airports that value simplicity and durability over advanced automation.
A third trend concerns the influence of funding mechanisms and procurement policy on project visibility and supplier eligibility. Infrastructure grants and airport improvement programs are expected to keep replacement and modernization activity active in several key markets, but the rules attached to such funding can vary by project and location. Where local content expectations or Buy American-type conditions apply, suppliers may need to demonstrate supply chain compliance, domestic sourcing pathways, or partner-based delivery models to remain competitive. This dynamic creates both opportunity and uncertainty. It can open doors for suppliers with the right compliance posture and installation footprint, while simultaneously constraining participation for firms that cannot meet localized procurement requirements. Participants should therefore treat policy and funding environments as strategic variables, not background conditions, and build procurement readiness into their commercial planning.
Strategic Actions for Decision-Makers
For manufacturers and equipment suppliers, the priority is to strengthen total-cost positioning rather than compete solely on initial price. This means investing in electro-mechanical architectures where they are gaining acceptance, standardizing high-demand configurations such as steel-walled designs that continue to dominate sales for practical reasons, and building service models that support both new installations and refurbishment. Suppliers should also map their compliance and sourcing capabilities against the funding and procurement rules that shape key airport projects, since eligibility can be as important as technical performance in winning bids. Differentiation is increasingly tied to demonstrated installation execution, component reliability, and the ability to support airports through the full asset lifecycle.
For investors, the market offers a profile of steady growth with selective opportunities in modernization, automation, and refurbishment-driven demand. The most attractive exposure is likely to come from participants that can balance scale with segment-specific relevance, maintain strong service and installation capabilities, and adapt product offerings to shifting technology preferences. Investors should pay close attention to how suppliers position themselves against regulatory and funding conditions, because project-level policy changes can influence order timing, market access, and margin dynamics. Monitoring which companies are strengthening their presence through project deliveries, trade engagement, and component-level innovation can provide early signals about competitive momentum.
For airport operators and procurement teams, the strategic focus should be on aligning bridge selection with operational priorities and lifecycle economics. Where gate utilization, turnaround consistency, and energy cost matter most, electro-mechanical solutions with automated docking and improved safety features may deliver value beyond upfront price. Where durability, simplicity, and first-cost control are paramount, steel-walled configurations and proven mechanical designs remain compelling. Procurement planning should also account for installation complexity, local service availability, and any funding-related eligibility requirements that may affect supplier selection. A structured evaluation framework that integrates technical performance, maintenance expectations, and regulatory conditions will support more resilient purchasing decisions.
For decision-makers seeking more detailed segmentation data, regional considerations, and project-level dynamics, deeper intelligence can provide the granularity needed to translate these trends into concrete plans. The Passenger Boarding Bridge Market Landscape 2026–2032 and related PW Consulting research materials are available for teams that require more detailed breakdowns across type, model, technology, structure, application, and regional demand patterns, along with customized guidance for specific market or procurement scenarios.
Worldwide Airport Furniture Market
For detailed analysis of this topic, please visit the official page: Passenger Boarding Bridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com