

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global Peeling Machines Market to Hit $557.5M by 2032 at 5.45% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global Peeling Machines Market: Strategic Intelligence for Agribusiness Leaders in 2026
Executive Overview
The global peeling machines market stands at a critical inflection point as 2026 unfolds, shaped by accelerating automation adoption, evolving food safety mandates, and shifting raw material economics. After a decade of steady valuation growth, the sector now presents a complex interplay of technological innovation, regional capacity shifts, and competitive realignment that demand careful strategic navigation by equipment manufacturers, food processors, and supply chain investors.
Our latest Worldwide Peeling Machines Market analysis delivers a comprehensive, data-grounded assessment designed specifically for executives who must calibrate capital allocation, product roadmaps, and partnership strategies across the forecast horizon of 2026 through 2032. This article outlines the strategic architecture of the study, explains how its framework translates into actionable decision-making, and highlights the critical intelligence layers that separate reactive operations from market-defining positioning.
Market Trajectory and Structural Momentum
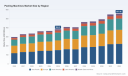
The worldwide peeling machines industry has demonstrated consistent expansion over the past half-decade, with market valuation climbing from approximately USD 298 million in 2020 to an estimated USD 384.5 million by 2025. This progression reflects enduring demand across plant-based and protein processing supply chains, compounded by incremental upgrades in throughput efficiency and hygiene compliance. Entering 2026, the market is positioned at USD 409.17 million, and our baseline trajectory projects sustained growth through the end of the forecast window, reaching roughly USD 557 million by 2032.
The compound annual growth rate across the 2026-2032 period is estimated at 5.45 percent, a figure that captures more than simple volume expansion. It reflects a transition toward higher-value processing configurations, where conventional mechanical designs are increasingly supplemented by sensor-guided, abrasive, and ultrasonic alternatives. In practical terms, the growth vector is not merely about deploying more units; it is about deploying smarter installations that reduce waste, improve food safety profiles, and compensate for tightening labor availability across commercial kitchen, contract manufacturing, and industrial scale environments.
Strategic planners should note that the 2025-2026 transition reveals a market that has absorbed earlier pandemic-era disruptions, logistics volatility, and equipment lead-time constraints. Current operating conditions are more normalized, but they are being re-shaped by a different set of forces: raw material pricing behavior, regional capacity realignment, and intensifying differentiation among technology providers. The report frames these dynamics not as isolated variables, but as interconnected levers that influence pricing architecture, procurement cycles, and service expectations throughout the value chain.
Technology Portfolio Shifts and Input Cost Realities
Within the equipment landscape, steam-based peeling systems continue to command substantial share by value, supported by their suitability for high-throughput environments and established operational familiarity. Abrasive and knife-based configurations remain important complements, each addressing distinct product shapes, skin characteristics, and throughput requirements. Chemical-based solutions occupy a smaller but strategically meaningful position, often leveraged where uniform skin removal and gentle handling are prioritized over maximum mechanical speed. The report maps these technology categories to processing realities rather than treating them as abstract categories, allowing readers to evaluate where certain mechanisms align with specific use cases, labor profiles, and sanitation protocols.
A crucial layer of analysis concerns material economics. Stainless steel remains the dominant construction material for food-grade peeling machinery due to its corrosion resistance, cleanability, and compatibility with stringent sanitary design expectations. Early 2026 pricing intelligence indicates that stainless steel in Northeast Asia was trading near USD 1.79 per kilogram in March 2026, with the broader global stainless steel market projected to approach USD 146.1 billion in the same year. Prices across the first quarter of 2026 stayed range-bound with a slight upward bias in select regions, influenced by steady industrial demand and alloying element cost behavior. These material dynamics matter because they feed directly into unit economics, retrofit decision timing, and the cost advantage calculus between refurbishing legacy lines versus specifying newer builds.
At the same time, regulatory expectations around hygienic design and easy-to-clean surfaces continue to reinforce the case for food-grade materials and integrated sanitary engineering. This is not simply a compliance issue. In many procurement environments, sanitation performance and cleaning cycle efficiency are becoming as influential as throughput metrics, particularly where processors are consolidating lines to maximize utilization and reduce downtime. Our analysis treats these operational pressures as core drivers of specification choices, not peripheral considerations.
Competitive Landscape and Differentiation Battles
The market is moderately concentrated, with three leading players accounting for a combined share of approximately 42.15 percent and the top five collectively representing around 58.6 percent. Concentration at this level indicates a landscape where scale, established distribution networks, installation expertise, and after-sales service can confer meaningful advantages. At the same time, the presence of numerous specialized manufacturers ensures that niche capability, regional responsiveness, and application-specific innovation remain viable competitive entry points.
Several names illustrate the breadth of competitive strategies currently in play. Sormac B.V., based in the Netherlands, develops and manufactures peeling machines for a wide fruit and vegetable assortment including potatoes, beets, celery, carrots, melons, watermelons, pumpkins, and cucumbers. Its product range includes knife peelers and specialized configurations such as CBS/MBS and UP-4000 series, with recent live demonstrations at a January 2026 trade show highlighting melon, onion, and vegetable peeling models. ASTRA Inc., headquartered in Japan, focuses on automatic fruit peeling machines optimized for apples, citrus, kiwi, orange, mango, and pineapple, emphasizing fast and high-quality results across formats like the KA-700H, KA-750PM, and FAP series, including a July 2025 release of an industrial pineapple peeler and corer built for simultaneous high-speed peeling and coring.
Other participants reflect different strategic emphases. Vanmark Equipment LLC, operating from the United States, manufactures potato and produce processing equipment spanning peelers, washers, and complete lines for chips, fries, and vegetable processing. TOMRA Food, based in Norway, provides advanced peeling and sorting solutions that leverage laser-based and sensor technologies for high-capacity automated processing. Hobart, also US-based, supplies commercial kitchen equipment including potato and vegetable peelers for professional foodservice. Dornow Food Technology GmbH, in Germany, provides abrasive and knife peeling machines and complete plants for potatoes and vegetables at various scales, while FAM, from Belgium, is regarded as a global leader offering innovative peeling solutions including ultrasonic approaches. Additional contributors such as Finis-Eillert, JBT Corporation, Electrolux Professional, Sammic, Metos, Boema SpA, Herbort Food Production Machinery, FROSFOOD, Fujimak Corporation, and others expand the competitive field with regional strengths and application-specific ingenuity.
Recent activity shows that exhibition presence and timely new product introductions remain important market-shaping tools. Participation at major industry events in early 2026, alongside launches of higher-speed or application-specific machines during the prior year, signals that firms are actively competing on throughput, precision, hygiene, and ease of integration rather than on price alone. The report uses these developments not as isolated news, but as indicators of where competitors are betting on future demand and how their positioning may influence procurement negotiations, replacement cycles, and service expectations.
Application Realities and Operational Decision Drivers
From an application standpoint, fruit and vegetable processing continues to be the largest demand center, reflecting the breadth of fresh-cut, ready-to-eat, and processed produce categories. Root and tuber processing represents another significant demand cluster, driven by the scale of potato, tuber, and root-based product pipelines that include fresh-cut items, chips, fries, and downstream processed goods. Seafood and meat processing, while smaller in relative terms, remains strategically relevant where precise skin, scale, or surface preparation is necessary to standardize yield and presentation. An additional set of miscellaneous applications rounds out the portfolio, often tied to specialized formats and mixed-product environments.
Depaneling Machine Market
Rather than presenting these categories as static share splits, the analysis connects them to procurement behavior. Different applications impose different requirements on peeling uniformity, waste reduction, changeover flexibility, sanitation, and maintenance intensity. A processor scaling output for fresh-cut produce may prioritize gentle handling and appearance consistency, while a high-volume fry or chip operation may value durability, line integration, and labor reduction above all else. The report’s framework is designed to help decision-makers translate these application-level needs into equipment specifications, service arrangements, and technology mix choices.
Automation trends are intensifying across the sector, largely as processors seek to offset labor shortages and improve throughput predictability. This shift supports demand for efficient peeling machines incorporating advanced knife, abrasive, and sensor-based technologies. Where automation is implemented thoughtfully, it can reduce variability, improve food safety outcomes, and free skilled labor for oversight and exception handling. Where it is implemented without proper integration planning, it can create hidden costs in cleaning, maintenance, and changeover. The study examines these tradeoffs explicitly so that capital planning is informed by operational reality rather than by automation as an abstract goal.
Why This Study Matters for 2026 Strategy
Time-sensitive capital and supply chain decisions are already being made across the industry, whether in the form of line expansion, technology retrofitting, regional sourcing adjustments, or supplier evaluation. In that environment, a well-structured market study functions less as a general reference and more as a decision support system. The Worldwide Peeling Machines Market report is designed to provide several practical outputs:
Core Report Contents Designed for Execution
- A structured assessment of market size evolution from 2020 through 2032, with the 2025 base year and 2026-2032 forecast anchored to observed historical behavior and forward-looking sector dynamics.
- An integrated view of technology categories, application contexts, and regional demand patterns, presented so that procurement, product development, and market entry teams can compare alternatives without relying on oversimplified aggregates.
- Competitive profiling that extends beyond corporate descriptions to address positioning, product emphasis, application specialization, and recent market-facing activity, including trade show presence and product introductions.
- Contextual analysis of material economics, hygienic design requirements, and automation trends as they affect equipment specification, total cost of ownership, and replacement timing.
- Decision-oriented framing that links macro trends to practical questions: which configurations are likely to be favored in high-throughput processing environments, how sanitation and labor pressures influence specification, and where differentiated capability can support pricing and retention.
What makes the study particularly relevant for 2026 is its timing. Market participants are operating in a period where demand is no longer simply rebounding from earlier disruption; it is being re-shaped by structural factors such as labor availability, hygiene expectations, material pricing, and the push toward more integrated, sensor-informed processing systems. The analysis is built to help executives interpret those forces in combination rather than in isolation, allowing them to assess not just what is happening, but what it implies for budgets, vendor selection, capacity planning, and competitive posture over the next several years.
Intelligence That Connects to Action
Executives rarely need more data for its own sake; they need better synthesis. The report is structured to support questions that arise in real decision cycles: whether to standardize on a particular peeling technology family across multiple facilities, how to evaluate suppliers with different regional support footprints, where material cost trends may affect the timing of retrofit versus replacement, and how to interpret competitor moves in exhibitions and new product announcements as signals of future competitive intensity.
The competitive analysis, for example, is built to help readers understand that scale advantage and specialization advantage are not mutually exclusive. Larger players may benefit from broader parts and service coverage, while specialized manufacturers may win on application fit, changeover speed, or unique peeling behavior for specific product types. The presence of multiple firms with overlapping yet distinct capabilities suggests a market where procurement teams can negotiate meaningfully, but only if they have a clear internal view of the performance attributes that matter most to their operations. The report supplies that interpretive structure.
Similarly, the material and regulation context is not presented merely as background information. Instead, it is linked to practical implications. If stainless steel pricing remains range-bound with periodic upward pressure where industrial demand and alloying costs persist, then budgeting for equipment, spare parts, and service contracts should account for input variability rather than assume flat cost assumptions. If hygienic design and easy-to-clean surfaces are increasingly important in specification reviews, then total cost of ownership calculations must give appropriate weight to sanitation time, cleaning chemical usage, and maintenance labor, not only to the initial purchase price. The study connects these factors so that financial and operational teams can plan on a consistent basis.
Accessing the Full Strategic Picture
A preview can indicate capability, but it cannot replace the complete evidentiary architecture. The full report contains the detailed market segmentation, forecast tables, competitive profiles, company-level recent developments, and contextual analysis necessary for a rigorous strategic review. It also includes the granular comparisons and interpretive guidance that allow readers to move from macro awareness to specific procurement, investment, and product decisions. Because the study deliberately focuses on presentation logic and decision relevance, the complete version is the appropriate instrument for teams that must defend recommendations to internal stakeholders, set multi-year plans, or assess supplier and partner options with confidence.
Worldwide Peeling Machines Market
For organizations active in food processing equipment, contract manufacturing, produce and tuber supply chains, or industrial automation-enabled kitchen environments, the worldwide peeling machines market in 2026 is not a peripheral concern. It is a functional node within broader issues of yield, hygiene, throughput, labor strategy, and capital efficiency. The report is designed to give decision-makers a clearer line of sight into those connections, with enough analytical discipline to support action across the 2026-2032 horizon.
To access the full dataset, detailed segmentation, competitive dossiers, and contextual analysis referenced here, visit the source page for the complete Worldwide Peeling Machines Market report and secure the complete intelligence package required for 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide Peeling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: D&O Insurance Market Hits $25.2B in 2025, Projects 7.64% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Evolving Landscape of D&O Insurance: Strategic Imperatives for 2026
The Directors and Officers (D&O) insurance market stands at a critical inflection point. As corporate governance faces unprecedented scrutiny from regulators, shareholders, and the public, the liability protection afforded to board members has never been more vital—or more complex. PW Consulting's latest comprehensive market research on the D&O Insurance sector provides decision-makers with the intelligence needed to navigate this shifting terrain with confidence. This report arrives at a moment when strategic foresight regarding insurance procurement, risk mitigation, and governance structures can meaningfully differentiate resilient organizations from those exposed to emerging liabilities.
The global D&O insurance market has demonstrated remarkable growth trajectories over the past half-decade. From a base of approximately 17.24 billion USD in 2020, the market expanded to 25.2 billion USD by 2025, reflecting a compound annual growth rate of 7.64 percent through the forecast period extending to 2032. This sustained expansion is not merely a function of nominal economic growth; it reflects deepening awareness of director liability, increasingly litigious environments, and the materialization of risks that were once theoretical. Looking ahead, the market is projected to reach 42.19 billion USD by 2032, suggesting that D&O coverage will remain a cornerstone of corporate risk management frameworks for the foreseeable future.
For directors, officers, and corporate secretaries, these macro-level figures translate into tangible decisions about coverage adequacy, policy structure, and carrier relationships. The 2026 outlook, in particular, demands attention. After several years of market hardening and premium volatility, indications point toward stabilization, yet the underlying risk environment continues to evolve in ways that require sophisticated interpretation. Our research unpacks these dynamics with the granularity necessary for informed decision-making, while providing the strategic context that generic market summaries cannot deliver.
Market Dynamics: Stabilization Amid Escalating Liability Risks
The D&O marketplace in 2026 presents a nuanced picture. Broad market assessments from rating agencies and industry analysts describe a stabilization pattern, with moderate rate adjustments and disciplined underwriting becoming the norm. This represents a meaningful shift from the turbulence of prior years, yet stabilization should not be mistaken for complacency. Several structural forces are simultaneously compressing and expanding the liability landscape, and boards must understand how these forces intersect with their specific organizational profiles.
One of the most significant developments concerns the rising tide of business insolvencies globally. Projections indicate that insolvencies will increase by approximately 5 percent in 2026, pushing levels 24 percent above pre-pandemic averages. This trend carries direct implications for D&O exposures, particularly in sectors such as automotive, construction, and retail, where financial distress often triggers shareholder actions, creditor claims, and regulatory investigations. Directors overseeing organizations in these vulnerable industries face heightened scrutiny, and the availability of robust D&O protection becomes a critical component of succession planning and risk transfer strategies.
Cyber Insurance Market
Complementing the insolvency narrative is the evolving profile of securities litigation. Median settlements in US securities class actions rose 21 percent in 2025, reaching 17 million USD. This escalation reflects not only larger claim values but also the expanding scope of alleged wrongdoing. Regulatory and geopolitical shifts have broadened the perimeter of what constitutes actionable director conduct, and plaintiffs' attorneys are increasingly aggressive in leveraging these expanded definitions. For boards, the implication is clear: defense costs and settlement exposures are growing faster than general inflation, and policy limits that appeared sufficient yesterday may prove inadequate tomorrow.
The cost of legal defense itself has become a material concern. Cumulative legal services inflation has risen 44 percent since 2020, directly eroding the effectiveness of retention layers and pushing more claims into higher coverage tiers. This dynamic affects the economics of D&O programs across the board, from public companies with extensive indemnification obligations to private enterprises where directors may face personal liability without the shield of corporate resources. Our research examines how these cost pressures are reshaping policy structuring, retention decisions, and the broader calculus of risk bearing.
Simultaneously, the sources of potential director liability are diversifying. Artificial intelligence oversight, ESG compliance, and geopolitical risk management have emerged as focal points for claims activity. Directors are now expected to demonstrate competence in areas that were peripheral to traditional corporate governance just a few years ago. Failure to exercise appropriate diligence in these domains can expose individuals to allegations of breach of fiduciary duty, and carriers are increasingly scrutinizing board composition and expertise during underwriting. This evolving expectations landscape makes it essential for organizations to align their governance practices with the risk appetite communicated in their insurance applications.
Competitive Landscape: Carriers Adapting to a New Risk Era
The D&O insurance market is characterized by a moderately concentrated competitive structure, with the top three carriers commanding approximately 32 percent of market revenue and the top five approaching 47 percent. This concentration suggests a market where scale, brand reputation, and underwriting sophistication confer advantages, yet ample room remains for specialized and regional players to differentiate through niche expertise and tailored solutions. Understanding the strategic positioning of major carriers is essential for organizations evaluating their insurance partners and negotiating coverage terms.
Chubb, with its multinational footprint spanning over 40 countries, exemplifies the comprehensive approach that global organizations require. Its portfolio encompasses Side A coverage and tailored solutions for public, private, and nonprofit entities, with a pronounced emphasis on governance and securities claims. For boards operating across multiple jurisdictions, Chubb's ability to deliver locally compliant policies within a unified framework represents a strategic advantage that simplifies administration while maintaining protection consistency.
AIG continues to provide D&O liability solutions that address the full spectrum of claims sources, from shareholder actions to competitor disputes and regulatory challenges. Its specialized product lines for public companies, private companies, and nonprofits reflect a granular understanding of how liability exposures differ across organizational structures. This segmentation matters because a private company's D&O needs—where personal asset protection often dominates—differ materially from those of a publicly traded entity facing securities class action exposure.
Travelers Insurance delivers coverage for defense costs, settlements, and judgments arising from management decisions and wrongful acts, serving public, private, and nonprofit clients. Its brand strength and claims handling reputation make it a frequent consideration for organizations seeking a balance of breadth and reliability. Liberty Mutual, through its Ironshore platform, extends D&O liability solutions designed for complex risks across varied company structures, emphasizing protection for leaders against claims stemming from management actions.
Allianz has positioned itself at the intersection of traditional D&O coverage and emerging risk categories. Its offerings address geopolitical, cyber, and regulatory risks, reflecting an insights-driven approach suited to boards confronting evolving liabilities. The December 2025 release of its D&O Insurance Insights 2026 report underscores this focus, highlighting the interplay of geopolitics, cyber threats, tariffs, and rising insolvency impacts on director liabilities. For organizations whose risk profiles extend beyond conventional governance concerns, Allianz's expanded perspective offers valuable alignment.
Zurich Insurance Group supplies D&O liability coverage with particular strength in multinational and mid-sized company segments, focusing on management and professional liability exposures. AXA XL, as part of the broader AXA Group, contributes specialized financial lines products with coverage enhancements designed for emerging risks. Beazley has built a reputation for D&O and management liability insurance with particular depth in cyber-exposed and specialty risk segments, making it a relevant consideration for technology-intensive and highly regulated organizations. Hiscox serves small to mid-sized businesses and specialized sectors, providing accessible solutions that address the D&O needs of organizations that may not command the attention of larger carriers. Berkshire Hathaway Specialty Insurance leverages its substantial financial backing to offer robust D&O coverage capable of supporting high-limit and complex risk scenarios, appealing to organizations with significant exposure profiles.
The recent developments among these and other industry participants illustrate how the market is responding to 2026 realities. WTW's February 2026 market outlook emphasized premium stabilization, AI oversight expectations, bankruptcy risk considerations, and securities litigation forecasts, providing a forward-looking framework that boards can use to benchmark their own risk assessments. Baldwin's January 2026 public company D&O outlook noted that favorable terms are continuing into 2026, with pricing stabilization expected to persist. AM Best's revised U.S. D&O outlook to stable, citing moderate rate decreases, low loss ratios, and stricter underwriting, reinforces the narrative of a market finding its footing while maintaining discipline. These complementary perspectives form a mosaic that our research synthesizes into actionable guidance.
Report Structure and Practical Utility
PW Consulting's D&O Insurance Market research is structured to deliver immediate operational value alongside long-term strategic insight. The report begins with a comprehensive market overview that contextualizes historical performance from 2020 through 2025 and projects forward through 2032. This temporal scope allows readers to identify inflection points, assess the durability of recent trends, and distinguish cyclical fluctuations from structural shifts.
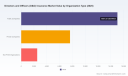
The segmentation analysis examines the market across multiple dimensions critical to procurement decisions. Coverage type breakdowns illuminate how Side A, Side B, and Side C protections are distributed across the market, helping organizations understand which coverage components are most competitive and where gaps may exist in their current programs. Organization type segmentation distinguishes among public companies, private companies, and nonprofit organizations, recognizing that each category faces distinct liability profiles and insurance requirements. Regional analysis provides a geographic lens that supports multinational organizations in coordinating coverage strategies across jurisdictions while acknowledging local market characteristics.
Competitive profiling extends beyond basic company descriptions to evaluate strategic positioning, product capabilities, and movement in response to market conditions. The analysis of recent developments—capturing carrier reports, market outlooks, and rating agency assessments from late 2025 through early 2026—ensures that the competitive picture reflects the most current intelligence available. This timeliness is essential because the D&O market can shift rapidly in response to loss experience, regulatory changes, and macroeconomic pressures.
The report's examination of industry context integrates regulatory developments, macroeconomic trends, and sector-specific risk factors into a cohesive narrative. The projected rise in global business insolvencies, the escalation of securities settlement values, the cumulative impact of legal cost inflation, and the emergence of AI and ESG oversight as liability vectors are all analyzed for their implications on D&O purchasing strategies. By connecting these disparate threads, the research enables boards and risk managers to anticipate rather than merely react to changing conditions.
Practical tools within the report support concrete decision-making. Guidance on policy structuring in an environment of stabilized but still elevated costs helps organizations optimize retention levels and coverage limits. Analysis of carrier appetites and underwriting trends informs negotiations and carrier selection. The competitive benchmarking framework allows organizations to assess whether their current programs reflect market standards or represent opportunities for improvement.
Strategic Decision-Making in 2026
The strategic value of this research lies in its capacity to transform market intelligence into boardroom action. As the D&O market stabilizes, organizations face a window of opportunity to re-evaluate their protection frameworks with less pressure than existed during periods of rapid premium escalation. This is the moment to audit current coverage adequacy against the evolving risk landscape, to assess whether policy structures align with organizational realities, and to engage carriers in conversations about emerging exposures that may not yet be reflected in standard underwriting questionnaires.
For public companies, the stabilization of pricing and the continuation of favorable terms into 2026 create conditions conducive to optimizing coverage without the urgency that characterized prior market cycles. Yet the underlying pressures—rising settlement values, legal cost inflation, and expanding liability theories—mean that optimization must be grounded in realistic loss scenarios rather than nominal premium considerations. Private companies, particularly those with growth trajectories or exposure to insolvency-sensitive sectors, should use this period to strengthen personal asset protection and ensure that indemnification arrangements are supported by adequate insurance backing. Nonprofit organizations, often overlooked in D&O discussions, face increasing expectations around governance and compliance, and our research addresses the specific considerations that apply to their risk profiles.
The research also supports longer-term strategic planning. As organizations look toward 2027 and beyond, the projected market trajectory suggests continued growth in D&O demand, driven by both expanding liabilities and increasing awareness of the need for protection. Boards that establish robust governance-insurance linkages now will be better positioned to manage the premium and coverage negotiations of future cycles. Understanding the competitive dynamics among carriers, the segmentation of market demand, and the macroeconomic forces shaping liability trends provides the foundation for resilient D&O strategies.
Access the Complete Intelligence
This overview has outlined the strategic context, market dynamics, competitive landscape, and practical applications that define the D&O insurance environment in 2026. The commentary provided here offers a substantive introduction to the themes and trends shaping the market, but the complete research deliverable contains detailed segmentation data, granular competitive analysis, forward projections, and actionable frameworks that cannot be fully replicated in a summary format.
Directors and Officers (D&O) Insurance Market
PW Consulting's Directors and Officers (D&O) Insurance Market research is designed for directors, officers, risk managers, corporate secretaries, and insurance procurement professionals who require more than surface-level market commentary. The full report provides the depth necessary to support policy decisions, carrier negotiations, governance enhancements, and risk transfer strategies with confidence. To access the complete intelligence—including detailed market sizing, segmentation insights, competitive benchmarking, and forward-looking analysis—visit the source webpage and obtain the full research deliverable. In a market where the difference between adequate and inadequate protection can have profound consequences for both organizations and individuals, comprehensive intelligence is not a luxury; it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Directors and Officers (D&O) Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Tissue Dispensers Market to Reach $2,554.55M by 2032, CAGR 5.25%
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Wave: Inside the Worldwide Tissue Dispensers Market 2026–2032
As organizations recalibrate their facility management strategies for the mid-2020s, the commercial washroom ecosystem is undergoing a quiet but decisive transformation. Tissue dispensers, long treated as commoditized fixtures, are now central to conversations around hygiene compliance, operational efficiency, and sustainability accountability. Our newly released Worldwide Tissue Dispensers Market research delivers a comprehensive, forward-looking blueprint for executives who must allocate capital, select partners, and shape product roadmaps in a market that is simultaneously maturing and fragmenting. This article previews the strategic architecture of the study, explains why its 2026 decision-usefulness is timed to current inflection points, and outlines the analytical rigor that will help leadership teams move from reactive procurement to disciplined market positioning.
Why 2026 Is a Defining Moment for Tissue Dispenser Strategy
The market has moved through a clear expansion arc over the past half-decade, with global revenue climbing from approximately 1.38 billion USD in 2020 to an estimated 1.79 billion USD in 2025. That trajectory reflects durable demand across away-from-home environments, where hygiene expectations have structurally reset and facility operators are balancing throughput, restocking labor, and material costs. The study’s forecast window, extending through 2032, projects a compound annual growth rate of 5.25 percent, positioning the sector for sustained, if uneven, expansion. For 2026 decision-making, this midpoint in the cycle matters because it is precisely when early-cycle pricing and capacity decisions begin to lock in margin profiles for the remainder of the decade.
Dispenser Pump Market
The research is built to help executives interpret that growth with precision rather than noise. Instead of presenting a single headline figure, the analysis decomposes the market across product architectures, end-user environments, operational modes, and geographic footprints, then cross-ties those dimensions to procurement cycles, compliance calendars, and channel dynamics. The result is a decision framework that can be applied to capacity planning, vendor evaluation, pricing strategy, and risk hedging. Readers who engage with the full study will find the underlying segment dimensions, regional intensity patterns, and end-user share structures laid out in a form that can be directly plugged into internal budgeting and sourcing models.
What the Research Delivers: A Practical Toolkit for Market Entry, Expansion, and Defense
The study is organized around four interlocking workstreams, each designed to translate market structure into actionable next steps.
- Macro trajectory and scenario mapping. The report grounds its forward view in a multi-year historical base and then stress-tests the 2026–2032 outlook against alternative demand pathways. This allows leadership to evaluate how shifts in commercial real estate utilization, hospitality occupancy, healthcare throughput, and public-sector budgeting could reshape volume and value over the forecast horizon.
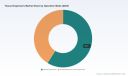
- Segment intelligence without blind spots. The analysis dissects the market by product type, including paper towel, toilet paper, napkin, and facial tissue dispensers; by end user, spanning commercial and office buildings, hospitality and tourism, healthcare facilities, and industrial and education environments; and by operation mode, contrasting manual units with automatic and sensor-based systems. Rather than stopping at descriptive splits, the study examines how these segments interact with pricing power, restocking frequency, vandal resistance requirements, and retrofit economics.
- Competitive and channel depth. A structured assessment of incumbent positioning, product architecture differentiation, and go-to-market tactics helps buyers and suppliers alike understand where differentiation is real and where it is largely cosmetic. The report also incorporates recent product launches and innovation announcements, giving readers a current read on how major players are pulling the market toward higher-capacity, touchless, and modular configurations.
- Regulatory and input-cost context. Because dispenser economics are inseparable from tissue supply and packaging accountability, the study embeds material cost signals and policy developments into its market logic. This includes producer price index behavior for sanitary tissue paper products, evolving extended producer responsibility frameworks across multiple U.S. states, and the influence of standardized testing protocols on product claims and procurement specifications.
Taken together, these workstreams create a market map that is detailed enough to support investment committee discussions yet structured enough to support rapid scenario comparison. The study deliberately surfaces enough granularity for users to recognize where their own categories sit within the broader landscape, while reserving the most decisive breakdowns for the complete report, where they can be examined alongside methodology notes, source triangulation, and full quantitative exhibits.
Competitive Architecture: Where Differentiation Is Being Won and Lost
The worldwide tissue dispensers market is not a winner-takes-all arena, but it is a disciplined one. Concentration among leading participants remains meaningful, and that concentration shapes pricing expectations, channel leverage, and the speed at which new features propagate. The research profiles a roster of established manufacturers whose strategies reveal the market’s central fault lines: durability versus aesthetics, capacity versus footprint, mechanical simplicity versus automation, and product ecosystem lock-in versus specification neutrality.
In North America, several long-tenured equipment specialists anchor the commercial washroom segment with vandal-resistant, surface-mounted and recessed designs. Bobrick Washroom Equipment, for example, has built its reputation on durable toilet tissue and paper towel dispensers, including touchless and surface-mounted models suited to demanding public environments. American Specialties, Inc. focuses on recessed and surface-mounted multi-roll toilet tissue dispensers and accessories in stainless steel, an approach that appeals to specifiers prioritizing finish consistency and theft deterrence. Palmer Fixture and Alwin Manufacturing both address the high-traffic public restroom segment through jumbo roll tissue dispensers, with ADA-compliant configurations and twin-roll options that reduce change-outs and support throughput. San Jamar contributes controlled-dispensing paper towel and bath tissue solutions, reinforcing the broader industry push toward measured consumption and reduced waste.
Alongside these equipment specialists, tissue manufacturers have expanded into dispensing systems as a way to secure away-from-home channel relevance and bundle value. Georgia-Pacific LLC provides commercial tissue dispensers and dispensing systems under brands such as Pacific Blue Ultra, pairing high-capacity automated and mechanical solutions with its tissue product portfolio. Kimberly-Clark Corporation manufactures professional dispensers including ICON and Scott systems for folded towels, bath tissue, and roll products, with an emphasis on away-from-home settings where branding, hygiene perception, and replacement logistics intersect. Essity AB, operating through its Tork brand, offers professional hygiene dispensers for hand towels, toilet tissue, and coreless systems with a strong sustainability narrative and a focus on high-traffic environments. Cascades Inc. echoes that sustainability-and-performance positioning through its PRO line dispensers and tissue products for away-from-home markets.
The competitive picture also includes specialists in modular commercial fittings and customizable branded hardware. Dolphin Solutions Ltd. supplies modular stainless steel combination paper towel dispenser and waste bin units for recessed mounting, an design-conscious answer to space-constrained commercial interiors. PROvider by WPI focuses on customizable commercial paper towel, tissue, and napkin dispensers, leaning into American-made quality and branding opportunities for facilities that want dispensers to do double duty as visual extensions of their identity.
What makes this roster strategically instructive is not simply who is present, but how recent moves reveal the market’s trajectory. In 2025, Palmer Fixture introduced a premium twin 9-inch jumbo tissue dispenser aimed at high-traffic public restrooms, a signal that capacity, ergonomics, and traffic tolerance remain competitive battlegrounds. Essity expanded its Tork professional hygiene offering with a new toilet paper system designed to complement its towel dispenser portfolio, reinforcing a systems-level approach to restroom efficiency. Kimberly-Clark enhanced its ICON dispenser line with interchangeable configurable faceplates, a reminder that upgrade paths and aesthetic flexibility are becoming important in retrofit-heavy building environments. The study uses developments like these not as isolated news items, but as evidence of how product architecture, service logic, and specification flexibility are being recombined to defend share and open new procurement windows.
Forces Reshaping Demand, Cost, and Compliance
Market performance in this category is increasingly shaped by forces that sit just outside the dispenser itself. Input costs, procurement policy, and standards expectations are converging in ways that alter both pricing and specification behavior. The research integrates these forces so that readers can evaluate demand not only by end-user type, but also by the cost environment that will govern margin and substitution decisions.
On the input side, producer price dynamics for sanitary tissue paper products have become a critical variable for anyone forecasting dispenser-adjacent economics. Recent index readings for sanitary tissue paper products made in paper mills and for those made from purchased sanitary paper stock have pointed to elevated cost levels relative to historical bases. Whether these pressures persist, ease, or propagate differently across product grades will influence tissue availability, bundle pricing, and the attractiveness of high-capacity or coreless systems that can reduce restocking frequency. The study treats these signals as part of the operating context rather than as isolated statistics, connecting them to restocking labor, waste reduction goals, and the economics of automatic versus manual dispensing.
On the regulatory side, extended producer responsibility frameworks are advancing in multiple U.S. states, with legislation in jurisdictions such as California, Colorado, Minnesota, Oregon, and Washington creating new obligations for producers of packaging and paper products. These laws increasingly require producers to fund collection and recycling programs, and some, like Minnesota’s Packaging Waste and Cost Reduction Act, phase in requirements through 2032 while introducing recyclability standards and producer responsibility organization participation. For tissue dispenser markets, the implication is twofold: sourcing and product design decisions must account for downstream accountability, and specification conversations are beginning to include material recoverability and waste management costs alongside traditional criteria like durability and capacity.
Standards also remain a quiet but essential determinant of market credibility. The ISO 12625 series provides standardized test methods and terminology for the physical properties of tissue paper and tissue products used in dispensers, giving buyers and manufacturers a common language for performance claims. In practice, adherence to standardized testing can influence specification acceptance, simplify cross-brand comparisons, and reduce the risk of post-installation dissatisfaction in high-use environments. The study incorporates these standards into its evaluation of product claims and procurement risk, because in a market where operational continuity and hygiene perception both matter, verifiable performance is a competitive asset.
How to Use This Intelligence for 2026 Decisions
The study is designed to support several concrete decision paths. For suppliers and product developers, it clarifies where capacity, automation, and specification flexibility are most likely to command premium positioning, and where commoditization risk is highest. For distributors and facility service providers, it maps the end-user environments and regional intensities that shape restocking rhythm, replacement cycles, and the appeal of sensor-based installations. For commercial real estate, hospitality, healthcare, and education operators, it provides the comparative context needed to evaluate total cost of ownership across manual and automatic options, while anticipating the compliance and material cost dynamics that will affect tissue supply over the forecast period.
Crucially, the research avoids the temptation to flatten the market into a single narrative. It preserves the analytical separation between product architectures, end-user needs, operational modes, and regional conditions so that executives can identify which combinations matter most to their own exposure. That structure is what makes the report useful not just as a market snapshot, but as a decision instrument that can be revisited as assumptions change.
What Remains Inside the Full Study
This preview has outlined the strategic logic, competitive architecture, and macro dynamics that frame the worldwide tissue dispensers market for 2026 planning. To make the analysis fully operational, the complete study goes further. It details the underlying segment breakdowns by region, product type, end user, and operation mode; presents the quantitative context that allows readers to see where value concentrates and how share is distributed among leading participants; and pairs those exhibits with methodological notes and source triangulation so that each conclusion can be traced and challenged. It also extends the competitive review into recent developments, product launch signals, and the operational implications of input-cost and regulatory shifts.
Worldwide Tissue Dispensers Market
For teams that need to move from direction to detail, the full report offers the segment-level precision, competitive benchmarking, and scenario structure required to support sourcing decisions, investment cases, and product roadmap choices. The macro arc, the competitive patterns, and the compliance and cost pressures described here all find their complete expression in the study’s exhibits and commentary. Engaging with the full analysis will give decision-makers the resolution they need to convert market awareness into concrete 2026 action.
For detailed analysis of this topic, please visit the official page: Worldwide Tissue Dispensers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Global Charge Plate Monitor Market Hits $55.21M in 2025, Poised to Reach $80.22M by 2032 at 5.48% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the ESD Control Ecosystem: Inside the 2026 Worldwide Charge Plate Monitor Market
In an era where static sensitivity defines manufacturing yield, the humble charge plate monitor has evolved from a compliance accessory to a critical pillar of electrostatic discharge control infrastructure. Our newly released Worldwide Charge Plate Monitor Market research delivers a comprehensive, forward-looking intelligence framework designed specifically for executive decision-makers, procurement strategists, and engineering leaders navigating the 2026 operating environment. This analysis moves beyond static snapshots to map the structural forces shaping demand, pricing, technological evolution, and competitive positioning across the global ionization verification landscape.
The Strategic Imperative: Why 2026 Demands Heightened Market Intelligence
As electronics miniaturization accelerates and cleanroom protocols tighten across semiconductor, medical device, and aerospace manufacturing floors, the margin for ESD control failure has never been narrower. Charge plate monitors serve as the primary validation instruments for ionizer performance, offset voltage stability, and discharge timing accuracy within ESD Protected Areas. The operational reality of 2026 is that compliance is no longer a box-checking exercise; it is a yield protection mechanism, a cleanroom integrity safeguard, and a supply chain resilience requirement. Decision-makers who lack granular visibility into monitor adoption patterns, standardization shifts, and regional deployment strategies risk misallocating capital, underestimating total cost of ownership, or falling behind competitors who have embedded real-time ionization auditing into their production workflows.
Our research is structured to convert this complexity into actionable strategic clarity. By anchoring executive planning in verified historical trajectories and forward-looking demand modeling, organizations can align product roadmaps, distribution strategies, and compliance investments with the actual velocity of market evolution rather than relying on fragmented vendor claims or anecdotal benchmarking.
Market Trajectory and Structural Growth Signals
The charge plate monitor sector has demonstrated consistent expansion over the past half-decade, reflecting the broader tightening of ESD governance across high-precision manufacturing verticals. Historical revenue tracking from 2020 through 2025 reveals a clear upward path, with baseline valuation expanding from approximately 42.15 million USD to 55.21 million USD by the end of the base year. This trajectory has carried momentum into the early forecast window, positioning the 2026 valuation at roughly 58.78 million USD. The growth pattern is not sporadic; it reflects sustained institutional adoption of standardized ionization verification practices, coupled with incremental upgrades to portable and benchtop instrumentation across mature and emerging production ecosystems.
Looking through the 2026 to 2032 forecast horizon, the market is projected to scale toward 80.22 million USD, underpinned by a compound annual growth rate of 5.48 percent. This moderate-but-durable expansion rate signals a maturing but still actively growing category where volume gains are driven by regulatory reinforcement, broader EPA coverage, and the replacement cycle of legacy verification tools rather than speculative hype. The forecast structure accounts for cross-vertical adoption curves, technology refresh intervals, and the compounding effect of standardized testing methodologies becoming embedded into routine production auditing. For strategic planners, this CAGR represents a reliable baseline for capacity planning, inventory forecasting, and long-term supplier negotiation frameworks.
Segmentation Architecture and Demand Concentration Dynamics
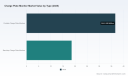
The worldwide market does not expand uniformly. Demand originates from a defined set of instrument architectures and application environments, each with distinct procurement rhythms, technical requirements, and compliance drivers. Portable and benchtop form factors anchor the hardware landscape, with portable units commanding a larger share of the deployment base due to their field-audit flexibility, collapsible configurations, and compatibility with mobile ESD auditing kits. Benchtop platforms serve higher-volume validation and laboratory-grade verification workflows, where controlled measurement conditions and sustained instrument availability drive procurement decisions.
On the application axis, demand is anchored by semiconductor and IC packaging environments, followed by electronic component assembly operations, flat panel display manufacturing, and aerospace and defense production lines. Each vertical imposes different tolerance thresholds, documentation requirements, and audit frequencies, which in turn shape instrument specification preferences, service contract structures, and regional supply chain expectations. The concentration of revenue across these verticals indicates that demand is diversified but not fragmented; a meaningful proportion of total market activity continues to flow through a limited number of high-compliance, high-throughput manufacturing contexts where ionization verification is non-negotiable.
Geographically, the market reflects a multi-pole demand structure. Asia Pacific represents the largest revenue concentration, consistent with the region's dense electronics manufacturing footprint and expanding cleanroom capacity. North America and Europe maintain substantial, structurally stable demand driven by established aerospace, medical device, and discrete semiconductor workflows. Latin America and the Middle East and Africa contribute smaller but strategically relevant shares, often tied to localized assembly expansion, technology transfer initiatives, and incremental EPA standardization efforts. The geographic distribution underscores a practical reality for suppliers and buyers alike: regional compliance cultures, service coverage expectations, and instrument preference profiles vary enough to require localized commercial strategies rather than one-size-fits-all deployment models.
Competitive Landscape: Incumbents, Differentiation, and Strategic Positioning
The competitive environment is defined by specialized instrumentation providers with deep roots in ESD control, ionizer verification, and static elimination technologies. Leading players have built their market positions not on broad consumer visibility, but on technical conformance, field reliability, and alignment with recognized testing protocols. Advanced Energy, operating through its Trek and Monroe instrument heritage, maintains a prominent presence with active charge plate monitors designed for air ionization system evaluation, offset voltage measurement, and discharge time verification. Its portfolio reflects a long-standing emphasis on audit-grade instrumentation for ESD control environments.
Simco-Ion, Technology Group continues to reinforce its standing through charged plate monitors engineered for electrostatic field measurement, ionization need determination, and ionizer performance evaluation across high frequency AC, pulsed DC, and steady-state DC configurations. The inclusion of programmable automated testing capabilities positions its offerings for environments that require repeatable, documentation-rich verification cycles. SCS, operating under Desco Industries, contributes portable charged plate monitor solutions tailored for SMT line ESD control and EPA environments, with emphasis on verifying ionizer offset voltage and discharge timing under production conditions.
Transforming Technologies, frequently referenced through its Warmbier instrumentation lineage, supplies charge plate monitors and ionizer verification meters designed around standardized test methods, reinforcing the link between instrument capability and compliance documentation. Prostat Corporation addresses field audit requirements with portable charge plate monitor assemblies built around compact, collapsible formats and defined capacitance characteristics, making them practical additions to mobile ESD auditing kits. Static Clean International rounds out the competitive field through distribution and supply of handheld charge plate monitors focused on static decay time measurement and ionizer system balance verification.
Collectively, these incumbents illustrate a market where differentiation is achieved through test method alignment, portability versus lab-grade trade-offs, automation depth, and service accessibility. The competitive intensity is not characterized by price wars alone; it is shaped by how effectively each vendor can demonstrate measurement reliability, reduce audit cycle friction, and support compliance documentation workflows across diverse production environments. Market concentration metrics indicate that a relatively small group of leading participants commands a substantial share of total revenue, reinforcing the importance of supplier evaluation criteria that extend beyond unit pricing to include calibration support, replacement part availability, and protocol familiarity.
Worldwide Charge Plate Monitor Market
Regulatory and Technical Dynamics Shaping Procurement Decisions
Standardization remains one of the most powerful demand accelerants in this category. Charge plate monitors are routinely employed to verify ionizer performance in alignment with ANSI/ESD STM3.1 test methods for ionization and ANSI/ESD SP3.3 guidance within ESD Protected Areas. As these protocols become more deeply embedded into internal quality systems and customer audit requirements, procurement teams increasingly prioritize instruments that can reliably support documented compliance rather than ad hoc spot checks. This shift favors solutions that streamline measurement repeatability, simplify data capture, and reduce interpretation ambiguity during audits.
Cold Plate Market
In medical device and life sciences manufacturing, the stakes are amplified by the intersection of ESD control and contamination control within cleanroom environments. Sensitive electronics production in these contexts requires verification tools that can operate consistently under controlled conditions while supporting both static management and broader cleanliness protocols. Instrumentation that aligns with these dual requirements tends to see stronger adoption in facilities where production validation, regulatory readiness, and cleanroom discipline must move in lockstep.
Technical design evolution also continues to influence purchasing behavior. Portable and collapsible monitor designs, including compact plate configurations with defined capacitance characteristics, have expanded the practicality of field auditing by enabling compact storage, rapid deployment, and integration into mobile ESD auditing kits. This trend is especially relevant for electronics and medical device production environments where audit coverage must extend across multiple workstations, ionizer arrays, and transient production zones without compromising measurement consistency. As a result, buyers are increasingly evaluating form factor, deployment speed, and kit integration alongside core measurement performance.
What the Research Delivers: Operational Content for Decision-Makers
This market study is constructed to support real-world strategic planning rather than abstract observation. The report provides a detailed examination of market sizing across historical and forecast periods, along with segmentation analysis that breaks down demand architecture by instrument type, application environment, and geographic exposure. Rather than leaving readers with isolated figures, the analysis connects sizing trends to the operational drivers behind them, including compliance adoption cycles, manufacturing footprint expansion, instrument replacement patterns, and regional procurement behavior.
The competitive profiling section goes beyond company descriptions to map product positioning, instrument capabilities, and strategic emphasis across the leading participants. This enables buyers, investors, and suppliers to understand where differentiation is being created, which technical features are gaining procurement relevance, and how established players are maintaining market share in a category defined by protocol adherence and audit reliability. The inclusion of recent industry context further grounds the analysis in the regulatory and technical dynamics that are actively shaping buying decisions in 2026.
Crucially, the research is designed to support scenario planning. By presenting forward-looking valuation pathways, concentration indicators, and segmentation structures, the report gives executives a framework to evaluate expansion timing, inventory strategy, channel partnerships, and compliance-related capital allocation with greater confidence. The objective is not simply to describe the market, but to provide a decision-ready architecture that can be integrated into product planning, sales targeting, and risk assessment workflows.
Conclusion: Converting Market Visibility into Strategic Advantage
The worldwide charge plate monitor market is moving with steady, structurally supported momentum. Growth is being shaped by compliance reinforcement, cleanroom expansion, instrument modernization, and the ongoing need for reliable ionization verification across high-sensitivity manufacturing environments. In this landscape, the organizations that outperform are those that treat ESD control instrumentation as a strategic asset rather than a compliance footnote.
Our Worldwide Charge Plate Monitor Market research provides the depth, segmentation clarity, and forward-looking framework required to make informed 2026 decisions. The full study contains the detailed segmentation breakdown, competitive profiling, regional deployment patterns, and forecast structures needed to translate industry visibility into procurement precision, product strategy, and commercial execution. For decision-makers ready to move from general awareness to precise market intelligence, the complete report offers the next layer of actionable insight.
For detailed analysis of this topic, please visit the official page: Worldwide Charge Plate Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Hotel Market Hits $1.23T in 2025, Projects 6.5% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the 2026 Global Hotel Market: Strategic Imperatives in a 6.5% CAGR Landscape
As capital markets recalibrate and traveler behaviors solidify into new patterns, the worldwide hotel sector stands at a decisive inflection point heading into 2026. With macroeconomic headwinds moderating and international mobility reaching sustained recovery levels, industry leaders require a precision instrument to navigate expansion, pricing architecture, and competitive positioning. This comprehensive Worldwide Hotel Market research delivers exactly that instrument—transforming raw volume trajectories into actionable strategic roadmaps for executives, developers, investors, and brand managers operating across the global hospitality value chain.
Worldwide Hotel Market
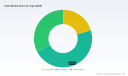
The foundation of this analysis rests on a rigorously modeled historical baseline and forward-looking projection framework anchored to 2025 as the base year. Over the historical window from 2020 through 2025, the sector demonstrated extraordinary resilience, expanding from a base of 550 billion USD to 1,230 billion USD despite operational disruptions and shifting demand distribution. Looking ahead through the forecast horizon of 2026 to 2032, the trajectory points toward sustained compounding growth, culminating in a projected valuation that underscores long-term structural expansion. The implied compound annual growth rate of 6.5 percent reflects not merely cyclical recovery but fundamental shifts in leisure consumption, corporate travel procurement, and asset deployment strategies worldwide.
Such macro momentum masks highly differentiated regional performance, tiered segment dynamics, and application-specific demand catalysts. The strategic value of this report lies in its capacity to isolate signal from noise, enabling decision makers to allocate capital, adjust brand architectures, and anticipate regulatory or cost pressures before they reshape margin profiles. By dissecting the operational and financial realities shaping each growth vector, the publication equips stakeholders with the intelligence required to outperform in a market where top-line expansion increasingly demands disciplined bottom-line execution.
Market Trajectory Architecture and Forecasting Methodology
The analytical core of this research is built upon a transparent, multi-scenario forecasting methodology that integrates historical supply and demand signals, macroeconomic indicators, and structural industry shifts. The projection window from 2026 through 2032 maps a steady climb in aggregate revenue, with each sequential year calibrated against established momentum factors and elasticity constraints. This structured approach allows readers to test sensitivity assumptions around rate performance, occupancy distribution, and capital deployment velocity without relying on static point estimates.
To ensure operational relevance, the report deliberately avoids abstract macro commentary in favor of applied financial logic. Readers will encounter demand-side drivers translated into portfolio implications, supply-side constraints mapped to development timelines, and pricing power dynamics assessed against labor, materials, and regulatory cost environments. The integration of benchmark metrics such as global RevPAR trajectories—which reached 102 dollars in 2025, representing a 4.5 percent year-over-year uplift—grounds the analysis in measurable operational reality rather than speculative narrative. Similarly, the projected corporate travel spending trajectory approaching 1.48 trillion dollars globally in 2025 reinforces the continued commercial demand underpinning midscale and upper-tier asset performance.
Crucially, the report distinguishes between headline growth and profitable growth. Executives are increasingly struggling with the disconnect between rising traffic and compressing margins due to labor cost escalation, construction material inflation, and compliance-driven operational adjustments. By embedding these pressure points directly into segment and regional evaluation frameworks, the publication provides a realistic lens through which expansion decisions can be stress-tested before execution.
Competitive Landscape and Strategic Positioning
Market concentration in the global hotel sector remains moderately dispersed, with the top three operators accounting for approximately 18.5 percent of aggregate revenue and the top five firms controlling just under 24 percent. This structural fragmentation rewards scale where it exists, but also creates space for targeted regional dominance, brand specialization, and franchise-led expansion models. The competitive environment is therefore defined not by monopolistic gravity, but by differentiated growth postures and asset strategy sophistication.
Among the largest global operators, Marriott International continues to scale aggressively across luxury, premium, select, and longer-stay formats, with recent expansion activity centered on Asia-Pacific and Middle East growth corridors. Its December 2025 announcement of 75 newly opened properties and 14,000 added rooms illustrates a deliberate push into high-growth demand markets while maintaining brand portfolio breadth. Hilton Worldwide has taken a parallel but tactically distinct path, introducing Spark by Hilton as a midscale conversion-focused brand aimed at capturing efficiency gains in the United States and Europe. This brand-level maneuver signals how established groups are optimizing portfolio mix rather than relying solely on greenfield development.
InterContinental Hotels Group pursued a partnership-led European expansion by aligning with Tishman Speyer on a 50-property pipeline emphasizing luxury and lifestyle positioning, reinforcing the industry-wide trend of leveraging capital partners to accelerate premium supply. Accor continued its geographically diversified deployment with 40 new hotels and 6,000 added rooms concentrated in Asia and Latin America, underscoring the strategic importance of emerging market penetration for globally balanced portfolios. Meanwhile, Wyndham Hotels & Resorts reached a milestone of 9,500 properties with targeted openings in India and Southeast Asia, extending its franchise strength in economy and midscale segments. Choice Hotels International, Radisson Hotel Group, and Hyatt Hotels Corporation each contributed distinct strategic footprints—spanning North American franchise scaling, EMEA multi-brand diversification, and lifestyle and all-inclusive growth respectively—demonstrating that competitive advantage in 2026 will be derived from area-specific execution rather than uniform global growth.
What these developments collectively reveal is a market where brand architecture, partnership structuring, and geographic targeting determine relative outperformance. The full report isolates these competitive behaviors within a comparative framework that examines revenue mix, asset ownership models, conversion potential, and regional exposure, enabling readers to benchmark their own strategic posture against the industry’s most adaptive players.
Segment Dynamics and Operational Pressures
Segmentation analysis in this research avoids simplistic category breakdowns by mapping each tier against its operational cost structure, demand elasticity, and capital intensity. The luxury segment continues to command premium pricing power but faces heightened scrutiny around asset productivity and brand differentiation. Midscale properties remain the volume engine of portfolio performance, attracting conversion interest from both established groups and private capital seeking stable yield profiles. Economy-tier assets are undergoing reevaluation as labor constraints, construction inflation, and brand standardization requirements reshape their return horizons.
The operational cost environment materially influences segment viability. In the United States, hotel labor costs increased 7.2 percent year-over-year in 2025, driven by wage pressures and persistent staffing shortages across operational functions. Simultaneously, global construction material costs for hotels rose between 5 and 8 percent in 2025, pressured by volatility in steel and lumber pricing. These dual cost vectors affect new supply economics, renovation pacing, and wage budgeting for existing properties, forcing operators to balance occupancy growth against margin preservation.
Regulatory evolution introduces additional complexity. The European Union’s Digital Services Act requires online travel agents and hotel platforms to disclose total prices inclusive of all fees, reshaping booking transparency and altering consumer comparison behavior. This mandate impacts European operators and their international OTA partners, requiring updates to revenue management workflows, distribution pricing strategies, and guest communication architecture. Altogether, these dynamics demonstrate that segment-level strategy cannot be designed in isolation from cost inflation, compliance requirements, and distribution platform reforms.
Hotel Furniture Market
Demand Sources and Regional Interplay
Demand composition across leisure travel, business travel, and other purpose-driven segments continues to recalibrate in response to corporate budgeting cycles, consumer mobility preferences, and global event-driven travel patterns. Leisure demand remains a structural growth driver, supported by sustained international travel enthusiasm and extended-stay behavioral shifts. Business travel benefits from corporate expenditure recovery and the projected elevation of global corporate travel spending, reinforcing demand for midscale and upper-tier assets near commercial hubs. Alternative purpose segments contribute incremental volume through events, medical travel, and project-related mobility, often requiring specialized service models and location-specific inventory strategies.
Regionally, the interplay between mature and developing markets defines deployment priorities. North American operations continue to benefit from strong domestic demand and franchise conversion opportunities, while European markets navigate regulatory compliance and premium brand repositioning. Asia-Pacific remains a central growth axis, attracting international brand investments and domestic portfolio expansions driven by rising middle-class mobility. Latin America and the Middle East and Africa regions offer targeted growth pockets where partnership models, franchise structures, and localized brand adaptations can generate outsized returns relative to capital deployed. The complete research unpacks these regional mechanics without relying on superficial ranking tables, instead establishing the operational logic behind market entry timing, brand selection, and asset type alignment.
What This Report Delivers for 2026 Decision-Making
This Worldwide Hotel Market study is designed as an executive decision-support platform rather than a static market summary. Its architecture emphasizes practical application across corporate strategy, development planning, brand management, and investment evaluation. Readers will gain access to structured assessments of demand trajectory, competitive positioning, cost-pressure sensitivity, regulatory impact pathways, and segment-specific performance drivers. The research translates trend data into strategic questions: Where should portfolio exposure be concentrated in 2026 and beyond? Which brand tiers offer the most resilient margin profile under rising operational costs? How should international growth plans be sequenced given regional cost and compliance differences? Which competitive moves signal durable advantage rather than temporary scale?
By consolidating historical performance evidence, forward-looking forecasts, competitive benchmarks, and operational pressure analysis into a single integrated reference, the report reduces the time required to align internal teams around a common strategic baseline. Investors can apply the framework to asset allocation and risk-adjusted return modeling. Operators can use it to prioritize brand extension, conversion targets, and market-specific pricing adjustments. Developers can evaluate timing sensitivity in relation to material cost trends and labor availability. In each case, the objective is the same: replace uncertainty with structured visibility.
Accessing the Full Intelligence Architecture
The analysis presented here frames the strategic stakes and methodological rigor underpinning the full Worldwide Hotel Market research, but the complete dataset, granular segmentation pathways, regional interaction models, and detailed competitive assessments reside within the full publication. Decision makers seeking to deploy capital, reconfigure brand portfolios, or recalibrate market entry strategies will find that the complete report provides the depth necessary to translate high-level momentum into executable plans.
To access the full research framework, including comprehensive demand mapping, cost-structure sensitivity, competitive benchmarking detail, and forward scenarios through 2032, visit the source page for the complete report. The executive summary provided here establishes the strategic context; the full document delivers the operational intelligence required to act decisively in the 2026 hotel market environment.
For detailed analysis of this topic, please visit the official page: Worldwide Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 2D Game Market Hits $55.2B in 2025 with 7.5% CAGR to $91.6B by 2032
By pmarketresearch, 2026-09-16
The Resilient Canvas: Strategic Insights into the Worldwide 2D Game Market Through 2032
The global video game industry is often defined by its relentless pursuit of graphical fidelity and immersive three-dimensional worlds. However, beneath the surface of photorealistic RTX-rendered landscapes lies a enduring powerhouse that continues to drive significant revenue and cultural relevance: the 2D game market. At PW Consulting, we recognize that while 3D innovation captures headlines, the 2D sector represents a stable, high-growth trajectory fueled by niche audiences, indie innovation, and the timeless appeal of classic gameplay mechanics. Our latest Worldwide 2D Game Market research is not merely a snapshot of current revenues; it is a strategic navigation tool designed for executives, investors, and product leaders operating within the digital entertainment ecosystem.
This comprehensive study offers a granular look at a market that has demonstrated remarkable resilience despite shifting consumer habits and technological disruptions. As the broader global video game software, add-ons, and content revenues reached an all-time high in 2025, estimated at $195 billion, the 2D segment carved out its own significant share of this expansion. Furthermore, broader industry forecasts from PwC's Global Entertainment & Media Outlook 2025–2029 suggest video game segment revenues could approach $300 billion by 2029, indicating that the ecosystem supporting 2D development remains robust. Our report contextualizes these macroeconomic signals specifically for the 2D vertical, providing the clarity needed to make informed decisions in 2026 and beyond.
Market Trajectory and Economic Drivers
Understanding the financial trajectory of the 2D game market requires more than observing current revenue figures; it demands an analysis of compound growth rates and historical stability. Our research establishes a clear baseline, tracking market performance from 2020 through the base year of 2025, and projecting forward into the forecast period of 2026 to 2032. This longitudinal view reveals a consistent upward trend, underscored by a projected CAGR of 7.5 percent over the forecast horizon.
Such growth is not accidental. It is the result of converging factors including the resurgence of retro-inspired aesthetics, the accessibility of powerful development engines, and the monetization flexibility required by modern audiences. According to recent industry analysis, including the BCG Video Gaming Report 2026, tiered pricing and subscription models are increasingly impacting 2D and indie game monetization strategies. Approximately 45 percent of gamers identify as serious fans willing to pay higher prices, while conversely, 30 percent reduce purchasing if prices rise. This dichotomy creates a complex pricing environment where developers must balance accessibility with premium value propositions. Our report dissects these revenue dynamics, offering models for how 2D titles can optimize lifecycle value without alienating price-sensitive segments.
The economic foundation of the 2D market is also supported by its diverse platform distribution. While mobile remains a dominant force in the broader gaming landscape, the 2D sector uniquely thrives across PC and console environments as well. The historical data from 2020 to 2025 shows steady revenue accumulation, with the market size expanding significantly as development tools lower the barrier to entry for independent studios. This democratization of development has led to a saturation of content, making discoverability a critical challenge. Our analysis addresses how market concentration and distribution channels influence revenue realization, helping stakeholders understand where value is being captured in the supply chain.
Competitive Landscape and Ecosystem Dynamics
The landscape of the Worldwide 2D Game Market is characterized by a mix of established legacy publishers, agile indie publishers, and critical infrastructure providers. Unlike markets dominated by a few giants, the 2D sector features a fragmented but active competitive environment. Our research provides detailed profiles of key companies that are shaping the trajectory of 2D gaming.
Worldwide 2D Game Market
On the publishing and development front, legacy powers remain vital. Nintendo Co., Ltd., based in Kyoto, continues to be a dominant player with iconic franchises like Super Mario Bros. and The Legend of Zelda series, maintaining active 2D platformer and adventure releases on Switch and other platforms. Similarly, Capcom Co., Ltd. in Osaka sustains presence through 2D fighting games such as the Street Fighter series and side-scrolling action titles, with ongoing support for 2D pixel-art and sprite-based games. Konami Holdings Corporation has also signaled renewed interest, with announced 2026 releases like Castlevania: Belmont's Curse, a new stylized 2D Castlevania game developed with Evil Empire and Motion Twin. These activities indicate that major publishers view 2D not as a relic, but as a viable, profitable genre for sustained engagement.
In the independent sector, Devolver Digital stands out as a publisher specializing in unique artistic 2D games with global distribution and marketing support for 2D platformers, puzzles, and adventures. Their model highlights the viability of niche artistic content in a crowded marketplace.
However, the ecosystem extends beyond publishers to the tools that enable creation. Unity Technologies provides the leading 2D game engine with updates for sprite animation, lighting, and atlas tools, powering thousands of active 2D game developments worldwide. In March 2026, Unity released updates to 2D game art, animation, and lighting tools in Unity 6.3 LTS, including Sprite Atlas best practices, demonstrating continuous investment in the 2D developer experience. Similarly, the Godot Foundation offers an open-source engine optimized for 2D game development, used by numerous independent studios for lightweight, cross-platform 2D titles. YoYo Games, operating under Opera in Dundee, UK, develops GameMaker Studio, a drag-and-drop tool focused exclusively on 2D game creation, widely used by indie developers for mobile and PC 2D games. Epic Games, Inc. also contributes via Unreal Engine with strong 2D paper and sprite capabilities, publishing and supporting 2D titles via the Epic Games Store.
Outsourcing and service providers form the backbone of production scalability. Keywords Studios, headquartered in Dublin, serves as a global outsourcing provider for 2D art, animation, QA, and localization services supporting 2D game production for major publishers. Virtuos in Singapore specializes in co-development, porting, and 2D/3D art production for AAA and 2D-focused games. Room 8 Group, with a global presence originally rooted in Ukraine, offers full-cycle 2D game development and art outsourcing for mobile, PC, and console 2D titles. Kevuru Games and Stepico, both based in Ukraine, focus on 2D game art outsourcing, animation, and full development for AAA and indie 2D projects, emphasizing stylized 2D games. Our report analyzes how these partners integrate into global production pipelines, noting that game development outsourcing for 2D art and animation remains active with specialized studios in Ukraine, India, and Singapore supporting global production pipelines.
Worldwide HTML5 Games Market
Segmentation and Consumer Dynamics
Strategic decision-making requires a deep understanding of how the market is segmented and who the consumers are. Our research breaks down the market across key dimensions without losing sight of the interconnected nature of these segments. We examine the distribution across regions, acknowledging that while Asia Pacific represents a significant portion of global engagement, North America and Europe maintain robust commercial ecosystems for 2D titles. Latin America and the Middle East and Africa present emerging opportunities with distinct growth characteristics.
Platform segmentation is equally critical. While mobile gaming drives volume, the PC and console segments often command higher average revenue per user for premium 2D experiences. Our analysis explores how development priorities shift based on target platforms, considering factors such as input methods, session lengths, and monetization capabilities. Genre segmentation further refines this view, covering Role-Playing Games, Action and Platformer, Puzzle and Strategy, and Casual and Hyper-casual categories. Each genre presents unique development lifecycles and audience expectations. For instance, the recent teaser by Gotcha Gotcha Games in March 2026 regarding RPG Maker New Project, the first entry supporting HD-2D game creation with aesthetics similar to Octopath Traveler and Dragon Quest HD-2D remakes, highlights the specific demand for high-fidelity 2D RPG experiences.
Consumer habits are evolving, influenced by broader trends in digital entertainment. Digital competition regulations targeting large online platforms continue to evolve globally, affecting distribution and discoverability of 2D games on major stores. This regulatory noise requires publishers to diversify distribution strategies and build direct relationships with communities. Our report evaluates these regulatory risks and opportunities, providing guidance on navigating store policies and maintaining visibility in a regulated digital marketplace.
Strategic Imperatives for 2026 and Beyond
The data presented in our Worldwide 2D Game Market report converges on several strategic imperatives for stakeholders aiming to capitalize on the forecast period through 2032. First, the integration of HD-2D aesthetics and modernized retro styles represents a significant value driver. As seen with recent announcements from established IPs, there is a market appetite for 2D games that honor traditional aesthetics while leveraging modern lighting and animation tools. Companies investing in engine updates, such as Unity's recent enhancements, are better positioned to meet these aesthetic demands efficiently.
Second, monetization strategy must be nuanced. With the broader industry highlighting the sensitivity of consumer spending to price changes, 2D developers cannot rely on one-size-fits-all pricing. The BCG report's findings on tiered pricing and subscriptions suggest that flexibility is key. Successful titles may need to offer multiple entry points, from free-to-play casual experiences to premium indie titles with expansion content. Our research provides frameworks for testing and implementing these models without fragmenting the user base.
Third, partnerships and outsourcing should be viewed as strategic levers rather than mere cost-saving measures. With specialized studios in Ukraine, India, and Singapore actively supporting global production pipelines, publishers can scale art and animation production rapidly. However, quality control and cultural alignment remain paramount. Our report details the capabilities of key outsourcing providers, helping companies build resilient supply chains that can adapt to geopolitical or operational disruptions.
Finally, discoverability in a regulated environment requires proactive community building and multi-channel distribution. Reliance on a single storefront exposes developers to policy changes and algorithmic shifts. Diversifying across PC, console, and mobile platforms, while leveraging direct sales channels where possible, mitigates this risk.
Why This Research Matters for Your Strategy
In an industry saturated with noise, precise intelligence is the differentiator between speculation and strategy. The Worldwide 2D Game Market report by PW Consulting is designed to cut through the ambiguity. It provides the historical context to understand where the market has been, the granular segmentation to understand where value currently resides, and the forward-looking projections to anticipate where it is going. The 7.5 percent CAGR and the projected market valuation reaching towards $91,579.51 million by 2032 are not just numbers; they represent the scale of opportunity available for those who can navigate the complexities of development, distribution, and monetization.
However, the full depth of this intelligence—including detailed regional breakdowns, specific platform revenue splits, and comprehensive competitive benchmarking data—is reserved for our clients who require actionable precision. This article serves as a testament to the rigor and scope of our analysis, but the complete dataset contains the specific figures and strategic annotations necessary to build your 2026 business plan.
We invite industry leaders, investors, and strategic planners to access the full report to unlock the detailed intelligence required to secure a competitive advantage in the worldwide 2D game market. The canvas is evolving, and the tools to paint the future are available to those equipped with the right insights.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Game Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Torsional Vibrational Damper Market to Reach $3,362.02 Million by 2032
By pmarketresearch, 2026-09-16
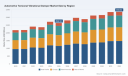
Strategic Imperatives in the Worldwide Automotive Torsional Vibrational Damper Market: Navigating Growth, Consolidation, and Technological Disruption Through 2032
The automotive industry is currently navigating a complex transitional phase defined by stringent emissions regulations, rapid electrification, and an unyielding consumer demand for refinement. Within this broader landscape, the torsional vibrational damper market occupies a critical, albeit often overlooked, niche. As internal combustion engines become increasingly downsized and hybridized to meet environmental targets, the management of crankshaft torsional vibrations has shifted from a secondary engineering consideration to a primary determinant of NVH performance, component durability, and overall vehicle reliability. PW Consulting’s newly released Worldwide Automotive Torsional Vibrational Damper Market study provides a comprehensive, data-driven roadmap for stakeholders seeking to capitalize on these shifting dynamics. Covering historical performance from 2020 through 2025 and projecting forward to 2032, this analysis is structured specifically to inform high-level procurement, R&D allocation, and geographic expansion strategies for the 2026 fiscal year and beyond.
Market Trajectory and Structural Evolution: A Decade of Measured Growth Amid Technological Flux
Over the past five years, the global torsional vibrational damper market has demonstrated a resilient growth trajectory, expanding from a revenue baseline of approximately 2.18 billion USD in 2020 to an estimated 2.72 billion USD in 2024 before consolidating slightly to 2.64 billion USD in 2025. This cyclical adjustment reflects the broader automotive production volatility experienced during the post-pandemic supply chain realignment, yet the underlying structural demand remains firmly intact. Moving into the forecast horizon, the market is projected to recover and steadily ascend, reaching 2.81 billion USD in 2026 and culminating at 3.36 billion USD by 2032. This expansion is underpinned by a compound annual growth rate of 3.5 percent, a figure that may appear moderate at first glance but carries profound strategic implications when dissected through the lens of powertrain evolution and component substitution rates.
The 3.5 percent CAGR should not be interpreted as a symptom of market stagnation, but rather as an indicator of a maturing ecosystem undergoing qualitative transformation. Revenue growth is increasingly decoupled from pure volume expansion and is instead being driven by value migration toward advanced materials, integrated multi-function modules, and higher-performance viscous and hybrid architectures. The base year of 2025 serves as a critical inflection point, capturing the market’s post-correction equilibrium before the accelerating adoption of electrification-enabling technologies begins to materially reshape demand curves. For automotive suppliers, tier-one manufacturers, and investment committees, understanding the velocity of this transition is paramount. The study provides granular visibility into how revenue streams are redistributing across product architectures, vehicle segments, and regional manufacturing footprints, enabling leadership teams to align capacity planning and technology roadmaps with actual commercial trajectories rather than speculative industry narratives.
Technology Inflection Points: Regulatory Pressure, Electrification, and Material Innovation Redefining Component Architectures
The fundamental drivers reshaping the torsional vibrational damper landscape are deeply intertwined with regulatory mandates and platform-level engineering shifts. EU fleet CO2 regulations and U.S. CAFE standards have systematically pushed original equipment manufacturers toward turbocharged small-displacement engines. While these powertrains deliver fuel efficiency gains, they simultaneously generate higher torsional excitations and more aggressive vibration spectra. Consequently, precisely engineered dampers are no longer optional accessories; they are critical stress-management components that protect crankshafts, drivetrains, and auxiliary belt systems from premature fatigue. This regulatory reality has elevated the functional requirements for damper durability, frequency targeting, and thermal resilience, directly influencing material selection and geometric design across the market.
Parallel to emissions-driven downsizing, the proliferation of 48-volt mild-hybrid architectures is introducing a new tier of integration complexity. With European market penetration of 48V systems projected to reach 35 percent of new vehicle sales by 2027, demand is accelerating for integrated belt-starter-generator torsional isolation units. These systems require dampers that can simultaneously manage engine firing pulses, starter-motor engagement shocks, and regenerative braking transients without compromising belt tension or alternator durability. The engineering response has been swift. Over 30 percent of companies have already launched hybrid dampers incorporating smart sensors, enabling real-time torque management and predictive maintenance capabilities. This sensorization trend hints at a broader industry trajectory where mechanical dampers evolve into data-generating nodes within vehicle health monitoring networks, opening adjacent revenue streams in software-defined diagnostic services and over-the-air maintenance forecasting.
Material innovation is equally transformative. Nearly 55 percent of new product developments in torsional vibration dampers now integrate lightweight composite materials, a shift designed to improve dynamic performance while simultaneously reducing noise, vibration, and harshness levels. Composite architectures allow engineers to tailor stiffness and damping coefficients with greater precision than traditional elastomeric formulations, particularly in high-frequency excitation zones. For competitors still reliant on legacy rubber-only designs, this material migration represents both a performance gap and a strategic vulnerability. The study dissects these technology adoption curves, mapping the pace at which advanced materials and sensor-integrated architectures are moving from pilot programs to series production, and identifying the supply chain bottlenecks that may delay or accelerate commercial viability.
Competitive Landscape and Porter’s Five Forces Realignment: Concentration, Differentiation, and the Rise of System-Level Integration
The torsional vibrational damper market operates under a moderately concentrated structure, with the top three enterprises collectively commanding approximately 42 percent of global revenue and the top five expanding that share to nearly 59 percent. This concentration reflects the capital intensity of damper manufacturing, the stringent validation cycles required by OEMs, and the long-term supply agreements that characterize automotive component procurement. However, concentration does not equate to complacency. The competitive battlefield has shifted from price-based volume competition to architectural differentiation, application-specific engineering, and system-level integration capabilities.
Vibracoustic SE has positioned itself prominently in the light-vehicle segment, offering pressed, vulcanized, and fluid torsional vibration dampers engineered to absorb crankshaft rotational vibrations. Their product philosophy emphasizes compatibility with decoupled pulleys, making their solutions particularly effective for downsized engines equipped with start-stop systems and auxiliary belt drive isolation. Continental AG has similarly expanded its OEM and aftermarket footprint with TVD and TVDi variants, leveraging flywheel, pulley, and elastomer track configurations to damp crankshaft vibrations and stabilize belt drives. In November 2024, Vibratech TVD reinforced its positioning in the high-performance segment by releasing OEM documentation highlighting dual viscous damper designs engineered for enhanced heat dissipation and durability. This move directly targets applications where elastomer-based alternatives struggle under high-temperature and high-load conditions. Continental followed a complementary trajectory in July 2024 with the launch of an integrated torsional vibration damper module tailored for 48V mild-hybrid engines, combining damper, pulley, and crank functions into a single architecture.
In the commercial and high-torque domain, ZF Friedrichshafen AG supplies DynaDamp torsional dampers utilizing dual mass flywheel technology, serving commercial vehicles, hybrids, and special applications with torque ratings extending up to 3,200 Nm. Their focus on decoupling engine vibrations and reducing rotational irregularities aligns closely with the durability and service-life expectations of heavy-duty platforms. Schaeffler AG, through its LuK and INA divisions, develops crankshaft torsional vibration dampers, spoke dampers, and pulley decouplers for both combustion and hybridized engines, targeting NVH reduction and crankshaft stress mitigation across diverse powertrain configurations. Viscous technology specialists such as Vibratech TVD and Hasse & Wrede GmbH continue to emphasize superior durability in demanding thermal environments, while Gates Corporation provides complete system solutions through its Micro-V and DriveAlign TVD lines, addressing crankshaft and engine vibration control for passenger cars and light commercial vehicles.
The competitive dynamic is increasingly defined by the ability to deliver validated, application-specific solutions rather than commoditized off-the-shelf components. Procurement teams are prioritizing suppliers that can demonstrate co-engineering capabilities, rapid prototyping cycles, and regulatory compliance documentation. The study maps these competitive differentiators, evaluates supplier risk profiles, and identifies white-space opportunities where regional manufacturing localization or material substitution could disrupt established supply relationships. For strategic planners, this competitive mapping is essential for negotiating long-term agreements, evaluating make-versus-buy scenarios, and anticipating consolidation events that may alter supply continuity.
Regional Demand Architecture and Application Segmentation: Navigating Heterogeneous Growth Engines
The geographic distribution of torsional vibrational damper demand reflects the uneven pace of automotive modernization across global markets. Asia Pacific remains the largest revenue contributor, anchored by high production volumes, expanding domestic consumer vehicle markets, and a growing base of commercial vehicle manufacturing. Europe represents a structurally distinct demand environment, where regulatory pressure, mild-hybrid adoption curves, and premium vehicle penetration create a high value-per-unit market characterized by stringent NVH expectations and rapid technology turnover. North America exhibits a more mixed profile, balancing light vehicle production with a substantial commercial vehicle segment and a persistent aftermarket demand curve that buffers OEM cycle volatility. The Rest of World segment, while smaller in absolute terms, is gaining strategic relevance as regional automotive clusters mature and localized content requirements influence component sourcing decisions.
Torsional Vibration Damper Market
The study deliberately avoids superficial regional or application-level aggregations in its executive disclosures, instead providing a structured analytical framework that allows strategists to construct scenario-based forecasts aligned with their specific portfolio exposure. Application segmentation reveals meaningful divergence in growth velocity across passenger cars, light commercial vehicles, and heavy commercial vehicles. Passenger car platforms continue to dominate absolute volume, but commercial vehicle segments are experiencing disproportionate value growth driven by torque escalation, extended service intervals, and stricter durability validation. Light commercial vehicle architectures are increasingly adopting passenger-car-derived vibration management strategies, while heavy commercial platforms are pushing the boundaries of dual-mass flywheel integration and high-torque viscous damping. Understanding how these application segments interact with regional production quotas, emissions compliance timelines, and electrification roadmaps is critical for capacity allocation and pricing strategy.
The 2026 Decision Framework: Translating Intelligence Into Capital Allocation, Sourcing Strategy, and R&D Prioritization
For executive teams formulating 2026 strategies, the torsional vibrational damper market presents a series of high-stakes decisions that extend far beyond conventional procurement optimization. Capital allocation must account for the steady migration toward sensor-integrated hybrid dampers, composite material formulations, and integrated belt-starter-generator modules, all of which require distinct tooling investments, validation protocols, and supplier qualification processes. Sourcing strategies must balance the stability of established tier-one relationships against the agility of regional suppliers capable of meeting localized content mandates and shorter lead-time requirements. R&D prioritization should focus on application-specific engineering capabilities that enable co-development with OEMs, particularly in mild-hybrid integration, thermal management of viscous architectures, and predictive diagnostics enabled by embedded sensor architectures.
The study is designed to operationalize these decisions by providing actionable intelligence across multiple analytical dimensions. It examines historical revenue behavior, forward-looking growth trajectories, technology adoption timelines, competitive positioning, and regulatory impact pathways, all structured to support portfolio planning, market entry evaluation, and risk mitigation. Readers gain access to a detailed mapping of product type evolution, vehicle segment utilization patterns, regional manufacturing dynamics, and supplier concentration metrics, alongside qualitative assessments of recent product launches, technical documentation releases, and material innovation roadmaps. The analysis also contextualizes market concentration within broader procurement risk frameworks, enabling supply chain leaders to stress-test continuity assumptions and identify secondary sourcing pathways before disruptions materialize.
Worldwide Automotive Torsional Vibrational Damper Market
Conclusion: Positioning for the Next Phase of Value Creation in Vibration Management Engineering
The worldwide automotive torsional vibrational damper market is entering a phase where incremental improvement yields diminishing strategic returns, and where structural differentiation, system-level integration, and regulatory-aligned engineering define competitive advantage. The 3.5 percent CAGR projected through 2032 masks the intensity of the underlying transformation: material migration toward composites, the sensorization of hybrid dampers, the integration of 48V mild-hybrid isolation units, and the recalibration of regional demand patterns in response to electrification timelines and emissions compliance deadlines. PW Consulting’s comprehensive study provides the analytical depth required to navigate this environment with confidence, equipping strategists, engineers, and procurement leaders with the intelligence necessary to translate market complexity into decisive action. For organizations seeking to secure supply continuity, accelerate technology adoption, and capture value from the evolving vibration management landscape, the complete report delivers the structured, decision-ready intelligence required to outperform in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Torsional Vibrational Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Mono Cartons Market to Hit USD 26,495 Million by 2032 at 5.25% CAGR
By pmarketresearch, 2026-09-16
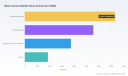
Strategic Imperatives in the Global Mono Cartons Market: A 2026 Outlook
The global packaging landscape is undergoing a structural transformation driven by sustainability mandates, supply chain reconfiguration, and shifting consumer expectations. Within this complex ecosystem, mono cartons have emerged as a critical vector for innovation, offering brands a pathway to simplify recycling streams while maintaining product integrity. As we navigate the midpoint of the decade, understanding the trajectory of this market is no longer optional—it is a strategic necessity for stakeholders across the value chain. PW Consulting's latest Worldwide Mono Cartons Market research provides the analytical framework required to make informed decisions in 2026 and beyond.
This deep dive explores the macroeconomic signals, competitive undercurrents, and regulatory pressures defining the sector, drawing from comprehensive data covering the historical period from 2020 through 2025 and extending our forecast horizon to 2032.
Market Trajectory and Growth Dynamics
The mono cartons market has demonstrated consistent resilience over the past five years. Following a baseline valuation in 2020, the sector has navigated inflationary pressures and logistical disruptions to deliver steady expansion. The total market revenue has progressed significantly, reflecting the robust demand for fiber-based packaging solutions that align with circular economy goals. Our analysis indicates that the market value has climbed to approximately $18,500 million in the base year of 2025, underscoring the sector's significance within the broader packaging industry.
Looking ahead, the growth narrative remains positive but nuanced. The forecast period from 2026 to 2032 suggests a compound annual growth rate (CAGR) of 5.25 percent. This rate implies a steady acceleration rather than explosive volatility, characteristic of mature packaging markets undergoing technological and regulatory upgrades. By 2032, the market is projected to reach substantial revenue milestones, driven by volume expansions in key verticals and geographic regions. However, realizing this potential requires navigating fluctuating raw material costs and evolving compliance landscapes.
Decision-makers must recognize that growth is not uniform across all vectors. Regional disparities, material preferences, and end-user applications create pockets of high opportunity amidst broader trends. Understanding where capital should be allocated requires granular insight into these segments, which are fully detailed in the comprehensive report.
Competitive Landscape and Strategic Positioning
The competitive environment for mono cartons is defined by a mix of global giants and specialized players who are actively reshaping their portfolios to meet sustainability targets. Market concentration remains moderate, with the top three companies holding approximately 15.4 percent of the market share and the top five accounting for 22.8 percent. This fragmentation suggests room for consolidation but also indicates that agility and niche innovation can yield competitive advantages even against larger incumbents.
Key Industry Participants
Several major corporations dominate the landscape, each leveraging distinct strengths in material science and manufacturing capacity.
-
WestRock Company , headquartered in Atlanta, USA, remains a global leader in paper and board packaging. They produce mono cartons from solid bleached sulfate (SBS) and recycled board, catering extensively to consumer goods, food, and pharmaceutical sectors. Their recent exhibition at Pack Expo International showcased recyclable mono cartons optimized for e-commerce shipping, highlighting a strategic pivot towards logistics-friendly packaging.
-
International Paper Company , based in Memphis, USA, manufactures mono cartons using folding boxboard. Their focus spans retail, cosmetics, and healthcare packaging worldwide, positioning them as a key supplier for premium and sensitive product categories.
-
Smurfit Kappa Group , a Dublin-based European powerhouse, offers mono cartons from sustainable paperboard sources. Their recent achievement of FSC certification for a new range of mono cartons using 100 percent recycled paperboard demonstrates a commitment to verifiable sustainability credentials that resonate with regulatory bodies and consumers alike.
-
Mondi Group , headquartered in Vienna, Austria, provides recyclable mono cartons made from kraftliner and recycled fibers. They serve fast-moving consumer goods and confectionery markets. In June 2025, Mondi launched Advantage Protect mono material cartons with high-barrier paperboard for food preservation without plastic layers, a significant development in reducing multi-material complexity.
-
Mayr-Melnhof Karton AG , also based in Vienna, specializes in high-quality coated folding boxboard for mono cartons. Their focus on confectionery, tobacco, and premium consumer packaging highlights the importance of surface quality and printability in specific segments.
-
Stora Enso Oyj , from Helsinki, Finland, produces barrier-coated paperboard mono cartons for food and beverage packaging with a focus on renewability. In November 2024, they commissioned a new paperboard line at their Imatra mill with 200,000 tons annual capacity, signaling significant capacity expansion to meet growing demand.
-
Huhtamaki Oyj , based in Espoo, Finland, offers mono cartons for dairy, frozen foods, and non-food applications using fiber-based materials. Their specialization in cold chain and hygiene-sensitive applications adds diversity to the competitive field.
Worldwide Mono Cartons Market -
Tetra Laval Group (Tetra Pak) , located in Pully, Switzerland, develops mono-material paperboard cartons as plastic-free alternatives for liquid packaging. Their engineering focus addresses one of the most challenging applications in the packaging sector.
Recent Strategic Moves
The competitive dynamics are further illustrated by recent corporate activities. These moves signal where investment is flowing and what capabilities are becoming table stakes for market relevance.
-
In April 2025, WestRock Company exhibited recyclable mono cartons at Pack Expo International, specifically showcasing EnviroWise mono cartons optimized for e-commerce shipping.
-
In March 2025, Smurfit Kappa Group achieved FSC certification for a new range of mono cartons using 100 percent recycled paperboard, reinforcing their sustainability narrative.
-
In June 2025, Mondi Group launched Advantage Protect mono material cartons with high-barrier paperboard for food preservation without plastic layers.
-
In November 2024, Stora Enso Oyj commissioned a new paperboard line for mono carton production at Imatra mill with 200,000 tons annual capacity.
Material and Segment Landscape
The composition of the market itself is shifting. Historically, virgin paperboard has constituted a significant portion of the supply, driven by its superior printing and structural properties. However, the push towards circularity is elevating the status of recycled paperboard and specialized variants like micro-flute. The balance between these material types is influenced by cost structures, availability, and performance requirements specific to the end application.
End-user demand is similarly diversified. The food and beverage sector remains a primary driver, demanding safety and barrier properties. Simultaneously, the pharmaceutical industry requires high compliance and protection standards, while personal care and cosmetics leverage mono cartons for premium branding that aligns with eco-conscious consumer values. Each vertical presents unique challenges regarding regulation, moisture resistance, and structural integrity.
Regional distribution of demand also varies significantly. Asia Pacific represents a substantial portion of market activity, followed by Europe and North America. Emerging regions in Latin America and the Middle East and Africa offer incremental growth opportunities, though they come with distinct logistical and regulatory considerations. A detailed breakdown of volume and value contributions across these dimensions is essential for precise market entry or expansion strategies.
Regulatory and Economic Headwinds
No strategic analysis of the mono cartons market is complete without addressing the external forces shaping supply and demand. Regulatory frameworks across major economies are increasingly favoring mono-material designs to facilitate recycling, creating a tailwind for mono cartons but also imposing strict compliance requirements.
Regulatory Pressures
-
EU Packaging and Packaging Waste Regulation (PPWR) : Mandates mono-material designs for recyclability, targeting 40 percent recycled content in paperboard cartons by 2030. This regulation directly impacts European manufacturers and exporters targeting the EU market.
Worldwide Digital Printed Cartons Market -
UK Plastic Packaging Tax : Applies a levy of £217 per tonne on non-recycled plastic content, incentivizing mono paperboard cartons over multi-material alternatives. This fiscal measure strengthens the economic case for fiber-based solutions in the UK.
-
China Extended Producer Responsibility : Requires packaging producers to achieve 30 percent recycled content in cartons by 2025, with fines up to CNY 1 million for non-compliance. This local legislation forces regional players to adjust their material sourcing strategies rapidly.
Raw Material Economics
Cost volatility remains a persistent risk. Solid bleached sulphate (SBS) paperboard, the primary material for mono cartons, is tracked by the US Bureau of Labor Statistics Producer Price Index at 278.5 (1982=100) in January 2026. This index level reflects ongoing cost pressures in the fiber market. Additionally, global recycled paperboard prices averaged $850 per ton in Q4 2025, up 5 percent year-over-year due to supply chain constraints. These input cost fluctuations can compress margins if not managed through hedging, efficiency improvements, or value-based pricing strategies.
The Strategic Value of Comprehensive Intelligence
Navigating this environment requires more than just high-level growth rates. It demands a granular understanding of how regulatory shifts intersect with material costs, how competitor capacity expansions will affect supply availability, and which end-user segments are poised for the fastest adoption of new mono-material technologies.
PW Consulting's Worldwide Mono Cartons Market report is designed to provide this level of operational clarity. The study goes beyond macroeconomic narratives to offer actionable intelligence on segmentation splits, regional performance metrics, and competitive benchmarking. It serves as a reference point for procurement teams managing raw material risks, strategic planners evaluating capacity investments, and marketing leaders positioning products against sustainability claims.
Access to detailed data on revenue contributions by region, material type, and end-user allows organizations to model scenarios with greater accuracy. Whether assessing the impact of the PPWR on European supply chains or evaluating the growth potential in Asian markets, the granular data points within the full report enable a level of precision that summary insights cannot match.
Conclusion: Preparing for 2032
The mono cartons market stands at a pivotal juncture. The convergence of regulatory mandates, material innovation, and consumer pressure is creating a clear direction towards sustainability, but the path is fraught with economic and operational complexities. With a projected CAGR of 5.25 percent through 2032, the opportunity is significant, yet the winners will be those who can interpret the underlying data to mitigate risk and capture share.
For executives and analysts tasked with steering their organizations through 2026 and beyond, relying on generalized market narratives is insufficient. The specific dynamics of material pricing, regional regulatory compliance, and competitor capacity shifts require detailed examination. PW Consulting's comprehensive research delivers the depth required to transform uncertainty into strategy.
To access the full suite of data, including detailed segmentation splits, regional revenue analysis, and comprehensive company profiles, we invite you to explore the complete Worldwide Mono Cartons Market research study. The full intelligence package is available exclusively through our platform, ensuring your team has the precise information needed to execute with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Mono Cartons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com