

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: D&O Insurance Market Hits $25.2B in 2025, Projects 7.64% CAGR to 2032

Navigating the Evolving Landscape of D&O Insurance: Strategic Imperatives for 2026
The Directors and Officers (D&O) insurance market stands at a critical inflection point. As corporate governance faces unprecedented scrutiny from regulators, shareholders, and the public, the liability protection afforded to board members has never been more vital—or more complex. PW Consulting's latest comprehensive market research on the D&O Insurance sector provides decision-makers with the intelligence needed to navigate this shifting terrain with confidence. This report arrives at a moment when strategic foresight regarding insurance procurement, risk mitigation, and governance structures can meaningfully differentiate resilient organizations from those exposed to emerging liabilities.
The global D&O insurance market has demonstrated remarkable growth trajectories over the past half-decade. From a base of approximately 17.24 billion USD in 2020, the market expanded to 25.2 billion USD by 2025, reflecting a compound annual growth rate of 7.64 percent through the forecast period extending to 2032. This sustained expansion is not merely a function of nominal economic growth; it reflects deepening awareness of director liability, increasingly litigious environments, and the materialization of risks that were once theoretical. Looking ahead, the market is projected to reach 42.19 billion USD by 2032, suggesting that D&O coverage will remain a cornerstone of corporate risk management frameworks for the foreseeable future.
For directors, officers, and corporate secretaries, these macro-level figures translate into tangible decisions about coverage adequacy, policy structure, and carrier relationships. The 2026 outlook, in particular, demands attention. After several years of market hardening and premium volatility, indications point toward stabilization, yet the underlying risk environment continues to evolve in ways that require sophisticated interpretation. Our research unpacks these dynamics with the granularity necessary for informed decision-making, while providing the strategic context that generic market summaries cannot deliver.
Market Dynamics: Stabilization Amid Escalating Liability Risks
The D&O marketplace in 2026 presents a nuanced picture. Broad market assessments from rating agencies and industry analysts describe a stabilization pattern, with moderate rate adjustments and disciplined underwriting becoming the norm. This represents a meaningful shift from the turbulence of prior years, yet stabilization should not be mistaken for complacency. Several structural forces are simultaneously compressing and expanding the liability landscape, and boards must understand how these forces intersect with their specific organizational profiles.
One of the most significant developments concerns the rising tide of business insolvencies globally. Projections indicate that insolvencies will increase by approximately 5 percent in 2026, pushing levels 24 percent above pre-pandemic averages. This trend carries direct implications for D&O exposures, particularly in sectors such as automotive, construction, and retail, where financial distress often triggers shareholder actions, creditor claims, and regulatory investigations. Directors overseeing organizations in these vulnerable industries face heightened scrutiny, and the availability of robust D&O protection becomes a critical component of succession planning and risk transfer strategies.
Cyber Insurance Market
Complementing the insolvency narrative is the evolving profile of securities litigation. Median settlements in US securities class actions rose 21 percent in 2025, reaching 17 million USD. This escalation reflects not only larger claim values but also the expanding scope of alleged wrongdoing. Regulatory and geopolitical shifts have broadened the perimeter of what constitutes actionable director conduct, and plaintiffs' attorneys are increasingly aggressive in leveraging these expanded definitions. For boards, the implication is clear: defense costs and settlement exposures are growing faster than general inflation, and policy limits that appeared sufficient yesterday may prove inadequate tomorrow.
The cost of legal defense itself has become a material concern. Cumulative legal services inflation has risen 44 percent since 2020, directly eroding the effectiveness of retention layers and pushing more claims into higher coverage tiers. This dynamic affects the economics of D&O programs across the board, from public companies with extensive indemnification obligations to private enterprises where directors may face personal liability without the shield of corporate resources. Our research examines how these cost pressures are reshaping policy structuring, retention decisions, and the broader calculus of risk bearing.
Simultaneously, the sources of potential director liability are diversifying. Artificial intelligence oversight, ESG compliance, and geopolitical risk management have emerged as focal points for claims activity. Directors are now expected to demonstrate competence in areas that were peripheral to traditional corporate governance just a few years ago. Failure to exercise appropriate diligence in these domains can expose individuals to allegations of breach of fiduciary duty, and carriers are increasingly scrutinizing board composition and expertise during underwriting. This evolving expectations landscape makes it essential for organizations to align their governance practices with the risk appetite communicated in their insurance applications.
Competitive Landscape: Carriers Adapting to a New Risk Era
The D&O insurance market is characterized by a moderately concentrated competitive structure, with the top three carriers commanding approximately 32 percent of market revenue and the top five approaching 47 percent. This concentration suggests a market where scale, brand reputation, and underwriting sophistication confer advantages, yet ample room remains for specialized and regional players to differentiate through niche expertise and tailored solutions. Understanding the strategic positioning of major carriers is essential for organizations evaluating their insurance partners and negotiating coverage terms.
Chubb, with its multinational footprint spanning over 40 countries, exemplifies the comprehensive approach that global organizations require. Its portfolio encompasses Side A coverage and tailored solutions for public, private, and nonprofit entities, with a pronounced emphasis on governance and securities claims. For boards operating across multiple jurisdictions, Chubb's ability to deliver locally compliant policies within a unified framework represents a strategic advantage that simplifies administration while maintaining protection consistency.
AIG continues to provide D&O liability solutions that address the full spectrum of claims sources, from shareholder actions to competitor disputes and regulatory challenges. Its specialized product lines for public companies, private companies, and nonprofits reflect a granular understanding of how liability exposures differ across organizational structures. This segmentation matters because a private company's D&O needs—where personal asset protection often dominates—differ materially from those of a publicly traded entity facing securities class action exposure.
Travelers Insurance delivers coverage for defense costs, settlements, and judgments arising from management decisions and wrongful acts, serving public, private, and nonprofit clients. Its brand strength and claims handling reputation make it a frequent consideration for organizations seeking a balance of breadth and reliability. Liberty Mutual, through its Ironshore platform, extends D&O liability solutions designed for complex risks across varied company structures, emphasizing protection for leaders against claims stemming from management actions.
Allianz has positioned itself at the intersection of traditional D&O coverage and emerging risk categories. Its offerings address geopolitical, cyber, and regulatory risks, reflecting an insights-driven approach suited to boards confronting evolving liabilities. The December 2025 release of its D&O Insurance Insights 2026 report underscores this focus, highlighting the interplay of geopolitics, cyber threats, tariffs, and rising insolvency impacts on director liabilities. For organizations whose risk profiles extend beyond conventional governance concerns, Allianz's expanded perspective offers valuable alignment.
Zurich Insurance Group supplies D&O liability coverage with particular strength in multinational and mid-sized company segments, focusing on management and professional liability exposures. AXA XL, as part of the broader AXA Group, contributes specialized financial lines products with coverage enhancements designed for emerging risks. Beazley has built a reputation for D&O and management liability insurance with particular depth in cyber-exposed and specialty risk segments, making it a relevant consideration for technology-intensive and highly regulated organizations. Hiscox serves small to mid-sized businesses and specialized sectors, providing accessible solutions that address the D&O needs of organizations that may not command the attention of larger carriers. Berkshire Hathaway Specialty Insurance leverages its substantial financial backing to offer robust D&O coverage capable of supporting high-limit and complex risk scenarios, appealing to organizations with significant exposure profiles.
The recent developments among these and other industry participants illustrate how the market is responding to 2026 realities. WTW's February 2026 market outlook emphasized premium stabilization, AI oversight expectations, bankruptcy risk considerations, and securities litigation forecasts, providing a forward-looking framework that boards can use to benchmark their own risk assessments. Baldwin's January 2026 public company D&O outlook noted that favorable terms are continuing into 2026, with pricing stabilization expected to persist. AM Best's revised U.S. D&O outlook to stable, citing moderate rate decreases, low loss ratios, and stricter underwriting, reinforces the narrative of a market finding its footing while maintaining discipline. These complementary perspectives form a mosaic that our research synthesizes into actionable guidance.
Report Structure and Practical Utility
PW Consulting's D&O Insurance Market research is structured to deliver immediate operational value alongside long-term strategic insight. The report begins with a comprehensive market overview that contextualizes historical performance from 2020 through 2025 and projects forward through 2032. This temporal scope allows readers to identify inflection points, assess the durability of recent trends, and distinguish cyclical fluctuations from structural shifts.
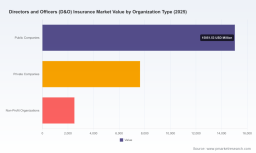
The segmentation analysis examines the market across multiple dimensions critical to procurement decisions. Coverage type breakdowns illuminate how Side A, Side B, and Side C protections are distributed across the market, helping organizations understand which coverage components are most competitive and where gaps may exist in their current programs. Organization type segmentation distinguishes among public companies, private companies, and nonprofit organizations, recognizing that each category faces distinct liability profiles and insurance requirements. Regional analysis provides a geographic lens that supports multinational organizations in coordinating coverage strategies across jurisdictions while acknowledging local market characteristics.
Competitive profiling extends beyond basic company descriptions to evaluate strategic positioning, product capabilities, and movement in response to market conditions. The analysis of recent developments—capturing carrier reports, market outlooks, and rating agency assessments from late 2025 through early 2026—ensures that the competitive picture reflects the most current intelligence available. This timeliness is essential because the D&O market can shift rapidly in response to loss experience, regulatory changes, and macroeconomic pressures.
The report's examination of industry context integrates regulatory developments, macroeconomic trends, and sector-specific risk factors into a cohesive narrative. The projected rise in global business insolvencies, the escalation of securities settlement values, the cumulative impact of legal cost inflation, and the emergence of AI and ESG oversight as liability vectors are all analyzed for their implications on D&O purchasing strategies. By connecting these disparate threads, the research enables boards and risk managers to anticipate rather than merely react to changing conditions.
Practical tools within the report support concrete decision-making. Guidance on policy structuring in an environment of stabilized but still elevated costs helps organizations optimize retention levels and coverage limits. Analysis of carrier appetites and underwriting trends informs negotiations and carrier selection. The competitive benchmarking framework allows organizations to assess whether their current programs reflect market standards or represent opportunities for improvement.
Strategic Decision-Making in 2026
The strategic value of this research lies in its capacity to transform market intelligence into boardroom action. As the D&O market stabilizes, organizations face a window of opportunity to re-evaluate their protection frameworks with less pressure than existed during periods of rapid premium escalation. This is the moment to audit current coverage adequacy against the evolving risk landscape, to assess whether policy structures align with organizational realities, and to engage carriers in conversations about emerging exposures that may not yet be reflected in standard underwriting questionnaires.
For public companies, the stabilization of pricing and the continuation of favorable terms into 2026 create conditions conducive to optimizing coverage without the urgency that characterized prior market cycles. Yet the underlying pressures—rising settlement values, legal cost inflation, and expanding liability theories—mean that optimization must be grounded in realistic loss scenarios rather than nominal premium considerations. Private companies, particularly those with growth trajectories or exposure to insolvency-sensitive sectors, should use this period to strengthen personal asset protection and ensure that indemnification arrangements are supported by adequate insurance backing. Nonprofit organizations, often overlooked in D&O discussions, face increasing expectations around governance and compliance, and our research addresses the specific considerations that apply to their risk profiles.
The research also supports longer-term strategic planning. As organizations look toward 2027 and beyond, the projected market trajectory suggests continued growth in D&O demand, driven by both expanding liabilities and increasing awareness of the need for protection. Boards that establish robust governance-insurance linkages now will be better positioned to manage the premium and coverage negotiations of future cycles. Understanding the competitive dynamics among carriers, the segmentation of market demand, and the macroeconomic forces shaping liability trends provides the foundation for resilient D&O strategies.
Access the Complete Intelligence
This overview has outlined the strategic context, market dynamics, competitive landscape, and practical applications that define the D&O insurance environment in 2026. The commentary provided here offers a substantive introduction to the themes and trends shaping the market, but the complete research deliverable contains detailed segmentation data, granular competitive analysis, forward projections, and actionable frameworks that cannot be fully replicated in a summary format.
Directors and Officers (D&O) Insurance Market
PW Consulting's Directors and Officers (D&O) Insurance Market research is designed for directors, officers, risk managers, corporate secretaries, and insurance procurement professionals who require more than surface-level market commentary. The full report provides the depth necessary to support policy decisions, carrier negotiations, governance enhancements, and risk transfer strategies with confidence. To access the complete intelligence—including detailed market sizing, segmentation insights, competitive benchmarking, and forward-looking analysis—visit the source webpage and obtain the full research deliverable. In a market where the difference between adequate and inadequate protection can have profound consequences for both organizations and individuals, comprehensive intelligence is not a luxury; it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Directors and Officers (D&O) Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com