

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 2D Game Market Hits $55.2B in 2025 with 7.5% CAGR to $91.6B by 2032

The Resilient Canvas: Strategic Insights into the Worldwide 2D Game Market Through 2032
The global video game industry is often defined by its relentless pursuit of graphical fidelity and immersive three-dimensional worlds. However, beneath the surface of photorealistic RTX-rendered landscapes lies a enduring powerhouse that continues to drive significant revenue and cultural relevance: the 2D game market. At PW Consulting, we recognize that while 3D innovation captures headlines, the 2D sector represents a stable, high-growth trajectory fueled by niche audiences, indie innovation, and the timeless appeal of classic gameplay mechanics. Our latest Worldwide 2D Game Market research is not merely a snapshot of current revenues; it is a strategic navigation tool designed for executives, investors, and product leaders operating within the digital entertainment ecosystem.
This comprehensive study offers a granular look at a market that has demonstrated remarkable resilience despite shifting consumer habits and technological disruptions. As the broader global video game software, add-ons, and content revenues reached an all-time high in 2025, estimated at $195 billion, the 2D segment carved out its own significant share of this expansion. Furthermore, broader industry forecasts from PwC's Global Entertainment & Media Outlook 2025–2029 suggest video game segment revenues could approach $300 billion by 2029, indicating that the ecosystem supporting 2D development remains robust. Our report contextualizes these macroeconomic signals specifically for the 2D vertical, providing the clarity needed to make informed decisions in 2026 and beyond.
Market Trajectory and Economic Drivers
Understanding the financial trajectory of the 2D game market requires more than observing current revenue figures; it demands an analysis of compound growth rates and historical stability. Our research establishes a clear baseline, tracking market performance from 2020 through the base year of 2025, and projecting forward into the forecast period of 2026 to 2032. This longitudinal view reveals a consistent upward trend, underscored by a projected CAGR of 7.5 percent over the forecast horizon.
Such growth is not accidental. It is the result of converging factors including the resurgence of retro-inspired aesthetics, the accessibility of powerful development engines, and the monetization flexibility required by modern audiences. According to recent industry analysis, including the BCG Video Gaming Report 2026, tiered pricing and subscription models are increasingly impacting 2D and indie game monetization strategies. Approximately 45 percent of gamers identify as serious fans willing to pay higher prices, while conversely, 30 percent reduce purchasing if prices rise. This dichotomy creates a complex pricing environment where developers must balance accessibility with premium value propositions. Our report dissects these revenue dynamics, offering models for how 2D titles can optimize lifecycle value without alienating price-sensitive segments.
The economic foundation of the 2D market is also supported by its diverse platform distribution. While mobile remains a dominant force in the broader gaming landscape, the 2D sector uniquely thrives across PC and console environments as well. The historical data from 2020 to 2025 shows steady revenue accumulation, with the market size expanding significantly as development tools lower the barrier to entry for independent studios. This democratization of development has led to a saturation of content, making discoverability a critical challenge. Our analysis addresses how market concentration and distribution channels influence revenue realization, helping stakeholders understand where value is being captured in the supply chain.
Competitive Landscape and Ecosystem Dynamics
The landscape of the Worldwide 2D Game Market is characterized by a mix of established legacy publishers, agile indie publishers, and critical infrastructure providers. Unlike markets dominated by a few giants, the 2D sector features a fragmented but active competitive environment. Our research provides detailed profiles of key companies that are shaping the trajectory of 2D gaming.
Worldwide 2D Game Market
On the publishing and development front, legacy powers remain vital. Nintendo Co., Ltd., based in Kyoto, continues to be a dominant player with iconic franchises like Super Mario Bros. and The Legend of Zelda series, maintaining active 2D platformer and adventure releases on Switch and other platforms. Similarly, Capcom Co., Ltd. in Osaka sustains presence through 2D fighting games such as the Street Fighter series and side-scrolling action titles, with ongoing support for 2D pixel-art and sprite-based games. Konami Holdings Corporation has also signaled renewed interest, with announced 2026 releases like Castlevania: Belmont's Curse, a new stylized 2D Castlevania game developed with Evil Empire and Motion Twin. These activities indicate that major publishers view 2D not as a relic, but as a viable, profitable genre for sustained engagement.
In the independent sector, Devolver Digital stands out as a publisher specializing in unique artistic 2D games with global distribution and marketing support for 2D platformers, puzzles, and adventures. Their model highlights the viability of niche artistic content in a crowded marketplace.
However, the ecosystem extends beyond publishers to the tools that enable creation. Unity Technologies provides the leading 2D game engine with updates for sprite animation, lighting, and atlas tools, powering thousands of active 2D game developments worldwide. In March 2026, Unity released updates to 2D game art, animation, and lighting tools in Unity 6.3 LTS, including Sprite Atlas best practices, demonstrating continuous investment in the 2D developer experience. Similarly, the Godot Foundation offers an open-source engine optimized for 2D game development, used by numerous independent studios for lightweight, cross-platform 2D titles. YoYo Games, operating under Opera in Dundee, UK, develops GameMaker Studio, a drag-and-drop tool focused exclusively on 2D game creation, widely used by indie developers for mobile and PC 2D games. Epic Games, Inc. also contributes via Unreal Engine with strong 2D paper and sprite capabilities, publishing and supporting 2D titles via the Epic Games Store.
Outsourcing and service providers form the backbone of production scalability. Keywords Studios, headquartered in Dublin, serves as a global outsourcing provider for 2D art, animation, QA, and localization services supporting 2D game production for major publishers. Virtuos in Singapore specializes in co-development, porting, and 2D/3D art production for AAA and 2D-focused games. Room 8 Group, with a global presence originally rooted in Ukraine, offers full-cycle 2D game development and art outsourcing for mobile, PC, and console 2D titles. Kevuru Games and Stepico, both based in Ukraine, focus on 2D game art outsourcing, animation, and full development for AAA and indie 2D projects, emphasizing stylized 2D games. Our report analyzes how these partners integrate into global production pipelines, noting that game development outsourcing for 2D art and animation remains active with specialized studios in Ukraine, India, and Singapore supporting global production pipelines.
Worldwide HTML5 Games Market
Segmentation and Consumer Dynamics
Strategic decision-making requires a deep understanding of how the market is segmented and who the consumers are. Our research breaks down the market across key dimensions without losing sight of the interconnected nature of these segments. We examine the distribution across regions, acknowledging that while Asia Pacific represents a significant portion of global engagement, North America and Europe maintain robust commercial ecosystems for 2D titles. Latin America and the Middle East and Africa present emerging opportunities with distinct growth characteristics.
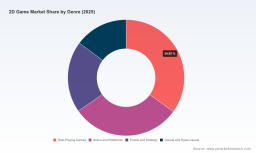
Platform segmentation is equally critical. While mobile gaming drives volume, the PC and console segments often command higher average revenue per user for premium 2D experiences. Our analysis explores how development priorities shift based on target platforms, considering factors such as input methods, session lengths, and monetization capabilities. Genre segmentation further refines this view, covering Role-Playing Games, Action and Platformer, Puzzle and Strategy, and Casual and Hyper-casual categories. Each genre presents unique development lifecycles and audience expectations. For instance, the recent teaser by Gotcha Gotcha Games in March 2026 regarding RPG Maker New Project, the first entry supporting HD-2D game creation with aesthetics similar to Octopath Traveler and Dragon Quest HD-2D remakes, highlights the specific demand for high-fidelity 2D RPG experiences.
Consumer habits are evolving, influenced by broader trends in digital entertainment. Digital competition regulations targeting large online platforms continue to evolve globally, affecting distribution and discoverability of 2D games on major stores. This regulatory noise requires publishers to diversify distribution strategies and build direct relationships with communities. Our report evaluates these regulatory risks and opportunities, providing guidance on navigating store policies and maintaining visibility in a regulated digital marketplace.
Strategic Imperatives for 2026 and Beyond
The data presented in our Worldwide 2D Game Market report converges on several strategic imperatives for stakeholders aiming to capitalize on the forecast period through 2032. First, the integration of HD-2D aesthetics and modernized retro styles represents a significant value driver. As seen with recent announcements from established IPs, there is a market appetite for 2D games that honor traditional aesthetics while leveraging modern lighting and animation tools. Companies investing in engine updates, such as Unity's recent enhancements, are better positioned to meet these aesthetic demands efficiently.
Second, monetization strategy must be nuanced. With the broader industry highlighting the sensitivity of consumer spending to price changes, 2D developers cannot rely on one-size-fits-all pricing. The BCG report's findings on tiered pricing and subscriptions suggest that flexibility is key. Successful titles may need to offer multiple entry points, from free-to-play casual experiences to premium indie titles with expansion content. Our research provides frameworks for testing and implementing these models without fragmenting the user base.
Third, partnerships and outsourcing should be viewed as strategic levers rather than mere cost-saving measures. With specialized studios in Ukraine, India, and Singapore actively supporting global production pipelines, publishers can scale art and animation production rapidly. However, quality control and cultural alignment remain paramount. Our report details the capabilities of key outsourcing providers, helping companies build resilient supply chains that can adapt to geopolitical or operational disruptions.
Finally, discoverability in a regulated environment requires proactive community building and multi-channel distribution. Reliance on a single storefront exposes developers to policy changes and algorithmic shifts. Diversifying across PC, console, and mobile platforms, while leveraging direct sales channels where possible, mitigates this risk.
Why This Research Matters for Your Strategy
In an industry saturated with noise, precise intelligence is the differentiator between speculation and strategy. The Worldwide 2D Game Market report by PW Consulting is designed to cut through the ambiguity. It provides the historical context to understand where the market has been, the granular segmentation to understand where value currently resides, and the forward-looking projections to anticipate where it is going. The 7.5 percent CAGR and the projected market valuation reaching towards $91,579.51 million by 2032 are not just numbers; they represent the scale of opportunity available for those who can navigate the complexities of development, distribution, and monetization.
However, the full depth of this intelligence—including detailed regional breakdowns, specific platform revenue splits, and comprehensive competitive benchmarking data—is reserved for our clients who require actionable precision. This article serves as a testament to the rigor and scope of our analysis, but the complete dataset contains the specific figures and strategic annotations necessary to build your 2026 business plan.
We invite industry leaders, investors, and strategic planners to access the full report to unlock the detailed intelligence required to secure a competitive advantage in the worldwide 2D game market. The canvas is evolving, and the tools to paint the future are available to those equipped with the right insights.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Game Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com