

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Global Charge Plate Monitor Market Hits $55.21M in 2025, Poised to Reach $80.22M by 2032 at 5.48% CAGR

Strategic Intelligence for the ESD Control Ecosystem: Inside the 2026 Worldwide Charge Plate Monitor Market
In an era where static sensitivity defines manufacturing yield, the humble charge plate monitor has evolved from a compliance accessory to a critical pillar of electrostatic discharge control infrastructure. Our newly released Worldwide Charge Plate Monitor Market research delivers a comprehensive, forward-looking intelligence framework designed specifically for executive decision-makers, procurement strategists, and engineering leaders navigating the 2026 operating environment. This analysis moves beyond static snapshots to map the structural forces shaping demand, pricing, technological evolution, and competitive positioning across the global ionization verification landscape.
The Strategic Imperative: Why 2026 Demands Heightened Market Intelligence
As electronics miniaturization accelerates and cleanroom protocols tighten across semiconductor, medical device, and aerospace manufacturing floors, the margin for ESD control failure has never been narrower. Charge plate monitors serve as the primary validation instruments for ionizer performance, offset voltage stability, and discharge timing accuracy within ESD Protected Areas. The operational reality of 2026 is that compliance is no longer a box-checking exercise; it is a yield protection mechanism, a cleanroom integrity safeguard, and a supply chain resilience requirement. Decision-makers who lack granular visibility into monitor adoption patterns, standardization shifts, and regional deployment strategies risk misallocating capital, underestimating total cost of ownership, or falling behind competitors who have embedded real-time ionization auditing into their production workflows.
Our research is structured to convert this complexity into actionable strategic clarity. By anchoring executive planning in verified historical trajectories and forward-looking demand modeling, organizations can align product roadmaps, distribution strategies, and compliance investments with the actual velocity of market evolution rather than relying on fragmented vendor claims or anecdotal benchmarking.
Market Trajectory and Structural Growth Signals
The charge plate monitor sector has demonstrated consistent expansion over the past half-decade, reflecting the broader tightening of ESD governance across high-precision manufacturing verticals. Historical revenue tracking from 2020 through 2025 reveals a clear upward path, with baseline valuation expanding from approximately 42.15 million USD to 55.21 million USD by the end of the base year. This trajectory has carried momentum into the early forecast window, positioning the 2026 valuation at roughly 58.78 million USD. The growth pattern is not sporadic; it reflects sustained institutional adoption of standardized ionization verification practices, coupled with incremental upgrades to portable and benchtop instrumentation across mature and emerging production ecosystems.
Looking through the 2026 to 2032 forecast horizon, the market is projected to scale toward 80.22 million USD, underpinned by a compound annual growth rate of 5.48 percent. This moderate-but-durable expansion rate signals a maturing but still actively growing category where volume gains are driven by regulatory reinforcement, broader EPA coverage, and the replacement cycle of legacy verification tools rather than speculative hype. The forecast structure accounts for cross-vertical adoption curves, technology refresh intervals, and the compounding effect of standardized testing methodologies becoming embedded into routine production auditing. For strategic planners, this CAGR represents a reliable baseline for capacity planning, inventory forecasting, and long-term supplier negotiation frameworks.
Segmentation Architecture and Demand Concentration Dynamics
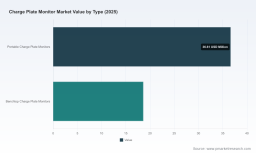
The worldwide market does not expand uniformly. Demand originates from a defined set of instrument architectures and application environments, each with distinct procurement rhythms, technical requirements, and compliance drivers. Portable and benchtop form factors anchor the hardware landscape, with portable units commanding a larger share of the deployment base due to their field-audit flexibility, collapsible configurations, and compatibility with mobile ESD auditing kits. Benchtop platforms serve higher-volume validation and laboratory-grade verification workflows, where controlled measurement conditions and sustained instrument availability drive procurement decisions.
On the application axis, demand is anchored by semiconductor and IC packaging environments, followed by electronic component assembly operations, flat panel display manufacturing, and aerospace and defense production lines. Each vertical imposes different tolerance thresholds, documentation requirements, and audit frequencies, which in turn shape instrument specification preferences, service contract structures, and regional supply chain expectations. The concentration of revenue across these verticals indicates that demand is diversified but not fragmented; a meaningful proportion of total market activity continues to flow through a limited number of high-compliance, high-throughput manufacturing contexts where ionization verification is non-negotiable.
Geographically, the market reflects a multi-pole demand structure. Asia Pacific represents the largest revenue concentration, consistent with the region's dense electronics manufacturing footprint and expanding cleanroom capacity. North America and Europe maintain substantial, structurally stable demand driven by established aerospace, medical device, and discrete semiconductor workflows. Latin America and the Middle East and Africa contribute smaller but strategically relevant shares, often tied to localized assembly expansion, technology transfer initiatives, and incremental EPA standardization efforts. The geographic distribution underscores a practical reality for suppliers and buyers alike: regional compliance cultures, service coverage expectations, and instrument preference profiles vary enough to require localized commercial strategies rather than one-size-fits-all deployment models.
Competitive Landscape: Incumbents, Differentiation, and Strategic Positioning
The competitive environment is defined by specialized instrumentation providers with deep roots in ESD control, ionizer verification, and static elimination technologies. Leading players have built their market positions not on broad consumer visibility, but on technical conformance, field reliability, and alignment with recognized testing protocols. Advanced Energy, operating through its Trek and Monroe instrument heritage, maintains a prominent presence with active charge plate monitors designed for air ionization system evaluation, offset voltage measurement, and discharge time verification. Its portfolio reflects a long-standing emphasis on audit-grade instrumentation for ESD control environments.
Simco-Ion, Technology Group continues to reinforce its standing through charged plate monitors engineered for electrostatic field measurement, ionization need determination, and ionizer performance evaluation across high frequency AC, pulsed DC, and steady-state DC configurations. The inclusion of programmable automated testing capabilities positions its offerings for environments that require repeatable, documentation-rich verification cycles. SCS, operating under Desco Industries, contributes portable charged plate monitor solutions tailored for SMT line ESD control and EPA environments, with emphasis on verifying ionizer offset voltage and discharge timing under production conditions.
Transforming Technologies, frequently referenced through its Warmbier instrumentation lineage, supplies charge plate monitors and ionizer verification meters designed around standardized test methods, reinforcing the link between instrument capability and compliance documentation. Prostat Corporation addresses field audit requirements with portable charge plate monitor assemblies built around compact, collapsible formats and defined capacitance characteristics, making them practical additions to mobile ESD auditing kits. Static Clean International rounds out the competitive field through distribution and supply of handheld charge plate monitors focused on static decay time measurement and ionizer system balance verification.
Collectively, these incumbents illustrate a market where differentiation is achieved through test method alignment, portability versus lab-grade trade-offs, automation depth, and service accessibility. The competitive intensity is not characterized by price wars alone; it is shaped by how effectively each vendor can demonstrate measurement reliability, reduce audit cycle friction, and support compliance documentation workflows across diverse production environments. Market concentration metrics indicate that a relatively small group of leading participants commands a substantial share of total revenue, reinforcing the importance of supplier evaluation criteria that extend beyond unit pricing to include calibration support, replacement part availability, and protocol familiarity.
Worldwide Charge Plate Monitor Market
Regulatory and Technical Dynamics Shaping Procurement Decisions
Standardization remains one of the most powerful demand accelerants in this category. Charge plate monitors are routinely employed to verify ionizer performance in alignment with ANSI/ESD STM3.1 test methods for ionization and ANSI/ESD SP3.3 guidance within ESD Protected Areas. As these protocols become more deeply embedded into internal quality systems and customer audit requirements, procurement teams increasingly prioritize instruments that can reliably support documented compliance rather than ad hoc spot checks. This shift favors solutions that streamline measurement repeatability, simplify data capture, and reduce interpretation ambiguity during audits.
Cold Plate Market
In medical device and life sciences manufacturing, the stakes are amplified by the intersection of ESD control and contamination control within cleanroom environments. Sensitive electronics production in these contexts requires verification tools that can operate consistently under controlled conditions while supporting both static management and broader cleanliness protocols. Instrumentation that aligns with these dual requirements tends to see stronger adoption in facilities where production validation, regulatory readiness, and cleanroom discipline must move in lockstep.
Technical design evolution also continues to influence purchasing behavior. Portable and collapsible monitor designs, including compact plate configurations with defined capacitance characteristics, have expanded the practicality of field auditing by enabling compact storage, rapid deployment, and integration into mobile ESD auditing kits. This trend is especially relevant for electronics and medical device production environments where audit coverage must extend across multiple workstations, ionizer arrays, and transient production zones without compromising measurement consistency. As a result, buyers are increasingly evaluating form factor, deployment speed, and kit integration alongside core measurement performance.
What the Research Delivers: Operational Content for Decision-Makers
This market study is constructed to support real-world strategic planning rather than abstract observation. The report provides a detailed examination of market sizing across historical and forecast periods, along with segmentation analysis that breaks down demand architecture by instrument type, application environment, and geographic exposure. Rather than leaving readers with isolated figures, the analysis connects sizing trends to the operational drivers behind them, including compliance adoption cycles, manufacturing footprint expansion, instrument replacement patterns, and regional procurement behavior.
The competitive profiling section goes beyond company descriptions to map product positioning, instrument capabilities, and strategic emphasis across the leading participants. This enables buyers, investors, and suppliers to understand where differentiation is being created, which technical features are gaining procurement relevance, and how established players are maintaining market share in a category defined by protocol adherence and audit reliability. The inclusion of recent industry context further grounds the analysis in the regulatory and technical dynamics that are actively shaping buying decisions in 2026.
Crucially, the research is designed to support scenario planning. By presenting forward-looking valuation pathways, concentration indicators, and segmentation structures, the report gives executives a framework to evaluate expansion timing, inventory strategy, channel partnerships, and compliance-related capital allocation with greater confidence. The objective is not simply to describe the market, but to provide a decision-ready architecture that can be integrated into product planning, sales targeting, and risk assessment workflows.
Conclusion: Converting Market Visibility into Strategic Advantage
The worldwide charge plate monitor market is moving with steady, structurally supported momentum. Growth is being shaped by compliance reinforcement, cleanroom expansion, instrument modernization, and the ongoing need for reliable ionization verification across high-sensitivity manufacturing environments. In this landscape, the organizations that outperform are those that treat ESD control instrumentation as a strategic asset rather than a compliance footnote.
Our Worldwide Charge Plate Monitor Market research provides the depth, segmentation clarity, and forward-looking framework required to make informed 2026 decisions. The full study contains the detailed segmentation breakdown, competitive profiling, regional deployment patterns, and forecast structures needed to translate industry visibility into procurement precision, product strategy, and commercial execution. For decision-makers ready to move from general awareness to precise market intelligence, the complete report offers the next layer of actionable insight.
For detailed analysis of this topic, please visit the official page: Worldwide Charge Plate Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com