

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Hotel Market Hits $1.23T in 2025, Projects 6.5% CAGR Through 2032

Navigating the 2026 Global Hotel Market: Strategic Imperatives in a 6.5% CAGR Landscape
As capital markets recalibrate and traveler behaviors solidify into new patterns, the worldwide hotel sector stands at a decisive inflection point heading into 2026. With macroeconomic headwinds moderating and international mobility reaching sustained recovery levels, industry leaders require a precision instrument to navigate expansion, pricing architecture, and competitive positioning. This comprehensive Worldwide Hotel Market research delivers exactly that instrument—transforming raw volume trajectories into actionable strategic roadmaps for executives, developers, investors, and brand managers operating across the global hospitality value chain.
Worldwide Hotel Market
The foundation of this analysis rests on a rigorously modeled historical baseline and forward-looking projection framework anchored to 2025 as the base year. Over the historical window from 2020 through 2025, the sector demonstrated extraordinary resilience, expanding from a base of 550 billion USD to 1,230 billion USD despite operational disruptions and shifting demand distribution. Looking ahead through the forecast horizon of 2026 to 2032, the trajectory points toward sustained compounding growth, culminating in a projected valuation that underscores long-term structural expansion. The implied compound annual growth rate of 6.5 percent reflects not merely cyclical recovery but fundamental shifts in leisure consumption, corporate travel procurement, and asset deployment strategies worldwide.
Such macro momentum masks highly differentiated regional performance, tiered segment dynamics, and application-specific demand catalysts. The strategic value of this report lies in its capacity to isolate signal from noise, enabling decision makers to allocate capital, adjust brand architectures, and anticipate regulatory or cost pressures before they reshape margin profiles. By dissecting the operational and financial realities shaping each growth vector, the publication equips stakeholders with the intelligence required to outperform in a market where top-line expansion increasingly demands disciplined bottom-line execution.
Market Trajectory Architecture and Forecasting Methodology
The analytical core of this research is built upon a transparent, multi-scenario forecasting methodology that integrates historical supply and demand signals, macroeconomic indicators, and structural industry shifts. The projection window from 2026 through 2032 maps a steady climb in aggregate revenue, with each sequential year calibrated against established momentum factors and elasticity constraints. This structured approach allows readers to test sensitivity assumptions around rate performance, occupancy distribution, and capital deployment velocity without relying on static point estimates.
To ensure operational relevance, the report deliberately avoids abstract macro commentary in favor of applied financial logic. Readers will encounter demand-side drivers translated into portfolio implications, supply-side constraints mapped to development timelines, and pricing power dynamics assessed against labor, materials, and regulatory cost environments. The integration of benchmark metrics such as global RevPAR trajectories—which reached 102 dollars in 2025, representing a 4.5 percent year-over-year uplift—grounds the analysis in measurable operational reality rather than speculative narrative. Similarly, the projected corporate travel spending trajectory approaching 1.48 trillion dollars globally in 2025 reinforces the continued commercial demand underpinning midscale and upper-tier asset performance.
Crucially, the report distinguishes between headline growth and profitable growth. Executives are increasingly struggling with the disconnect between rising traffic and compressing margins due to labor cost escalation, construction material inflation, and compliance-driven operational adjustments. By embedding these pressure points directly into segment and regional evaluation frameworks, the publication provides a realistic lens through which expansion decisions can be stress-tested before execution.
Competitive Landscape and Strategic Positioning
Market concentration in the global hotel sector remains moderately dispersed, with the top three operators accounting for approximately 18.5 percent of aggregate revenue and the top five firms controlling just under 24 percent. This structural fragmentation rewards scale where it exists, but also creates space for targeted regional dominance, brand specialization, and franchise-led expansion models. The competitive environment is therefore defined not by monopolistic gravity, but by differentiated growth postures and asset strategy sophistication.
Among the largest global operators, Marriott International continues to scale aggressively across luxury, premium, select, and longer-stay formats, with recent expansion activity centered on Asia-Pacific and Middle East growth corridors. Its December 2025 announcement of 75 newly opened properties and 14,000 added rooms illustrates a deliberate push into high-growth demand markets while maintaining brand portfolio breadth. Hilton Worldwide has taken a parallel but tactically distinct path, introducing Spark by Hilton as a midscale conversion-focused brand aimed at capturing efficiency gains in the United States and Europe. This brand-level maneuver signals how established groups are optimizing portfolio mix rather than relying solely on greenfield development.
InterContinental Hotels Group pursued a partnership-led European expansion by aligning with Tishman Speyer on a 50-property pipeline emphasizing luxury and lifestyle positioning, reinforcing the industry-wide trend of leveraging capital partners to accelerate premium supply. Accor continued its geographically diversified deployment with 40 new hotels and 6,000 added rooms concentrated in Asia and Latin America, underscoring the strategic importance of emerging market penetration for globally balanced portfolios. Meanwhile, Wyndham Hotels & Resorts reached a milestone of 9,500 properties with targeted openings in India and Southeast Asia, extending its franchise strength in economy and midscale segments. Choice Hotels International, Radisson Hotel Group, and Hyatt Hotels Corporation each contributed distinct strategic footprints—spanning North American franchise scaling, EMEA multi-brand diversification, and lifestyle and all-inclusive growth respectively—demonstrating that competitive advantage in 2026 will be derived from area-specific execution rather than uniform global growth.
What these developments collectively reveal is a market where brand architecture, partnership structuring, and geographic targeting determine relative outperformance. The full report isolates these competitive behaviors within a comparative framework that examines revenue mix, asset ownership models, conversion potential, and regional exposure, enabling readers to benchmark their own strategic posture against the industry’s most adaptive players.
Segment Dynamics and Operational Pressures
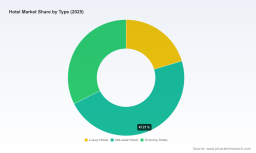
Segmentation analysis in this research avoids simplistic category breakdowns by mapping each tier against its operational cost structure, demand elasticity, and capital intensity. The luxury segment continues to command premium pricing power but faces heightened scrutiny around asset productivity and brand differentiation. Midscale properties remain the volume engine of portfolio performance, attracting conversion interest from both established groups and private capital seeking stable yield profiles. Economy-tier assets are undergoing reevaluation as labor constraints, construction inflation, and brand standardization requirements reshape their return horizons.
The operational cost environment materially influences segment viability. In the United States, hotel labor costs increased 7.2 percent year-over-year in 2025, driven by wage pressures and persistent staffing shortages across operational functions. Simultaneously, global construction material costs for hotels rose between 5 and 8 percent in 2025, pressured by volatility in steel and lumber pricing. These dual cost vectors affect new supply economics, renovation pacing, and wage budgeting for existing properties, forcing operators to balance occupancy growth against margin preservation.
Regulatory evolution introduces additional complexity. The European Union’s Digital Services Act requires online travel agents and hotel platforms to disclose total prices inclusive of all fees, reshaping booking transparency and altering consumer comparison behavior. This mandate impacts European operators and their international OTA partners, requiring updates to revenue management workflows, distribution pricing strategies, and guest communication architecture. Altogether, these dynamics demonstrate that segment-level strategy cannot be designed in isolation from cost inflation, compliance requirements, and distribution platform reforms.
Hotel Furniture Market
Demand Sources and Regional Interplay
Demand composition across leisure travel, business travel, and other purpose-driven segments continues to recalibrate in response to corporate budgeting cycles, consumer mobility preferences, and global event-driven travel patterns. Leisure demand remains a structural growth driver, supported by sustained international travel enthusiasm and extended-stay behavioral shifts. Business travel benefits from corporate expenditure recovery and the projected elevation of global corporate travel spending, reinforcing demand for midscale and upper-tier assets near commercial hubs. Alternative purpose segments contribute incremental volume through events, medical travel, and project-related mobility, often requiring specialized service models and location-specific inventory strategies.
Regionally, the interplay between mature and developing markets defines deployment priorities. North American operations continue to benefit from strong domestic demand and franchise conversion opportunities, while European markets navigate regulatory compliance and premium brand repositioning. Asia-Pacific remains a central growth axis, attracting international brand investments and domestic portfolio expansions driven by rising middle-class mobility. Latin America and the Middle East and Africa regions offer targeted growth pockets where partnership models, franchise structures, and localized brand adaptations can generate outsized returns relative to capital deployed. The complete research unpacks these regional mechanics without relying on superficial ranking tables, instead establishing the operational logic behind market entry timing, brand selection, and asset type alignment.
What This Report Delivers for 2026 Decision-Making
This Worldwide Hotel Market study is designed as an executive decision-support platform rather than a static market summary. Its architecture emphasizes practical application across corporate strategy, development planning, brand management, and investment evaluation. Readers will gain access to structured assessments of demand trajectory, competitive positioning, cost-pressure sensitivity, regulatory impact pathways, and segment-specific performance drivers. The research translates trend data into strategic questions: Where should portfolio exposure be concentrated in 2026 and beyond? Which brand tiers offer the most resilient margin profile under rising operational costs? How should international growth plans be sequenced given regional cost and compliance differences? Which competitive moves signal durable advantage rather than temporary scale?
By consolidating historical performance evidence, forward-looking forecasts, competitive benchmarks, and operational pressure analysis into a single integrated reference, the report reduces the time required to align internal teams around a common strategic baseline. Investors can apply the framework to asset allocation and risk-adjusted return modeling. Operators can use it to prioritize brand extension, conversion targets, and market-specific pricing adjustments. Developers can evaluate timing sensitivity in relation to material cost trends and labor availability. In each case, the objective is the same: replace uncertainty with structured visibility.
Accessing the Full Intelligence Architecture
The analysis presented here frames the strategic stakes and methodological rigor underpinning the full Worldwide Hotel Market research, but the complete dataset, granular segmentation pathways, regional interaction models, and detailed competitive assessments reside within the full publication. Decision makers seeking to deploy capital, reconfigure brand portfolios, or recalibrate market entry strategies will find that the complete report provides the depth necessary to translate high-level momentum into executable plans.
To access the full research framework, including comprehensive demand mapping, cost-structure sensitivity, competitive benchmarking detail, and forward scenarios through 2032, visit the source page for the complete report. The executive summary provided here establishes the strategic context; the full document delivers the operational intelligence required to act decisively in the 2026 hotel market environment.
For detailed analysis of this topic, please visit the official page: Worldwide Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com