

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Tissue Dispensers Market to Reach $2,554.55M by 2032, CAGR 5.25%

Strategic Intelligence for the Next Wave: Inside the Worldwide Tissue Dispensers Market 2026–2032
As organizations recalibrate their facility management strategies for the mid-2020s, the commercial washroom ecosystem is undergoing a quiet but decisive transformation. Tissue dispensers, long treated as commoditized fixtures, are now central to conversations around hygiene compliance, operational efficiency, and sustainability accountability. Our newly released Worldwide Tissue Dispensers Market research delivers a comprehensive, forward-looking blueprint for executives who must allocate capital, select partners, and shape product roadmaps in a market that is simultaneously maturing and fragmenting. This article previews the strategic architecture of the study, explains why its 2026 decision-usefulness is timed to current inflection points, and outlines the analytical rigor that will help leadership teams move from reactive procurement to disciplined market positioning.
Why 2026 Is a Defining Moment for Tissue Dispenser Strategy
The market has moved through a clear expansion arc over the past half-decade, with global revenue climbing from approximately 1.38 billion USD in 2020 to an estimated 1.79 billion USD in 2025. That trajectory reflects durable demand across away-from-home environments, where hygiene expectations have structurally reset and facility operators are balancing throughput, restocking labor, and material costs. The study’s forecast window, extending through 2032, projects a compound annual growth rate of 5.25 percent, positioning the sector for sustained, if uneven, expansion. For 2026 decision-making, this midpoint in the cycle matters because it is precisely when early-cycle pricing and capacity decisions begin to lock in margin profiles for the remainder of the decade.
Dispenser Pump Market
The research is built to help executives interpret that growth with precision rather than noise. Instead of presenting a single headline figure, the analysis decomposes the market across product architectures, end-user environments, operational modes, and geographic footprints, then cross-ties those dimensions to procurement cycles, compliance calendars, and channel dynamics. The result is a decision framework that can be applied to capacity planning, vendor evaluation, pricing strategy, and risk hedging. Readers who engage with the full study will find the underlying segment dimensions, regional intensity patterns, and end-user share structures laid out in a form that can be directly plugged into internal budgeting and sourcing models.
What the Research Delivers: A Practical Toolkit for Market Entry, Expansion, and Defense
The study is organized around four interlocking workstreams, each designed to translate market structure into actionable next steps.
- Macro trajectory and scenario mapping. The report grounds its forward view in a multi-year historical base and then stress-tests the 2026–2032 outlook against alternative demand pathways. This allows leadership to evaluate how shifts in commercial real estate utilization, hospitality occupancy, healthcare throughput, and public-sector budgeting could reshape volume and value over the forecast horizon.
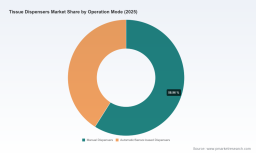
- Segment intelligence without blind spots. The analysis dissects the market by product type, including paper towel, toilet paper, napkin, and facial tissue dispensers; by end user, spanning commercial and office buildings, hospitality and tourism, healthcare facilities, and industrial and education environments; and by operation mode, contrasting manual units with automatic and sensor-based systems. Rather than stopping at descriptive splits, the study examines how these segments interact with pricing power, restocking frequency, vandal resistance requirements, and retrofit economics.
- Competitive and channel depth. A structured assessment of incumbent positioning, product architecture differentiation, and go-to-market tactics helps buyers and suppliers alike understand where differentiation is real and where it is largely cosmetic. The report also incorporates recent product launches and innovation announcements, giving readers a current read on how major players are pulling the market toward higher-capacity, touchless, and modular configurations.
- Regulatory and input-cost context. Because dispenser economics are inseparable from tissue supply and packaging accountability, the study embeds material cost signals and policy developments into its market logic. This includes producer price index behavior for sanitary tissue paper products, evolving extended producer responsibility frameworks across multiple U.S. states, and the influence of standardized testing protocols on product claims and procurement specifications.
Taken together, these workstreams create a market map that is detailed enough to support investment committee discussions yet structured enough to support rapid scenario comparison. The study deliberately surfaces enough granularity for users to recognize where their own categories sit within the broader landscape, while reserving the most decisive breakdowns for the complete report, where they can be examined alongside methodology notes, source triangulation, and full quantitative exhibits.
Competitive Architecture: Where Differentiation Is Being Won and Lost
The worldwide tissue dispensers market is not a winner-takes-all arena, but it is a disciplined one. Concentration among leading participants remains meaningful, and that concentration shapes pricing expectations, channel leverage, and the speed at which new features propagate. The research profiles a roster of established manufacturers whose strategies reveal the market’s central fault lines: durability versus aesthetics, capacity versus footprint, mechanical simplicity versus automation, and product ecosystem lock-in versus specification neutrality.
In North America, several long-tenured equipment specialists anchor the commercial washroom segment with vandal-resistant, surface-mounted and recessed designs. Bobrick Washroom Equipment, for example, has built its reputation on durable toilet tissue and paper towel dispensers, including touchless and surface-mounted models suited to demanding public environments. American Specialties, Inc. focuses on recessed and surface-mounted multi-roll toilet tissue dispensers and accessories in stainless steel, an approach that appeals to specifiers prioritizing finish consistency and theft deterrence. Palmer Fixture and Alwin Manufacturing both address the high-traffic public restroom segment through jumbo roll tissue dispensers, with ADA-compliant configurations and twin-roll options that reduce change-outs and support throughput. San Jamar contributes controlled-dispensing paper towel and bath tissue solutions, reinforcing the broader industry push toward measured consumption and reduced waste.
Alongside these equipment specialists, tissue manufacturers have expanded into dispensing systems as a way to secure away-from-home channel relevance and bundle value. Georgia-Pacific LLC provides commercial tissue dispensers and dispensing systems under brands such as Pacific Blue Ultra, pairing high-capacity automated and mechanical solutions with its tissue product portfolio. Kimberly-Clark Corporation manufactures professional dispensers including ICON and Scott systems for folded towels, bath tissue, and roll products, with an emphasis on away-from-home settings where branding, hygiene perception, and replacement logistics intersect. Essity AB, operating through its Tork brand, offers professional hygiene dispensers for hand towels, toilet tissue, and coreless systems with a strong sustainability narrative and a focus on high-traffic environments. Cascades Inc. echoes that sustainability-and-performance positioning through its PRO line dispensers and tissue products for away-from-home markets.
The competitive picture also includes specialists in modular commercial fittings and customizable branded hardware. Dolphin Solutions Ltd. supplies modular stainless steel combination paper towel dispenser and waste bin units for recessed mounting, an design-conscious answer to space-constrained commercial interiors. PROvider by WPI focuses on customizable commercial paper towel, tissue, and napkin dispensers, leaning into American-made quality and branding opportunities for facilities that want dispensers to do double duty as visual extensions of their identity.
What makes this roster strategically instructive is not simply who is present, but how recent moves reveal the market’s trajectory. In 2025, Palmer Fixture introduced a premium twin 9-inch jumbo tissue dispenser aimed at high-traffic public restrooms, a signal that capacity, ergonomics, and traffic tolerance remain competitive battlegrounds. Essity expanded its Tork professional hygiene offering with a new toilet paper system designed to complement its towel dispenser portfolio, reinforcing a systems-level approach to restroom efficiency. Kimberly-Clark enhanced its ICON dispenser line with interchangeable configurable faceplates, a reminder that upgrade paths and aesthetic flexibility are becoming important in retrofit-heavy building environments. The study uses developments like these not as isolated news items, but as evidence of how product architecture, service logic, and specification flexibility are being recombined to defend share and open new procurement windows.
Forces Reshaping Demand, Cost, and Compliance
Market performance in this category is increasingly shaped by forces that sit just outside the dispenser itself. Input costs, procurement policy, and standards expectations are converging in ways that alter both pricing and specification behavior. The research integrates these forces so that readers can evaluate demand not only by end-user type, but also by the cost environment that will govern margin and substitution decisions.
On the input side, producer price dynamics for sanitary tissue paper products have become a critical variable for anyone forecasting dispenser-adjacent economics. Recent index readings for sanitary tissue paper products made in paper mills and for those made from purchased sanitary paper stock have pointed to elevated cost levels relative to historical bases. Whether these pressures persist, ease, or propagate differently across product grades will influence tissue availability, bundle pricing, and the attractiveness of high-capacity or coreless systems that can reduce restocking frequency. The study treats these signals as part of the operating context rather than as isolated statistics, connecting them to restocking labor, waste reduction goals, and the economics of automatic versus manual dispensing.
On the regulatory side, extended producer responsibility frameworks are advancing in multiple U.S. states, with legislation in jurisdictions such as California, Colorado, Minnesota, Oregon, and Washington creating new obligations for producers of packaging and paper products. These laws increasingly require producers to fund collection and recycling programs, and some, like Minnesota’s Packaging Waste and Cost Reduction Act, phase in requirements through 2032 while introducing recyclability standards and producer responsibility organization participation. For tissue dispenser markets, the implication is twofold: sourcing and product design decisions must account for downstream accountability, and specification conversations are beginning to include material recoverability and waste management costs alongside traditional criteria like durability and capacity.
Standards also remain a quiet but essential determinant of market credibility. The ISO 12625 series provides standardized test methods and terminology for the physical properties of tissue paper and tissue products used in dispensers, giving buyers and manufacturers a common language for performance claims. In practice, adherence to standardized testing can influence specification acceptance, simplify cross-brand comparisons, and reduce the risk of post-installation dissatisfaction in high-use environments. The study incorporates these standards into its evaluation of product claims and procurement risk, because in a market where operational continuity and hygiene perception both matter, verifiable performance is a competitive asset.
How to Use This Intelligence for 2026 Decisions
The study is designed to support several concrete decision paths. For suppliers and product developers, it clarifies where capacity, automation, and specification flexibility are most likely to command premium positioning, and where commoditization risk is highest. For distributors and facility service providers, it maps the end-user environments and regional intensities that shape restocking rhythm, replacement cycles, and the appeal of sensor-based installations. For commercial real estate, hospitality, healthcare, and education operators, it provides the comparative context needed to evaluate total cost of ownership across manual and automatic options, while anticipating the compliance and material cost dynamics that will affect tissue supply over the forecast period.
Crucially, the research avoids the temptation to flatten the market into a single narrative. It preserves the analytical separation between product architectures, end-user needs, operational modes, and regional conditions so that executives can identify which combinations matter most to their own exposure. That structure is what makes the report useful not just as a market snapshot, but as a decision instrument that can be revisited as assumptions change.
What Remains Inside the Full Study
This preview has outlined the strategic logic, competitive architecture, and macro dynamics that frame the worldwide tissue dispensers market for 2026 planning. To make the analysis fully operational, the complete study goes further. It details the underlying segment breakdowns by region, product type, end user, and operation mode; presents the quantitative context that allows readers to see where value concentrates and how share is distributed among leading participants; and pairs those exhibits with methodological notes and source triangulation so that each conclusion can be traced and challenged. It also extends the competitive review into recent developments, product launch signals, and the operational implications of input-cost and regulatory shifts.
Worldwide Tissue Dispensers Market
For teams that need to move from direction to detail, the full report offers the segment-level precision, competitive benchmarking, and scenario structure required to support sourcing decisions, investment cases, and product roadmap choices. The macro arc, the competitive patterns, and the compliance and cost pressures described here all find their complete expression in the study’s exhibits and commentary. Engaging with the full analysis will give decision-makers the resolution they need to convert market awareness into concrete 2026 action.
For detailed analysis of this topic, please visit the official page: Worldwide Tissue Dispensers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com