

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Peeling Machines Market to Hit $557.5M by 2032 at 5.45% CAGR

Navigating the Global Peeling Machines Market: Strategic Intelligence for Agribusiness Leaders in 2026
Executive Overview
The global peeling machines market stands at a critical inflection point as 2026 unfolds, shaped by accelerating automation adoption, evolving food safety mandates, and shifting raw material economics. After a decade of steady valuation growth, the sector now presents a complex interplay of technological innovation, regional capacity shifts, and competitive realignment that demand careful strategic navigation by equipment manufacturers, food processors, and supply chain investors.
Our latest Worldwide Peeling Machines Market analysis delivers a comprehensive, data-grounded assessment designed specifically for executives who must calibrate capital allocation, product roadmaps, and partnership strategies across the forecast horizon of 2026 through 2032. This article outlines the strategic architecture of the study, explains how its framework translates into actionable decision-making, and highlights the critical intelligence layers that separate reactive operations from market-defining positioning.
Market Trajectory and Structural Momentum
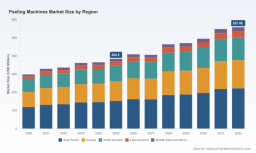
The worldwide peeling machines industry has demonstrated consistent expansion over the past half-decade, with market valuation climbing from approximately USD 298 million in 2020 to an estimated USD 384.5 million by 2025. This progression reflects enduring demand across plant-based and protein processing supply chains, compounded by incremental upgrades in throughput efficiency and hygiene compliance. Entering 2026, the market is positioned at USD 409.17 million, and our baseline trajectory projects sustained growth through the end of the forecast window, reaching roughly USD 557 million by 2032.
The compound annual growth rate across the 2026-2032 period is estimated at 5.45 percent, a figure that captures more than simple volume expansion. It reflects a transition toward higher-value processing configurations, where conventional mechanical designs are increasingly supplemented by sensor-guided, abrasive, and ultrasonic alternatives. In practical terms, the growth vector is not merely about deploying more units; it is about deploying smarter installations that reduce waste, improve food safety profiles, and compensate for tightening labor availability across commercial kitchen, contract manufacturing, and industrial scale environments.
Strategic planners should note that the 2025-2026 transition reveals a market that has absorbed earlier pandemic-era disruptions, logistics volatility, and equipment lead-time constraints. Current operating conditions are more normalized, but they are being re-shaped by a different set of forces: raw material pricing behavior, regional capacity realignment, and intensifying differentiation among technology providers. The report frames these dynamics not as isolated variables, but as interconnected levers that influence pricing architecture, procurement cycles, and service expectations throughout the value chain.
Technology Portfolio Shifts and Input Cost Realities
Within the equipment landscape, steam-based peeling systems continue to command substantial share by value, supported by their suitability for high-throughput environments and established operational familiarity. Abrasive and knife-based configurations remain important complements, each addressing distinct product shapes, skin characteristics, and throughput requirements. Chemical-based solutions occupy a smaller but strategically meaningful position, often leveraged where uniform skin removal and gentle handling are prioritized over maximum mechanical speed. The report maps these technology categories to processing realities rather than treating them as abstract categories, allowing readers to evaluate where certain mechanisms align with specific use cases, labor profiles, and sanitation protocols.
A crucial layer of analysis concerns material economics. Stainless steel remains the dominant construction material for food-grade peeling machinery due to its corrosion resistance, cleanability, and compatibility with stringent sanitary design expectations. Early 2026 pricing intelligence indicates that stainless steel in Northeast Asia was trading near USD 1.79 per kilogram in March 2026, with the broader global stainless steel market projected to approach USD 146.1 billion in the same year. Prices across the first quarter of 2026 stayed range-bound with a slight upward bias in select regions, influenced by steady industrial demand and alloying element cost behavior. These material dynamics matter because they feed directly into unit economics, retrofit decision timing, and the cost advantage calculus between refurbishing legacy lines versus specifying newer builds.
At the same time, regulatory expectations around hygienic design and easy-to-clean surfaces continue to reinforce the case for food-grade materials and integrated sanitary engineering. This is not simply a compliance issue. In many procurement environments, sanitation performance and cleaning cycle efficiency are becoming as influential as throughput metrics, particularly where processors are consolidating lines to maximize utilization and reduce downtime. Our analysis treats these operational pressures as core drivers of specification choices, not peripheral considerations.
Competitive Landscape and Differentiation Battles
The market is moderately concentrated, with three leading players accounting for a combined share of approximately 42.15 percent and the top five collectively representing around 58.6 percent. Concentration at this level indicates a landscape where scale, established distribution networks, installation expertise, and after-sales service can confer meaningful advantages. At the same time, the presence of numerous specialized manufacturers ensures that niche capability, regional responsiveness, and application-specific innovation remain viable competitive entry points.
Several names illustrate the breadth of competitive strategies currently in play. Sormac B.V., based in the Netherlands, develops and manufactures peeling machines for a wide fruit and vegetable assortment including potatoes, beets, celery, carrots, melons, watermelons, pumpkins, and cucumbers. Its product range includes knife peelers and specialized configurations such as CBS/MBS and UP-4000 series, with recent live demonstrations at a January 2026 trade show highlighting melon, onion, and vegetable peeling models. ASTRA Inc., headquartered in Japan, focuses on automatic fruit peeling machines optimized for apples, citrus, kiwi, orange, mango, and pineapple, emphasizing fast and high-quality results across formats like the KA-700H, KA-750PM, and FAP series, including a July 2025 release of an industrial pineapple peeler and corer built for simultaneous high-speed peeling and coring.
Other participants reflect different strategic emphases. Vanmark Equipment LLC, operating from the United States, manufactures potato and produce processing equipment spanning peelers, washers, and complete lines for chips, fries, and vegetable processing. TOMRA Food, based in Norway, provides advanced peeling and sorting solutions that leverage laser-based and sensor technologies for high-capacity automated processing. Hobart, also US-based, supplies commercial kitchen equipment including potato and vegetable peelers for professional foodservice. Dornow Food Technology GmbH, in Germany, provides abrasive and knife peeling machines and complete plants for potatoes and vegetables at various scales, while FAM, from Belgium, is regarded as a global leader offering innovative peeling solutions including ultrasonic approaches. Additional contributors such as Finis-Eillert, JBT Corporation, Electrolux Professional, Sammic, Metos, Boema SpA, Herbort Food Production Machinery, FROSFOOD, Fujimak Corporation, and others expand the competitive field with regional strengths and application-specific ingenuity.
Recent activity shows that exhibition presence and timely new product introductions remain important market-shaping tools. Participation at major industry events in early 2026, alongside launches of higher-speed or application-specific machines during the prior year, signals that firms are actively competing on throughput, precision, hygiene, and ease of integration rather than on price alone. The report uses these developments not as isolated news, but as indicators of where competitors are betting on future demand and how their positioning may influence procurement negotiations, replacement cycles, and service expectations.
Application Realities and Operational Decision Drivers
From an application standpoint, fruit and vegetable processing continues to be the largest demand center, reflecting the breadth of fresh-cut, ready-to-eat, and processed produce categories. Root and tuber processing represents another significant demand cluster, driven by the scale of potato, tuber, and root-based product pipelines that include fresh-cut items, chips, fries, and downstream processed goods. Seafood and meat processing, while smaller in relative terms, remains strategically relevant where precise skin, scale, or surface preparation is necessary to standardize yield and presentation. An additional set of miscellaneous applications rounds out the portfolio, often tied to specialized formats and mixed-product environments.
Depaneling Machine Market
Rather than presenting these categories as static share splits, the analysis connects them to procurement behavior. Different applications impose different requirements on peeling uniformity, waste reduction, changeover flexibility, sanitation, and maintenance intensity. A processor scaling output for fresh-cut produce may prioritize gentle handling and appearance consistency, while a high-volume fry or chip operation may value durability, line integration, and labor reduction above all else. The report’s framework is designed to help decision-makers translate these application-level needs into equipment specifications, service arrangements, and technology mix choices.
Automation trends are intensifying across the sector, largely as processors seek to offset labor shortages and improve throughput predictability. This shift supports demand for efficient peeling machines incorporating advanced knife, abrasive, and sensor-based technologies. Where automation is implemented thoughtfully, it can reduce variability, improve food safety outcomes, and free skilled labor for oversight and exception handling. Where it is implemented without proper integration planning, it can create hidden costs in cleaning, maintenance, and changeover. The study examines these tradeoffs explicitly so that capital planning is informed by operational reality rather than by automation as an abstract goal.
Why This Study Matters for 2026 Strategy
Time-sensitive capital and supply chain decisions are already being made across the industry, whether in the form of line expansion, technology retrofitting, regional sourcing adjustments, or supplier evaluation. In that environment, a well-structured market study functions less as a general reference and more as a decision support system. The Worldwide Peeling Machines Market report is designed to provide several practical outputs:
Core Report Contents Designed for Execution
- A structured assessment of market size evolution from 2020 through 2032, with the 2025 base year and 2026-2032 forecast anchored to observed historical behavior and forward-looking sector dynamics.
- An integrated view of technology categories, application contexts, and regional demand patterns, presented so that procurement, product development, and market entry teams can compare alternatives without relying on oversimplified aggregates.
- Competitive profiling that extends beyond corporate descriptions to address positioning, product emphasis, application specialization, and recent market-facing activity, including trade show presence and product introductions.
- Contextual analysis of material economics, hygienic design requirements, and automation trends as they affect equipment specification, total cost of ownership, and replacement timing.
- Decision-oriented framing that links macro trends to practical questions: which configurations are likely to be favored in high-throughput processing environments, how sanitation and labor pressures influence specification, and where differentiated capability can support pricing and retention.
What makes the study particularly relevant for 2026 is its timing. Market participants are operating in a period where demand is no longer simply rebounding from earlier disruption; it is being re-shaped by structural factors such as labor availability, hygiene expectations, material pricing, and the push toward more integrated, sensor-informed processing systems. The analysis is built to help executives interpret those forces in combination rather than in isolation, allowing them to assess not just what is happening, but what it implies for budgets, vendor selection, capacity planning, and competitive posture over the next several years.
Intelligence That Connects to Action
Executives rarely need more data for its own sake; they need better synthesis. The report is structured to support questions that arise in real decision cycles: whether to standardize on a particular peeling technology family across multiple facilities, how to evaluate suppliers with different regional support footprints, where material cost trends may affect the timing of retrofit versus replacement, and how to interpret competitor moves in exhibitions and new product announcements as signals of future competitive intensity.
The competitive analysis, for example, is built to help readers understand that scale advantage and specialization advantage are not mutually exclusive. Larger players may benefit from broader parts and service coverage, while specialized manufacturers may win on application fit, changeover speed, or unique peeling behavior for specific product types. The presence of multiple firms with overlapping yet distinct capabilities suggests a market where procurement teams can negotiate meaningfully, but only if they have a clear internal view of the performance attributes that matter most to their operations. The report supplies that interpretive structure.
Similarly, the material and regulation context is not presented merely as background information. Instead, it is linked to practical implications. If stainless steel pricing remains range-bound with periodic upward pressure where industrial demand and alloying costs persist, then budgeting for equipment, spare parts, and service contracts should account for input variability rather than assume flat cost assumptions. If hygienic design and easy-to-clean surfaces are increasingly important in specification reviews, then total cost of ownership calculations must give appropriate weight to sanitation time, cleaning chemical usage, and maintenance labor, not only to the initial purchase price. The study connects these factors so that financial and operational teams can plan on a consistent basis.
Accessing the Full Strategic Picture
A preview can indicate capability, but it cannot replace the complete evidentiary architecture. The full report contains the detailed market segmentation, forecast tables, competitive profiles, company-level recent developments, and contextual analysis necessary for a rigorous strategic review. It also includes the granular comparisons and interpretive guidance that allow readers to move from macro awareness to specific procurement, investment, and product decisions. Because the study deliberately focuses on presentation logic and decision relevance, the complete version is the appropriate instrument for teams that must defend recommendations to internal stakeholders, set multi-year plans, or assess supplier and partner options with confidence.
Worldwide Peeling Machines Market
For organizations active in food processing equipment, contract manufacturing, produce and tuber supply chains, or industrial automation-enabled kitchen environments, the worldwide peeling machines market in 2026 is not a peripheral concern. It is a functional node within broader issues of yield, hygiene, throughput, labor strategy, and capital efficiency. The report is designed to give decision-makers a clearer line of sight into those connections, with enough analytical discipline to support action across the 2026-2032 horizon.
To access the full dataset, detailed segmentation, competitive dossiers, and contextual analysis referenced here, visit the source page for the complete Worldwide Peeling Machines Market report and secure the complete intelligence package required for 2026 planning.
For detailed analysis of this topic, please visit the official page: Worldwide Peeling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com