

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Strategic Imperatives in the Conductive Fibers Market: A 2026 Decision-Maker's Outlook
The global conductive fibers market has matured from a niche materials segment into a critical enabler of technological convergence across electronics, textiles, and industrial manufacturing. As enterprises navigate the 2026 landscape, decisions surrounding material selection, supply chain localization, and R&D allocation increasingly hinge on granular market intelligence. This article outlines the strategic contours of the Worldwide Conductive Fibers Market, drawing from recent performance data and emerging industry dynamics to illustrate why comprehensive market research is indispensable for capital allocation and competitive positioning in the coming cycle.
Organizations that fail to align their product roadmaps with the shifting economics of conductive materials risk ceding ground to rivals who treat functional textiles as strategic assets rather than commodity inputs. The following analysis synthesizes the macroeconomic trajectory of the sector, examines the competitive architecture among key material suppliers, and highlights the operational and regulatory factors that will define profitability through 2032.
Trajectory of Market Expansion: Interpreting the Growth Curve
Historical revenue data reveals a steady accumulation of market value over the past half-decade, with the sector transitioning from incremental growth to a phase characterized by compounding expansion. In the 2020 base year, the global conductive fibers market generated approximately 870.7 million USD in revenue. By 2025, that figure reached 1250.0 million USD, reflecting an ecosystem that has absorbed increased capital investment, technological maturation, and broader commercial adoption across end-use industries.
Electrically Conductive Textiles Market
Looking forward, the forecast period from 2026 through 2032 projects a compound annual growth rate of 7.5 percent. This trajectory suggests that the market will surpass the 1500 million USD threshold in the near term and continue its ascent toward the 2000 million USD range before the decade concludes. The sustainability of this expansion is not merely a function of volume but of value migration: high-performance fiber architectures are capturing premium pricing in smart textile and advanced EMI applications, while cost-optimized conductive solutions are simultaneously penetrating broader industrial and anti-static use cases.
Decision-makers analyzing this growth curve must recognize that top-line expansion does not distribute evenly across material classes or geographic corridors. The research framework unpacks these divergences, mapping how specific fiber typologies align with distinct application requirements and how regional procurement patterns reflect both industrial maturity and emerging demand centers. Rather than treating the market as a monolith, the study segments the opportunity landscape to reveal where capital efficiency and product differentiation intersect.
Navigating Competitive Architecture and Strategic Positioning
Defining the Player Ecosystem
The conductive fibers market is characterized by a moderately fragmented competitive structure. The top three firms collectively account for approximately 22.5 percent of total market revenue, while the top five firms consolidate their footprint at roughly 34.8 percent. This concentration pattern indicates that while established material science conglomerates maintain significant influence, there remains substantial operational space for specialized manufacturers who compete on technical differentiation, application-specific engineering, and supply chain agility.
Prominent participants span multiple geographies and material competencies, reflecting the interdisciplinary nature of the market. Japanese material leaders such as Toray Industries, Inc. and Teijin Limited contribute advanced conductive fiber portfolios tailored for smart textiles, electronics integration, and sustainable advanced fiber solutions across automotive and medical domains. In Europe, Bekaert leverages its Bekinox® stainless steel fiber and yarn platform to serve smart textile, e-textile, data transmission, and durable EMI shielding applications, while Shieldex produces silver-plated conductive yarns and fibers for antistatic, antimicrobial, EMI shielding, and smart textile uses.
North American firms contribute critical technological depth across polymer-based and metalized fiber platforms. 3M Company supplies conductive fibers and related materials for EMI shielding, electrostatic dissipation, and high-performance industrial applications, while DuPont de Nemours, Inc. provides conductive fiber technologies integrated into advanced materials for electronics, wearables, and protective applications. Shakespeare Polymers & Filaments specializes in carbon-suffused nylon and polyester conductive fibers for electrostatic dissipative performance in ESD carpeting, industrial, and textile applications. Syscom Advanced Materials, operating under the Agsis brand, develops highly conductive yarns and fibers tailored for wearable technology and demanding engineering applications. Eeonyx Corporation emphasizes knitted conductive textiles and fibers designed for flexibility and comfort in wearable electronics, and Swift Textile Metalizing LLC focuses on metalized and conductive textile fibers for aerospace, defense, and EMI shielding applications.
In Asia, Haining Taierxin New Materials Co., Ltd. manufactures conductive filament yarns, conductive staple fibers, and anti-static fabrics for electronics, smart garments, and industrial protective clothing, while Kolon Industries, Inc. produces high-performance fibers including conductive variants for textiles and industrial applications. Seiren Co., Ltd. adds further depth with conductive textiles and fibers focused on smart clothing, automotive, and functional fabric solutions.
Recent Developments Reshaping Competitive Dynamics
Competitive positioning is being actively reshaped by product and portfolio developments that signal how firms intend to capture margin in adjacent application spaces. In January 2026, Haining Taierxin New Materials Co., Ltd. positioned itself as a leading manufacturer setting benchmarks in functional textiles, emphasizing conductive filament yarns and staple fibers for smart garments and EMI shielding. This portfolio positioning reflects a broader industry pattern in which regional manufacturers pursue technical credibility in high-value segments rather than competing solely on cost.
Prior to that, in January 2025, DexMat announced the launch of Galvorn C conductive yarn featuring high strength of 800 MPa, lower resistivity, and lower density, targeting advanced performance applications. Developments of this nature matter because they illustrate the directionality of material innovation: performance improvements in tensile strength, resistivity, and density directly influence design feasibility in wearable electronics and durable industrial deployments. Firms seeking to enter or expand within the conductive fibers value chain must evaluate whether their partner ecosystem can support these elevated performance thresholds without compromising scalability or cost discipline.
Market Dynamics Shaping the 2026 Competitive Environment
Demand Drivers and End-Use Capitalization
The demand environment for conductive fibers is being shaped by an expanding constellation of end-use requirements. Rising demand for smart wearables and e-textiles is accelerating innovation in flexible, durable conductive fibers with improved washability and signal transmission capabilities. This demand signal is not confined to consumer-facing product categories; it is also driving industrial investment in functional fabrics that must perform reliably under repeated mechanical stress, laundering cycles, and environmental exposure.
Anti-static and industrial safety applications continue to represent a foundational pillar of market consumption, particularly where electrostatic dissipation is critical to operational integrity in sensitive manufacturing and processing environments. At the same time, the wearable electronics and smart textiles domain has emerged as a growth engine that incentivizes material suppliers to refine stitchability, stretch tolerance, and long-term conductance stability. EMI shielding applications add a further dimension to demand, especially as electronic packaging becomes more compact and electromagnetic compatibility requirements intensify across automotive, healthcare, and communication equipment categories.
Material Economics and Supply-Side Considerations
Cost architecture remains a decisive factor in how conductive fibers are selected and deployed. Silver-coated and stainless steel fibers are widely used in conductive yarns, yet their economic profiles differ substantially. Stainless steel offers a significant cost advantage over silver while maintaining conductivity suitable for textile integration. For procurement and product strategy teams, this distinction is not merely a technical footnote; it structures volume planning, margin envelopes, and supplier selection criteria across applications where performance tolerances can accommodate steel-based solutions.
At the same time, premium silver-based solutions remain strategically important for applications where signal integrity, antimicrobial function, or higher conductivity thresholds justify the material premium. A rigorous market research perspective does not assume a single material winner across all use cases; instead, it maps the cost-performance frontier so that businesses can determine where stainless steel, carbon-based, metal-coated, or conductive polymer fibers provide the optimal balance of price, durability, and functional efficacy.
Regulatory Expectations and Quality Standards
Regulatory and standards-related expectations are becoming increasingly central to commercial viability. Conductive fiber products must comply with evolving safety standards and certifications for electrical conductivity, washability, and durability in smart textile and EMI shielding applications. Compliance requirements influence not only product design and testing protocols but also market access timelines, customer qualification cycles, and the credibility of supplier claims. Organizations entering this market must treat regulatory alignment as a strategic capability, not a downstream compliance task, because certification outcomes can determine the pace at which new fibers are adopted by risk-sensitive end users.
Worldwide Conductive Fibers Market
What the Research Delivers for Executive Decision-Making
A comprehensive market research study on conductive fibers provides more than headline growth figures. For 2026 decision-making, the value lies in structured, actionable intelligence that connects market sizing with the operational realities of product development, sourcing, and competitive positioning. The study is designed to support multiple decision contexts, from investment prioritization and portfolio strategy to supplier evaluation and market entry planning.
Central to the analysis is a detailed examination of market segmentation by region, type, and application. This segmentation enables readers to understand how revenue and growth are distributed across the major demand geographies and how material typologies align with specific application requirements. Rather than leaving executives to infer these dynamics from aggregate data, the report isolates the relative weight of each segment, helping teams assess where demand momentum is strongest and where competitive intensity is likely to intensify.
The research also builds a competitive landscape profile that examines the capabilities, positioning, and recent strategic moves of leading firms. By profiling companies across material categories and geographic bases, the study equips readers with a comparative framework for evaluating partnership opportunities, benchmarking internal R&D trajectories, and anticipating shifts in supplier power. Recent developments are incorporated directly into this competitive narrative, ensuring that the analysis reflects current portfolio actions rather than static corporate descriptions.
In addition, the study integrates market dynamics that shape near-term commercial outcomes. These include demand-side drivers, material cost considerations, and regulatory certification requirements that affect product viability. By embedding these dynamics into the analytical structure, the research helps organizations anticipate constraints and opportunities that could influence pricing, adoption speed, and market share retention.
The forecast component extends the analysis through 2032, giving readers a multi-year planning horizon. This forward-looking dimension is essential for capital-intensive decisions such as capacity expansion, long-term supplier contracts, and material innovation roadmaps. Executives can use the projection framework to test scenarios, set performance benchmarks, and evaluate how different growth assumptions might alter strategic priorities across the forecast window.
Translating Research into Actionable Strategy for 2026
For leaders operating in or adjacent to the conductive fibers ecosystem, the strategic implication of this market environment is clear: advantage will accrue to organizations that integrate materials intelligence into their broader commercial strategy. That integration requires more than awareness of growth trends. It requires an understanding of how segment economics, competitor actions, material cost differentials, and standards compliance interact to shape achievable positioning.
Companies evaluating product expansion can use the segmentation analysis to identify application overlaps where their existing capabilities may be extended into conductive fiber markets with lower barriers to entry. Organizations seeking supply chain resilience can use the competitive profiles and regional data to diversify sourcing strategies and reduce dependence on narrowly concentrated supply bases. Firms investing in innovation can benchmark recent product developments to determine whether their performance targets are aligned with the trajectory of customer expectations in wearable electronics, industrial safety, and EMI shielding.
The research also supports negotiation and partnership strategy. Because market concentration remains moderate, there is real scope for buyers and suppliers to structure relationships that balance cost efficiency with performance assurance. Understanding which firms occupy leadership positions in specific segments, and what recent portfolio moves suggest about their strategic intent, can inform supplier selection and joint development opportunities.
Why Detailed Intelligence Matters Now
The conductive fibers market is entering a phase where differentiation will depend on the precision of market understanding. Aggregate growth is encouraging, but execution depends on knowing which segments offer the most favorable risk-adjusted returns, which material platforms provide strategic flexibility, and how competitor activity is reshaping customer expectations. The Worldwide Conductive Fibers Market research study is built to provide that level of insight with the depth required for high-stakes planning.
Complete segment-level data, competitive positioning details, and forward-looking scenario analysis are presented in full within the report, enabling stakeholders to move from strategic curiosity to operational clarity. For executives responsible for product strategy, sourcing, or market expansion in 2026, the research offers a structured path to informed action.
To access the full analytical framework, segment breakdowns, and competitive intelligence needed for your strategic planning, we invite you to review the complete Worldwide Conductive Fibers Market research at the source page, where the complete dataset and detailed commentary are available for deeper evaluation.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tilt & Turn Window Market Hits $648.5M in 2025, Forecasted to Reach $927.2M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for 2026: Navigating the Worldwide Handles of Tilt & Turn Windows Market
As the global construction and fenestration sectors enter a phase of redefined sustainability mandates and supply chain recalibrations, the handles of tilt and turn windows market stands at a critical inflection point. Beyond their obvious mechanical function, these components now embody broader industry priorities: energy performance, security integration, architectural minimalism, and smart home interoperability. PW Consulting's latest Worldwide Handles of Tilt & Turn Windows Market research has been engineered to equip corporate leaders, product strategists, and procurement executives with the contextual intelligence required to make confident 2026 decisions. This report does not merely track historical movement; it maps the structural forces that will determine competitive positioning through 2032.
The recent trajectory of the market underscores a clear expansion narrative. From a base of approximately 510.45 million USD in 2020, global revenue has progressed through successive growth cycles to reach an estimated 648.5 million USD in 2025, with forward projections placing the market at roughly 704.35 million USD in 2026 and advancing toward 927.2 million USD by 2032. This expansion reflects a compound annual growth rate of 5.23 percent across the forecast horizon, a pace that signals sustained structural demand rather than cyclical recovery. For executives evaluating capacity planning, geographic expansion, or product portfolio upgrades, these figures establish the operational urgency of aligning internal roadmaps with external market momentum. The underlying growth is not abstract; it is anchored in regulatory tightening, material innovation, and the accelerating replacement of legacy window systems in both mature and emerging building markets.
Anatomy of the Competitive Field
The handles of tilt and turn windows market is defined by a concentrated yet highly specialized competitive architecture. Our analysis places the collective market share of the top three participants at 31.4 percent, while the top five firms collectively hold 38.25 percent. This moderate concentration indicates a landscape where scale matters, yet differentiated engineering, design credibility, and regional compliance capabilities continue to create meaningful entry and expansion opportunities. Rather than a unidimensional pricing competition, the field rewards manufacturers who can harmonize materials science, locking reliability, aesthetic finish, and after-installation service ecosystems.
German and Central European manufacturers dominate the technical and design discourse, building on decades of standardized inward-opening window architecture. HOPPE has built its reputation through an extensive portfolio spanning multiple design series and material options, supported by integrated security concepts tailored to European-style tilt and turn systems. Gretsch-Unitas (G-U) reinforces this positioning with aluminum turn handles and accessories engineered for modern architectural aesthetics, optional key or push-button locking, and compliance with recognized European testing frameworks. MACO contributes a hardware systems perspective, supplying compatible handles for aluminum, timber, and PVC profiles while emphasizing multi-point locking coordination and fabrication efficiency. Roto Frank extends the technical frontier through corrosion-resistant hardware platforms designed for long-term functional performance in aluminum systems, with concealed hinge configurations that align with contemporary minimalist facades. Siegenia has pushed further into connected building ecosystems, advancing smart window handles that integrate security and comfort functions while preparing for Matter-compatible smart home environments. Winkhaus complements this mix with tilt and turn hardware systems that support high-performance sash configurations, including flush sash concealed hinge solutions.
Outside the core European cluster, the competitive map broadens in ways that reveal strategic diversification. ASSA ABLOY Fenestration leverages global reach to deliver specialized hardware for aluminum window applications, including solutions for non-standard geometries such as round tops and trapezoid profiles, with finishes engineered for corrosion resistance. Trojan maintains a value-and-performance orientation in the UK market, supplying handles suited to uPVC and related profiles. FPL Hardware addresses North American demand through series developed for casement and tilt-turn applications, while Formani positions itself at the premium architectural end of the spectrum, emphasizing understated design language and award-recognized product lines suited to European systems. Together, these players illustrate how material selection, regional code requirements, and application intent continue to fragment the market into distinct value propositions.
Market Dynamics Shaping 2026 Decision-Making
The strategic landscape for handles of tilt and turn windows is being reshaped by overlapping forces: regulatory acceleration, raw material economics, and the rising expectation that fenestration hardware must integrate with broader building performance and connectivity goals. Understanding these dynamics is essential because they directly influence demand timing, cost structures, and product roadmap priorities.
Regulatory Pressure as a Demand Catalyst
European policy momentum has become a decisive driver for high-performance window hardware. The EU Energy Performance of Buildings Directive establishes minimum energy performance standards with renovation targets that push residential buildings toward performance improvements by 2030, alongside requirements addressing the least efficient non-residential stock. These mandates stimulate demand for window systems and compatible hardware that can contribute to airtightness, thermal control, and long-term durability. In parallel, the UK Future Homes Standard and updates to Part L continue to emphasize improved U-values and air permeability, reinforcing the adoption of tilt and turn configurations that can satisfy stricter energy efficiency expectations. For suppliers and system integrators, this regulatory environment is not simply a compliance burden. It is a demand catalyst that favors hardware capable of supporting energy-conscious installation practices and repeatable performance.
Material Economics and Manufacturing Realities
Material cost dynamics remain a critical factor for planning and pricing. Aluminum and zinc alloys continue to serve as core materials for tilt and turn window handles, with metal-based solutions forming the majority of production across the broader door and window hardware sector. At the same time, producer price pressures have entered the equation. In 2025, the producer price index for aluminum mill shapes increased by 22.8 percent compared with the prior year, affecting manufacturing costs for metal window hardware components. This cost environment rewards manufacturers that have invested in supply chain resilience, production efficiency, and material substitution strategies, while also highlighting the importance of transparent cost-to-value communication with downstream customers. Executives evaluating sourcing strategies must therefore weigh not only performance specifications, but also volatility exposure and regional procurement flexibility.
Hardware Products of Doors & Windows Market
Performance Expectations Beyond the Handle Itself
Market expectations increasingly treat the handle as part of a broader system rather than an isolated accessory. International demand for aluminum tilt and turn windows continues to grow due to their versatility, security characteristics, and energy performance potential. In response, hardware systems are being designed with corrosion resistance, compatibility across profile types, and adaptability to special window shapes in mind. This system-level perspective influences product development in two important ways. First, it pushes manufacturers to ensure that handles, locking mechanisms, and opening geometries work cohesively across multiple substrates and installation conditions. Second, it elevates the importance of fabrication support and technical documentation, since window producers and installers increasingly depend on integrated solutions that reduce on-site variability.
What the Report Delivers for 2026 Strategy
This study is structured to convert market intelligence into operational clarity. Rather than stopping at aggregate size and growth rates, the report connects demand signals to the decision points that matter most to supplier strategy, channel planning, and product investment. The analysis combines quantitative market structure with qualitative evaluation of technology direction, competitive positioning, and regulatory influence. Readers will find a detailed examination of how the market is segmented by geography, material composition, and end-use application, along with the strategic implications embedded in those splits. The report also examines competitive interaction patterns, including how established players differentiate through design language, security features, manufacturing scale, and smart integration capabilities.
Importantly, the study integrates the latest industry developments that are shaping near-term market behavior. Recent activity includes the January 2026 launch of Siegenia's second-generation smart window handle with Matter compatibility, alongside a concealed tilt sash locking drive showcased at FENSTERBAU 2026; Roto North America's January 2025 promotion of aluminum hardware platforms emphasizing aesthetic design, corrosion resistance, and long-term performance; and ActivWall's March 2026 exhibition of a new Tilt & Turn window at the International Builders' Show. These developments are not isolated news items. They signal how manufacturers are aligning product launches with trade visibility, smart home interoperability, and the ongoing push toward energy-conscious, design-sensitive window systems.
The report further provides practical frameworks for interpreting market concentration, evaluating regional demand characteristics, and assessing material-type trends without relying on short-term conjecture. It outlines where value is being created through premium design, where cost efficiency remains decisive, and where technical differentiation such as multi-point locking, concealed hardware, or smart connectivity is reshaping buyer expectations. For organizations planning product launches, capacity allocation, or partnership strategy, these insights are designed to reduce uncertainty and sharpen prioritization.
Why This Intelligence Matters Now
The 2026 outlook for handles of tilt and turn windows is defined by the intersection of regulatory urgency, material cost sensitivity, and system-level performance demands. In such an environment, companies that rely on backward-looking assumptions risk misallocating resources or entering product segments with misaligned positioning. This PW Consulting study is built to support forward-looking decisions: identifying where durable growth is most likely to emerge, where competitive intensity will intensify, and where differentiated capabilities will command premium value.
The full research unpacks the underlying segmentation logic, the competitive coordination patterns among leading manufacturers, and the forward demand scenarios that will shape planning through 2032. Because the most actionable detail is embedded in the complete dataset and strategic commentary, the complete intelligence is available through the source page. For executives who need to move from awareness to action, the full report provides the depth required to align product strategy, sourcing decisions, and regional expansion plans with the market's actual structure rather than its surface signals. In a segment where performance, design, and compliance increasingly converge, that clarity is the foundation of durable commercial advantage.
Worldwide Handles of Tilt & Turn Windows Market
For detailed analysis of this topic, please visit the official page: Worldwide Handles of Tilt & Turn Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Portable Gaming Console Market Hits $16.5B in 2025, Poised to Reach $30.1B by 2032
By pmarketresearch, 2026-09-16
Navigating the Pocket-Sized Future: Strategic Intelligence for the 2026 Portable Gaming Console Market
The portable gaming landscape is undergoing its most significant structural transformation in over a decade. As the line between dedicated handhelds, PC-based gaming devices, and cloud-streaming endpoints continues to blur, enterprise leaders across hardware manufacturing, software ecosystems, retail distribution, and semiconductor supply chains are confronting a fundamental strategic question: where will the next wave of portable entertainment revenue originate, and how should organizations position themselves to capture it? The Worldwide Portable Gaming Consoles Market study, grounded in historical data from 2020 through a base year of 2025 and projecting through 2032, provides the analytical architecture required to move beyond reactive product cycles and instead make informed, forward-looking capital and product allocation decisions.
At the macro level, the trajectory is unambiguous. Global revenue in this category has expanded steadily from 8,450.0 million USD in 2020 to 16,500.0 million USD by 2025, reflecting a compound annual growth rate of 8.98 percent across the forecast window extending to 2032. The modeled expansion does not plateau abruptly; rather, the revenue curve continues to climb toward 18,053.73 million USD in 2026 and projects toward a 30,127.12 million USD ceiling by the end of the forecast period. For strategy teams, these trajectory markers are not merely headline validation. They signal sustained consumer willingness to pay for portable experiences, the maturation of hybrid home-and-portable product architectures, and the growing monetization of PC-grade handheld ecosystems alongside traditional retro and Android-focused submarkets. Yet aggregate growth numbers tell only half the story. The strategic value of this research lies in its decomposition of those top-line movements into actionable decision layers, from console-type adoption shifts and channel-specific purchase behaviors to regional demand intensity and supply-side cost pressures.
Gaming Laptop Market
Why 2026 Is a Pivotal Inflection Point
The portable gaming market is no longer defined solely by cartridge-driven or cartridge-adjacent dedicated devices. The emergence of high-performance Windows-based handhelds, Linux-centric PC gaming portables, and cloud-anchored streaming endpoints has fractured legacy segmentation and forced manufacturers, platform holders, and retail partners to recalibrate. Historical spend patterns from 2020 through 2025 demonstrate that demand momentum has been consistently upward, but 2026 represents a moment where execution discipline separates sustainable market share growth from short-lived hype cycles. Several dynamics converge to make this year particularly decisive.
Worldwide Portable Gaming Consoles Market
First, silicon and subsystem architecture are shifting rapidly. Ecosystem players are explicitly linking next-generation performance leaps to major architectural improvements rather than incremental refreshes, with public development commentary emphasizing that meaningful gains must be paired with battery life retention and thermal management discipline. This creates an environment where product roadmaps cannot be optimized for peak specification alone; they must balance performance density, power efficiency, and supply feasibility. Second, component cost volatility has moved from an abstract risk to a near-term operational reality. Recent market signals indicate that pricing pressures tied to high-density DRAM demand, advanced display panel requirements, and broader semiconductor sourcing constraints are influencing product launch timing and pre-order cadence for premium handhelds. Organizations that treat component procurement as a static backdrop will find their margin assumptions and channel pricing strategies misaligned with reality. Third, regulatory and compliance frameworks around energy efficiency and lithium-ion battery safety continue to evolve across regions, increasing the non-negotiable cost of compliance for any device seeking global distribution. The market research contextualizes these dynamics within the broader revenue model, enabling teams to stress-test product economics against real-world constraints rather than idealized specification sheets.
What the Report Delivers: Tactical Intelligence Over Generic Trends
This study is structured to support concrete operational decisions rather than high-level narrative. It maps the historical and forecast revenue path across multiple interlocking dimensions, allowing strategy, product marketing, supply chain, and channel management teams to isolate where growth is concentrating and where margin erosion or saturation risk is emerging. The analytical framework is deliberately multidimensional:
- Historical baseline and forward trajectory mapping across the 2020 to 2032 window, anchored by a 2025 base year and consistent USD million revenue units, so that organizational planning can be reconciled with a single coherent model.
- Console-type segmentation that distinguishes dedicated gaming handhelds, PC-based handheld consoles, and Android and retro handhelds, enabling firms to evaluate where their product strategy intersects with high-volume mainstream segments versus niche or value-oriented categories.
- Regional demand distribution across five major geographic territories, helping organizations align go-to-market priorities, localized pricing strategies, and distribution partnerships without assuming uniform growth intensity across markets.
- Distribution channel mapping across online retail, offline specialty stores, and mass merchandisers, giving retail and channel teams visibility into where consumer acquisition is concentrated and how omnichannel mix decisions may affect inventory planning and promotional allocation.
- Competitive intensity and concentration analytics, reflecting a market environment where a relatively small group of ecosystem participants commands the majority of revenue share, while specialized brands retain relevance through targeted product positioning and platform differentiation.
- Company-level profiles and recent development tracking that connect product launches, concept unveilings, pre-order adjustments, and platform integration moves to market-level implications, so that competitive intelligence is tied directly to revenue and positioning consequences.
- Supply-side and industry context overlays covering component cost trends, advanced display and memory demand, battery safety and energy efficiency certification requirements, and geopolitical trade dynamics affecting advanced semiconductor sourcing, all of which feed into realistic cost structure and time-to-market assumptions.
Each lens is designed to translate directly into a decision support function. Pricing strategy teams can use channel and segmentation views to evaluate where premium positioning is defensible and where promotional elasticity is already priced in. Supply chain and procurement teams can benchmark component cost pressures against forecast revenue growth to determine whether margin protection should come from bill-of-materials optimization, channel mix shifts, or product tiering. Product planners can reference recent development patterns to anticipate where platform ecosystems are converging and where fragmentation creates opportunity for differentiated portable experiences.
Competitive Architecture: Ecosystem Leaders, Specialist Innovators, and the Fragmentation Reality
The portable gaming market’s competitive structure is defined by a combination of dominant platform ecosystems and specialized hardware players that compete through performance, price, and ecosystem access rather than sheer scale. Concentration metrics in the research indicate that a small cohort of leading participants commands a substantial share of total revenue, while a longer tail of manufacturers serves distinct consumer segments through curated value propositions. This duality matters because it shapes both pricing power and market entry risk.
Ecosystem-anchored players remain central to the market’s direction. Nintendo’s hybrid console approach continues to anchor mainstream portable and home-integration demand, reinforced by a recent platform generation that emphasizes backward compatibility and expanded hybrid utility. This positions the company as a volume and ecosystem anchor within the broader handheld landscape. Parallel to that, PC gaming-centered ecosystems are expanding the definition of portable hardware. Valve’s Linux-based portable PC gaming approach maintains a strong presence through a dedicated software library and a publicly acknowledged roadmap that prioritizes architectural improvements over minor refreshes. Meanwhile, partnerships linking Windows-based portable hardware with major console ecosystems are reshaping the competitive center of gravity, particularly as premium handhelds target high-performance AAA portable gaming through advanced processor architectures and ecosystem-integrated subscription and library services.
Beyond platform anchors, a meaningful layer of specialist innovators is driving differentiation in form factor, operating model, and target audience. Premium Windows and Android-focused handheld manufacturers continue to compete on compactness, performance density, and display technology, with concepts such as foldable display configurations pointing toward new usage paradigms that blend handheld play with larger-screen versatility. On the value and enthusiast side, budget-oriented Android and Linux-based emulation devices address retro gaming and accessible portable entertainment, sustaining a distinct demand segment that may not drive headline platform ecosystem growth but nevertheless contributes to category breadth and price-point diversity. Cloud-gaming-anchored devices further extend the category boundary by decoupling local compute requirements from the gaming experience, positioning portable hardware as a client endpoint within broader streaming service models.
Recent developments underscore that competitive positioning is not static. Product launches spanning hybrid console refreshes, Windows-based AAA-targeted handhelds, and ecosystem-integrated PC portables illustrate how quickly hardware roadmaps are converging around performance, library access, and platform integration. At the same time, selective pre-order adjustments tied to component cost escalation and publicly discussed development timelines that emphasize architectural necessity over release cadence reveal that execution risk remains material. Organizations reading the market only through launch announcements risk missing the underlying dynamics: component sourcing feasibility, silicon readiness, and supply proportionality are increasingly decisive in determining which premium devices reach consumers at intended specifications and price points. The research places these developments within a competitive concentration framework, enabling leadership teams to assess not only who is active, but how durable their positioning is likely to be as cost structures and platform expectations evolve.
Decision-Makers Should Use This Research To Answer Five Strategic Questions
For enterprise planning in 2026, the market study is most valuable when it is used to sharpen specific strategic judgments rather than to confirm broad optimism. The report is designed to support the following lines of inquiry:
- Where is revenue growth concentrating across console types, and does our portfolio allocation match the demand mix we expect to see through 2032 rather than the mix that prevailed five years ago?
- How should channel strategy adapt if consumer acquisition continues to skew toward specific retail models, and what inventory, pricing, and promotional commitments follow from that mix?
- What combination of component cost pressure, certification requirements, and geopolitical sourcing constraints is realistic for our next product cycle, and where do margin risks emerge if we assume steady cost conditions?
- Which competitive positions are anchored by ecosystem breadth and backward compatibility, and which are dependent on transient specification advantages that may erode as next-generation silicon and platform integrations arrive?
- How do regional demand differences influence where we prioritize distribution partnerships, localized product positioning, and compliance investment?
These questions cannot be answered credibly by tracking launch headlines alone. They require a structured view of historical momentum, forecast trajectory, segmentation behavior, channel economics, concentration dynamics, and supply-side realism. The report provides that structure, allowing strategy teams to convert market intelligence into planning assumptions that can be defended in executive discussions and operationalized across product, commercial, and supply functions.
Access the Full Intelligence Model
The portable gaming market is expanding, but expansion alone does not create competitive advantage. Advantage comes from understanding where growth is structurally concentrated, how device categories and channels are reallocating demand, where cost and compliance pressures will shape product economics, and which competitive positions are durable versus contingent. The Worldwide Portable Gaming Consoles Market study was built to deliver precisely that level of decision-grade clarity.
This article has outlined the strategic contours and the decision framework, but it does not reproduce the full segmentation data, regional demand values, channel-specific revenue splits, or the complete competitive and supply-side detail that underpin the model. Those elements are central to the report’s operational value and are preserved in the full dataset and analysis. To evaluate how the 2026 to 2032 trajectory applies to your portfolio, pricing, channel mix, and supply strategy in concrete terms, access the complete research suite and review the underlying segmentation, concentration, and company-level intelligence in detail.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Gaming Consoles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide WiFi as a Service Market Hits $8,354.2M in 2025 with 19.52% CAGR through 2032
By pmarketresearch, 2026-09-16
The Strategic Shift to Connectivity-as-a-Subscription: Inside the Global WiFi as a Service Market
The New Infrastructure Imperative
Enterprise connectivity is undergoing a fundamental architectural transformation. The traditional model of large upfront capital expenditures for network hardware, followed by periodic refreshes and manual maintenance, is being steadily displaced by operational expenditure frameworks that treat wireless infrastructure as an ongoing service. This transition is not merely a financial engineering exercise. It reflects a deeper operational reality: as organizations deploy more distributed locations, support hybrid workforces, and integrate IoT and edge computing workloads, the burden of managing complex wireless environments has outpaced the capabilities of many internal IT teams. WiFi as a Service addresses this gap by bundling hardware, cloud management, analytics, and ongoing support into predictable subscription models.
For leadership teams evaluating infrastructure roadmaps in 2026, understanding the trajectory of this market is no longer optional. It is a strategic necessity that touches capital allocation, vendor selection, compliance posture, and competitive positioning. The Worldwide WiFi as a Service Market study we have just published maps this transition with granular precision, offering a decision framework that moves beyond high-level trends to the operational and financial details that actually drive procurement choices.
Market Trajectory and the Scale of the Opportunity
The numbers tell a clear story of accelerating adoption. The global WiFi as a Service market reached approximately 8,354 million USD in 2025, up from 3,420 million USD in 2020. That represents a compound annual growth rate of roughly 19.52 percent across the historical period, and the momentum carries strongly into the forecast window. By 2026, the market is projected to surpass the 10 billion dollar threshold, climbing to 11,965 million USD in 2027 and continuing its ascent through 2032, when it is expected to reach 29,106 million USD. These figures are not abstract growth statistics. They signal a structural reallocation of enterprise networking budgets toward recurring service models, with subscription-based procurement now accounting for a meaningful share of new wireless deployments.
What matters for strategy leaders is not just the headline growth, but the composition of that growth. The market is expanding across every major organizational scale, vertical industry, and geographic region, though the pace and drivers vary considerably. Large enterprises and small-to-medium businesses are both converting significant portions of their wireless spend into as-a-service contracts, but for different reasons. Large organizations are drawn to centralized cloud management, integrated security, and the ability to scale deployments across dozens or hundreds of sites without proportional headcount growth. Smaller enterprises value the reduced operational complexity, predictable billing, and access to enterprise-grade features that were previously out of reach. The study breaks down these adoption patterns across components, organization sizes, verticals, and regions, providing a nuanced view of where demand is concentrated and where untapped potential remains.
Market Concentration and Competitive Dynamics
The vendor landscape reflects both the maturity of the underlying technology and the intensity of competition. The top three players command a combined market share of roughly 41.35 percent, while the top five extend that concentration to approximately 57.8 percent. This level of consolidation indicates that scale, platform integration, and ecosystem partnerships are becoming decisive advantages, yet it also leaves substantial room for specialized providers and regional operators to compete on service quality, industry-specific features, and localized support.
Several established networking leaders anchor the competitive field. Cisco Meraki continues to push cloud-managed wireless forward with subscription-based licensing that spans from simplified SMB offerings to full-scale enterprise deployments, including recent enhancements to its Meraki Go WiFi 6E subscription service for small businesses. Hewlett Packard Enterprise, through its Aruba Central platform, has expanded its as-a-service subscription models for access points and edge services, most recently deepening integration with Microsoft Azure for edge computing workloads. Extreme Networks delivers WiFi as a Service through its ExtremeCloud IQ platform, offering opEx subscription options for WiFi 6 and 6E access points alongside advanced analytics, and has moved to certify the platform for WiFi 7 support in enterprise environments. Ruckus Networks, operating under CommScope, has focused on high-density scenarios, deploying its cloud-managed WiFi as a Service across hundreds of European hospitality sites with AI-driven optimization. Fortinet differentiates through security integration, bundling wireless access with Secure SD-WAN in subscription models. Ubiquiti provides cloud-hosted management for its UniFi access points, while Rogers Communications serves the Canadian enterprise market with managed multi-location deployments. Purple, formerly GNS, has carved a distinct position by embedding guest analytics and marketing tools into its wireless service, particularly for retail and hospitality environments worldwide.
These profiles are only the starting point. The full study examines competitive positioning, partnership strategies, product lifecycle moves, and the specific ways each player is adapting to regional regulatory requirements and evolving customer expectations.
Industry Catalysts and the Forces Reshaping Demand
Several concurrent developments are accelerating the shift toward WiFi as a Service. On the infrastructure side, the availability of unlicensed spectrum in the 6 GHz band, as enabled by recent FCC actions, has expanded the capacity needed for WiFi 6E and WiFi 7 deployments, which are critical for supporting the density and throughput demands of modern as-a-service models. At the same time, access point costs for subscription-based deployments typically range between 500 and 1,500 dollars per unit when bundled with cloud management, making the financial case for opEx models increasingly attractive, especially for organizations that want to avoid large upfront procurement cycles.
On the regulatory front, compliance is becoming a more prominent factor in vendor selection and deployment architecture. The European Union Data Act mandates data portability for cloud-managed WiFi services, a requirement that took effect in September 2025 and directly influences how multinational organizations structure their wireless contracts and data governance policies. In China, cybersecurity regulations continue to require local data storage for in-country operations, adding complexity for global providers and creating opportunities for vendors that can navigate these constraints effectively. These regulatory pressures are not isolated concerns. They shape everything from contract terms and data residency options to the geographic distribution of managed services infrastructure.
A broader macro trend reinforces the financial appeal: recent enterprise surveys indicate that approximately one in four new WiFi purchases is now made through subscription services rather than traditional capex procurement. This shift reflects a growing comfort with recurring models among finance and IT leadership, particularly in environments where agility, scalability, and reduced operational overhead are prioritized over asset ownership.
What the Study Covers: A Practical Toolkit for Decision-Makers
The Worldwide WiFi as a Service Market report is designed to move beyond market narrative and into actionable intelligence. It provides a structured foundation for procurement planning, vendor evaluation, and investment prioritization. The study includes:
- A comprehensive market sizing framework covering historical performance from 2020 through 2025 and a detailed forecast extending to 2032, with revenue expressed in millions of USD and a clearly defined compound annual growth rate across the forecast horizon.
- Segmentation analysis across components, organization size, vertical industry, and geographic region, allowing leaders to benchmark their own deployment patterns against broader adoption trends and identify high-growth segments aligned with their strategic objectives.
- Detailed competitive profiles of leading providers, including headquarters location, product and service positioning, subscription models, and recent strategic moves such as product launches, partnerships, certification updates, and deployment expansions.
- An examination of market dynamics driven by regulation, infrastructure economics, macro procurement shifts, and regional compliance requirements, helping organizations anticipate constraints and opportunities before they affect procurement timelines.
- Contextual analysis of how cloud management, edge integration, security bundling, and analytics capabilities are influencing vendor selection across different industry verticals and organizational scales.
Each section is built to support concrete decisions. Whether the objective is to evaluate whether an as-a-service model fits a particular multi-site rollout, to compare subscription structures across vendors, to understand the implications of regional data regulations, or to forecast budget requirements over the next several years, the study provides the granularity needed to move from strategic intent to execution.
Strategic Implications for 2026 Planning
For organizations entering 2026 with infrastructure decisions on the table, the WiFi as a Service market offers both opportunity and complexity. The growth trajectory suggests that subscription-based wireless will continue to capture a larger share of enterprise networking spend, but the optimal path depends on context. A retail chain focused on guest experience and location analytics will evaluate providers differently than a healthcare system prioritizing secure, compliant connectivity across distributed facilities. A multinational operating across North America, Europe, and Asia Pacific must weigh differing regulatory frameworks, data residency expectations, and regional support capabilities. Even within a single organization, the calculus may differ between headquarters, remote branches, and temporary or seasonal sites.
Worldwide WiFi as a Service Market
The study is structured to help leaders navigate these nuances. It does not prescribe a one-size-fits-all answer. Instead, it equips decision-makers with the market context, segmentation insights, competitive intelligence, and dynamic factors required to build a tailored strategy. The goal is to enable confident choices about vendor selection, contract structure, deployment phasing, and risk mitigation, particularly as regulatory requirements and technology capabilities continue to evolve.
Access the Full Intelligence
The macro figures and competitive snapshots outlined here represent only the opening layer of the analysis. The complete study delivers the detailed regional breakdowns, component and vertical splits, organization-size comparisons, vendor-specific strategic assessments, and forward-looking scenario context that procurement leaders, IT strategists, and investors need to make informed commitments. For organizations that require a full view of market size trajectories, segmentation distributions, concentration metrics, and the evolving regulatory and infrastructure landscape, the full report is available for review and download.
In a market growing at nearly twenty percent annually and reshaping how enterprises procure, manage, and secure wireless infrastructure, the difference between reactive purchasing and strategic planning is substantial. The Worldwide WiFi as a Service Market study is built to close that gap, providing the depth and structure required to turn market intelligence into executable strategy in 2026 and beyond.
Worldwide Infrastructure as a Service Market
For detailed analysis of this topic, please visit the official page: Worldwide WiFi as a Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Self-Checkout Market Hits $5.8B in 2025, Projects 13.01% CAGR to 2032
By pmarketresearch, 2026-09-16
The Self-Checkout Revolution: Strategic Insights for the 2026 Retail Landscape
The retail sector stands at a critical inflection point. As we move through 2026, the integration of self-checkout technologies has transitioned from a novel convenience to a fundamental component of operational strategy. For enterprise leaders, investors, and technology partners, understanding the trajectory of this market is no longer optional—it is essential for navigating the complexities of modern commerce. PW Consulting's latest comprehensive study, the Worldwide Self-Checkout in Retail Market report, offers a definitive roadmap through this evolving terrain.
This analysis is not merely a collection of statistics; it is a strategic asset designed to inform capital allocation, technology procurement, and long-term planning. By examining the interplay between macroeconomic drivers, technological innovation, and competitive dynamics, this research equips decision-makers with the intelligence required to thrive in an increasingly automated retail environment.
Market Trajectory and Macroeconomic Context
The global self-checkout market has demonstrated remarkable resilience and growth over the past half-decade. Between 2020 and 2025, the market expanded significantly, rising from a baseline of approximately 3.12 billion USD to over 5.83 billion USD in 2025. This historical performance underscores the accelerating adoption of self-service technologies across diverse retail formats, driven by shifting consumer preferences and operational necessities.
Looking forward, the forecast period from 2026 to 2032 projects sustained momentum. The market is anticipated to reach new heights, with revenue expected to surpass 6.76 billion USD in 2026 and continue its ascent toward 13.73 billion USD by 2032. This growth path is underpinned by a compound annual growth rate of 13.01 percent, signaling a robust expansion phase that outpaces many traditional retail infrastructure segments. Such figures indicate that self-checkout is not peaking but rather entering a mature growth stage where innovation and integration become the primary value drivers.
The year 2025, serving as the base year for this analysis, captures a market that has already weathered significant macroeconomic volatility, including labor fluctuations and regulatory shifts. The transition into the 2026-2032 forecast window provides a critical lens for evaluating how retailers will adapt to these enduring pressures while scaling their self-checkout deployments.
Core Market Drivers and Industry Dynamics
Several converging forces are propelling the adoption of self-checkout systems globally. Chief among these is the persistent pressure on labor costs and availability. Retailers are increasingly seeking to optimize staffing levels at checkout lanes to manage operational expenses, a trend that continues to accelerate deployment rates. Concurrently, regulatory updates regarding overtime salary thresholds in major markets have prompted chains to revisit scheduling and automation strategies, further incentivizing the shift toward self-service models.
However, the landscape is not without its complexities. The regulatory environment is tightening, particularly concerning data privacy. Multiple new state privacy laws enacted in 2025 have increased compliance requirements for retailers utilizing systems that collect customer data via cameras, sensors, or payment integrations. Furthermore, the retail sector's privacy maturity currently lags behind global averages, with data breaches costing an average of 3.91 million USD. Self-checkout systems handling biometric or vision data necessitate enhanced security measures under these expanding laws, adding a layer of strategic consideration to technology selection and deployment.
Despite some retailers scaling back or limiting self-checkout in high-shrink locations due to theft concerns, overall global terminal shipments reached nearly 205,000 units in 2024, with continued adoption observed in Europe and other key regions. This dichotomy highlights the need for nuanced strategies that balance loss prevention with the efficiency gains of automation.
Worldwide Self-Checkout in Retail Market
Technology Evolution and Solution Segmentation
The technological backbone of the self-checkout market is diversifying rapidly. The market is broadly categorized by solution types, ranging from cashless systems to traditional cash-based interfaces. Cashless systems currently represent the larger share of revenue, reflecting the global shift toward digital payments and contactless transactions. However, cash-based systems remain relevant in specific markets and demographic segments, ensuring a inclusive approach to checkout technology.
Component-wise, the market is driven by hardware solutions, which encompass the physical kiosks and scanning equipment. Software solutions and associated services form the remaining critical pillars, enabling the intelligence, user interface, and maintenance ecosystems that keep these systems operational. The integration of these components determines the overall efficacy and customer experience of the self-checkout process.
End-user adoption varies across retail formats. Hypermarkets and supermarkets remain the dominant segment, leveraging self-checkout to manage high transaction volumes and reduce queue times. Convenience stores are also a significant segment, adopting compact solutions to maximize floor space and throughput. Department stores and specialty stores follow, utilizing these systems to enhance the shopping experience in specific contexts. The ability to tailor solutions to these diverse environments is a key differentiator for technology providers.
Self-service Kiosk Market
Competitive Landscape: Innovation Among Key Players
The market is characterized by a concentrated competitive environment, with a few major players holding a significant share of the landscape. The top three companies account for a substantial portion of the market presence, while the top five entities collectively command over 86 percent of the market concentration. This consolidation highlights the high barriers to entry and the importance of scale, integration capabilities, and proven reliability in this sector.
Leading companies are actively reshaping the market through product innovation and strategic partnerships. NCR Voyix Corporation, based in Atlanta, continues to expand its footprint with cloud-based self-checkout solutions featuring modular hardware and real-time software updates. Their focus on AI-enabled kiosks and integration with loss prevention systems positions them at the forefront of adaptive checkout models. In early 2026, NCR Voyix highlighted its next-generation cloud-based solution, emphasizing enhanced efficiency and modular designs.
Diebold Nixdorf, Inc., headquartered in North Canton, Ohio, has made significant strides in AI-driven security and efficiency. Their introduction of Vynamic Smart Vision Shrink Reduction exemplifies the industry's move toward using computer vision to mitigate shrinkage, verify age-restricted items, and improve transaction speed for non-barcoded products. This enhancement addresses critical pain points for grocery and convenience retailers, bridging the gap between automation and loss prevention.
Toshiba Global Commerce Solutions, located in Durham, North Carolina, delivers customizable kiosks and software tailored to diverse retail formats. Their emphasis on operational efficiency and hybrid checkout models allows retailers to blend self-service with traditional assisted lanes, providing flexibility in store layouts.
In the Asia Pacific region, Fujitsu Limited supplies U-Scan systems, including RFID-enabled and computer vision solutions for fast, contactless scanning. Fujitsu, in collaboration with GK Software, recently conducted a hackathon to pioneer new retail solutions, including self-checkout enhancements, reflecting the growing adoption in European markets such as Germany, where fixed self-service checkouts have increased significantly.
Other notable players are carving niches through specialization. ITAB Group specializes in hardware and store solutions with a strong European presence. ECR Software Corporation develops hardware and CATAPULT software for traditional and departmental retail installations, supporting multiple payment types. StrongPoint ASA provides automation solutions with a focus on digitalizing physical commerce.
The hardware and component ecosystem is also robust. Zebra Technologies supplies rugged scanners and mobile integration for high-traffic settings. Honeywell International Inc. provides scanning and sensing technologies to improve accuracy. Datalogic S.p.A. delivers vision-based solutions for kiosks. Gilbarco Inc. focuses on convenience retail and fuel station integrations.
Emerging innovators are pushing the boundaries of user experience. Mashgin Inc. offers AI-powered computer vision solutions that bypass traditional barcodes for frictionless retail experiences. Partner Tech USA Inc. launched the 'Paula' compact tabletop AI-powered kiosk, focusing on efficiency and shrink reduction in retail and QSR environments. Companies like Pan-Oston Corporation, Pyramid Computer GmbH, MetroClick, Qingdao CCL Technology Co., Ltd., and Slabb Inc. contribute to the diverse hardware and software landscape, each bringing unique design and integration capabilities to the global market.
Regional Nuances and Deployment Strategies
While the market grows globally, regional dynamics play a crucial role in shaping deployment strategies. North America remains a primary engine of growth, reflecting the high penetration of technology and the mature retail infrastructure in the region. Europe follows as a significant market, driven by labor cost pressures and a strong acceptance of self-service technologies among consumers. The Asia Pacific region presents unique opportunities, with rapid urbanization and changing shopping habits fueling demand. Latin America and the Middle East and Africa, while smaller in current valuation, represent emerging frontiers where infrastructure development and retail expansion could unlock substantial growth over the forecast period.
Understanding these regional variations is essential for multinational retailers and technology vendors. Regulatory frameworks, cultural preferences, and payment infrastructures differ markedly across these geographies. A strategy that succeeds in North America may require adaptation for the European or Asian markets. This report provides the granular context needed to navigate these differences without relying on a one-size-fits-all approach.
Strategic Value for 2026 Decision-Making
For executives and strategists operating in 2026, this research offers actionable intelligence across several dimensions. First, it provides a clear benchmark for market sizing and growth expectations, enabling accurate revenue forecasting and investment planning. The projected trajectory through 2032 allows organizations to align their long-term roadmaps with market reality.
Second, the analysis of competitive dynamics helps identify potential partners, acquisition targets, or areas of differentiation. By understanding the capabilities and recent moves of key players, businesses can refine their vendor selection criteria or develop counter-strategies to maintain competitive advantage. The detailed profiles of companies reveal strategic focuses, such as AI integration, cloud architecture, or specific retail format specialization.
Third, the examination of market drivers and regulatory factors equips risk managers and compliance officers with the knowledge to anticipate challenges. The evolving landscape of data privacy laws and labor regulations requires proactive planning. This report highlights these dynamics, allowing organizations to build resilient operations that can adapt to regulatory changes without compromising efficiency.
Finally, the segmentation data offers insights into where the value lies within the market. Whether a company is focused on hardware manufacturing, software development, or end-user deployment, understanding the revenue distribution across components, solution types, and end-user segments is vital for targeting resources effectively. The report illuminates these splits, guiding stakeholders toward the most promising opportunities.
Conclusion and Access to Comprehensive Intelligence
The Worldwide Self-Checkout in Retail Market is a dynamic, high-growth sector poised to redefine the retail experience. As automation becomes increasingly intertwined with daily commerce, the ability to make informed, data-driven decisions will separate leaders from laggards. PW Consulting's latest research delivers the depth, breadth, and strategic context necessary to navigate this transformation with confidence.
While this overview highlights the macro trends, competitive landscape, and strategic implications, the full report contains the detailed quantitative analysis, specific segmentation data, and granular regional insights required for precise execution. To unlock the complete intelligence and secure a comprehensive understanding of the market's future, we invite you to explore the full study. Access the detailed report to gain the proprietary data and expert analysis needed to drive your strategy forward in this critical market.
For detailed analysis of this topic, please visit the official page: Worldwide Self-Checkout in Retail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Business Travel Insurance Market Hits $18.5B in 2025, Poised for $31.4B by 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global International Business Travel Insurance Plans Market (2026–2032)
The landscape of corporate mobility is undergoing a profound transformation, reshaping the risk management frameworks that multinational enterprises rely upon to protect their most valuable assets—human capital. As organizations navigate a complex environment defined by fluctuating geopolitical stability, evolving regulatory mandates, and the relentless push toward global operational integration, the International Business Travel Insurance Plans Market has emerged as a critical instrument of strategic governance. This latest market research from PW Consulting offers a comprehensive examination of the sector, providing decision-makers with the analytical rigor required to make informed allocation, partnership, and compliance choices throughout the forecast horizon.
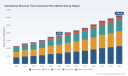
Drawing on historical performance data and forward-looking modeling, the analysis establishes a clear trajectory for the industry. Between 2020 and 2025, the global market expanded from approximately 11.5 billion USD to a projected 18.5 billion USD, reflecting sustained momentum driven by the gradual recovery and subsequent acceleration of cross-border corporate activity. Looking ahead to the 2026–2032 forecast period, the sector is expected to grow at a compound annual growth rate of 7.85 percent, reaching an estimated 31.4 billion USD by the close of the decade. These figures underscore a market transitioning from reactive risk mitigation to proactive, value-added protection ecosystems. For executives tasked with balancing cost containment against employee safety and regulatory compliance, understanding the structural forces behind this expansion is no longer optional—it is foundational to enterprise resilience.
Yet macroeconomic aggregates only tell part of the story. The real strategic leverage lies in grasping the nuanced segmentation dynamics, concentration patterns, and competitive maneuvers that will determine which providers deliver sustained service quality, adaptive coverage architecture, and scalable claims infrastructure. This research report is engineered to translate raw market data into actionable intelligence, equipping finance leaders, risk managers, procurement specialists, and travel operations directors with the frameworks needed to evaluate policy portfolios, assess vendor capabilities, and align insurance procurement with broader corporate travel strategies.
Market Trajectory and Structural Expansion Drivers
The growth profile of the International Business Travel Insurance Plans Market reflects a confluence of macro-level shifts that are fundamentally altering how organizations approach duty of care, mobility budgeting, and workforce protection. Over the historical review window, revenue progression has been characterized by consistent year-over-year gains, with the most pronounced acceleration occurring as corporate travel volumes returned to pre-pandemic baselines and subsequently surpassed them in several key verticals. The forecast period extends this upward curve, projecting steady expansion as enterprises institutionalize travel risk management as a core operational function rather than an ancillary administrative task.
Several structural catalysts are fueling this sustained expansion. First, multinational corporations are increasingly formalizing duty of care obligations, recognizing that the legal, reputational, and human costs of inadequate travel protection far exceed the premiums required to secure comprehensive coverage. Regulatory environments across multiple jurisdictions are reinforcing these expectations, prompting organizations to audit existing policy frameworks and adopt solutions that offer transparent coverage boundaries, rapid emergency response, and scalable administration across employee populations. Second, the proliferation of specialized product architectures—ranging from single-trip coverage for episodic assignments to multi-trip and annual policies for high-frequency business travelers—is enabling firms to match insurance structures to distinct mobility profiles, reducing coverage gaps while optimizing cost efficiency. Third, the freelance economy, independent consulting, and hybrid workforce models are expanding the addressable user base beyond traditional corporate travel cohorts, creating new demand streams that providers are actively targeting through tailored plan designs.
From a competitive structure perspective, the market exhibits moderate concentration, with the top three participants collectively commanding roughly one-third of total industry revenue and the leading five players accounting for just under half of the overall market. This distribution suggests a landscape where scale advantages exist but have not yet foreclosed competitive differentiation. Mid-tier and specialized insurers retain meaningful opportunities to capture share through niche product innovation, exceptional claims resolution, and superior digital user experiences. For procurement teams and risk directors, this competitive balance translates into tangible negotiation leverage and a wider spectrum of partnership models—provided they can systematically evaluate provider capabilities against internal mobility requirements.
2026 as a Strategic Inflection Point for Corporate Risk Governance
The year 2026 represents a decisive inflection point for enterprises recalibrating their approach to international business travel protection. Several converging factors elevate the strategic importance of this market at the current moment. Corporate travel volumes continue their upward trajectory, with organizations rebuilding global footprints, expanding supplier networks, and deploying teams to emerging markets at rates that demand robust, standardized coverage protocols. Simultaneously, the expectation that employers will proactively safeguard traveling staff has shifted from a best-practice recommendation to a baseline operational requirement, reinforced by evolving legal interpretations, stakeholder scrutiny, and internal governance standards.
Beyond compliance, the functional role of travel insurance is expanding. Modern corporate programs are increasingly evaluated not only on coverage breadth but also on integration capability, data visibility, and administrative efficiency. Decision-makers are seeking solutions that align with existing travel management platforms, provide real-time risk intelligence, and simplify the claims lifecycle for both employees and finance departments. Providers that invest in seamless digital ecosystems, clear communication pathways, and rapid assistance services are positioning themselves as strategic partners rather than transactional vendors. This evolution places a premium on due diligence: organizations must assess whether prospective insurers can support multi-jurisdictional assignments, accommodate diverse employee profiles, and deliver consistent service quality across high-frequency and low-frequency travel patterns alike.
The professional traveler segment is anticipated to be a particularly dynamic contributor to near-term growth, driven by rising trip frequency and a growing suite of specialized offerings designed to address the unique exposure profiles of business-oriented mobility. At the same time, institutional buyers in the government and non-governmental organization space are refining their procurement criteria, emphasizing emergency evacuation coordination, medical continuity, and administrative centralization. These trends collectively indicate a market where differentiation is increasingly defined by execution quality, plan flexibility, and the ability to translate coverage terms into real-world protection outcomes.
Analytical Framework and Operational Value of the Full Report
This market research publication is structured to deliver both strategic orientation and granular analytical utility. Readers will encounter a systematic mapping of the market across multiple axes, including regional distribution, plan typologies, and application categories, all contextualized within historical performance trends and forward-looking projections. The report does not merely present figures; it interprets them through the lens of operational decision-making, connecting market structure to procurement strategy, vendor evaluation, and risk allocation priorities.
Key analytical components include an assessment of purchasing patterns across different organizational profiles, an examination of how policy architecture aligns with distinct travel behaviors, and a dissection of regional demand characteristics that influence coverage requirements, pricing dynamics, and provider availability. The research also addresses market concentration metrics, providing a framework for understanding competitive density, barriers to entry, and the extent to which scale or specialization shapes provider positioning. By connecting these structural insights to real-world procurement considerations, the report enables readers to identify which coverage types, distribution channels, and partnership models are most aligned with their organizational footprint and risk tolerance.
In addition to quantitative mapping, the study integrates qualitative intelligence on provider capabilities, service design priorities, and operational differentiators. This dual lens—combining market sizing with competitive and functional analysis—allows decision-makers to move beyond headline revenue figures and evaluate the practical implications of market structure. Procurement leaders can use the framing to build scorecards for vendor comparison; risk managers can align coverage selection with duty-of-care obligations and employee exposure profiles; and travel operations teams can assess how administrative complexity, claims responsiveness, and digital integration capabilities influence total cost of ownership.
Competitive Landscape: Strategic Positioning Among Leading Providers
The international business travel insurance sector features a roster of established insurers, specialized medical coverage providers, and broader travel protection organizations that are actively competing on product breadth, assistance infrastructure, and partnership ecosystems. Understanding the positioning of these players is essential for organizations evaluating vendor suitability, negotiating contract terms, or considering bundled solutions that integrate travel protection with broader health and risk services.
Several market participants are distinguished by the scale and integration of their global assistance networks. Allianz Partners, operating with significant US-based business infrastructure, has continued to deepen its strategic footprint through targeted partnerships, industry engagement, and leadership appointments designed to strengthen its travel insurance capabilities and expand underwriting capacity for affinity partners and retailers. Recent moves, including its association with broader travel and tourism industry bodies and the appointment of senior leadership focused on travel sector expansion, signal an intent to reinforce service reach and policy flexibility for corporate and high-frequency travelers.
In the realm of specialized international health and medical coverage, International Medical Group has carved a notable position by focusing on employer and group-oriented plans that support internationally assigned personnel. Its product frameworks emphasize medical protection, evacuation coordination, and structured assistance services, appealing to organizations that require coverage continuity across multiple jurisdictions. Seven Corners similarly emphasizes customizable plan design, targeting business travelers and corporate travel programs with modular protection options and global assistance capabilities that can be adapted to varying assignment durations and coverage needs.
Traditional travel insurance providers remain highly relevant in the business segment as well. Travelex Insurance Services, Travel Guard (AIG), and Berkshire Hathaway Travel Protection each offer plans structured to accommodate trip cancellation related to work obligations, emergency medical scenarios, and international trip protection. Their product emphasis tends to center on flexibility, claims support, and coverage options that address the practical realities of business itineraries, ranging from short consultative trips to extended corporate assignments. Blue Cross Blue Shield Global Solutions, leveraging its broader health network partnerships, adds another dimension to the competitive field by offering group-oriented international health coverage with centralized administration and access to established provider networks—an approach that resonates particularly with organizations seeking to align travel protection with existing health benefits architectures.
For enterprises evaluating these and other providers, the strategic question is not simply which organization commands the largest revenue share, but which service model, coverage architecture, and administrative approach best matches internal mobility patterns and risk governance priorities. The full report provides a more detailed examination of competitive dynamics, product differentiation themes, and partnership activity that can inform vendor shortlisting and contract structuring.
Business Travel Insurance Market
Regulatory Pressures, Duty of Care, and Emerging Market Dynamics
The current market environment is shaped by an interplay of regulatory expectations, operational imperatives, and behavioral shifts that collectively elevate the importance of travel insurance within corporate governance frameworks. One of the most consequential dynamics is the increasing emphasis on duty of care responsibilities. Employers are expected to demonstrate proactive measures to protect employees traveling internationally on company business, and insurance programs are a central component of that risk management architecture. Coverage that addresses medical emergencies, evacuation contingencies, and trip interruption scenarios helps organizations fulfill these obligations while reducing the operational and financial exposure associated with unforeseen events abroad.
At the same time, macro trends are reinforcing demand for structured business travel protection. Rising corporate travel volumes, expanding international assignment activity, and heightened awareness of traveler safety are prompting organizations to standardize coverage protocols across employee populations rather than relying on ad hoc or individually procured solutions. This shift benefits providers that can deliver scalable, administratively efficient programs with clear coverage parameters and reliable assistance infrastructure. It also creates opportunities for insurers that can distinguish themselves through continuous service quality, responsive claims resolution, and product designs attuned to the realities of business mobility.
Behavioral and structural shifts within the traveler base are also influencing market development. As business trip frequency increases and specialized product offerings multiply, the professional traveler segment is positioned for notable growth. Organizations are increasingly seeking plans that reflect the cadence and exposure profile of frequent international travel, while independent professionals and freelance consultants represent an expanding audience that values flexible, individually accessible coverage. These overlapping demand streams encourage providers to refine segmentation strategies and develop products that address both institutional and individual buyer requirements without sacrificing administrative coherence or claims effectiveness.
Conclusion: Converting Market Intelligence into Enterprise Resilience
The International Business Travel Insurance Plans Market is entering a phase in which strategic selection, vendor evaluation, and program design will have an outsized impact on organizational resilience, employee protection, and total cost of ownership. With a clear growth trajectory, expanding demand drivers, and a competitive field that balances scale with specialization, enterprises have both the opportunity and the imperative to approach travel insurance procurement with analytical discipline. This market research report provides the structured insight necessary to navigate that complexity—offering historical context, forward-looking projections, segmentation logic, competitive intelligence, and dynamic analysis calibrated to the needs of corporate decision-makers.
International Business Travel Insurance Plans Market
For executives seeking to align insurance strategy with broader mobility objectives, the complete study delivers the depth required to move from general market awareness to targeted, evidence-based action. The full report examines the granular breakdowns, vendor-specific positioning, regional demand patterns, and forward scenarios that underpin the strategic conclusions summarized here. Readers ready to advance their evaluation and strengthen their risk governance framework are encouraged to access the complete publication for comprehensive data, detailed segmentation analysis, and the full competitive intelligence necessary to support confident 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: International Business Travel Insurance Plans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Non-Filtering Cloth Vacuum Filters Market to Hit $378.74M by 2032 at 5.85% CAGR
By pmarketresearch, 2026-09-16
Strategic Foresight for the Non-Filtering Cloth Vacuum Filters Market: Navigating Growth and Consolidation Through 2032
The global landscape for non-filtering cloth vacuum filters is undergoing a period of careful recalibration. As industrial operators prioritize solid-liquid separation efficiency, equipment uptime, and compliance with tightening hygiene and material standards, the demand for engineered cloth filters has evolved from a commodity consideration to a strategic operational variable. Our latest Worldwide Non-Filtering Cloth Vacuum Filters Market research translates this shift into a structured decision-making framework, offering a full historical arc from 2020 through 2025 and a forward-looking forecast spanning 2026 to 2032. The study is designed not merely to describe market size, but to equip procurement leaders, filtration engineers, and executive strategists with the intelligence needed to time investments, evaluate supplier partnerships, and align product roadmaps with where the industry is heading.
Worldwide Non-Filtering Cloth Vacuum Filters Market
The market has demonstrated steady expansion over the past five years, with recorded revenue progression reflecting both volume growth and incremental value migration toward engineered, application-specific cloth solutions. This trajectory carries forward into the forecast horizon, where the global market is projected to grow from a base of approximately USD 254.4 million in 2025 to an estimated USD 268.6 million in 2026, and onward to roughly USD 378.7 million by 2032. The compound annual growth rate across the forecast period is estimated at 5.85 percent, signaling a market that is expanding with discipline rather than volatility. Such a profile is important for planners: it suggests that growth will be driven by durable operational requirements across core sectors rather than by short-term speculation, allowing organizations to build longer-cycle strategies around supplier capacity, product specialization, and downstream application development.
Worldwide Non-pleated Air Filters Market
What makes this research actionable is its deliberate focus on where financial value and technical differentiation intersect. The report traces how revenue is distributed across the principal type categories, highlighting how reusable cloth sleeves continue to represent the largest share of the market, while disposable primary liners and high-temperature synthetic cloths occupy distinct operational niches with their own adoption drivers. It also examines application-side demand, showing how industrial vacuum systems command the largest portion of market activity, followed by commercial cleaning and residential vacuums. These structural insights matter because they reveal not only where dollars are being deployed today, but also where performance requirements, replacement cycles, and specification sensitivity are likely to shape future purchasing behavior. Importantly, the study preserves the analytical nuance needed to understand regional and segment-level momentum without reducing the market to a set of isolated figures. This enables readers to recognize which geographies and applications are expanding with the strongest relative intensity, while keeping the detailed breakdowns available in the full report for teams that require granular planning inputs.
Why 2026 Is a Decision Bottleneck for Filtration Buyers and Suppliers
The 2026 to 2032 window is more than a forecasting period; it is a strategic planning horizon for organizations that must commit now to material specifications, vendor relationships, and capacity arrangements. Several converging forces make the coming year particularly consequential. First, the broader filter cloth ecosystem continues to expand, with related synthetic filtration materials projected to approach USD 2.1 billion globally in 2026, reinforcing the scale of the underlying material supply chain and the incentives for specialization. Within that environment, non-filtering cloth vacuum filters are benefiting from sustained demand for more efficient solid-liquid separation in mining, minerals processing, and wastewater treatment, where improved cake dryness, flow rates, and equipment uptime translate directly into operational cost advantages.
At the same time, regulatory and application-specific expectations are increasing the cost of mismatched specifications. In food processing applications, vacuum filter cloths must satisfy food-grade certifications and hygiene standards such as FDA and CE to ensure safety and purity during liquid-solid separation. This is a meaningful shift for procurement teams, because it ties filtration performance not only to throughput, but also to documentation, traceability, and compliance readiness. Companies that design their sourcing and product selection around these standards gain a clearer path to qualification in sensitive industries, while those that treat filtration cloth as interchangeable risk qualification delays and operational rework.
Material science developments are also reshaping the competitive playing field. The continued use of polypropylene and polyester as primary materials in woven and non-woven cloths provides a familiar baseline, but innovation is increasingly concentrated in monofilament and multifilament synthetic yarns that enable custom vacuum filter belts with high dimensional stability and abrasion resistance across a wide range of micron ratings. Some manufacturers are supporting belt widths up to 4300 mm while maintaining tight tolerance requirements, an advancement that matters for large-scale continuous processes where uniformity and durability directly influence replacement frequency and process consistency. As these capabilities become more differentiated, procurement strategies that rely on generic specifications will increasingly fall short relative to engineered alternatives.
In parallel, industry activity in 2025 and into 2026 shows that participants are actively reinforcing their market presence through exhibitions, technical engagement, and customer recognition. Companies have been showcasing vacuum filter cloths and related filtration materials at major industry gatherings, including CINTE2025 and the 2025 China Shanghai International Filtration Industry Exhibition, while maintaining ongoing engagement around events such as FILTECH and FiltXPO. supplier performance is also receiving heightened attention, with recent recognition awarded to filtration suppliers for their contribution to industrial processes and supply reliability. These developments signal a market where visibility, technical demonstration, and proven supply dependability are becoming essential elements of commercial positioning.
Competitive Structure and What It Means for Strategic Sourcing
The market is characterized by a moderately concentrated competitive structure. The top three players account for an estimated 38.25 percent of market revenue, while the top five represent approximately 52.4 percent. This concentration suggests that a relatively small group of established suppliers holds meaningful share, yet there remains sufficient fragmentation for specialized manufacturers and regional players to compete on application expertise, customization, and responsiveness. For buyers, the implication is twofold: scale and consistency can be accessed through leading suppliers, but differentiated requirements often call for partners with targeted engineering capabilities and material knowledge.
Several companies illustrate the breadth of competitive approaches now shaping the market. Micronics Engineered Filtration Group, part of Cleanova and based in Chattanooga, Tennessee, specializes in custom-engineered filter media and cloths for vacuum filtration equipment, including rotary vacuum disc filters, drum filters, horizontal belt vacuum filters, and pan filters. Its applications span liquid-solid separation in mining, minerals, alumina refining, chemicals, and wastewater, reflecting a positioning built on engineered fit rather than broad commoditization.
Bolian Filtration Solutions Co., Ltd., headquartered in Tieling, Liaoning Province, China, manufactures woven filter cloths and fabrics specifically for vacuum filtration applications. Its product range covers horizontal vacuum belt filter cloths, rotary drum filter cloths, horizontal disc filter cloths, and specialized cloths for lithium battery and desulfurization processes in metallurgy, mining, chemicals, and new energy sectors. Bolian's recent visibility at filtration industry exhibitions and its recognition as an outstanding supplier at a major 2026 annual meeting underscore the growing importance of supplier reliability, technical alignment, and customer validation in a market where downstream processors are increasingly selective.
In Europe, GKD Group, headquartered in Düren, Germany, provides horizontal vacuum belt filters and associated filtration fabrics and belts, featuring wide throat vacuum boxes, pre-filtered cloth or belt wash water, and in-house manufactured spares. Its approach emphasizes integrated equipment and fabric support for efficient solid-liquid separation in industrial processes, an arrangement that can reduce coordination risk for operators seeking aligned system performance. Testori S.p.A., based in Novate Milanese, Italy, offers filter media including bags for vacuum disc filters, belts for vacuum belt filters, and cloths for vacuum drum filters, using various polymers and yarns tailored for solid-liquid separation with options for different cake discharge principles. K2TEC, based in France, manufactures filter belts and cloths for vacuum belt filters using PP, PES, PA, PVDF, and PTFE materials with micron ranges from 1 to 2000, and supports its products with patented closures and edge reinforcements for applications in chemical, mineral, pharmaceutical, and mechanical industries.
Together, these profiles show that the competitive field is not monolithic. Some participants compete through broad industrial coverage and custom engineering, others through material breadth and micron-level versatility, and others through integrated equipment-plus-fabric systems. This diversity gives buyers multiple paths to value, but it also increases the importance of clearly defining performance requirements before sourcing. The full report analyzes these competitive dynamics in greater depth, helping readers assess which supplier archetypes align with their operational priorities and where the market is most vulnerable to specification gaps, supply constraints, or quality variability.
How to Use the Report for 2026 Planning
This study is structured to support concrete decisions across the buying, engineering, and commercial functions. It provides a historical baseline from 2020 to 2025 for context, then extends into a ten-year forecast that allows organizations to model substitution patterns, replacement cycles, and application growth with greater confidence. The segmentation framework organizes the market by region, type, and application so that planners can see not only aggregate growth but also the structural composition beneath it. This is particularly useful for companies trying to determine whether demand is being led by industrial-scale process requirements, commercial cleaning operations, or residential vacuum use, and how those demand centers differ in specification sensitivity and purchasing rhythm.
The report also explores the dynamics that shape market behavior, including raw material considerations such as polypropylene, polyester, and polyamide usage; the role of monofilament and multifilament yarns in improving dimensional stability and abrasion resistance; and the growing importance of compliance requirements in food-related applications. These forces are not treated as background detail, but as factors that influence supplier selection, product design, and total cost of ownership. By connecting material trends with application needs, the research helps teams anticipate where specification upgrades are likely to become standard rather than optional.
For executives evaluating market entry, expansion, or partnership strategy, the study’s concentration analysis and company profiles provide a practical map of competitive intensity. Rather than relying on broad impressions, readers can identify which segments show the strongest momentum, where incumbent suppliers are well positioned, and where opportunities may exist for suppliers that can demonstrate specialized performance, reliable delivery, and regulatory readiness. The full version of the report contains the detailed segment splits and regional values needed for precise financial and operational planning, while this overview establishes the strategic logic behind those figures.
Read the Full Intelligence, Not Just the Trajectory
The Worldwide Non-Filtering Cloth Vacuum Filters Market research is built for organizations that require more than an aggregate growth narrative. It translates a market expanding from roughly USD 254.4 million in 2025 toward an estimated USD 378.7 million by 2032 into a usable planning foundation, with a forecast CAGR of 5.85 percent and a detailed segmentation structure that clarifies how type, application, and regional demand interact. It also situates the market within broader industry forces, from material innovation and equipment integration to compliance expectations and supplier recognition, so that decision-makers can align procurement and product strategy with where value is actually being created.
To access the complete segmentation data, detailed regional and application breakdowns, competitive profiles, and forward forecasts that support precise 2026 planning, readers are encouraged to view the full report through our official market intelligence portal. The overview above is intended to demonstrate the scope and analytical rigor of the study, while the full publication provides the depth required for sourcing decisions, investment planning, and long-range market positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Filtering Cloth Vacuum Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Portable Chromatography Market to Reach $1,508.39 Million by 2032 at 5.86% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Inside the Worldwide Portable Chromatography Systems Market
The landscape of analytical chemistry is undergoing a fundamental transformation. The shift from centralized laboratory infrastructure to decentralized, field-deployable analytical solutions is no longer a niche trend but a structural reallocation of capital and capability across the global life sciences and industrial testing sectors. For executive leadership teams, R&D directors, and investment strategists, understanding the trajectory of the Worldwide Portable Chromatography Systems Market is essential for navigating the complexities of the 2026 fiscal year and beyond. This market intelligence briefing serves as a strategic gateway into our comprehensive market research report, designed to equip decision-makers with the foresight needed to capitalize on emerging opportunities while mitigating regulatory and competitive risks.
Our latest study provides a rigorous analysis of market evolution from 2020 through 2032. The data reveals a market that has demonstrated resilience and consistent growth, expanding from a baseline of 765.4 million USD in 2020 to a projected valuation of 1012.5 million USD in 2025. Looking forward, the market is anticipated to reach 1508.39 million USD by 2032. This trajectory reflects a Compound Annual Growth Rate of 5.86 percent over the forecast period. These figures are not merely historical records; they represent the underlying velocity of adoption for portable analytical technologies in critical sectors ranging from environmental monitoring to pharmaceutical quality assurance. For stakeholders planning capital allocation in 2026, this growth rate signals a mature yet expanding ecosystem where strategic positioning today will define market share tomorrow.
Decoding the Competitive Architecture
The portable chromatography sector is characterized by a consolidated yet dynamic competitive landscape. Market concentration metrics indicate that the top three players command 42.5 percent of the market, while the top five entities hold 58.8 percent. This moderate concentration suggests a market where established giants maintain significant influence, yet there remains ample room for specialized innovators and agile entrants to capture value through differentiation in portability, battery life, and application-specific software.
Leading this ecosystem is Agilent Technologies, based in Santa Clara, California. Agilent continues to set benchmarks with systems like the 1290 Infinity II LC System and the HPLC Chip Cube, which enable miniaturized portable LC-MS applications essential for field analysis. Their recent product launch in October 2025 of the enhanced portable 1260 Infinity III LC system, featuring battery operation for field pharma purity testing, underscores a commitment to operational autonomy in remote settings.
Chromatography Columns Market
Thermo Fisher Scientific, headquartered in Waltham, Massachusetts, offers robust solutions such as the Vanquish Flex UHPLC systems with modular portable designs and the Dionex ICS-6000 HPIC for portable ion chromatography. Their focus on environmental and pharma testing is reinforced by recent regulatory milestones, including the June 2025 CE Mark receipt for Dionex portable IC system upgrades tailored for EU environmental monitoring.
Waters Corporation, located in Milford, Massachusetts, markets the ACQUITY UPLC H-Class system in compact portable formats and the ARC HPLC for field-deployable bioanalysis. Their strategy emphasizes reliability and integration with existing laboratory workflows, making them a critical partner for organizations transitioning between centralized and decentralized testing models.
Shimadzu Corporation, based in Kyoto, Japan, supplies the Prominence-i Portable LC system and Nexera-i for integrated portable UHPLC, specifically targeting clinical and food safety applications. Their showcase of the Nexera Portable UHPLC at Pittcon 2025 in March, featuring a new field-deployable autosampler, highlights the ongoing refinement of user experience and throughput in mobile units.
PerkinElmer, also in Waltham, Massachusetts, focuses on actionable on-site insights with the Flexar SQ300 LC-MS featuring portable cart-based systems designed for environmental and forensic chromatography. Meanwhile, Scion Instruments, based in Livingston, UK, produces the 436-GC and 456-GC modular portable gas chromatography systems, which are pivotal for field oil and gas and VOC analysis. Together, these companies form the backbone of the current supply chain, each carving out distinct value propositions that collectively drive the market forward.
Market Dynamics and Regulatory Currents
Strategic planning for 2026 requires more than an understanding of revenue projections; it demands a granular grasp of the regulatory and operational dynamics shaping the market. The deployment of portable chromatography systems, particularly those intended for clinical use, is increasingly governed by stringent accreditation standards. Systems must comply with ISO 15189:2022 accreditation standards for medical laboratories, a requirement that influences procurement specifications and validation timelines for healthcare providers.
Furthermore, reimbursement landscapes play a crucial role in adoption rates within outpatient and clinical settings. The CPT code 82542 covers column chromatography procedures applicable to portable systems in outpatient settings. Understanding the nuances of billing codes and insurance coverage is vital for manufacturers and service providers aiming to expand their footprint in the healthcare sector. For those navigating the US market, compliance with FDA regulations remains a critical checkpoint. It is important to note that portable GC systems labeled for research use only cannot be marketed for direct diagnostic purposes under FDA 21 CFR 809.10. This regulatory boundary creates a clear distinction between research tools and diagnostic devices, impacting product labeling, marketing strategies, and sales channels.
On the supply chain side, material science constraints continue to influence cost structures. Medical-grade PEEK tubing used in portable LC systems costs 50 to 100 dollars per meter due to USP Class VI compliance. While this contributes to the overall cost of goods, it also serves as a quality differentiator that justifies premium positioning in high-stakes applications where system integrity is non-negotiable. These dynamics create a complex interplay between cost management, regulatory adherence, and value proposition, requiring stakeholders to adopt a multi-dimensional strategy.
Segmentation Drivers and Application Growth
The demand for portable chromatography is being propelled by diverse end-user needs, reflecting the versatility of the technology. While specific regional and application percentages are detailed in the full proprietary dataset, the broader segmentation logic reveals where investment and innovation are converging.
- Environmental Testing remains a dominant driver, fueled by the need for real-time monitoring of pollutants, VOCs, and water quality in remote or disaster-affected areas. The ability to deploy systems on-site reduces turnaround time from weeks to minutes, a capability that is becoming a regulatory and operational imperative.
- Forensics and Defense applications are seeing increased requisition for mobile units that can perform immediate analysis at crime scenes or border checkpoints. The portability and robustness of systems offered by key players enable rapid decision-making in high-stakes scenarios.
- Food and Beverage Safety is another critical pillar, as global supply chains demand faster verification of contaminants and adulterants. Portable systems allow for testing at the point of origin or distribution, enhancing traceability and consumer safety.
- Pharmaceutical and Life Sciences sectors are leveraging portable configurations for process analytical technology (PAT) and bioanalysis. The ability to conduct purity testing and monitoring directly on the manufacturing floor or at clinical trial sites streamlines development cycles and ensures quality control.
Product type segmentation further delineates the market's technical evolution. Portable Gas Chromatography continues to lead in applications requiring volatile compound analysis, such as environmental and petrochemical use cases. Portable Liquid Chromatography is pivotal for pharmaceutical and biological sample analysis, while Portable Ion Chromatography addresses specific needs in environmental anion/cation monitoring and pharma testing. Each modality presents unique engineering challenges and opportunities, from battery capacity to thermal management, dictating the roadmap for product development and market entry.
Why This Research is Critical for 2026 Decision-Making
As we move into 2026, the convergence of technological advancement, regulatory shifts, and evolving customer expectations creates a window of strategic opportunity. However, navigating this landscape without precise intelligence carries significant risk. The Worldwide Portable Chromatography Systems Market report is designed to eliminate guesswork by providing a structured, data-backed view of the ecosystem.
The report delivers actionable insights that go beyond high-level trends. It includes a detailed analysis of raw material costs, supply chain vulnerabilities, and cost structure benchmarks that affect pricing strategies. The assessment of recent developments, such as product launches, regulatory clearances, and trade show showcases from 2025, offers a forward-looking perspective on competitive moves and technological capabilities. By analyzing these events, stakeholders can anticipate shifts in product availability, feature sets, and market positioning.
Additionally, the research addresses critical questions that often arise during strategic planning. For instance, understanding the regulatory boundaries for research-use-only versus diagnostic devices is essential for market access planning. Clarifying reimbursement codes and accreditation requirements helps in forecasting adoption rates and revenue potential in specific verticals. The report also evaluates the impact of material costs and compliance standards on the total cost of ownership, enabling more accurate financial modeling.
For investors, the report provides a clear view of market concentration and growth vectors, helping to identify which segments offer the highest ROI potential. For manufacturers, it offers a blueprint for product roadmap alignment, highlighting gaps in current offerings and opportunities for innovation. For service providers and consultants, it serves as a reference for advising clients on technology selection, compliance, and operational efficiency.
Unlocking the Full Intelligence
This article serves as a high-level overview of the strategic themes and data points encompassed within our comprehensive Worldwide Portable Chromatography Systems Market research. However, the true value lies in the depth of the analysis. The full report contains exhaustive segmentation data, detailed company profiles, granular forecast models, and scenario analyses that are essential for precise decision-making. It maps the interplay between regional dynamics, product innovation, and regulatory frameworks with a level of detail that cannot be fully captured in a summary.
Accessing the complete report will allow your organization to:
- Benchmark your product portfolio against key competitors and their recent developments.
- Validate market entry or expansion strategies with robust, data-driven forecasts.
- Identify emerging trends in application areas and technology modalities before they become mainstream.
- Navigate complex regulatory environments with confidence, informed by up-to-date compliance insights.
- Optimize pricing and cost structures based on detailed supply chain and material cost analysis.
The market for portable chromatography systems is poised for sustained growth, driven by the undeniable advantages of speed, mobility, and on-site accuracy. Yet, realizing the benefits of this growth requires a strategic approach grounded in accurate intelligence. Our report provides the foundation for that strategy, offering the clarity needed to make informed decisions in a rapidly evolving market.
We invite you to explore the full scope of our research to gain the competitive edge necessary for success in 2026 and beyond. The detailed insights, proprietary data, and strategic recommendations contained in the full report are available for immediate access. Visit our source page to download the complete Worldwide Portable Chromatography Systems Market research and equip your team with the intelligence required to lead in the decade ahead.
Worldwide Portable Chromatography Systems Market
For detailed analysis of this topic, please visit the official page: Worldwide Portable Chromatography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com