

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Portable Gaming Console Market Hits $16.5B in 2025, Poised to Reach $30.1B by 2032

Navigating the Pocket-Sized Future: Strategic Intelligence for the 2026 Portable Gaming Console Market
The portable gaming landscape is undergoing its most significant structural transformation in over a decade. As the line between dedicated handhelds, PC-based gaming devices, and cloud-streaming endpoints continues to blur, enterprise leaders across hardware manufacturing, software ecosystems, retail distribution, and semiconductor supply chains are confronting a fundamental strategic question: where will the next wave of portable entertainment revenue originate, and how should organizations position themselves to capture it? The Worldwide Portable Gaming Consoles Market study, grounded in historical data from 2020 through a base year of 2025 and projecting through 2032, provides the analytical architecture required to move beyond reactive product cycles and instead make informed, forward-looking capital and product allocation decisions.
At the macro level, the trajectory is unambiguous. Global revenue in this category has expanded steadily from 8,450.0 million USD in 2020 to 16,500.0 million USD by 2025, reflecting a compound annual growth rate of 8.98 percent across the forecast window extending to 2032. The modeled expansion does not plateau abruptly; rather, the revenue curve continues to climb toward 18,053.73 million USD in 2026 and projects toward a 30,127.12 million USD ceiling by the end of the forecast period. For strategy teams, these trajectory markers are not merely headline validation. They signal sustained consumer willingness to pay for portable experiences, the maturation of hybrid home-and-portable product architectures, and the growing monetization of PC-grade handheld ecosystems alongside traditional retro and Android-focused submarkets. Yet aggregate growth numbers tell only half the story. The strategic value of this research lies in its decomposition of those top-line movements into actionable decision layers, from console-type adoption shifts and channel-specific purchase behaviors to regional demand intensity and supply-side cost pressures.
Gaming Laptop Market
Why 2026 Is a Pivotal Inflection Point
The portable gaming market is no longer defined solely by cartridge-driven or cartridge-adjacent dedicated devices. The emergence of high-performance Windows-based handhelds, Linux-centric PC gaming portables, and cloud-anchored streaming endpoints has fractured legacy segmentation and forced manufacturers, platform holders, and retail partners to recalibrate. Historical spend patterns from 2020 through 2025 demonstrate that demand momentum has been consistently upward, but 2026 represents a moment where execution discipline separates sustainable market share growth from short-lived hype cycles. Several dynamics converge to make this year particularly decisive.
Worldwide Portable Gaming Consoles Market
First, silicon and subsystem architecture are shifting rapidly. Ecosystem players are explicitly linking next-generation performance leaps to major architectural improvements rather than incremental refreshes, with public development commentary emphasizing that meaningful gains must be paired with battery life retention and thermal management discipline. This creates an environment where product roadmaps cannot be optimized for peak specification alone; they must balance performance density, power efficiency, and supply feasibility. Second, component cost volatility has moved from an abstract risk to a near-term operational reality. Recent market signals indicate that pricing pressures tied to high-density DRAM demand, advanced display panel requirements, and broader semiconductor sourcing constraints are influencing product launch timing and pre-order cadence for premium handhelds. Organizations that treat component procurement as a static backdrop will find their margin assumptions and channel pricing strategies misaligned with reality. Third, regulatory and compliance frameworks around energy efficiency and lithium-ion battery safety continue to evolve across regions, increasing the non-negotiable cost of compliance for any device seeking global distribution. The market research contextualizes these dynamics within the broader revenue model, enabling teams to stress-test product economics against real-world constraints rather than idealized specification sheets.
What the Report Delivers: Tactical Intelligence Over Generic Trends
This study is structured to support concrete operational decisions rather than high-level narrative. It maps the historical and forecast revenue path across multiple interlocking dimensions, allowing strategy, product marketing, supply chain, and channel management teams to isolate where growth is concentrating and where margin erosion or saturation risk is emerging. The analytical framework is deliberately multidimensional:
- Historical baseline and forward trajectory mapping across the 2020 to 2032 window, anchored by a 2025 base year and consistent USD million revenue units, so that organizational planning can be reconciled with a single coherent model.
- Console-type segmentation that distinguishes dedicated gaming handhelds, PC-based handheld consoles, and Android and retro handhelds, enabling firms to evaluate where their product strategy intersects with high-volume mainstream segments versus niche or value-oriented categories.
- Regional demand distribution across five major geographic territories, helping organizations align go-to-market priorities, localized pricing strategies, and distribution partnerships without assuming uniform growth intensity across markets.
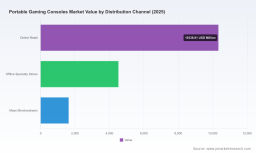
- Distribution channel mapping across online retail, offline specialty stores, and mass merchandisers, giving retail and channel teams visibility into where consumer acquisition is concentrated and how omnichannel mix decisions may affect inventory planning and promotional allocation.
- Competitive intensity and concentration analytics, reflecting a market environment where a relatively small group of ecosystem participants commands the majority of revenue share, while specialized brands retain relevance through targeted product positioning and platform differentiation.
- Company-level profiles and recent development tracking that connect product launches, concept unveilings, pre-order adjustments, and platform integration moves to market-level implications, so that competitive intelligence is tied directly to revenue and positioning consequences.
- Supply-side and industry context overlays covering component cost trends, advanced display and memory demand, battery safety and energy efficiency certification requirements, and geopolitical trade dynamics affecting advanced semiconductor sourcing, all of which feed into realistic cost structure and time-to-market assumptions.
Each lens is designed to translate directly into a decision support function. Pricing strategy teams can use channel and segmentation views to evaluate where premium positioning is defensible and where promotional elasticity is already priced in. Supply chain and procurement teams can benchmark component cost pressures against forecast revenue growth to determine whether margin protection should come from bill-of-materials optimization, channel mix shifts, or product tiering. Product planners can reference recent development patterns to anticipate where platform ecosystems are converging and where fragmentation creates opportunity for differentiated portable experiences.
Competitive Architecture: Ecosystem Leaders, Specialist Innovators, and the Fragmentation Reality
The portable gaming market’s competitive structure is defined by a combination of dominant platform ecosystems and specialized hardware players that compete through performance, price, and ecosystem access rather than sheer scale. Concentration metrics in the research indicate that a small cohort of leading participants commands a substantial share of total revenue, while a longer tail of manufacturers serves distinct consumer segments through curated value propositions. This duality matters because it shapes both pricing power and market entry risk.
Ecosystem-anchored players remain central to the market’s direction. Nintendo’s hybrid console approach continues to anchor mainstream portable and home-integration demand, reinforced by a recent platform generation that emphasizes backward compatibility and expanded hybrid utility. This positions the company as a volume and ecosystem anchor within the broader handheld landscape. Parallel to that, PC gaming-centered ecosystems are expanding the definition of portable hardware. Valve’s Linux-based portable PC gaming approach maintains a strong presence through a dedicated software library and a publicly acknowledged roadmap that prioritizes architectural improvements over minor refreshes. Meanwhile, partnerships linking Windows-based portable hardware with major console ecosystems are reshaping the competitive center of gravity, particularly as premium handhelds target high-performance AAA portable gaming through advanced processor architectures and ecosystem-integrated subscription and library services.
Beyond platform anchors, a meaningful layer of specialist innovators is driving differentiation in form factor, operating model, and target audience. Premium Windows and Android-focused handheld manufacturers continue to compete on compactness, performance density, and display technology, with concepts such as foldable display configurations pointing toward new usage paradigms that blend handheld play with larger-screen versatility. On the value and enthusiast side, budget-oriented Android and Linux-based emulation devices address retro gaming and accessible portable entertainment, sustaining a distinct demand segment that may not drive headline platform ecosystem growth but nevertheless contributes to category breadth and price-point diversity. Cloud-gaming-anchored devices further extend the category boundary by decoupling local compute requirements from the gaming experience, positioning portable hardware as a client endpoint within broader streaming service models.
Recent developments underscore that competitive positioning is not static. Product launches spanning hybrid console refreshes, Windows-based AAA-targeted handhelds, and ecosystem-integrated PC portables illustrate how quickly hardware roadmaps are converging around performance, library access, and platform integration. At the same time, selective pre-order adjustments tied to component cost escalation and publicly discussed development timelines that emphasize architectural necessity over release cadence reveal that execution risk remains material. Organizations reading the market only through launch announcements risk missing the underlying dynamics: component sourcing feasibility, silicon readiness, and supply proportionality are increasingly decisive in determining which premium devices reach consumers at intended specifications and price points. The research places these developments within a competitive concentration framework, enabling leadership teams to assess not only who is active, but how durable their positioning is likely to be as cost structures and platform expectations evolve.
Decision-Makers Should Use This Research To Answer Five Strategic Questions
For enterprise planning in 2026, the market study is most valuable when it is used to sharpen specific strategic judgments rather than to confirm broad optimism. The report is designed to support the following lines of inquiry:
- Where is revenue growth concentrating across console types, and does our portfolio allocation match the demand mix we expect to see through 2032 rather than the mix that prevailed five years ago?
- How should channel strategy adapt if consumer acquisition continues to skew toward specific retail models, and what inventory, pricing, and promotional commitments follow from that mix?
- What combination of component cost pressure, certification requirements, and geopolitical sourcing constraints is realistic for our next product cycle, and where do margin risks emerge if we assume steady cost conditions?
- Which competitive positions are anchored by ecosystem breadth and backward compatibility, and which are dependent on transient specification advantages that may erode as next-generation silicon and platform integrations arrive?
- How do regional demand differences influence where we prioritize distribution partnerships, localized product positioning, and compliance investment?
These questions cannot be answered credibly by tracking launch headlines alone. They require a structured view of historical momentum, forecast trajectory, segmentation behavior, channel economics, concentration dynamics, and supply-side realism. The report provides that structure, allowing strategy teams to convert market intelligence into planning assumptions that can be defended in executive discussions and operationalized across product, commercial, and supply functions.
Access the Full Intelligence Model
The portable gaming market is expanding, but expansion alone does not create competitive advantage. Advantage comes from understanding where growth is structurally concentrated, how device categories and channels are reallocating demand, where cost and compliance pressures will shape product economics, and which competitive positions are durable versus contingent. The Worldwide Portable Gaming Consoles Market study was built to deliver precisely that level of decision-grade clarity.
This article has outlined the strategic contours and the decision framework, but it does not reproduce the full segmentation data, regional demand values, channel-specific revenue splits, or the complete competitive and supply-side detail that underpin the model. Those elements are central to the report’s operational value and are preserved in the full dataset and analysis. To evaluate how the 2026 to 2032 trajectory applies to your portfolio, pricing, channel mix, and supply strategy in concrete terms, access the complete research suite and review the underlying segmentation, concentration, and company-level intelligence in detail.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Gaming Consoles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com