

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide WiFi as a Service Market Hits $8,354.2M in 2025 with 19.52% CAGR through 2032

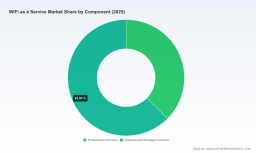
The Strategic Shift to Connectivity-as-a-Subscription: Inside the Global WiFi as a Service Market
The New Infrastructure Imperative
Enterprise connectivity is undergoing a fundamental architectural transformation. The traditional model of large upfront capital expenditures for network hardware, followed by periodic refreshes and manual maintenance, is being steadily displaced by operational expenditure frameworks that treat wireless infrastructure as an ongoing service. This transition is not merely a financial engineering exercise. It reflects a deeper operational reality: as organizations deploy more distributed locations, support hybrid workforces, and integrate IoT and edge computing workloads, the burden of managing complex wireless environments has outpaced the capabilities of many internal IT teams. WiFi as a Service addresses this gap by bundling hardware, cloud management, analytics, and ongoing support into predictable subscription models.
For leadership teams evaluating infrastructure roadmaps in 2026, understanding the trajectory of this market is no longer optional. It is a strategic necessity that touches capital allocation, vendor selection, compliance posture, and competitive positioning. The Worldwide WiFi as a Service Market study we have just published maps this transition with granular precision, offering a decision framework that moves beyond high-level trends to the operational and financial details that actually drive procurement choices.
Market Trajectory and the Scale of the Opportunity
The numbers tell a clear story of accelerating adoption. The global WiFi as a Service market reached approximately 8,354 million USD in 2025, up from 3,420 million USD in 2020. That represents a compound annual growth rate of roughly 19.52 percent across the historical period, and the momentum carries strongly into the forecast window. By 2026, the market is projected to surpass the 10 billion dollar threshold, climbing to 11,965 million USD in 2027 and continuing its ascent through 2032, when it is expected to reach 29,106 million USD. These figures are not abstract growth statistics. They signal a structural reallocation of enterprise networking budgets toward recurring service models, with subscription-based procurement now accounting for a meaningful share of new wireless deployments.
What matters for strategy leaders is not just the headline growth, but the composition of that growth. The market is expanding across every major organizational scale, vertical industry, and geographic region, though the pace and drivers vary considerably. Large enterprises and small-to-medium businesses are both converting significant portions of their wireless spend into as-a-service contracts, but for different reasons. Large organizations are drawn to centralized cloud management, integrated security, and the ability to scale deployments across dozens or hundreds of sites without proportional headcount growth. Smaller enterprises value the reduced operational complexity, predictable billing, and access to enterprise-grade features that were previously out of reach. The study breaks down these adoption patterns across components, organization sizes, verticals, and regions, providing a nuanced view of where demand is concentrated and where untapped potential remains.
Market Concentration and Competitive Dynamics
The vendor landscape reflects both the maturity of the underlying technology and the intensity of competition. The top three players command a combined market share of roughly 41.35 percent, while the top five extend that concentration to approximately 57.8 percent. This level of consolidation indicates that scale, platform integration, and ecosystem partnerships are becoming decisive advantages, yet it also leaves substantial room for specialized providers and regional operators to compete on service quality, industry-specific features, and localized support.
Several established networking leaders anchor the competitive field. Cisco Meraki continues to push cloud-managed wireless forward with subscription-based licensing that spans from simplified SMB offerings to full-scale enterprise deployments, including recent enhancements to its Meraki Go WiFi 6E subscription service for small businesses. Hewlett Packard Enterprise, through its Aruba Central platform, has expanded its as-a-service subscription models for access points and edge services, most recently deepening integration with Microsoft Azure for edge computing workloads. Extreme Networks delivers WiFi as a Service through its ExtremeCloud IQ platform, offering opEx subscription options for WiFi 6 and 6E access points alongside advanced analytics, and has moved to certify the platform for WiFi 7 support in enterprise environments. Ruckus Networks, operating under CommScope, has focused on high-density scenarios, deploying its cloud-managed WiFi as a Service across hundreds of European hospitality sites with AI-driven optimization. Fortinet differentiates through security integration, bundling wireless access with Secure SD-WAN in subscription models. Ubiquiti provides cloud-hosted management for its UniFi access points, while Rogers Communications serves the Canadian enterprise market with managed multi-location deployments. Purple, formerly GNS, has carved a distinct position by embedding guest analytics and marketing tools into its wireless service, particularly for retail and hospitality environments worldwide.
These profiles are only the starting point. The full study examines competitive positioning, partnership strategies, product lifecycle moves, and the specific ways each player is adapting to regional regulatory requirements and evolving customer expectations.
Industry Catalysts and the Forces Reshaping Demand
Several concurrent developments are accelerating the shift toward WiFi as a Service. On the infrastructure side, the availability of unlicensed spectrum in the 6 GHz band, as enabled by recent FCC actions, has expanded the capacity needed for WiFi 6E and WiFi 7 deployments, which are critical for supporting the density and throughput demands of modern as-a-service models. At the same time, access point costs for subscription-based deployments typically range between 500 and 1,500 dollars per unit when bundled with cloud management, making the financial case for opEx models increasingly attractive, especially for organizations that want to avoid large upfront procurement cycles.
On the regulatory front, compliance is becoming a more prominent factor in vendor selection and deployment architecture. The European Union Data Act mandates data portability for cloud-managed WiFi services, a requirement that took effect in September 2025 and directly influences how multinational organizations structure their wireless contracts and data governance policies. In China, cybersecurity regulations continue to require local data storage for in-country operations, adding complexity for global providers and creating opportunities for vendors that can navigate these constraints effectively. These regulatory pressures are not isolated concerns. They shape everything from contract terms and data residency options to the geographic distribution of managed services infrastructure.
A broader macro trend reinforces the financial appeal: recent enterprise surveys indicate that approximately one in four new WiFi purchases is now made through subscription services rather than traditional capex procurement. This shift reflects a growing comfort with recurring models among finance and IT leadership, particularly in environments where agility, scalability, and reduced operational overhead are prioritized over asset ownership.
What the Study Covers: A Practical Toolkit for Decision-Makers
The Worldwide WiFi as a Service Market report is designed to move beyond market narrative and into actionable intelligence. It provides a structured foundation for procurement planning, vendor evaluation, and investment prioritization. The study includes:
- A comprehensive market sizing framework covering historical performance from 2020 through 2025 and a detailed forecast extending to 2032, with revenue expressed in millions of USD and a clearly defined compound annual growth rate across the forecast horizon.
- Segmentation analysis across components, organization size, vertical industry, and geographic region, allowing leaders to benchmark their own deployment patterns against broader adoption trends and identify high-growth segments aligned with their strategic objectives.
- Detailed competitive profiles of leading providers, including headquarters location, product and service positioning, subscription models, and recent strategic moves such as product launches, partnerships, certification updates, and deployment expansions.
- An examination of market dynamics driven by regulation, infrastructure economics, macro procurement shifts, and regional compliance requirements, helping organizations anticipate constraints and opportunities before they affect procurement timelines.
- Contextual analysis of how cloud management, edge integration, security bundling, and analytics capabilities are influencing vendor selection across different industry verticals and organizational scales.
Each section is built to support concrete decisions. Whether the objective is to evaluate whether an as-a-service model fits a particular multi-site rollout, to compare subscription structures across vendors, to understand the implications of regional data regulations, or to forecast budget requirements over the next several years, the study provides the granularity needed to move from strategic intent to execution.
Strategic Implications for 2026 Planning
For organizations entering 2026 with infrastructure decisions on the table, the WiFi as a Service market offers both opportunity and complexity. The growth trajectory suggests that subscription-based wireless will continue to capture a larger share of enterprise networking spend, but the optimal path depends on context. A retail chain focused on guest experience and location analytics will evaluate providers differently than a healthcare system prioritizing secure, compliant connectivity across distributed facilities. A multinational operating across North America, Europe, and Asia Pacific must weigh differing regulatory frameworks, data residency expectations, and regional support capabilities. Even within a single organization, the calculus may differ between headquarters, remote branches, and temporary or seasonal sites.
Worldwide WiFi as a Service Market
The study is structured to help leaders navigate these nuances. It does not prescribe a one-size-fits-all answer. Instead, it equips decision-makers with the market context, segmentation insights, competitive intelligence, and dynamic factors required to build a tailored strategy. The goal is to enable confident choices about vendor selection, contract structure, deployment phasing, and risk mitigation, particularly as regulatory requirements and technology capabilities continue to evolve.
Access the Full Intelligence
The macro figures and competitive snapshots outlined here represent only the opening layer of the analysis. The complete study delivers the detailed regional breakdowns, component and vertical splits, organization-size comparisons, vendor-specific strategic assessments, and forward-looking scenario context that procurement leaders, IT strategists, and investors need to make informed commitments. For organizations that require a full view of market size trajectories, segmentation distributions, concentration metrics, and the evolving regulatory and infrastructure landscape, the full report is available for review and download.
In a market growing at nearly twenty percent annually and reshaping how enterprises procure, manage, and secure wireless infrastructure, the difference between reactive purchasing and strategic planning is substantial. The Worldwide WiFi as a Service Market study is built to close that gap, providing the depth and structure required to turn market intelligence into executable strategy in 2026 and beyond.
Worldwide Infrastructure as a Service Market
For detailed analysis of this topic, please visit the official page: Worldwide WiFi as a Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com