

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Conductive Fibers Market Hits $2.07B by 2032

Strategic Imperatives in the Conductive Fibers Market: A 2026 Decision-Maker's Outlook
The global conductive fibers market has matured from a niche materials segment into a critical enabler of technological convergence across electronics, textiles, and industrial manufacturing. As enterprises navigate the 2026 landscape, decisions surrounding material selection, supply chain localization, and R&D allocation increasingly hinge on granular market intelligence. This article outlines the strategic contours of the Worldwide Conductive Fibers Market, drawing from recent performance data and emerging industry dynamics to illustrate why comprehensive market research is indispensable for capital allocation and competitive positioning in the coming cycle.
Organizations that fail to align their product roadmaps with the shifting economics of conductive materials risk ceding ground to rivals who treat functional textiles as strategic assets rather than commodity inputs. The following analysis synthesizes the macroeconomic trajectory of the sector, examines the competitive architecture among key material suppliers, and highlights the operational and regulatory factors that will define profitability through 2032.
Trajectory of Market Expansion: Interpreting the Growth Curve
Historical revenue data reveals a steady accumulation of market value over the past half-decade, with the sector transitioning from incremental growth to a phase characterized by compounding expansion. In the 2020 base year, the global conductive fibers market generated approximately 870.7 million USD in revenue. By 2025, that figure reached 1250.0 million USD, reflecting an ecosystem that has absorbed increased capital investment, technological maturation, and broader commercial adoption across end-use industries.
Electrically Conductive Textiles Market
Looking forward, the forecast period from 2026 through 2032 projects a compound annual growth rate of 7.5 percent. This trajectory suggests that the market will surpass the 1500 million USD threshold in the near term and continue its ascent toward the 2000 million USD range before the decade concludes. The sustainability of this expansion is not merely a function of volume but of value migration: high-performance fiber architectures are capturing premium pricing in smart textile and advanced EMI applications, while cost-optimized conductive solutions are simultaneously penetrating broader industrial and anti-static use cases.
Decision-makers analyzing this growth curve must recognize that top-line expansion does not distribute evenly across material classes or geographic corridors. The research framework unpacks these divergences, mapping how specific fiber typologies align with distinct application requirements and how regional procurement patterns reflect both industrial maturity and emerging demand centers. Rather than treating the market as a monolith, the study segments the opportunity landscape to reveal where capital efficiency and product differentiation intersect.
Navigating Competitive Architecture and Strategic Positioning
Defining the Player Ecosystem
The conductive fibers market is characterized by a moderately fragmented competitive structure. The top three firms collectively account for approximately 22.5 percent of total market revenue, while the top five firms consolidate their footprint at roughly 34.8 percent. This concentration pattern indicates that while established material science conglomerates maintain significant influence, there remains substantial operational space for specialized manufacturers who compete on technical differentiation, application-specific engineering, and supply chain agility.
Prominent participants span multiple geographies and material competencies, reflecting the interdisciplinary nature of the market. Japanese material leaders such as Toray Industries, Inc. and Teijin Limited contribute advanced conductive fiber portfolios tailored for smart textiles, electronics integration, and sustainable advanced fiber solutions across automotive and medical domains. In Europe, Bekaert leverages its Bekinox® stainless steel fiber and yarn platform to serve smart textile, e-textile, data transmission, and durable EMI shielding applications, while Shieldex produces silver-plated conductive yarns and fibers for antistatic, antimicrobial, EMI shielding, and smart textile uses.
North American firms contribute critical technological depth across polymer-based and metalized fiber platforms. 3M Company supplies conductive fibers and related materials for EMI shielding, electrostatic dissipation, and high-performance industrial applications, while DuPont de Nemours, Inc. provides conductive fiber technologies integrated into advanced materials for electronics, wearables, and protective applications. Shakespeare Polymers & Filaments specializes in carbon-suffused nylon and polyester conductive fibers for electrostatic dissipative performance in ESD carpeting, industrial, and textile applications. Syscom Advanced Materials, operating under the Agsis brand, develops highly conductive yarns and fibers tailored for wearable technology and demanding engineering applications. Eeonyx Corporation emphasizes knitted conductive textiles and fibers designed for flexibility and comfort in wearable electronics, and Swift Textile Metalizing LLC focuses on metalized and conductive textile fibers for aerospace, defense, and EMI shielding applications.
In Asia, Haining Taierxin New Materials Co., Ltd. manufactures conductive filament yarns, conductive staple fibers, and anti-static fabrics for electronics, smart garments, and industrial protective clothing, while Kolon Industries, Inc. produces high-performance fibers including conductive variants for textiles and industrial applications. Seiren Co., Ltd. adds further depth with conductive textiles and fibers focused on smart clothing, automotive, and functional fabric solutions.
Recent Developments Reshaping Competitive Dynamics
Competitive positioning is being actively reshaped by product and portfolio developments that signal how firms intend to capture margin in adjacent application spaces. In January 2026, Haining Taierxin New Materials Co., Ltd. positioned itself as a leading manufacturer setting benchmarks in functional textiles, emphasizing conductive filament yarns and staple fibers for smart garments and EMI shielding. This portfolio positioning reflects a broader industry pattern in which regional manufacturers pursue technical credibility in high-value segments rather than competing solely on cost.
Prior to that, in January 2025, DexMat announced the launch of Galvorn C conductive yarn featuring high strength of 800 MPa, lower resistivity, and lower density, targeting advanced performance applications. Developments of this nature matter because they illustrate the directionality of material innovation: performance improvements in tensile strength, resistivity, and density directly influence design feasibility in wearable electronics and durable industrial deployments. Firms seeking to enter or expand within the conductive fibers value chain must evaluate whether their partner ecosystem can support these elevated performance thresholds without compromising scalability or cost discipline.
Market Dynamics Shaping the 2026 Competitive Environment
Demand Drivers and End-Use Capitalization
The demand environment for conductive fibers is being shaped by an expanding constellation of end-use requirements. Rising demand for smart wearables and e-textiles is accelerating innovation in flexible, durable conductive fibers with improved washability and signal transmission capabilities. This demand signal is not confined to consumer-facing product categories; it is also driving industrial investment in functional fabrics that must perform reliably under repeated mechanical stress, laundering cycles, and environmental exposure.
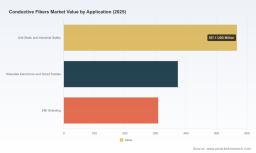
Anti-static and industrial safety applications continue to represent a foundational pillar of market consumption, particularly where electrostatic dissipation is critical to operational integrity in sensitive manufacturing and processing environments. At the same time, the wearable electronics and smart textiles domain has emerged as a growth engine that incentivizes material suppliers to refine stitchability, stretch tolerance, and long-term conductance stability. EMI shielding applications add a further dimension to demand, especially as electronic packaging becomes more compact and electromagnetic compatibility requirements intensify across automotive, healthcare, and communication equipment categories.
Material Economics and Supply-Side Considerations
Cost architecture remains a decisive factor in how conductive fibers are selected and deployed. Silver-coated and stainless steel fibers are widely used in conductive yarns, yet their economic profiles differ substantially. Stainless steel offers a significant cost advantage over silver while maintaining conductivity suitable for textile integration. For procurement and product strategy teams, this distinction is not merely a technical footnote; it structures volume planning, margin envelopes, and supplier selection criteria across applications where performance tolerances can accommodate steel-based solutions.
At the same time, premium silver-based solutions remain strategically important for applications where signal integrity, antimicrobial function, or higher conductivity thresholds justify the material premium. A rigorous market research perspective does not assume a single material winner across all use cases; instead, it maps the cost-performance frontier so that businesses can determine where stainless steel, carbon-based, metal-coated, or conductive polymer fibers provide the optimal balance of price, durability, and functional efficacy.
Regulatory Expectations and Quality Standards
Regulatory and standards-related expectations are becoming increasingly central to commercial viability. Conductive fiber products must comply with evolving safety standards and certifications for electrical conductivity, washability, and durability in smart textile and EMI shielding applications. Compliance requirements influence not only product design and testing protocols but also market access timelines, customer qualification cycles, and the credibility of supplier claims. Organizations entering this market must treat regulatory alignment as a strategic capability, not a downstream compliance task, because certification outcomes can determine the pace at which new fibers are adopted by risk-sensitive end users.
Worldwide Conductive Fibers Market
What the Research Delivers for Executive Decision-Making
A comprehensive market research study on conductive fibers provides more than headline growth figures. For 2026 decision-making, the value lies in structured, actionable intelligence that connects market sizing with the operational realities of product development, sourcing, and competitive positioning. The study is designed to support multiple decision contexts, from investment prioritization and portfolio strategy to supplier evaluation and market entry planning.
Central to the analysis is a detailed examination of market segmentation by region, type, and application. This segmentation enables readers to understand how revenue and growth are distributed across the major demand geographies and how material typologies align with specific application requirements. Rather than leaving executives to infer these dynamics from aggregate data, the report isolates the relative weight of each segment, helping teams assess where demand momentum is strongest and where competitive intensity is likely to intensify.
The research also builds a competitive landscape profile that examines the capabilities, positioning, and recent strategic moves of leading firms. By profiling companies across material categories and geographic bases, the study equips readers with a comparative framework for evaluating partnership opportunities, benchmarking internal R&D trajectories, and anticipating shifts in supplier power. Recent developments are incorporated directly into this competitive narrative, ensuring that the analysis reflects current portfolio actions rather than static corporate descriptions.
In addition, the study integrates market dynamics that shape near-term commercial outcomes. These include demand-side drivers, material cost considerations, and regulatory certification requirements that affect product viability. By embedding these dynamics into the analytical structure, the research helps organizations anticipate constraints and opportunities that could influence pricing, adoption speed, and market share retention.
The forecast component extends the analysis through 2032, giving readers a multi-year planning horizon. This forward-looking dimension is essential for capital-intensive decisions such as capacity expansion, long-term supplier contracts, and material innovation roadmaps. Executives can use the projection framework to test scenarios, set performance benchmarks, and evaluate how different growth assumptions might alter strategic priorities across the forecast window.
Translating Research into Actionable Strategy for 2026
For leaders operating in or adjacent to the conductive fibers ecosystem, the strategic implication of this market environment is clear: advantage will accrue to organizations that integrate materials intelligence into their broader commercial strategy. That integration requires more than awareness of growth trends. It requires an understanding of how segment economics, competitor actions, material cost differentials, and standards compliance interact to shape achievable positioning.
Companies evaluating product expansion can use the segmentation analysis to identify application overlaps where their existing capabilities may be extended into conductive fiber markets with lower barriers to entry. Organizations seeking supply chain resilience can use the competitive profiles and regional data to diversify sourcing strategies and reduce dependence on narrowly concentrated supply bases. Firms investing in innovation can benchmark recent product developments to determine whether their performance targets are aligned with the trajectory of customer expectations in wearable electronics, industrial safety, and EMI shielding.
The research also supports negotiation and partnership strategy. Because market concentration remains moderate, there is real scope for buyers and suppliers to structure relationships that balance cost efficiency with performance assurance. Understanding which firms occupy leadership positions in specific segments, and what recent portfolio moves suggest about their strategic intent, can inform supplier selection and joint development opportunities.
Why Detailed Intelligence Matters Now
The conductive fibers market is entering a phase where differentiation will depend on the precision of market understanding. Aggregate growth is encouraging, but execution depends on knowing which segments offer the most favorable risk-adjusted returns, which material platforms provide strategic flexibility, and how competitor activity is reshaping customer expectations. The Worldwide Conductive Fibers Market research study is built to provide that level of insight with the depth required for high-stakes planning.
Complete segment-level data, competitive positioning details, and forward-looking scenario analysis are presented in full within the report, enabling stakeholders to move from strategic curiosity to operational clarity. For executives responsible for product strategy, sourcing, or market expansion in 2026, the research offers a structured path to informed action.
To access the full analytical framework, segment breakdowns, and competitive intelligence needed for your strategic planning, we invite you to review the complete Worldwide Conductive Fibers Market research at the source page, where the complete dataset and detailed commentary are available for deeper evaluation.
For detailed analysis of this topic, please visit the official page: Worldwide Conductive Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com