

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Non-Filtering Cloth Vacuum Filters Market to Hit $378.74M by 2032 at 5.85% CAGR

Strategic Foresight for the Non-Filtering Cloth Vacuum Filters Market: Navigating Growth and Consolidation Through 2032
The global landscape for non-filtering cloth vacuum filters is undergoing a period of careful recalibration. As industrial operators prioritize solid-liquid separation efficiency, equipment uptime, and compliance with tightening hygiene and material standards, the demand for engineered cloth filters has evolved from a commodity consideration to a strategic operational variable. Our latest Worldwide Non-Filtering Cloth Vacuum Filters Market research translates this shift into a structured decision-making framework, offering a full historical arc from 2020 through 2025 and a forward-looking forecast spanning 2026 to 2032. The study is designed not merely to describe market size, but to equip procurement leaders, filtration engineers, and executive strategists with the intelligence needed to time investments, evaluate supplier partnerships, and align product roadmaps with where the industry is heading.
Worldwide Non-Filtering Cloth Vacuum Filters Market
The market has demonstrated steady expansion over the past five years, with recorded revenue progression reflecting both volume growth and incremental value migration toward engineered, application-specific cloth solutions. This trajectory carries forward into the forecast horizon, where the global market is projected to grow from a base of approximately USD 254.4 million in 2025 to an estimated USD 268.6 million in 2026, and onward to roughly USD 378.7 million by 2032. The compound annual growth rate across the forecast period is estimated at 5.85 percent, signaling a market that is expanding with discipline rather than volatility. Such a profile is important for planners: it suggests that growth will be driven by durable operational requirements across core sectors rather than by short-term speculation, allowing organizations to build longer-cycle strategies around supplier capacity, product specialization, and downstream application development.
Worldwide Non-pleated Air Filters Market
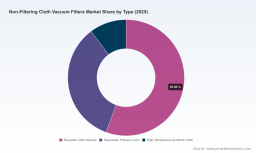
What makes this research actionable is its deliberate focus on where financial value and technical differentiation intersect. The report traces how revenue is distributed across the principal type categories, highlighting how reusable cloth sleeves continue to represent the largest share of the market, while disposable primary liners and high-temperature synthetic cloths occupy distinct operational niches with their own adoption drivers. It also examines application-side demand, showing how industrial vacuum systems command the largest portion of market activity, followed by commercial cleaning and residential vacuums. These structural insights matter because they reveal not only where dollars are being deployed today, but also where performance requirements, replacement cycles, and specification sensitivity are likely to shape future purchasing behavior. Importantly, the study preserves the analytical nuance needed to understand regional and segment-level momentum without reducing the market to a set of isolated figures. This enables readers to recognize which geographies and applications are expanding with the strongest relative intensity, while keeping the detailed breakdowns available in the full report for teams that require granular planning inputs.
Why 2026 Is a Decision Bottleneck for Filtration Buyers and Suppliers
The 2026 to 2032 window is more than a forecasting period; it is a strategic planning horizon for organizations that must commit now to material specifications, vendor relationships, and capacity arrangements. Several converging forces make the coming year particularly consequential. First, the broader filter cloth ecosystem continues to expand, with related synthetic filtration materials projected to approach USD 2.1 billion globally in 2026, reinforcing the scale of the underlying material supply chain and the incentives for specialization. Within that environment, non-filtering cloth vacuum filters are benefiting from sustained demand for more efficient solid-liquid separation in mining, minerals processing, and wastewater treatment, where improved cake dryness, flow rates, and equipment uptime translate directly into operational cost advantages.
At the same time, regulatory and application-specific expectations are increasing the cost of mismatched specifications. In food processing applications, vacuum filter cloths must satisfy food-grade certifications and hygiene standards such as FDA and CE to ensure safety and purity during liquid-solid separation. This is a meaningful shift for procurement teams, because it ties filtration performance not only to throughput, but also to documentation, traceability, and compliance readiness. Companies that design their sourcing and product selection around these standards gain a clearer path to qualification in sensitive industries, while those that treat filtration cloth as interchangeable risk qualification delays and operational rework.
Material science developments are also reshaping the competitive playing field. The continued use of polypropylene and polyester as primary materials in woven and non-woven cloths provides a familiar baseline, but innovation is increasingly concentrated in monofilament and multifilament synthetic yarns that enable custom vacuum filter belts with high dimensional stability and abrasion resistance across a wide range of micron ratings. Some manufacturers are supporting belt widths up to 4300 mm while maintaining tight tolerance requirements, an advancement that matters for large-scale continuous processes where uniformity and durability directly influence replacement frequency and process consistency. As these capabilities become more differentiated, procurement strategies that rely on generic specifications will increasingly fall short relative to engineered alternatives.
In parallel, industry activity in 2025 and into 2026 shows that participants are actively reinforcing their market presence through exhibitions, technical engagement, and customer recognition. Companies have been showcasing vacuum filter cloths and related filtration materials at major industry gatherings, including CINTE2025 and the 2025 China Shanghai International Filtration Industry Exhibition, while maintaining ongoing engagement around events such as FILTECH and FiltXPO. supplier performance is also receiving heightened attention, with recent recognition awarded to filtration suppliers for their contribution to industrial processes and supply reliability. These developments signal a market where visibility, technical demonstration, and proven supply dependability are becoming essential elements of commercial positioning.
Competitive Structure and What It Means for Strategic Sourcing
The market is characterized by a moderately concentrated competitive structure. The top three players account for an estimated 38.25 percent of market revenue, while the top five represent approximately 52.4 percent. This concentration suggests that a relatively small group of established suppliers holds meaningful share, yet there remains sufficient fragmentation for specialized manufacturers and regional players to compete on application expertise, customization, and responsiveness. For buyers, the implication is twofold: scale and consistency can be accessed through leading suppliers, but differentiated requirements often call for partners with targeted engineering capabilities and material knowledge.
Several companies illustrate the breadth of competitive approaches now shaping the market. Micronics Engineered Filtration Group, part of Cleanova and based in Chattanooga, Tennessee, specializes in custom-engineered filter media and cloths for vacuum filtration equipment, including rotary vacuum disc filters, drum filters, horizontal belt vacuum filters, and pan filters. Its applications span liquid-solid separation in mining, minerals, alumina refining, chemicals, and wastewater, reflecting a positioning built on engineered fit rather than broad commoditization.
Bolian Filtration Solutions Co., Ltd., headquartered in Tieling, Liaoning Province, China, manufactures woven filter cloths and fabrics specifically for vacuum filtration applications. Its product range covers horizontal vacuum belt filter cloths, rotary drum filter cloths, horizontal disc filter cloths, and specialized cloths for lithium battery and desulfurization processes in metallurgy, mining, chemicals, and new energy sectors. Bolian's recent visibility at filtration industry exhibitions and its recognition as an outstanding supplier at a major 2026 annual meeting underscore the growing importance of supplier reliability, technical alignment, and customer validation in a market where downstream processors are increasingly selective.
In Europe, GKD Group, headquartered in Düren, Germany, provides horizontal vacuum belt filters and associated filtration fabrics and belts, featuring wide throat vacuum boxes, pre-filtered cloth or belt wash water, and in-house manufactured spares. Its approach emphasizes integrated equipment and fabric support for efficient solid-liquid separation in industrial processes, an arrangement that can reduce coordination risk for operators seeking aligned system performance. Testori S.p.A., based in Novate Milanese, Italy, offers filter media including bags for vacuum disc filters, belts for vacuum belt filters, and cloths for vacuum drum filters, using various polymers and yarns tailored for solid-liquid separation with options for different cake discharge principles. K2TEC, based in France, manufactures filter belts and cloths for vacuum belt filters using PP, PES, PA, PVDF, and PTFE materials with micron ranges from 1 to 2000, and supports its products with patented closures and edge reinforcements for applications in chemical, mineral, pharmaceutical, and mechanical industries.
Together, these profiles show that the competitive field is not monolithic. Some participants compete through broad industrial coverage and custom engineering, others through material breadth and micron-level versatility, and others through integrated equipment-plus-fabric systems. This diversity gives buyers multiple paths to value, but it also increases the importance of clearly defining performance requirements before sourcing. The full report analyzes these competitive dynamics in greater depth, helping readers assess which supplier archetypes align with their operational priorities and where the market is most vulnerable to specification gaps, supply constraints, or quality variability.
How to Use the Report for 2026 Planning
This study is structured to support concrete decisions across the buying, engineering, and commercial functions. It provides a historical baseline from 2020 to 2025 for context, then extends into a ten-year forecast that allows organizations to model substitution patterns, replacement cycles, and application growth with greater confidence. The segmentation framework organizes the market by region, type, and application so that planners can see not only aggregate growth but also the structural composition beneath it. This is particularly useful for companies trying to determine whether demand is being led by industrial-scale process requirements, commercial cleaning operations, or residential vacuum use, and how those demand centers differ in specification sensitivity and purchasing rhythm.
The report also explores the dynamics that shape market behavior, including raw material considerations such as polypropylene, polyester, and polyamide usage; the role of monofilament and multifilament yarns in improving dimensional stability and abrasion resistance; and the growing importance of compliance requirements in food-related applications. These forces are not treated as background detail, but as factors that influence supplier selection, product design, and total cost of ownership. By connecting material trends with application needs, the research helps teams anticipate where specification upgrades are likely to become standard rather than optional.
For executives evaluating market entry, expansion, or partnership strategy, the study’s concentration analysis and company profiles provide a practical map of competitive intensity. Rather than relying on broad impressions, readers can identify which segments show the strongest momentum, where incumbent suppliers are well positioned, and where opportunities may exist for suppliers that can demonstrate specialized performance, reliable delivery, and regulatory readiness. The full version of the report contains the detailed segment splits and regional values needed for precise financial and operational planning, while this overview establishes the strategic logic behind those figures.
Read the Full Intelligence, Not Just the Trajectory
The Worldwide Non-Filtering Cloth Vacuum Filters Market research is built for organizations that require more than an aggregate growth narrative. It translates a market expanding from roughly USD 254.4 million in 2025 toward an estimated USD 378.7 million by 2032 into a usable planning foundation, with a forecast CAGR of 5.85 percent and a detailed segmentation structure that clarifies how type, application, and regional demand interact. It also situates the market within broader industry forces, from material innovation and equipment integration to compliance expectations and supplier recognition, so that decision-makers can align procurement and product strategy with where value is actually being created.
To access the complete segmentation data, detailed regional and application breakdowns, competitive profiles, and forward forecasts that support precise 2026 planning, readers are encouraged to view the full report through our official market intelligence portal. The overview above is intended to demonstrate the scope and analytical rigor of the study, while the full publication provides the depth required for sourcing decisions, investment planning, and long-range market positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Filtering Cloth Vacuum Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com