

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global GCB Market to Hit $548 Million by 2032, 6.81% CAGR Through 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave of Power Infrastructure: Strategic Insights from the Worldwide Digital Generator Circuit Breaker Market Study
The global energy transition is not merely shifting fuel sources; it is fundamentally rewiring the architecture of power generation and protection. As utilities and independent power producers navigate the dual pressures of decarbonization mandates and grid reliability, Generator Circuit Breakers (GCBs) have emerged as critical guardians of turbine integrity and plant uptime. Our newly released Worldwide Digital Generator Circuit Breaker Market report delivers a comprehensive, data-rich examination of this vital sector, equipping executive teams with the foresight required to optimize capital allocation, technology roadmaps, and competitive positioning through 2032.
A Market in Measured Expansion
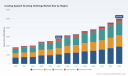
The trajectory of the global GCB market reveals a steady, structurally sound growth curve that rewards early strategic alignment. Between 2020 and 2025, the sector expanded from a baseline of approximately $252.14 million to $345.5 million, navigating supply chain recalibrations and macroeconomic volatility without losing momentum. Looking ahead, our baseline forecast places 2026 revenues at roughly $360.3 million, with a projected compound annual growth rate of 6.81 percent carrying the market to $547.57 million by 2032. This expansion is not accidental; it reflects the compounding impact of aging infrastructure replacement cycles, the commissioning of next-generation generation assets, and the accelerating digitization of plant protection systems. For capital planning teams, the message is clear: demand visibility is strong, but capturing it requires differentiated value propositions that transcend commodity pricing wars.
Technology Shifts Reshaping the Asset Base
The technological composition of the GCB landscape is undergoing a quiet but decisive transformation. Traditional SF6-insulated designs continue to hold substantial installed share, yet the market is increasingly tilting toward vacuum-based and air-insulated alternatives. This migration is being driven less by pure performance economics and more by the regulatory and ESG calculus surrounding fluorinated greenhouse gas emissions. Operators are now evaluating lifecycle environmental impacts alongside traditional interrupting capacity and short-circuit withstand metrics, a shift that has accelerated the adoption of vacuum interrupter architectures in both new builds and life-cycle retrofits. The resulting technology mix is fragmenting into distinct application niches, where duty-cycle requirements, generator sizing, and grid code compliance dictate technology selection. Our study dissects these technology pathways, mapping the engineering trade-offs that procurement and engineering teams must weigh when specifying protection systems for diverse generation profiles.
End-User Diversification and Application Realities
GCB demand is not monolithic. The market supply chain interfaces with a heterogeneous end-user base spanning thermal generation, hydropower, nuclear facilities, and emerging integrated gas and renewable platforms. Each segment imposes unique operational stresses and protection philosophies. Thermal and nuclear assets, with their high continuous currents and stringent reliability mandates, demand breakers engineered to specialized duty cycles that far exceed distribution-class specifications. Hydropower installations, meanwhile, require solutions capable of withstanding long mechanical endurance cycles and harsh environmental exposures. As grid architectures incorporate more decentralized and hybrid generation, the protection logic surrounding generator isolation is evolving, pushing manufacturers to deliver smarter, more adaptive interrupting solutions that integrate seamlessly with plant-level control architectures. The report segments these application realities with granular operational context, enabling stakeholders to understand where growth will materialize and which capability gaps represent the greatest commercial opportunity.
Worldwide Digital Generator Circuit Breaker (GCB) Market
Regional Realignment and Infrastructure Investment Cycles
Geographic demand patterns are being rewritten by localized energy security priorities, grid modernization budgets, and the pace of generation fleet turnover. Asia Pacific continues to anchor a substantial share of global activity, reflecting sustained investment in baseload and peaking capacity alongside rapidly expanding transmission infrastructure. Europe’s market is characterized by a emphasis on sustainability-compliant technologies, retrofitting of aging assets, and alignment with regional decarbonization frameworks. North America’s demand profile is shaped by reliability mandates, nuclear fleet extensions, and the ongoing modernization of both fossil and hydro generation assets. Meanwhile, the Middle East and Africa and Latin America represent high-growth frontiers where capacity expansion programs are driving new procurement waves. Our geographic analysis connects these regional narratives to underlying investment cycles, policy environments, and supply-side dynamics, providing a structured lens for market entry, partnership strategy, and localized capacity planning.
The Rise of Digital GCBs: From Interrupting to Intelligence
The defining innovation in the current market cycle is the transition from purely electromechanical interrupting devices to digitally enabled protection assets. These Digital GCBs embed smart monitoring, predictive maintenance capabilities, and communication protocols that transform breakers from passive safety components into active contributors to plant availability. By aggregating health data, enabling on-premise and cloud connectivity, and feeding asset management systems with real-time condition indicators, digital platforms are helping operators move from reactive maintenance to condition-based interventions. This shift carries profound implications for total cost of ownership, spare parts logistics, and overall plant reliability metrics. Our study examines how digitalization is being embedded across the value chain, from sensor integration and health diagnostics to cybersecurity considerations and interoperability with substation automation systems. For OEMs, the digital layer is becoming a differentiator and a recurring revenue frontier; for operators, it represents a pathway to extract more operational certainty from critical protection assets.
Competitive Landscape: Architects of the Next Generation of Protection
The global GCB arena is shaped by a concentrated group of incumbent manufacturers that have built deep engineering heritage, global service networks, and increasingly sophisticated digital portfolios. Market concentration data indicates that a small cohort of players commands a dominant share of deliveries, underscoring the importance of long-term supplier relationships and technology alignment in procurement strategy.
- Hitachi Energy stands as a historically dominant force in GCB technology, with a legacy spanning decades and thousands of field installations across demanding generation environments. The company’s recent strategic emphasis centers on digital integration, sustainability, and lifecycle management, exemplified by dedicated digital GCB platforms that tie into smart monitoring ecosystems for health data aggregation and predictive maintenance. Celebrating seven decades of innovation in early 2025, the firm has reinforced its commitment to enhancing generator protection through lifecycle optimization and connected asset management, positioning digital readiness as a core pillar of its value proposition.
- GE Vernova brings a broad, application-diverse portfolio to the market, with thousands of installations covering power plants across a wide capacity spectrum. Its product philosophy integrates optimized digital cooling solutions and intelligent communication capabilities to support real-time operational adjustments and remote health monitoring. In late 2025, the company updated its service documentation to accentuate maintenance, retrofit, and digital monitoring offerings, signaling an intensifying focus on post-sale value creation and the extension of asset service life.
- Siemens has carved a strong position around vacuum-based GCB systems that emphasize SF6-free operation and extended maintenance intervals, appealing to operators pursuing sustainability targets and reduced operational expenditure. Its portfolio supports generator and transformer protection with an emphasis on reliability, lifecycle efficiency, and compatibility with renewable integration strategies, aligning its technology roadmap with the broader decarbonization agenda.
- Eaton addresses specific segments of the market with medium-voltage generator breaker solutions engineered around rigorous industry duty requirements. Its vacuum-based families are designed to deliver high continuous current carrying capability and robust performance for smaller to medium generator sets, reflecting a focused engineering approach to specialized application duties and compliance-driven design.
Beyond product portfolios, the competitive arena is being reshaped by collaboration models, service bundling, and digital platform ecosystems. Firms are increasingly competing on total lifecycle value rather than unit price alone, integrating health monitoring, retrofit services, and remote diagnostics into long-term service agreements. Our competitive analysis unpacks these positioning strategies, service architectures, and innovation trajectories, offering a structured framework for benchmarking vendor capabilities and identifying partnership opportunities that align with your operational objectives.
Regulatory and Engineering Mandates as Market Catalysts
Market evolution does not occur in a vacuum; it is guided by international standards, safety requirements, and material constraints that define what is technically permissible and commercially viable. International standards such as IEC/IEEE 62271-37-013:2021 establish the performance framework for high-voltage generator circuit-breakers, specifying design expectations for indoor and outdoor installations operating above 1 kV up to 38 kV at 50/60 Hz. These standards reinforce the specialized nature of GCB design, distinguishing generator-duty requirements from distribution-class equipment and ensuring that interrupting performance, short-circuit ratings, and continuous current capabilities are validated under rigorous conditions.
Electronic Circuit Breaker Market
At the same time, engineering specifications anchored in standards such as IEEE C37.013 compel manufacturers and specifiers to approach generator protection as a distinct discipline, with unique duty cycles and reliability expectations. The material dimension adds another layer of strategic importance: the industry’s move away from SF6 toward vacuum interrupter technologies reflects both environmental compliance imperatives and corporate carbon reduction targets, influencing specification decisions across new builds and life-cycle upgrades. The report connects these regulatory and material dynamics to real-world procurement behavior, showing how standards compliance and sustainability preferences are steering technology selection, certification requirements, and service expectations across global markets.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Making
The Worldwide Digital Generator Circuit Breaker Market study is structured to support strategic decision-making at multiple levels, from corporate planning and technology investment to procurement policy and competitive positioning. It combines historical performance analysis with forward-looking forecasts, enabling readers to calibrate expectations against realized market behavior and projected growth corridors. The report provides:
- A structured market size and growth framework covering historical performance and the 2026–2032 forecast horizon, grounded in transparent methodologies and scenario-aware assumptions.
- Technology-based and end-user-based segmentation that clarifies how different application demands and engineering preferences drive volume distribution across the asset base.
- Regional demand mapping that links procurement momentum to infrastructure investment cycles, energy policy trajectories, and fleet renewal timelines.
- A competitive and vendor landscape analysis that evaluates product philosophies, digital service offerings, and lifecycle value propositions across leading manufacturers.
- An examination of the regulatory, standards-based, and material constraints shaping specification behavior and technology adoption.
- Practical strategic implications for operators, OEMs, service providers, and investors seeking to align capabilities with high-probability growth vectors.
Every section is designed to translate data into action. Rather than presenting isolated statistics, the analysis ties market size evolution, technology trends, and competitive moves to concrete executive questions: Which application segments are expanding demand fastest, and what capability gaps do they reveal? How does the digital layer change the economics of ownership and service? Where do standards and sustainability considerations most strongly influence specification decisions? What supplier relationships and partnership models will matter most in a concentrated, high-expertise market?
Strategic Imperatives for the Year Ahead
As 2026 unfolds, three strategic imperatives stand out for organizations operating in or adjacent to the GCB market. First, technology alignment is becoming a strategic differentiator: the shift toward vacuum and air-insulated architectures, combined with embedded digital monitoring, is changing the value calculus of protection assets and rewarding suppliers and operators who can navigate lifecycle environmental performance alongside electrical reliability. Second, digital value capture is moving from pilot to practice: health data aggregation, predictive maintenance, and connected asset management are transitioning from experimental features to core components of service contracts and uptime guarantees, creating new commercial models and new risk dimensions around data integration and cybersecurity. Third, regional nuance matters more than ever: procurement outcomes will increasingly depend on localized investment timing, regulatory expectations, and the maturity of service and retrofit ecosystems, making geographic precision essential for both market entry and supplier selection.
The Worldwide Digital Generator Circuit Breaker Market report is built to help leadership teams navigate these imperatives with confidence. By combining rigorous market sizing, segmentation clarity, competitive intelligence, and forward-looking scenario context, it offers a decision-grade foundation for capacity planning, technology roadmap development, vendor evaluation, and growth strategy. The full study contains the detailed data tables, segmentation breakdowns, regional analyses, and vendor profiles that executives and analysts require to translate market dynamics into executable strategy.
To access the complete forecast models, segmentation depth, and competitive benchmarking, visit the source page for the full Worldwide Digital Generator Circuit Breaker Market research. Obtain the full intelligence set and position your organization to act decisively on the opportunities shaping the next phase of generator protection and digital power infrastructure.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Generator Circuit Breaker (GCB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global IT Infrastructure Outsourcing Market Hits $435.5B in 2025 with 6.74% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Crossroads: Strategic Intelligence for the Global IT Infrastructure Outsourcing Market in 2026
In an era defined by rapid digital transformation, escalating cyber threats, and the convergence of artificial intelligence with core enterprise operations, IT infrastructure outsourcing has evolved from a cost-optimization tactic into a strategic imperative. As organizations worldwide recalibrate their technology stacks, the Worldwide IT Infrastructure Outsourcing Service Market has emerged as a critical battleground for competitive advantage, operational resilience, and regulatory compliance. This foundational industry analysis, grounded in rigorous historical tracking and forward-looking modeling, offers decision-makers a clear lens through which to evaluate one of the most consequential outsourcing segments of the decade.
Drawing on comprehensive data spanning 2020 through 2025 and projecting trends across a seven-year forecast horizon through 2032, the research captures not merely the trajectory of spending but the structural shifts redefining how enterprises consume, manage, and secure technology services. By synthesizing macroeconomic indicators, service-model evolution, and competitive positioning, this report equips executives with the contextual depth required to navigate procurement strategies, vendor selection, and long-term infrastructure roadmaps with confidence.
Worldwide Infrastructure as a Service Market
Historical Trajectory and the Scale of Transformation
The market has exhibited remarkable resilience and sustained growth throughout the tracking period. Starting from a baseline in 2020, the global revenue generated by IT infrastructure outsourcing services has expanded consistently, reflecting heightened enterprise dependency on outsourced operations amid cloud migration acceleration, legacy system modernization, and post-pandemic operational recalibrations. By the most recent measurement year, the market had crossed a significant threshold, signaling mature adoption patterns and the normalization of infrastructure outsourcing as a core business function rather than a peripheral support activity.
Looking ahead, the projected expansion through 2032 underscores a compounding growth dynamic. At a compounded annual growth rate of 6.74 percent, the market is positioned to traverse into materially higher revenue tiers over the forecast window. This trajectory is not merely a function of incremental spend; it reflects deepening enterprise commitments to integrated outsourcing models that bundle network operations, managed hosting, infrastructure management, and security oversight into cohesive delivery frameworks. For procurement leaders and C-suite strategists, such sustained expansion signals that the outsourcing landscape will remain highly active, competitively intense, and continuously reshaped by technological and regulatory forces.
Architectural Shifts Redefining Service Consumption
The composition of outsourced IT infrastructure has fundamentally restructured itself. What was once a spectrum dominated by standalone data center leases and routine help desk engagements has matured into a portfolio of sophisticated, interlocked service lines. Enterprises increasingly view outsourcing not as a series of discrete transactions but as an operational architecture that must deliver scalability, visibility, and risk mitigation simultaneously.
Managed hosting and data center services continue to anchor the market, reflecting enduring demand for reliable, geographically diversified compute environments. Yet the fastest-growing areas of investment are emerging where infrastructure services intersect with security postures, cloud orchestration, and AI-enabled monitoring. Network outsourcing remains essential for maintaining global connectivity and complex routing environments, while managed security services have become inseparable from infrastructure contracts as organizations confront the reality that uptime without protection carries unacceptable business risk. End-user support and help desk functions have also transformed; rather than being treated as reactive cost centers, they are being integrated into proactive service models that leverage automation, predictive diagnostics, and omnichannel engagement.
This structural rebalancing matters for strategy because it directly influences vendor evaluation criteria, contract architecture, and service-level expectations. Organizations that continue to evaluate outsourcing proposals through a narrow cost-per-ticket or per-server lens risk overlooking the value layers that now define market leadership: integrated threat detection, compliance assurance, hybrid environment orchestration, and AI-augmented operational intelligence.
Worldwide IT Infrastructure Outsourcing Service Market
Competitive Dynamics Among Enterprise-Scale Providers
The provider landscape is populated by global firms with distinct geographic footprints, delivery models, and strategic positioning. Market concentration, as measured by the combined share of leading participants, remains moderate, indicating a competitive field with room for differentiation and consolidation. This dispersion is significant for decision-makers because it implies that procurement leverage, specialized capability pairing, and partnership structuring can materially influence outcomes.
Several multinational integrators and technology consultancies anchor the upper tier of the market. Each brings a differentiated mix of managed services, cloud operations, hybrid infrastructure support, and cybersecurity integration. Providers headquartered in North America and Europe maintain strong enterprise relationships and compliance-oriented delivery frameworks, while firms based in India and other high-scalability regions contribute scale, depth in infrastructure operations, and expanding capabilities in digital transformation and automation. Japan-based organizations extend global reach through established enterprise relationships and group synergies that span infrastructure, cloud management, and end-to-end IT operations.
What distinguishes competitive positioning in this environment is rarely a single offering. Instead, differentiation emerges from how providers combine data center management, network and infrastructure management, hybrid cloud capabilities, security integration, and industry-specific solutioning. The ability to operate across multiple service domains while maintaining rigorous controls, geographic flexibility, and contractual transparency has become a decisive factor in vendor selection. Organizations evaluating partners must therefore assess portfolios holistically, prioritizing providers whose delivery models align with specific risk tolerances, compliance regimes, and operational ambitions.
Regulatory Pressure and Compliance as Operational Gatekeepers
The outsourcing environment is increasingly defined by regulatory expectations that transform compliance from an administrative afterthought into an operational gatekeeper. Cybersecurity now stands alongside infrastructure services as one of the most frequently outsourced functions, reflecting board-level recognition that external expertise is essential for maintaining resilient security postures across complex, distributed environments. This shift is amplified by mandatory standards and frameworks that span data protection, transaction integrity, and operational transparency.
Providers and their clients are navigating an expanding matrix of compliance requirements. Data privacy and security obligations tied to GDPR, HIPAA, PCI DSS, and SOX continue to shape contracting practices, service design, and audit expectations. In parallel, certification and governance regimes such as SOC 2, ISO 27001, and emerging AI governance standards are becoming baseline expectations for organizations seeking to de-risk third-party relationships. Continuous vendor risk assessment, documented control environments, and transparent audit trails are no longer optional enhancements; they are prerequisites for long-term outsourcing engagements.
Cross-border dynamics add further complexity. Recent regulatory instruments, including stringent controls on transactions involving bulk sensitive personal data, impose heightened cybersecurity obligations and record-keeping requirements on international service arrangements. As a result, enterprises must weigh not only cost and capability but also jurisdictional exposure, data residency considerations, and the regulatory readiness of prospective partners. For procurement teams, compliance literacy has become a core competency, and vendor assessments must include rigorous review of security architectures, incident response processes, and governance maturity.
Labor Economics, Geographic Strategy, and the Push Toward Intelligent Delivery
The economics of outsourcing delivery are undergoing a meaningful recalibration. Rising labor costs in traditional outsourcing hubs have begun to reshape location strategies and operating models. Providers are responding with a combination of nearshoring, automation, and intelligent service design. This evolution is not simply a cost-response measure; it reflects a broader rethinking of how infrastructure services are delivered, monitored, and optimized.
AI-enabled management and automation are increasingly embedded into delivery frameworks. Predictive maintenance, automated incident triage, policy-driven orchestration, and agentic workflow integration are transitioning from experimental initiatives to operational realities. Recent strategic moves by major providers illustrate this momentum, including acquisitions and partnerships designed to embed advanced AI capabilities into business-process and infrastructure delivery. These developments signal that competitive differentiation will increasingly depend on how effectively providers blend human expertise with automated intelligence to reduce latency, improve accuracy, and scale service delivery without proportionally escalating cost structures.
For enterprises, this dynamic creates both opportunity and caution. Automation can unlock efficiency, but it also raises questions about service quality assurance, exception handling, and the strategic role of in-house teams. Organizations must define where intelligent automation adds genuine value and where human oversight remains essential, particularly in environments with stringent uptime requirements or sensitive operational contexts.
Strategic Imperatives for Enterprise Decision-Makers in 2026
As the market expands and its architecture grows more complex, strategic decision-making must move beyond transactional procurement. Several imperatives stand out for organizations planning their infrastructure outsourcing strategies over the coming years.
- Evaluate providers against an integrated capability baseline that includes hybrid infrastructure management, security integration, compliance readiness, and cloud orchestration rather than isolated service checklists.
- Treat regulatory alignment as a primary selection criterion, ensuring that partners can demonstrate control maturity, audit transparency, and the ability to adapt to evolving cross-border data and cybersecurity requirements.
- Structure contracts to incentivize outcomes, not only cost containment. Service-level frameworks should reflect integrated monitoring, proactive threat response, and continuous improvement expectations.
- Incorporate AI-augmented delivery and automation into sourcing evaluations, assessing how providers use intelligent tools to improve reliability, reduce response times, and manage scale efficiently.
- Balance global scale with geographic flexibility. Where labor economics, data residency, and latency concerns intersect, nearshoring and multi-region delivery models may offer more resilient operating postures than single-hub dependency.
Why Comprehensive Intelligence Matters Now
The Worldwide IT Infrastructure Outsourcing Service Market is at an inflection point where growth, technology convergence, and regulatory pressure intersect. In such an environment, partial visibility can lead to suboptimal vendor selection, misaligned contract structures, and unanticipated compliance exposure. Executive teams require market intelligence that connects historical performance, forward-looking projections, service-model evolution, and competitive dynamics into a coherent strategic framework.
This research report delivers exactly that synthesis. It provides a structured foundation for evaluating market direction, understanding the forces reshaping service demand, and identifying the criteria that will separate reliable partners from commoditized providers. By integrating rigorous market sizing, segmentation architecture, competitive profiling, and industry-context dynamics, the analysis supports more disciplined planning across procurement, IT leadership, risk management, and enterprise strategy functions.
To access the complete segment breakdowns, detailed competitive profiles, methodology depth, and forward-looking scenario analysis that support these insights, readers should consult the full report. The complete dataset and proprietary intelligence are essential for organizations seeking to convert market awareness into actionable, differentiated strategy.
For detailed analysis of this topic, please visit the official page: Worldwide IT Infrastructure Outsourcing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global 5G-Advanced Chip Market Poised to Hit $41.5B by 2032 at 40.45% CAGR
By pmarketresearch, 2026-09-16
Navigating the 5G-Advanced Chip Revolution: Strategic Intelligence for 2026 Enterprise Decisions
The global semiconductor landscape is undergoing a tectonic shift, driven by the transition from initial 5G deployment to the sophisticated capabilities of 5G-Advanced. As enterprises across telecommunications, automotive, industrial manufacturing, and consumer technology sectors evaluate their roadmaps for the latter half of the decade, the hardware foundation supporting these networks has become a critical variable in strategic planning. PW Consulting's latest Worldwide 5G-Advanced Chip Market report offers a comprehensive lens into this transformation, providing decision-makers with the data density required to navigate a market defined by rapid escalation and intense technological competition.
For stakeholders operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for capital allocation, supply chain resilience, and product portfolio optimization. The market has moved from nascent experimentation to high-volume commercialization, creating a complex environment where timing and technological alignment determine competitive advantage. This introduction outlines the strategic value embedded within our latest research, highlighting the market dynamics, competitive currents, and technical specifications that will define success in the coming years.
Market Trajectory and Macroeconomic Scale
The velocity of growth in the 5G-Advanced chip sector is unprecedented. Our analysis tracks the market evolution from a historical baseline through a forecast period extending to 2032. The data reveals a steep adoption curve that underscores the accelerating integration of advanced wireless capabilities into diverse hardware ecosystems. Starting from a foundational period, the market crossed significant thresholds in the early 2020s, with revenue figures climbing sharply as infrastructure and devices began aligning with evolving 3GPP standards.
Worldwide 5G Processor Market
By 2025, the market had reached substantial scale, reflecting the culmination of years of research and development into commercially viable products. Looking forward to 2026, the projected revenue continues to expand at a pace that demands attention from investors and corporate strategists alike. The compound annual growth rate (CAGR) observed over the forecast period indicates a sustained surge, driven by the proliferation of high-performance applications that require more than legacy connectivity. This growth is not linear; it is compounded by the expanding addressable market as 5G-Advanced features move from premium segments to broader industrial and consumer use cases.
The forecast horizon through 2032 suggests that the peak of this investment cycle is still ahead. Organizations that analyze these trends now can position themselves to capture value before the market matures and competition intensifies further. The sheer magnitude of the revenue projections emphasizes that 5G-Advanced is not a niche enhancement but a foundational shift in how connectivity is engineered and monetized.
Segmentation Dynamics: Types, Applications, and Regions
A granular understanding of where value is being created is essential for targeted strategy. The market is diversified across chip types, application verticals, and geographic regions, each with distinct growth drivers and technical requirements. Our report dissects these segments to reveal the underlying forces shaping demand.
In terms of chip architecture, the market is dominated by baseband processing capabilities, which form the core of signal handling and protocol management. However, the ecosystem is equally dependent on radio frequency (RF) transceivers and front-end modules, as well as power management solutions that ensure efficiency in high-performance deployments. The balance between these components reflects the broader engineering challenges of 5G-Advanced, where bandwidth, latency, and energy consumption must be optimized simultaneously.
On the application side, mobile devices and wearables remain a primary consumption channel, leveraging advanced modems to deliver enhanced user experiences. Yet, the industrial sector is emerging as a powerful growth engine. Industrial IoT and robotics applications are increasingly reliant on robust, low-latency connections that 5G-Advanced chips enable, facilitating automation and real-time data analytics at the edge. Automotive and vehicle-to-everything (V2X) communications represent another critical vector, where safety and connectivity intersect to redefine transportation infrastructure. Fixed wireless access continues to play a role in bridging connectivity gaps, supported by chipsets designed for robust network performance.
Geographically, the market distribution highlights the concentration of manufacturing and deployment capabilities. Asia Pacific stands out as a significant hub, reflecting the region's dense manufacturing base and rapid technology adoption. North America and Europe also contribute substantial shares, driven by infrastructure investment and enterprise innovation. Emerging regions are beginning to integrate into this global supply chain, adding layers of complexity and opportunity for companies with international operational footprints.
The Competitive Arena: Leaders and Innovators
The competitive landscape of the 5G-Advanced chip market is characterized by a mix of established giants and specialized innovators, each pursuing distinct strategies to capture market share. Market concentration metrics indicate that a small number of players control a significant portion of the revenue, underscoring the high barriers to entry and the capital intensity of advanced semiconductor development. The top three players account for a dominant share, while the top five extend their influence further, shaping the standards and supply dynamics of the industry.
Qualcomm Technologies, Inc., based in San Diego, remains a pivotal force with its lineup of 5G-Advanced modem-RF systems. Their platforms, including the Snapdragon X85 and X80, support 3GPP Release 18 features across smartphones, fixed wireless access, automotive, and infrastructure segments. In March 2026, Qualcomm announced the Qualcomm X105 5G Modem-RF, described as the world's first 3GPP Release 19-ready modem. This launch integrates enhanced 5G-Advanced performance with AI capabilities, with sampling to customers underway and commercial devices anticipated in the second half of 2026. Such moves signal a continuous iteration cycle where leadership is maintained through rapid product evolution.
MediaTek Inc., headquartered in Hsinchu, Taiwan, offers a broad portfolio of 5G-Advanced solutions. Their M90 modem and T930 flagship platform for fixed wireless access and customer premises equipment support Release 18 standards. MediaTek has also emphasized MIMO enhancements, with 8Rx/3Tx configurations delivering significant spectrum efficiency gains. In March 2026, the company showcased the world's first 5G-Advanced CPE device with Wi-Fi 8 powered by the T930 chipset, highlighting improvements in uplink performance and AI-driven quality of service engines. Additionally, MediaTek introduced new 5G-Advanced telematics chipsets, expanding their reach into automotive applications.
Samsung Electronics Co., Ltd., in Suwon, South Korea, operates with a dual role in modem and smartphone integration. Their Exynos processors and 5G-Advanced chipsets leverage advances in GAA transistor technology and high-bandwidth memory to support high-performance wireless applications. This vertical integration allows Samsung to optimize performance across the device stack, a strategic advantage in the mobile and infrastructure sectors.
Broadcom Inc., located in San Jose, California, focuses on infrastructure-grade solutions. Their BroadPeak 5nm Massive MIMO SoC platform is designed for 5G-Advanced and 6G-ready infrastructure, incorporating RF and converter technology with FPGA interoperability for wideband radios. In February 2026, Broadcom completed interoperability testing of Agilex 7 FPGAs with the BroadPeak SoC platform at 32.44Gbps JESD204C, enabling scalable beamforming and AI-assisted signal processing. These collaborations highlight the importance of open architectures in scaling network capabilities.
Other notable players include GCT Semiconductor Holding Inc., which announced first commercial shipments of its 5G chipset in January 2026 for applications including air-to-ground networks, marking a milestone in niche deployment areas. Sequans Communications, based in Paris, is developing 5G NR eRedCap chipsets with platforms like Monarch 3 and Calliope 3, supporting the transition to 5G-Advanced IoT with low-energy designs. Huawei Technologies Co., Ltd., in Shenzhen, supplies 5G-Advanced chipsets and infrastructure solutions with demonstrated applications in robotics and healthcare. Intel Corporation, in Santa Clara, offers infrastructure-focused chipsets and network processors supporting edge computing and base station solutions. Together, these companies illustrate the breadth of innovation driving the market.
Industry Dynamics and Technological Catalysts
Beyond company actions, the market is shaped by broader industry dynamics including standardization, regulatory frameworks, and manufacturing infrastructure. The 3GPP Release 18 specifications define the core features of 5G-Advanced, introducing enhancements in advanced downlink and uplink MIMO, AI/ML data-driven designs, energy-efficient networks, evolved duplexing, RedCap evolution, and expanded positioning. These specifications form the technical backbone that chipsets must support, creating a standardized baseline for interoperability and performance.
The Global System for Mobile Communications Association (GSA) tracks the ecosystem's readiness, noting that as of May 2025, five modems supported 5G-Advanced features with 75 devices hardware-compatible with Release 18, primarily using Qualcomm Snapdragon platforms. Increased device launches are expected from late 2025 onward via Snapdragon X85 adoption, indicating a pipeline of products ready to absorb advanced chip capabilities.
Regulatory and investment environments also play a crucial role. The U.S. CHIPS Act has driven substantial semiconductor supply chain investments, including advanced packaging and GaN-on-SiC fabs for 5G/6G, radars, and satellite technologies. TSMC's Arizona facilities are producing advanced nodes such as 4nm, 3nm, and 2nm, supporting high-volume manufacturing of chips for 5G/6G smartphones and related applications. These infrastructure developments reduce supply bottlenecks and enable the production of the complex chips required for next-generation networks.
Worldwide 5G-Advanced Chip Market
Additionally, material science trends influence component selection. GaN RF chips account for over half of RF chips in telecom equipment and are projected to reach up to 90% market share due to requirements for high-frequency mmWave 5G-Advanced signal amplification. This shift impacts procurement strategies and supply chain planning for organizations involved in RF front-end design.
Strategic Imperatives for 2026 and Beyond
For enterprises operating in 2026, the insights contained in this report translate into actionable intelligence across several dimensions. Procurement teams must evaluate supplier capabilities against the backdrop of rapid product cycles and evolving standards. Understanding which chip types and architectures align with specific application requirements can optimize performance and cost. Supply chain managers need to assess the geographic distribution of manufacturing and the impact of government incentives on availability and lead times.
Product strategists should consider how 5G-Advanced features can be leveraged to differentiate offerings in competitive markets. The convergence of AI integration with modem technology, as seen in recent launches, opens new possibilities for intelligent connectivity and network optimization. Meanwhile, the growth in industrial IoT and automotive segments suggests opportunities for cross-industry collaboration and new business models.
Investors and analysts can use the market size projections and segmentation data to inform capital allocation and valuation models. The high CAGR and expanding revenue base indicate a sector with significant upside, but also one where competitive positioning and technological execution will determine long-term winners. The concentration of market share among top players suggests that partnerships, licensing, and ecosystem access may be as important as raw manufacturing capacity.
Risk management is another critical area. The reliance on specific standards, materials, and manufacturing nodes introduces vulnerabilities that must be mitigated through diversification and scenario planning. Regulatory changes and geopolitical factors can influence supply chain flows and market access, requiring continuous monitoring and adaptive strategies.
Accessing Comprehensive Intelligence
This overview provides a snapshot of the strategic landscape surrounding the Worldwide 5G-Advanced Chip Market. However, the full depth of analysis required for precise decision-making is contained within the complete report. Detailed segmentation data, historical trends, forecast models, and company profiles offer the granularity needed to validate hypotheses and build robust strategies.
PW Consulting's research is designed to serve as a foundational tool for executives, planners, and technical leaders who need to navigate the complexities of this high-growth market. The report integrates quantitative data with qualitative insights, covering the interplay of technology, competition, and regulation that defines the industry.
For organizations seeking to secure their position in the 5G-Advanced era, access to comprehensive market intelligence is not optional. We invite stakeholders to explore the full report for detailed figures, regional breakdowns, application-specific forecasts, and in-depth competitive analysis. Engaging with this intelligence now will ensure that your organization is prepared to capitalize on the opportunities of 2026 and beyond, with a clear view of where the market is heading and how to reach it.
Visit our research portal to access the complete Worldwide 5G-Advanced Chip Market report and equip your team with the insights needed to lead in this dynamic landscape.
For detailed analysis of this topic, please visit the official page: Worldwide 5G-Advanced Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Diet Pet Food Hits $17.54B in 2025, Projected 7.12% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Prescription Diet Pet Food Market: A 2026 Outlook
Executive Overview
The global prescription diet pet food market stands at a critical inflection point as we move through 2026. What was once a niche segment confined to clinical veterinary recommendations has evolved into a mainstream pillar of pet health management, driven by rising pet humanization, increased awareness of preventive nutrition, and a shift toward condition-specific therapeutic feeding. For industry stakeholders, understanding the trajectory of this market is no longer optional—it is a strategic necessity. Our latest comprehensive analysis, Worldwide Prescription Diet Pet Food Market, provides decision-makers with the granular intelligence required to navigate growth, competitive pressure, regulatory complexity, and supply chain volatility through 2032.
Over the historical analysis window from 2020 to 2025, the market demonstrated consistent and accelerating expansion, with total revenue climbing from approximately 12,450.6 million USD to 17,540.0 million USD. This trajectory underscores more than mere recovery from earlier disruptions; it reflects structural demand shifts that have fundamentally altered how pet owners, veterinarians, and manufacturers approach animal health nutrition. Looking forward, the forecast period spanning 2026 through 2032 projects the market reaching an estimated 28,387.13 million USD by the terminal forecast year, underpinned by a compound annual growth rate of 7.12 percent. These figures are not abstract projections—they represent the aggregate outcome of therapeutic adoption curves, channel expansion, and product innovation dynamics that our report dissects across multiple operational dimensions.
Macro Growth Trajectory and What It Means for 2026 Strategy
The market's upward momentum is not linear, and treating it as such creates strategic blind spots. The expansion observed between 2020 and 2025 reveals a segment that has built Resilience against economic headwinds while capitalizing on the growing preference for veterinary-supervised nutritional interventions. By 2026, the market has already crossed the 19,602.15 million USD threshold, signaling that the era of incremental growth has given way to a more aggressive adoption phase. Companies entering this window with outdated assumptions about market maturity will find themselves misaligned with both consumer behavior and veterinary prescribing habits.
The forecast arc from 2026 onward illustrates compounding growth, with revenue milestones reaching 20,227.39 million USD in 2027, 22,424.38 million USD in 2028, and continuing to escalate toward the late-2030s. This progression highlights the importance of timing in capacity planning, portfolio investment, and geographic prioritization. Manufacturers that scale too conservatively risk ceding shelf space and veterinary preference to competitors who move decisively. Conversely, those that overinvest without sufficient segmentation intelligence may find themselves burdened by misalignment between product formats and regional demand profiles. Our research isolates the inflection points where these decisions must be made, offering forward-looking indicators rather than backward-looking summaries.
Strategic planning for 2026 requires appreciation of how the growth rate is distributed across different market vectors. While top-line figures capture attention, the operational reality is that growth emanates from distinct drivers—veterinary channel consolidation, expanded condition coverage, format diversification between dry and wet therapeutic offerings, and the gradual penetration of emerging markets where pet healthcare infrastructure is still maturing. Each of these vectors carries its own risk-return profile, and our report maps them against practical decision frameworks.
Structural Demand Drivers Shaping Strategic Planning
Several interconnected forces are propelling the prescription diet segment beyond traditional boundaries. Pet owners increasingly view animals as family members, transforming purchasing behavior from cost-conscious commodity selection to value-driven health investment. This cultural shift has reinforced veterinary authority as the primary gatekeeper for therapeutic nutrition, ensuring that prescription diets retain a moat that over-the-counter wellness products cannot easily breach. At the same time, veterinary clinics themselves are evolving into broader wellness centers, integrating nutritional counseling into routine care and expanding the touchpoints where prescription diets are recommended.
Regulatory frameworks continue to shape market conduct in ways that reward compliance and penalize ambiguity. In the United States, prescription pet foods require veterinary authorization for sale under FDA guidelines to ensure that therapeutic claims are substantiated, reinforcing the clinical credibility of the category and limiting informal distribution pathways. Concurrently, AAFCO mandates nutritional adequacy statements and ingredient listing in descending order by weight for all complete and balanced pet foods, establishing baseline transparency expectations that influence consumer trust and formulation strategies. These standards do not merely constrain—they provide a structured environment in which brands can differentiate through verifiable efficacy and clear labeling discipline.
On the supply side, raw material volatility has introduced a new layer of strategic consideration. Chicken meal prices rose 8 percent year-over-year to 1,450 USD per metric ton due to avian influenza impacts, illustrating how protein ingredient markets can fluctuate in response to disease outbreaks and agricultural disruptions. For manufacturers of therapeutic diets, where consistency and nutritional precision are paramount, sourcing resilience is not a back-office concern—it is a product integrity issue. The report examines how leading players are adjusting procurement strategies, reformulation buffers, and supplier diversification to mitigate these exposures without compromising formulation integrity.
Regional and Segment Dynamics Without the Noise
The market's geographic footprint reflects differing stages of maturity, veterinary infrastructure, and consumer acceptance of therapeutic nutrition. North America continues to anchor a substantial share of global revenue, supported by high veterinary engagement rates, established prescription channels, and strong brand loyalty among consumers who trust clinician recommendations. Europe represents a similarly significant base, shaped by robust regulatory oversight, including EU Regulation (EC) No 183/2005, which requires registration of pet food establishments and imposes strict additive limits for imported veterinary diets. These regulatory conditions influence both market entry timing and formulation adaptation requirements for multinational players.
Asia Pacific, Latin America, and the Middle East and Africa collectively represent growth frontiers where the prescription diet concept is still gaining structural footholds. In these regions, the pace of expansion is influenced by the gradual professionalization of veterinary care, the spread of premium pet retail formats, and the extent to which local regulatory environments align with international standards. Our analysis avoids simplistic regional rankings and instead evaluates each geography across adoption readiness, channel accessibility, and competitive intensity, allowing leaders to prioritize investments where the marginal return justifies the execution complexity.
Segmentation across pet types reveals the relative weighting of canine and feline therapeutic demand, with canine prescriptions historically commanding a larger revenue contribution due to broader market penetration and a wider array of condition-specific formulations. Feline prescription diets, while smaller in absolute terms, are experiencing targeted growth as veterinary awareness of cat-specific health challenges—such as renal function, urinary tract maintenance, and weight management—continues to deepen. The report further dissects condition-level demand, where weight management, digestive care, renal and urinary care, skin and food sensitivities, and diabetes and other conditions each carry distinct formulation requirements, veterinarian engagement patterns, and consumer education needs. Rather than providing static percentage splits, we analyze how these condition categories interact with product format, pricing tolerance, and prescription frequency to reveal which therapeutic subcategories offer the most actionable growth opportunities in the current cycle.
Competitive Landscape: Concentration, Innovation, and Channel Control
The prescription diet market is characterized by a high degree of competitive concentration, with the top three players collectively accounting for 68.45 percent of market revenue and the top five extending that share to 82.12 percent. This concentration is not accidental—it reflects the structural advantages of established veterinary relationships, extensive clinical research portfolios, and manufacturing scale that creates barriers for newcomers. Yet concentration does not imply stagnation. The leading companies continue to compete aggressively on formulation innovation, channel reach, and brand trust, and our report evaluates each major player through the lens of strategic positioning rather than mere market share.
Hill's Pet Nutrition, headquartered in Topeka, Kansas, offers a Prescription Diet line with over 40 therapeutic formulas for dogs and cats addressing conditions like kidney disease, urinary health, obesity, and dermatology issues, available exclusively through veterinarians. This exclusive channel strategy reinforces clinical authority and limits dilution, while the breadth of formulas provides veterinarians with a comprehensive toolkit for varied cases. In October 2024, Hill's launched Prescription Diet k/d Chicken & Vegetable Stew for cats to support kidney health, demonstrating a focus on format innovation and palatability enhancement for hard-to-feed patients. For competitors, this signals that texture, flavor, and patient compliance are becoming as strategically relevant as nutrient profiles themselves.
Royal Canin, based in Aimargues, France, provides a Veterinary Diet range including formulas for gastrointestinal, cardiac, joint, and renal support in dogs and cats, sold via veterinary channels worldwide. Its global distribution footprint and condition-specific portfolio make it a persistent benchmark for international scalability. In June 2024, Royal Canin introduced new size options for Veterinary Diet Renal Support wet formulas, addressing a practical pain point in multi-pet households and varying patient appetites. This type of incremental product architecture improvement may appear modest, but it directly influences repeat purchase behavior and veterinary recommendation consistency.
Nestlé Purina PetCare, operating from St. Louis, Missouri, markets Pro Plan Veterinary Diets with specialized nutrition for allergies, critical care, weight management, and orthopedic needs in pets, distributed through vets. Its participation in major industry events underscores the importance of visibility and education in a category where veterinarian confidence drives adoption. In March 2024, Nestlé Purina showcased updated Pro Plan Veterinary Diets at Global Pet Expo, using the platform to communicate formulation advancements and reinforce relationships with the veterinary community. Such engagements are not just marketing—they are strategic investments in the prescription pathway itself.
Virbac, headquartered in Carros, France, focuses on Veterinary HPM diets targeting obesity, urinary, and skin conditions for dogs and cats through prescription-only therapeutic nutrition. Its positioning illustrates how specialized brands can compete by emphasizing distinct formulation philosophies and targeted condition coverage rather than attempting to match the breadth of larger portfolios. Together, these companies represent the competitive core that defines pricing norms, channel expectations, and innovation tempo across the category.
Beyond these headline players, the report maps adjacent competitors, private-label dynamics emerging through veterinary clinic partnerships, and the potential for regional challengers to gain traction where global brands face regulatory friction or distribution gaps. The FSMA Rule requiring preventive controls for pet food manufacturing, including allergen cross-contact prevention in prescription diets, adds an operational requirement that disproportionately affects smaller manufacturers lacking robust quality systems. This regulatory reality further reinforces the competitive advantages of established players while creating compliance costs that shape market entry calculations for new entrants.
Operational Intelligence Embedded in the Report
Our research is designed to translate market complexity into actionable decision support. The report structure moves beyond high-level summaries to provide operational depth across formulation trends, packaging and format shifts, veterinary channel economics, and regulatory compliance pathways. Readers will find detailed analysis of how therapeutic claims are substantiated and communicated, how manufacturing preventive controls intersect with allergen management, and how ingredient price volatility influences margin planning and reformulation timing. The study also covers distribution architectures, examining how veterinary clinics, specialty retailers, and authorized online channels differ in their prescription diet turnover, customer education responsibilities, and brand preference formation.
Worldwide Prescription Cat Food Market
Additionally, the report evaluates the strategic implications of labeling discipline under AAFCO and FDA expectations, the cross-border complexities introduced by EU registration and additive restrictions, and the practical impact of FSMA preventive control obligations on production scheduling and quality assurance. By integrating these compliance dimensions with commercial analysis, the study helps leaders assess not only where the market is going, but what it costs to operate competitively within it.
Worldwide Prescription Diet Pet Food Market
Why This Report Matters for 2026 Decision-Making
The prescription diet pet food market rewards organizations that combine scientific credibility with commercial discipline. In 2026, the companies that outperform will be those that understand how growth is distributed across conditions, formats, and channels; how regulatory requirements shape both product architecture and market entry timing; and how competitive concentration creates both barriers and opportunities depending on a player's strategic posture. Our report provides the structural intelligence needed to make those judgments with confidence, while deliberately preserving the detailed sub-segment data, regional revenue figures, and condition-level market splits for subscribers who require the full operational picture.
For executives, category managers, and strategy teams, this research functions as a decision calibration tool. It clarifies where demand is structurally strengthening, where competitive intensity is concentrated, and where regulatory and supply chain variables are most likely to affect margin and execution. The macro trajectory, competitive profiles, and dynamic context presented here represent only the visible portion of the analysis. The complete intelligence—segment-level sizing, regional breakdowns, channel-specific behavior, and forward indicators for formulation and compliance priorities—is available through the full report, enabling leaders to move from market awareness to precise strategic action.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Diet Pet Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cooling Apparel Market to Hit $5.02B by 2032, 8.99% CAGR
By pmarketresearch, 2026-09-16
Mapping the Thermal Frontier: Strategic Imperatives in the Worldwide Cooling Apparel Market Through 2032
Executive Perspective
The global demand for cooling apparel has transitioned from a seasonal novelty to a structural market imperative. As thermal stress becomes a persistent operational and lifestyle challenge across multiple continents, garment technologies designed to regulate body temperature are reshaping product roadmaps, supply chain strategies, and consumer engagement models. PW Consulting’s latest Worldwide Cooling Apparel Market study delivers a comprehensive, forward-looking intelligence framework for executives navigating this rapidly evolving landscape. Anchored in a rigorous historical review spanning 2020 to 2025, the analysis extends through a seven-year forecast window ending in 2032, translating macroeconomic indicators, technological adoption curves, and competitive maneuvers into actionable strategic guidance.
At the macro level, the market has demonstrated sustained momentum, with overall revenue climbing from approximately 1,840.55 million USD in 2020 to an estimated 2,745.5 million USD by the 2025 base year. The trajectory reflects a compound annual growth rate of 8.99 percent, positioning the sector among the more resilient categories within performance and functional apparel. By the close of the forecast horizon in 2032, projected revenue approaches the 5,018.88 million USD threshold, signaling a market that will more than double its 2020 footprint. These figures are not merely top-line indicators; they represent a structural reallocation of consumer expenditure, industrial procurement budgets, and innovation capital toward thermal management solutions. For leadership teams evaluating portfolio expansion, capacity planning, or geographic positioning, the magnitude and persistence of this growth curve warrant dedicated analytical attention.
This introductory briefing unpacks the strategic architecture of the full study, outlines the operational content designed for corporate decision-makers, and highlights the competitive and contextual forces that will define profitable execution in 2026 and beyond. The objective is to demonstrate the report’s capacity to convert complex market signals into calibrated strategy. Readers seeking granular segmentation breakdowns, detailed revenue splits, or precise regional volume allocations will find those elements systematically unpacked within the complete intelligence package, where full dataset accessibility supports scenario modeling and investment justification.
The Anatomy of a Comprehensive Market Intelligence Study
A functional market study must bridge the gap between high-level economic trends and the tactical decisions made on production floors, in merchandising departments, and within corporate development teams. The Cooling Apparel research is structured to serve precisely that function. Rather than offering a static snapshot, the report constructs a multi-dimensional analytical framework that integrates historical performance validation, forward-facing demand modeling, technology lifecycle assessment, and competitive benchmarking. Each module is designed to answer specific strategic questions that arise during annual planning cycles, product development sprints, and market entry evaluations.
Historical Baseline and Forecast Architecture
The study’s temporal architecture begins with a verified historical track record covering the 2020 through 2025 period. This baseline serves as a calibration anchor, enabling readers to test the credibility of the forecasting methodology against actual market behavior during periods of supply chain disruption, shifts in raw material pricing, and evolving regulatory frameworks. From that foundation, the model extends across the 2026 to 2032 forecast window, applying proven demand-driver logic that accounts for climate pattern acceleration, industrial safety mandates, athletic performance expectations, and healthcare-adjacent thermal management requirements.
Rather than presenting growth as a monolithic line item, the research decomposes the trajectory into technology-driven adoption pathways and application-specific demand engines. Decision-makers can trace how evaporative mechanisms, phase-change integration, air-cooled configurations, and active liquid cooling systems each contribute to distinct customer segments and purchase cycles. The report deliberately maintains strategic ambiguity around exact percentage splits and absolute regional or application-level dollar figures in this executive preview, reserving those critical allocations for the complete dataset. This approach ensures that prospects who require precise allocation intelligence for budgeting, capacity allocation, or competitive positioning are directed to the full analytical environment where raw data tables, sensitivity parameters, and drill-down visualizations are fully accessible.
Operational Content for Cross-Functional Execution
Beyond macro indicators, the study translates market behavior into operational playbooks. The content portfolio includes supply chain vulnerability mapping, cost structure sensitivity analyses, and technology maturity assessments that directly inform sourcing, inventory planning, and product engineering decisions. Readers will find structured evaluations of how material input fluctuations, labor cost trajectories, and regulatory compliance requirements intersect with manufacturing economics. These components are especially critical for organizations that must balance performance claims with cost discipline in an environment where staple fiber pricing and wage inflation are exerting measurable pressure on unit economics.
The research also delivers pathway analyses for application-specific commercialization. Industrial and occupational safety deployments, sports and outdoor performance segments, military and defense procurement channels, and healthcare-adjacent thermal garments each follow distinct compliance, certification, and purchasing cadence requirements. By mapping these pathways without prematurely disclosing exact revenue concentrations, the report preserves strategic flexibility for the reader while establishing a clear framework for segment prioritization, resource allocation, and go-to-market sequencing.
Competitive Architecture and the Pursuit of Thermal Differentiation
The cooling apparel market is characterized by a moderately concentrated competitive landscape, where a select group of influential players commands a meaningful share of brand visibility, patent portfolios, and channel relationships. The study situates this concentration within a broader ecosystem of legacy athletic brands, specialized outdoor manufacturers, and regionally rooted innovators who have each carved distinct positioning through material science, sweat-activated mechanisms, moisture-wicking architectures, and phase-change integrations. Rather than reducing competition to a single metric, the report evaluates how companies leverage product architecture, sustainability narratives, and research-driven fabric engineering to defend and expand their thermal comfort propositions.
Strategic Positioning Within Industry Leaders
Several organizations define the competitive center of gravity through continuous fabric innovation and targeted seasonal expansions. Columbia Sportswear has reinforced its outdoor performance identity through sweat-activated cooling platforms that span shirts, pants, and headwear, while recently extending its thermal portfolio with next-generation fabric introductions showcased at major industry gatherings. Under Armour continues to advance its athletic cooling line through infrared-responsive technologies and expanded collection depth, reinforcing the connection between thermal regulation and sport performance. Nike maintains a strong presence through advanced evaporation-based constructions aimed at sports execution, while Adidas leverages moisture-management systems designed to keep active users dry and thermally balanced during training cycles.
Beyond the large-scale athletic incumbents, the landscape includes highly focused specialists and sustainability-oriented players. Mission Cooling emphasizes instant-relief fabric systems activated by water, targeting runners and active consumers with towels, hats, and shirts, and has recently extended its offerings into sustainable material formats. Coolibar integrates cooling functionality with high-UPF sun protection, addressing dual consumer concerns around thermal comfort and ultraviolet exposure. ExOfficio contributes breathable mesh-based constructions tailored for travel and outdoor use, Patagonia advances quick-drying, odor-controlled cooling base layers for hiking applications, and Icebreaker utilizes natural merino wool blends that regulate temperature through inherent fiber properties. Meanwhile, Kuchofuku illustrates a different commercial axis by adapting phase-change concepts into office-friendly cooling vests and shirts, aligning thermal comfort with workplace compliance norms.
These profiles are not merely descriptive; they form the basis for a strategic mapping exercise that helps readers identify white-space opportunities, assess potential partnership or licensing pathways, and evaluate where incremental innovation may yield the strongest margin protection. The complete study expands this competitive scan into detailed positioning matrices and recent development timelines, including product launches, trade show activations, and catalog extensions that reveal how incumbents are adjusting their thermal roadmaps in real time.
Forces Reshaping the Operating Environment in 2026
No thermal apparel strategy can be constructed in isolation from the material, regulatory, and demographic forces that shape cost structures and demand velocity. The research integrates a set of dynamic industry inputs that directly influence production feasibility, compliance pathways, and consumer adoption rates. Understanding these forces is essential for executives who must convert market growth into sustainable margin performance rather than top-line expansion alone.
Material Economics and Manufacturing Cost Pressures
Input cost volatility remains a central concern for fabric-intensive categories. Recent reporting indicates that polyester staple fiber prices have moved upward, placing additional strain on cooling fabric production economics. At the same time, garment manufacturing labor costs in key production regions have followed an upward trajectory, further tightening the cost base for apparel output. These pressures do not automatically translate into price increases or margin erosion; they require deliberate sourcing strategies, fabric engineering trade-offs, and product mix optimization. The study provides structured sensitivity perspectives that allow readers to evaluate how different material and labor scenarios affect feasible price points, margin floors, and volume commitments across multiple application channels.
Regulatory Compliance and Material Governance
Compliance requirements are increasingly shaping which cooling technologies can be commercialized, where they can be sold, and how they must be documented. Regulatory frameworks in major markets have introduced restrictions and testing expectations around certain microencapsulated cooling agents and nanoparticle-associated formulations. These developments matter because they influence product development timelines, supplier qualification processes, and regional commercialization priorities. The report incorporates compliance-aware scenario planning so that organizations can anticipate documentation burdens, assess formulation substitution pathways, and align R&D priorities with evolving chemical governance expectations rather than reacting after launch readiness is compromised.
Worldwide Cooling Apparel (Cooling Clothing) Market
Climate-Driven Demand Acceleration
On the demand side, an observable increase in the frequency of extreme heat events has strengthened the consumer and occupational case for thermal management apparel. Consumer survey data points to meaningful year-over-year demand uplift tied directly to heat exposure patterns, reinforcing cooling apparel as a functional necessity rather than a discretionary purchase in many contexts. This demand acceleration interacts with technology adoption curves, seasonal purchasing windows, and channel assortment strategies, creating both opportunity and execution risk. Organizations that can align product timing, inventory deployment, and communication narratives with these climate-driven purchase triggers are better positioned to capture revenue without overextending inventory exposure during off-peak periods.
Competitive Velocity and Innovation Cadence
Recent product and channel developments underscore the pace at which competitors are refreshing thermal offerings. New fabric launches, expanded cooling collections presented at major trade venues, and material sustainability extensions all signal that thermal apparel is treated as a core innovation track rather than a peripheral seasonal line. For decision-makers, the strategic implication is clear: product lifecycles are compressing, and differentiation increasingly depends on the integration of fabric performance, comfort claims, durability, and sustainability credentials. The study captures these developments in a structured timeline format, enabling readers to compare innovation cadence across the competitive set and identify where incremental improvements may be insufficient relative to the pace of market evolution.
Worldwide Cooling Mattress Topper Market
Translating Intelligence Into 2026 Decision Architecture
The strategic value of a market study lies not in what it describes, but in how it equips leaders to act. The Cooling Apparel research is designed to support a concrete set of decision workflows that executive teams, product leaders, and commercial strategists encounter during planning cycles. These workflows span portfolio prioritization, channel and geography evaluation, supply chain resilience assessment, and competitive differentiation design.
Portfolio Prioritization and Technology Pathway Selection
Organizations must decide where to concentrate development resources across evaporative systems, phase-change materials, air-cooled configurations, and active liquid cooling approaches. Each pathway carries distinct performance characteristics, cost profiles, and customer perception implications. The report helps readers align technology selection with target applications and price architecture by mapping adoption logic and demand drivers, while reserving exact allocation figures and split details for the downloadable dataset. This balance allows leadership to assess relative strategic attractiveness before committing to specific volume assumptions or engineering roadmaps.
Sourcing, Compliance, and Cost Structure Alignment
Because material pricing and labor cost trajectories directly influence manufacturing feasibility, the study supports sourcing and cost-planning exercises that connect market outlooks with operational realities. Executives can use the integrated cost and compliance perspectives to test whether current supplier bases, formulation choices, and production footprints remain aligned with both margin targets and regulatory expectations. This is particularly important when cooling agents, fiber inputs, and garment assembly costs are simultaneously subject to upward pressure or governance change.
Go-to-Market Sequencing and Demand Timing
The interaction between climate-driven demand spikes, seasonal assortment plans, and trade-channel visibility creates a timing challenge that many organizations manage inconsistently. The research provides a structural view of how demand acceleration interacts with product launch cadence and channel execution. By understanding these dynamics, commercial teams can better sequence assortment rollouts, manage inventory exposure, and align promotional narratives with periods of heightened thermal stress. The complete study expands this into detailed planning support that connects market signals with execution calendars and assortment architecture without prematurely disclosing the precise quantitative distribution across segments.
Competitive Positioning and White-Space Evaluation
With a moderately concentrated market structure, differentiation increasingly depends on specialized performance claims, material credibility, and segment-specific use cases. The report enables readers to evaluate where existing competitive coverage is dense and where customer needs remain underserved by current product architectures. This assessment supports decisions around licensing, collaboration, niche product creation, and brand narrative design. Rather than presenting a static ranking, the study frames competition as a dynamic map of technology claims, channel presence, and innovation tempo, giving strategists a basis for positioning choices that are responsive to actual market behavior.
Accessing the Complete Strategic Dataset
This briefing has outlined the analytical foundation, operational content, competitive context, and decision architecture embedded in the Worldwide Cooling Apparel Market study. The intent has been to demonstrate the depth of the research environment and its relevance to executive planning in 2026 and the broader forecast window. Yet the full strategic value of the study resides in the granular data, sensitivity models, and drill-down intelligence that cannot be fully reproduced within an introductory overview.
For organizations that require precise segment allocations, detailed regional and application-level breakdowns, and complete technology split perspectives to support investment cases, budget approvals, and product planning, the complete dataset is available through the full report portal. There, readers gain access to the structured tables, scenario parameters, and competitive timelines necessary to convert market direction into executable strategy. In a category advancing at a sustained growth rate toward the midpoint of the next decade, the difference between directional awareness and decision-ready intelligence is substantial. PW Consulting’s cooling apparel research is built to close that gap for teams prepared to act on thermal market opportunity with precision.
For detailed analysis of this topic, please visit the official page: Worldwide Cooling Apparel (Cooling Clothing) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Global CUTI Market to Reach $4.43 Billion by 2032, Growing at 6.5% CAGR
By pmarketresearch, 2026-09-16
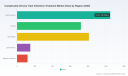
Strategic Insights: Navigating the Worldwide Complicated Urinary Tract Infections Treatment Market in 2026 and Beyond
The global healthcare landscape is undergoing a profound transformation, driven by escalating antibiotic resistance, aging demographics, and the increasing complexity of infectious disease management. Within this evolving ecosystem, Complicated Urinary Tract Infections (cUTIs) represent a critical clinical challenge, demanding sophisticated therapeutic interventions and robust market intelligence. As we step into 2026, stakeholders across the pharmaceutical value chain—from innovator biotechs to generic manufacturers, healthcare providers, and payers—must possess a granular understanding of the market forces shaping this high-stakes segment. This article outlines the strategic imperatives for 2026 decision-making and introduces our comprehensive market research report, designed to equip leaders with the actionable intelligence required to thrive in the Worldwide Complicated Urinary Tract Infections Treatment Market.
The Strategic Value of Precision Intelligence for 2026 Decision-Making
The cUTI treatment market is not merely a volume-driven arena; it is a complex interplay of clinical efficacy, resistance patterns, reimbursement dynamics, and regulatory pathways. For executives formulating strategy in 2026, relying on high-level aggregates is no longer sufficient. The margin for error has narrowed. Decisions regarding R&D pipelines, commercial launches, manufacturing capacity, pricing strategies, and market access must be grounded in data that reflects the nuanced realities of this therapeutic area. Our latest research provides the depth and breadth necessary to de-risk strategic choices. It moves beyond superficial trends to uncover the underlying drivers of growth, the shifting competitive dynamics, and the emerging opportunities that will define the next cycle of value creation.
By leveraging the insights contained in this report, organizations can align their operational capabilities with market demand more effectively. Whether assessing the viability of entering specific therapeutic niches, optimizing portfolio mix, or anticipating competitor moves, the intelligence presented here serves as a foundational asset. It enables leaders to answer critical questions: Which drug classes are gaining traction against resistant pathogens? How are distribution channels evolving to meet patient needs? What regulatory and reimbursement shifts could alter market accessibility? The answers to these questions are pivotal for securing a competitive advantage in 2026 and beyond.
Macro Market Trajectory: Growth Dynamics and Structural Trends
The Worldwide Complicated Urinary Tract Infections Treatment Market is demonstrating sustained growth, underpinned by a rising prevalence of bacterial infections, increased hospitalization rates, and a critical need for effective therapies against multidrug-resistant organisms. Our analysis captures a clear trajectory of expansion over the forecast horizon. Starting from a robust base in the historical period, the market has shown consistent revenue generation, culminating in a projected value of 2,850.5 Million USD in 2025. As we look ahead to 2026, the market is poised to reach approximately 3,035.78 Million USD, reflecting a continued upward momentum.
This growth is not linear; it is fueled by specific structural factors. The increasing incidence of cUTIs associated with healthcare settings, the growing burden of urological procedures, and the recognition of cUTIs as a significant cause of morbidity are all contributing to expanded treatment volumes. Furthermore, the shift toward managing infections in outpatient and community settings, supported by advancements in oral antibiotic formulations and improved diagnostic capabilities, is reshaping the treatment paradigm. These dynamics are expected to sustain a Compound Annual Growth Rate of 6.5 Percent over the forecast period from 2026 to 2032, driving the market toward a projected valuation of 4,429.64 Million USD by the end of the forecast window.
It is important to note that this growth is distributed across diverse therapeutic and geographic landscapes. While the aggregate figures highlight the scale of opportunity, the true strategic insight lies in understanding the relative performance and positioning of different regions and therapeutic categories. The market exhibits distinct regional characteristics, with North America maintaining a dominant position in terms of revenue contribution, followed by significant contributions from Europe and Asia Pacific. These regional variations reflect differences in healthcare infrastructure, prescription practices, reimbursement policies, and the local prevalence of resistant pathogens. Our report provides a detailed breakdown of these regional dynamics, offering stakeholders the ability to tailor their strategies to specific market environments without relying on generalized assumptions.
Therapeutic Evolution: Drug Class Segmentation and Innovation Pipeline
The cUTI treatment arsenal is diverse, encompassing established antibiotic classes and emerging novel therapies designed to combat resistance. The market segmentation by drug class reveals a competitive landscape where legacy agents continue to hold substantial share, while new entrant therapies and combination approaches are gaining momentum. Carbapenems remain a cornerstone of therapy for severe cUTIs, reflecting their broad-spectrum activity and reliability in treating complicated cases. Cephalosporins also command a significant portion of the market, supported by their widespread use and established clinical profiles. Fluoroquinolones, while facing increasing scrutiny due to resistance concerns and safety profiles, continue to be utilized in specific patient populations where appropriate.
Beyond these traditional classes, the market is witnessing the rise of novel combination therapies and specialized agents targeting resistant strains. The segment for novel combination therapies is expanding as clinicians seek more effective options for infections caused by multidrug-resistant Gram-negative bacteria. This shift is driven by the limitations of monotherapy in the face of evolving resistance mechanisms. Additionally, the "Others" category captures a range of emerging drugs and off-label uses that contribute to the overall market complexity. The interplay between these drug classes is dynamic, influenced by factors such as clinical guidelines, formulary placements, and the availability of new evidence supporting efficacy and safety.
Innovation remains a key catalyst for market evolution. Several companies are actively advancing their pipelines, introducing agents with differentiated mechanisms of action or improved pharmacokinetic profiles. For instance, the development of oral options for cUTI treatment represents a significant unmet need, offering the potential to reduce hospital stays and improve patient convenience. The progress of oral tebipenem HBr, which has shown positive topline results from Phase 3 trials and holds FDA Qualified Infectious Disease Product designation, underscores the industry's focus on delivering patient-centric solutions. Similarly, recent FDA approvals such as Xacduro for Acinetobacter infections, including cUTI, highlight the ongoing efforts to address specific resistant pathogens. These developments illustrate the importance of monitoring the pipeline closely, as today's clinical candidates may become tomorrow's market leaders.
Competitive Landscape: Key Players and Strategic Postures
The cUTI treatment market is characterized by a mix of established pharmaceutical giants and specialized biotech firms, each employing distinct strategies to capture value. Market concentration metrics indicate a moderately fragmented landscape, with the top five players holding a combined revenue share of approximately 48.2 Percent, and the top three accounting for 35.4 Percent. This structure suggests that while large incumbents wield significant influence, there is room for agile competitors to carve out niches through innovation, differentiation, and targeted commercialization.
Worldwide Complicated Urinary Tract Infections Treatment Market
Major multinational corporations continue to leverage their broad commercial infrastructure and robust R&D capabilities to maintain strong positions. Merck & Co., Inc. markets Zerbaxa (ceftolozane/tazobactam), an FDA-approved antibiotic for cUTI and complicated intra-abdominal infections, benefiting from its inclusion in CMS Medicare Part D formularies. GlaxoSmithKline plc offers Zavicefta (ceftazidime-avibactam), approved for cUTI and pyelonephritis in adults with limited treatment options, supported by regulatory authorizations in both the US and Europe. Pfizer Inc. provides Avycaz (ceftazidime-avibactam), indicated for cUTI including pyelonephritis, leveraging its global reach to expand access to this beta-lactam/beta-lactamase inhibitor combination. Allison (AbbVie Inc.) supplies Dalvance (dalbavancin), which has off-label utility in cUTI, alongside Imipenem/cilastatin/relebactam for cUTI, demonstrating a multi-faceted approach to infectious disease therapy. Basilea Pharmaceutica Ltd. has developed Cresemba primarily as an antifungal but partners on antibacterial agents for resistant cUTI, highlighting the collaborative nature of innovation in this space.
In parallel, specialized companies are making significant strides with targeted therapies. VenatoRx Pharmaceuticals received FDA approval for Xacduro (sulbactam-durlobactam) in 2023, with full approval granted in December 2023 for hospital-acquired and ventilator-associated bacterial pneumonia and cUTI caused by susceptible Acinetobacter baumannii. This approval addresses a critical gap in the treatment of multidrug-resistant Gram-negative infections. Spero Therapeutics is advancing tebipenem HBr oral pivoxil, which has achieved FDA QIDP designation and recently announced positive topline results from the Phase 3 ADAPT-PO trial for cUTI and acute pyelonephritis. These developments exemplify how focused innovation can disrupt the status quo and create new competitive pressures.
The competitive landscape is further shaped by regulatory and intellectual property dynamics. Key patents for ceftazidime-avibactam, marketed as Avycaz and Zavicefta, expire in 2033 in major markets, which could eventually open the door to generic entry and shift pricing pressures. Meanwhile, the FDA's QIDP designation for tebipenem HBr provides priority review and five-year regulatory exclusivity, incentivizing development and potentially accelerating patient access. These factors must be integrated into any competitive analysis, as they influence the timing and nature of market entry, exclusivity periods, and the long-term sustainability of revenue streams.
Distribution Channels and Market Access Dynamics
The route to market for cUTI treatments is multifaceted, reflecting the diverse settings in which these infections are managed. Hospital pharmacies continue to represent the largest distribution channel, capturing the majority of revenue. This dominance is driven by the clinical severity of many cUTI cases, the need for intravenous administration in acute care settings, and the role of hospitals in managing patients with comorbidities or resistant infections. Hospital formularies and antimicrobial stewardship programs play a crucial role in determining the adoption of specific therapies, making relationships with healthcare institutions a priority for commercial strategies.
Retail pharmacies constitute the second-largest channel, underscoring the importance of outpatient management. As the healthcare system increasingly emphasizes cost containment and patient convenience, the shift toward oral therapies and community-based care is gaining traction. Retail distribution enables broader access for patients completing treatment courses outside the hospital, and formulary positioning within retail networks can significantly impact prescription volume. Online pharmacies represent a growing segment, driven by the expansion of telemedicine, digital health platforms, and direct-to-patient delivery models. While currently a smaller portion of the market, the online channel is poised for acceleration as digital health adoption increases and regulatory frameworks evolve to support remote prescribing and dispensing.
Worldwide Urethritis Drugs Market
Reimbursement and market access remain critical considerations across all channels. The inclusion of key therapies in formularies, such as Zerbaxa in CMS Medicare Part D with tier 3 copay status, influences patient affordability and provider prescribing behavior. Payer policies, including prior authorization requirements and step therapy protocols, can create barriers to access or favor certain drug classes over others. Understanding the nuances of reimbursement landscapes is essential for forecasting uptake and designing effective market access strategies.
Operational Challenges and Supply Chain Considerations
Beyond demand and competition, market participants must navigate operational complexities that can impact product availability and cost structures. Recent reports indicate a global shortage of piperacillin-tazobactam API, which has impacted supply for cUTI treatments amid increased demand post-pandemic. Such supply chain disruptions highlight the vulnerability of the pharmaceutical ecosystem and the need for resilient sourcing strategies. Manufacturers and distributors must assess their exposure to raw material constraints, evaluate alternative supply routes, and consider inventory management practices that mitigate risk. These operational factors are not peripheral; they are integral to maintaining market share and ensuring consistent patient care. Furthermore, fluctuations in API availability can influence pricing dynamics and create opportunities for competitors with stable supply chains to capture displaced volume.
Report Overview: Actionable Intelligence for Strategic Execution
Our Worldwide Complicated Urinary Tract Infections Treatment Market research report is designed to provide a comprehensive, data-rich foundation for strategic planning. It goes beyond high-level trends to deliver granular analysis across multiple dimensions critical to business success. The report includes detailed segmentation by region, drug class, and distribution channel, offering insights into the relative performance and growth trajectories of each segment. Stakeholders can examine the market share dynamics, revenue contributions, and forecasted demand for specific categories, enabling precise portfolio alignment and resource allocation.
The competitive analysis section provides deep profiles of key companies, including their product portfolios, pipeline assets, recent developments, and strategic positioning. By evaluating the actions of major players and emerging entrants, organizations can anticipate competitive moves, identify potential partnership opportunities, and benchmark their own performance against industry leaders. The report also incorporates regulatory and reimbursement developments, patent expirations, and clinical trial updates, ensuring that decision-makers have a holistic view of the factors influencing market accessibility and innovation.
Additionally, the report addresses market dynamics such as the impact of antibiotic resistance trends, healthcare utilization patterns, and the role of antimicrobial stewardship. These qualitative and quantitative insights are synthesized to provide actionable recommendations for market entry, product positioning, pricing strategies, and commercialization planning. Whether the goal is to expand market share, launch a new therapy, optimize supply chain resilience, or assess M&A targets, the report delivers the intelligence necessary to execute with confidence.
Conclusion: Positioning for Success in the cUTI Treatment Market
The Worldwide Complicated Urinary Tract Infections Treatment Market presents a compelling landscape of growth and innovation, but realizing value in this environment requires more than informed speculation. It demands rigorous analysis, forward-looking insights, and a clear understanding of the forces shaping demand, supply, and competition. As we move through 2026, the organizations that succeed will be those that leverage data-driven intelligence to make strategic decisions with precision and agility. Our market research report offers the depth, breadth, and actionable focus needed to navigate this complex terrain. We invite industry leaders to explore the full findings and unlock the strategic advantages embedded within this critical therapeutic market.
For detailed analysis of this topic, please visit the official page: Worldwide Complicated Urinary Tract Infections Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Teslameter Market to Hit $303.25M by 2032, 6.5% CAGR
By pmarketresearch, 2026-09-16
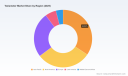
Global Magnetic Precision: Strategic Intelligence for the Worldwide Teslameter Market (2026–2032)
The Worldwide Teslameter Market stands at a critical inflection point. As industrial automation, electric vehicle development, medical imaging, and advanced materials research accelerate, the demand for high-precision magnetic field measurement instruments is no longer a niche technical requirement—it is a foundational enabler of product certification, quality assurance, and accelerated R&D cycles. Our latest Worldwide Teslameter Market report maps this evolution with granular rigor, translating macroeconomic momentum into actionable decision frameworks for engineering leaders, procurement directors, and strategic planners navigating 2026 and beyond.
The baseline trajectory is unmistakable. From 142.15 million USD in 2020, the market expanded through successive waves of electromagnetics-driven innovation, reaching 195.14 million USD in 2025. The forward window tells an equally clear story: revenue is projected to climb from 213.02 million USD in 2026 toward 303.25 million USD by 2032, sustaining a compound annual growth rate of 6.5 percent across the forecast horizon. These are not abstract indicators. They reflect a structural shift in how manufacturers validate magnetic performance, how research institutions calibrate particle environments, and how healthcare suppliers guarantee imaging fidelity. For organizations operating in this ecosystem, the strategic question is no longer whether the market is expanding, but where capital, supplier partnerships, and product development priorities must be deployed to capture disproportionate value.
Yet headline figures only scratch the surface. Market growth is fragmented across instrument form factors, application verticals, and regional manufacturing ecosystems, each carrying distinct pricing dynamics, adoption curves, and compliance pressures. The following sections outline how our research architecture converts this complexity into executable intelligence.
Structural Mapping: Regional Anchors, Instrument Categories, and Application Drivers
Precision magnetic measurement exhibits pronounced geographic concentration. The Asia Pacific corridor continues to anchor the largest revenue share, driven by dense electronics manufacturing, automotive electrification programs, and rapidly scaling semiconductor fabrication facilities. North America follows as a second major hub, supported by aerospace and defense procurement cycles, university research networks, and a mature ecosystem of specialized instrumentation vendors. European demand reflects a different profile: strong emphasis on medical technology, industrial automation, and stringent calibration standards that favor high-accuracy, traceable measurement platforms. Latin America and the Middle East and Africa represent emerging but strategically relevant demand pockets, often shaped by localized industrial modernization programs and cross-border technology transfers.
This geographic dispersion is mirrored in how the market segments by instrument architecture. Handheld teslameters dominate field-deployable measurement workflows, favored for rapid spot-checks, maintenance diagnostics, and on-site quality verification. Benchtop teslameters serve controlled laboratory and production-line environments where repeatability, resolution, and calibration traceability take precedence. Integrated and USB modules address the growing need for embedded magnetic sensing within broader test systems, enabling real-time data acquisition and seamless integration with automation software stacks.
Application-side demand reinforces this segmentation logic. Automotive and electric vehicle development programs require rigorous magnet characterization across motor design, battery management testing, and NVH analysis. Industrial and manufacturing operations depend on magnetic field validation for motor assembly, sensor calibration, and process control. Medical and healthcare applications push precision requirements higher, particularly around imaging system calibration and diagnostic equipment validation. Aerospace and scientific research impose the most exacting tolerance thresholds, driving adoption of absolute measurement platforms for particle accelerator environments, materials characterization, and advanced physics experimentation. Each vertical carries its own procurement cadence, specification depth, and certification requirements. Our report dissects how these demand streams interact, overlap, and diverge across the 2026–2032 forecast window.
Competitive Architecture: Precision Leaders, Distribution Shifts, and Portfolio Differentiation
The competitive landscape is defined by a mix of specialized precision instrument manufacturers and broader test-and-measurement suppliers, with concentration reflecting the technical barriers to high-accuracy magnetic field instrumentation. The market remains moderately consolidated, with the top three competitors accounting for roughly 38.5 percent of revenue and the top five capturing approximately 52.3 percent. This concentration signals that credibility, calibration pedigree, and application-specific validation are powerful moats. At the same time, the remaining addressable space is large enough to sustain a diverse set of regional players, niche specialists, and platform-oriented vendors.
Several firms anchor the high-precision tier. Lake Shore Cryotronics is recognized for DC and AC magnetic field measurement systems built around Hall probe architectures, serving industrial and scientific research contexts where measurement stability is non-negotiable. Metrolab Technology SA occupies a distinct position with precision NMR-based teslameters designed for absolute measurement at high resolution, a capability set that aligns closely with particle accelerator environments and MRI-related metrology. Caylar complements this precision orientation with NMR teslameter platforms aimed at MRI mapping and specialized semiconductor and accelerator applications. Group3 Technology Ltd and its North American entity, G3 Magnetics LLC, emphasize high-accuracy digital teslameters and gaussmeters, including multi-axis models that extend versatility across measurement geometries. Maurer Magnetic AG focuses on reliable residual magnetism detection through its M-Test LL platform, addressing inspection workflows where reproducibility matters as much as absolute accuracy. Senis AG and Hirst Magnetic Instruments Ltd broaden the handheld segment with portable 3-axis measurement solutions designed for field inspection and rapid magnetic field assessment. Meanwhile, Kanetec, PCE Instruments, Permag Products, Dexing Magnet Tech, and Tunkia extend the competitive field across Asia and global distribution networks, supplying digital gaussmeters and teslameters for industrial and general-purpose measurement tasks.
The competitive narrative is not static. Strategic moves in late 2024 demonstrate how companies are reshaping channel access and product visibility. Group3 Technology appointed Caylar SAS as its official distributor for digital teslameters and related magnetic measurement instruments across Europe, a channel expansion that strengthens regional reach for high-accuracy platforms. Around the same period, Hirst Magnetic Instruments announced a new 3-axis handheld gaussmeter at The Magnetics Show Europe, signaling continued investment in portable measurement form factors and direct engagement with the application community. These developments matter because distribution partnerships and product launches alter procurement options, shorten evaluation cycles, and reshape regional service coverage.
Worldwide Teslameter Market
Operational Coverage: What the Report Delivers Beyond Market Sizing
A credible market study must go beyond sizing to give decision-makers a usable operating picture. This report is structured to support that objective across multiple layers of strategic inquiry.
The instrument-level analysis breaks down handheld, benchtop, and integrated/USB segment dynamics, examining how form factor influences pricing, calibration cadence, integration complexity, and end-user procurement behavior. Rather than treating these categories as static buckets, the research evaluates where each architecture is gaining traction, which technical features are becoming table stakes, and how product roadmaps are adapting to application-specific measurement demands.
The application-side evaluation examines demand intensity across automotive and electric vehicles, industrial and manufacturing, medical and healthcare, and aerospace and scientific research. This section connects measurement requirements to product development cycles, quality certification processes, and R&D investment patterns, helping buyers and vendors anticipate specification shifts rather than react to them.
Multimeters Market
Regional analysis maps demand concentration, supply chain exposure, and localized procurement behavior. Special attention is given to how export control environments, material availability, and cross-border sourcing strategies influence instrument availability and total cost of ownership. Given the concentration of magnet-related materials and precision electronic components in certain manufacturing corridors, the report incorporates how regulatory changes are reshaping channel risk, lead-time expectations, and sourcing diversification efforts.
Competitor and channel intelligence covers company profiles, product positioning, and recent strategic events that influence market access. By aligning vendor capabilities with application requirements and regional coverage, the report helps organizations benchmark alternatives, evaluate substitution risk, and identify partnership opportunities that extend beyond conventional supplier comparisons.
Decision Value for 2026: Translating Trajectory into Strategy
For enterprises operating in or adjacent to magnetic measurement, the 2026–2032 window creates a clear strategic mandate: precision, portability, and supply resilience must be treated as interconnected priorities. The 6.5 percent CAGR and the projected expansion toward 303.25 million USD by 2032 indicate sustained demand, but sustained demand does not automatically translate into uniform opportunity. Value capture depends on understanding which application verticals are expanding fastest, which instrument categories are becoming the default choice for specific workflows, and how regional sourcing constraints alter procurement strategy.
Procurement leaders can use the research to evaluate whether to consolidate suppliers around instruments with stronger calibration support and regional service coverage, or to diversify across form factors to reduce operational downtime during inspection surges. Product and engineering teams can align development roadmaps with the measurement precision thresholds that high-growth applications are beginning to require, rather than designing to legacy specifications that may lose relevance as EV architectures, imaging platforms, and accelerator-adjacent research mature. Market-entry and expansion teams can assess where regional demand concentration intersects with distribution capacity, identifying areas where channel partnerships, local assembly, or service localization may create competitive leverage.
Risk-aware planning also demands attention to material and regulatory dynamics. Export controls affecting rare earth elements and permanent magnets have introduced new complexity into the supply of magnetic components and related electronics. These developments do not merely affect raw material pricing; they influence instrument availability, lead times, and the strategic calculus of sourcing from particular regions. Organizations that map these exposures early are better positioned to structure inventory strategies, qualify alternative components, and align product specifications with realistic supply conditions.
Why This Research Matters Now
The Worldwide Teslameter Market is evolving under overlapping pressures: technological precision requirements are rising, application demand is broadening, and supply-side dynamics are becoming more sensitive to regulatory and material constraints. In that environment, strategic decisions require more than aggregate market figures. They require a structured view of segmentation, competitive positioning, regional exposure, and the operational implications of recent industry moves.
Our report is designed to provide that view without oversimplifying it. It preserves analytical depth while keeping the focus on decisions that can be acted upon in 2026: where demand is concentrated, how instrument architectures are being selected, which vendors are shaping access and differentiation, and how regulatory and supply-chain developments alter planning assumptions. The full market intelligence, including detailed segmentation trajectories, competitor comparative analysis, and forecast breakdowns, is available through the complete report. For organizations seeking to align product strategy, procurement planning, and market positioning with the next phase of market expansion, the source intelligence offers the granularity needed to move from directional awareness to precise execution.
Access the Complete Worldwide Teslameter Market Report
For detailed analysis of this topic, please visit the official page: Worldwide Teslameter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Food Encapsulating Tech Market Hits $11.54B in 2025, Projected 8.12% CAGR to 2032
By pmarketresearch, 2026-09-16
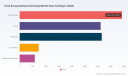
Global Food Encapsulating Technology Market: Strategic Intelligence for 2026 and Beyond
As the global food and beverage industry navigates an era of heightened consumer demand for functional nutrition, clean-label transparency, and shelf-stable delivery systems, encapsulating technologies have transitioned from niche academic applications to foundational manufacturing infrastructure. The Worldwide Food Encapsulating Technology Market is projected to reach US$19,932.09 million by 2032, reflecting a compound annual growth rate of 8.12 percent from the base year 2025 through the end of the forecast period. This trajectory is not merely a statistical projection; it represents a structural shift in how manufacturers protect sensitive bioactives, optimize flavor retention, and meet increasingly stringent regulatory labeling mandates across multiple jurisdictions.
For executive leadership, procurement strategists, and R&D directors preparing for 2026, understanding the mechanics behind this expansion is no longer optional. It is a prerequisite for capital allocation, partnership selection, and technology road mapping. This market intelligence briefing synthesizes historical performance data spanning 2020 through 2025 with forward-looking projections extending to 2032, offering a comprehensive view of market velocity, technological maturation, and competitive positioning. Yet, the full analytical architecture—segment-level revenue contributions, regional performance differentials, technology adoption curves, and phase-specific demand drivers—contains far more granular decision-support metrics than can be responsibly summarized in an introductory overview. To access the complete dataset, consult the full market research report.
Macro Market Trajectory and Structural Growth Drivers
The historical record demonstrates a clear inflection point beginning in 2022, with revenues climbing from approximately US$8,734.41 million that year to US$10,194.14 million in 2023, followed by continued expansion to US$11,540.0 million in the base year. This acceleration reflects the convergence of several macro forces. First, the functional food and beverage sector has matured beyond basic fortification, now demanding precision delivery systems that preserve the efficacy of probiotics, enzymes, and heat-sensitive vitamins through thermal processing, pasteurization, and extended shelf life. Second, consumer preference for sensory consistency in flavored and reduced-sugar formulations has elevated the strategic value of encapsulation as a masking and release-control mechanism. Third, regulatory frameworks governing nutritional labeling, additive transparency, and food safety compliance have incentivized manufacturers to adopt encapsulation as a risk-mitigation layer, particularly when stabilizing bioactives that degrade under standard storage or processing conditions.
Looking ahead to the 2026 to 2032 forecast horizon, the compound annual growth rate of 8.12 percent implies a market that will more than double its base-year valuation within seven years. This expansion will not be linear. It will be shaped by capital investment cycles in advanced manufacturing facilities, the commercial maturation of alternative wall material platforms, and the pace at which mid-tier manufacturers transition from conventional blending to controlled-release microencapsulation. The underlying data set tracks these inflection points across multiple dimensions, mapping growth vectors that allow decision-makers to anticipate capacity bottlenecks, evaluate technology adoption timing, and align procurement strategies with projected demand shifts. A detailed breakdown of these vectors—distinct from the headline CAGR—is essential for scenario planning and remains accessible within the complete research publication.
Technology Architecture and Core Phase Demand Patterns
Food encapsulation is fundamentally a materials science discipline, and the market is segmented by the primary processing technologies employed to achieve ingredient protection, controlled release, and sensory optimization. The dominant methodologies in the current landscape span spray drying, spray chilling, fluid bed coating, extrusion, and a portfolio of emerging or niche techniques. Each modality carries distinct trade-offs in terms of throughput, particle size distribution, wall material compatibility, and suitability for specific core ingredients. Spray drying remains a high-volume workhorse for flavor and colorant stabilization, particularly where rapid dehydration and cost efficiency are paramount. Fluid bed coating and extrusion offer more precise layer-by-layer deposition for functional ingredients requiring graded release profiles. Spray chilling serves specialized applications where thermal sensitivity rules out high-temperature drying.
Food Flavor Enhancer Market
Parallel to technology segmentation, the market is structured around the core phases being encapsulated. Flavors and colorants represent a substantial share of demand, driven by the need to maintain sensory integrity in complex matrices and alongside clean-label reformulation initiatives. Vitamins and minerals form another critical pillar, particularly as fortification requirements intersect with bioavailability optimization and stability under varied processing conditions. Enzymes, probiotics, sweeteners, and a range of other core phases complete the demand spectrum, each with unique encapsulation challenges related to activity preservation, carrier compatibility, and release timing. The interaction between technology type and core phase is not a simple one-to-one mapping; it is a multidimensional matrix that determines manufacturing feasibility, cost structure, and end-use performance. The full report dissects these intersections with segmentation-level revenue data, enabling stakeholders to identify which technology-phase combinations are gaining share, which are plateauing, and where innovation pipelines are likely to redirect investment flows in 2026 and beyond.
Competitive Dynamics and Strategic Positioning of Leading Players
The market structure exhibits moderate concentration, with the top three firms accounting for approximately 31.4 percent of overall revenue and the top five firms collectively representing roughly 46.8 percent. This concentration level signals a landscape where large-scale ingredient manufacturers and specialized technology providers coexist, each pursuing differentiation through proprietary wall materials, application-specific delivery systems, and targeted capacity expansions. The competitive environment is not defined by price competition alone; it is increasingly driven by formulation science, regulatory compliance enablement, and the ability to offer integrated ingredient-plus-encapsulation solutions that reduce downstream processing complexity for food manufacturers.
Several organizations have established particularly strong positions through deliberate portfolio strategies. Balchem Corporation, headquartered in New Hampton, New York, has built its brand around advanced microencapsulation platforms including BakeShure, ConfecShure, and MeatShure, each engineered for controlled release and ingredient protection in bakery, confectionery, meat, and broader food applications. In December 2025, the company announced the development of a new high-capacity microencapsulation manufacturing facility in Orange County, New York, with an expected opening in 2027, signaling a clear commitment to scaling capacity for these specialized technologies. Cargill, based in Minneapolis, leverages carbohydrate science and large-scale production infrastructure to provide encapsulation solutions for flavors, nutrients, and functional ingredients across food and beverage categories. Kerry Group, operating from Tralee, Ireland, combines flavor and nutrient encapsulation capabilities with extensive R&D resources focused on clean-label ingredient systems, positioning the firm at the intersection of sensory performance and labeling transparency.
Ingredion, headquartered in Westchester, Illinois, specializes in polysaccharide-based wall materials—primarily starch and modified starch—delivering customized encapsulation solutions tailored to dairy, beverage, and snack applications. BASF SE, from Ludwigshafen, Germany, supplies advanced encapsulation platforms that emphasize stability, bioavailability, and controlled release for vitamins, carotenoids, and other sensitive food ingredients, aligning closely with formulation requirements in functional and fortified products. DSM-Firmenich, operating from Heerlen, Netherlands, and Kaiseraugst, Switzerland, offers flavor delivery systems, premixes, probiotics, vitamins, and encapsulation technologies designed to optimize taste, texture, and nutrition in functional foods. Givaudan, based in Vernier, Switzerland, is widely recognized for flavor encapsulation and functional ingredient delivery systems, while International Flavors & Fragrances Inc., headquartered in New York, focuses on flavor and fragrance encapsulation for food and beverage products. Symrise AG, from Holzminden, Germany, develops encapsulated flavors and functional ingredients tailored to food industry requirements, and FrieslandCampina Kievit, operating from Amersfoort, Netherlands, provides spray-dried encapsulation solutions for flavors and creamers.
Worldwide Food Encapsulating Technology Market
The competitive field also includes specialized and emerging players whose technology focus addresses specific formulation gaps. Sensient Technologies Corporation, based in Milwaukee, Wisconsin, delivers color and flavor encapsulation technologies for food and beverage markets. TasteTech Ltd., from Bristol, United Kingdom, concentrates on microencapsulation for flavors and functional ingredients, while Xampla, headquartered in Cambridge, United Kingdom, has advanced plant protein-based microcapsules—utilizing materials such as pea protein—for nutrient encapsulation with enteric release properties. In May 2025, Xampla published peer-reviewed research demonstrating that its plant protein microcapsules effectively protect fat-soluble nutrients like Vitamin D2 through processing, storage, and simulated gastric digestion, releasing active ingredients in the intestine. This validation underscores a broader industry trajectory toward bio-based wall materials and targeted release mechanisms that align with clean-label expectations and regulatory preferences.
Understanding how these players position themselves across regions, technologies, and core phases is critical for partnership evaluation, supply chain diversification, and competitive benchmarking. The complete market research provides firm-level revenue estimates, addressable segment exposure, and technology portfolio mapping that enable granular competitive analysis. These insights are deliberately reserved for the full report to preserve analytical integrity and guide readers toward the complete intelligence package.
Wall Material Innovation, Regulatory Alignment, and Food Safety Implications
The effectiveness of any encapsulation system is fundamentally determined by the choice of wall material. Common materials in food encapsulation include polysaccharides such as starch, maltodextrin, and gum Arabic, alongside proteins like whey protein, soy protein, and pea protein. Each material class presents distinct functional attributes: polysaccharides often excel in film formation, moisture barrier properties, and compatibility with spray drying, while protein-based matrices can offer improved emulsification, nutrient binding, and, in certain formulations, targeted release behavior under specific pH or enzymatic conditions. The selection of wall material is rarely a single-variable decision; it is integrated with core ingredient characteristics, processing environment, desired release kinetics, and labeling considerations.
Regulatory alignment has become an increasingly important driver for encapsulation adoption. Food encapsulation technologies support compliance with nutritional labeling mandates by improving the stability and controlled release of vitamins, minerals, and bioactives in fortified foods, reducing degradation-related discrepancies between labeled and actual nutrient content. In parallel, encapsulation of bacteriocin-producing lactic acid bacteria and natural antimicrobials such as nisin is being researched to enhance food safety in higher-risk products, supporting compliance with FDA and USDA guidelines through more reliable antimicrobial delivery and activity retention. These regulatory and safety dimensions are not peripheral considerations; they are becoming embedded in product development timelines, quality assurance protocols, and go-to-market strategies.
The full research publication examines how these material science and regulatory forces shape segment-level demand, influence technology selection, and affect the competitive positioning of wall material specialists versus integrated ingredient suppliers. Detailed analysis of material adoption trends, formulation compatibility matrices, and compliance-related procurement drivers is available in the complete report.
Integration of Market Context Into 2026 Decision Frameworks
For organizations preparing for 2026, the encapsulation market presents both opportunity and execution complexity. Growth is robust, but it is unevenly distributed across technologies, core phases, and geographies. Capital deployment, supplier qualification, and R&D prioritization require a clear understanding of where demand is converging, where capacity is tightening, and which technological pathways are gaining validation through peer-reviewed research and commercial scaling. The historical data set covering 2020 through 2025 establishes a credible baseline, while the 2026 to 2032 forecast provides a structured lens for scenario modeling. Strategic decisions around facility investment, partnership selection, portfolio expansion, and formulation roadmap alignment should be grounded in the full segmentation architecture rather than headline figures alone.
The complete report delivers the operational detail necessary to convert market awareness into executable strategy. It includes technology-by-segment revenue distributions, regional performance differentials, core phase adoption patterns, concentration analysis across the competitive set, and detailed company profiles that map recent developments, capacity moves, and technology validation milestones. The two most recent developments highlighted in the intelligence set illustrate the kind of forward-looking signal embedded in the full publication: Balchem Corporation’s announced high-capacity microencapsulation facility in Orange County, New York, expected to open in 2027, and Xampla’s May 2025 peer-reviewed validation of plant protein microcapsules for fat-soluble nutrient protection and enteric release. These events are not isolated; they reflect capacity expansion logic and material science validation trends that influence regional supply dynamics, formulation feasibility, and competitive intensity. The full report contextualizes these developments within broader market trajectories and quantifies their likely impact on segment-level momentum.
Conclusion: Accessing Complete Strategic Intelligence
The Worldwide Food Encapsulating Technology Market is entering a phase where differentiation will be determined by formulation precision, wall material innovation, regulatory enablement, and the ability to scale specialized microencapsulation capabilities without compromising cost efficiency or performance reliability. An 8.12 percent compound annual growth rate through 2032, a base-year valuation of US$11,540.0 million, and a projected endpoint above US$19.9 billion all point to a maturing but still rapidly evolving market. Yet the headline metrics only frame the opportunity. The real strategic value lies in the segmentation detail, competitive positioning maps, technology-phase interaction analysis, regional differentiation, and company-level development tracking that enable precise decision-making.
This briefing has outlined the macro drivers, structural segmentation logic, competitive landscape, and regulatory and material science context that shape the market. To move from high-level awareness to actionable intelligence—complete with segment-level revenue splits, regional performance comparisons, technology adoption curves, and firm-specific strategic profiles—the full research report should be consulted. The complete dataset and analytical framework are designed to support capital planning, supplier evaluation, R&D prioritization, and competitive benchmarking for the 2026 decision cycle and the forecast horizon that follows.
For detailed analysis of this topic, please visit the official page: Worldwide Food Encapsulating Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com