

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Projects Global CUTI Market to Reach $4.43 Billion by 2032, Growing at 6.5% CAGR

Strategic Insights: Navigating the Worldwide Complicated Urinary Tract Infections Treatment Market in 2026 and Beyond
The global healthcare landscape is undergoing a profound transformation, driven by escalating antibiotic resistance, aging demographics, and the increasing complexity of infectious disease management. Within this evolving ecosystem, Complicated Urinary Tract Infections (cUTIs) represent a critical clinical challenge, demanding sophisticated therapeutic interventions and robust market intelligence. As we step into 2026, stakeholders across the pharmaceutical value chain—from innovator biotechs to generic manufacturers, healthcare providers, and payers—must possess a granular understanding of the market forces shaping this high-stakes segment. This article outlines the strategic imperatives for 2026 decision-making and introduces our comprehensive market research report, designed to equip leaders with the actionable intelligence required to thrive in the Worldwide Complicated Urinary Tract Infections Treatment Market.
The Strategic Value of Precision Intelligence for 2026 Decision-Making
The cUTI treatment market is not merely a volume-driven arena; it is a complex interplay of clinical efficacy, resistance patterns, reimbursement dynamics, and regulatory pathways. For executives formulating strategy in 2026, relying on high-level aggregates is no longer sufficient. The margin for error has narrowed. Decisions regarding R&D pipelines, commercial launches, manufacturing capacity, pricing strategies, and market access must be grounded in data that reflects the nuanced realities of this therapeutic area. Our latest research provides the depth and breadth necessary to de-risk strategic choices. It moves beyond superficial trends to uncover the underlying drivers of growth, the shifting competitive dynamics, and the emerging opportunities that will define the next cycle of value creation.
By leveraging the insights contained in this report, organizations can align their operational capabilities with market demand more effectively. Whether assessing the viability of entering specific therapeutic niches, optimizing portfolio mix, or anticipating competitor moves, the intelligence presented here serves as a foundational asset. It enables leaders to answer critical questions: Which drug classes are gaining traction against resistant pathogens? How are distribution channels evolving to meet patient needs? What regulatory and reimbursement shifts could alter market accessibility? The answers to these questions are pivotal for securing a competitive advantage in 2026 and beyond.
Macro Market Trajectory: Growth Dynamics and Structural Trends
The Worldwide Complicated Urinary Tract Infections Treatment Market is demonstrating sustained growth, underpinned by a rising prevalence of bacterial infections, increased hospitalization rates, and a critical need for effective therapies against multidrug-resistant organisms. Our analysis captures a clear trajectory of expansion over the forecast horizon. Starting from a robust base in the historical period, the market has shown consistent revenue generation, culminating in a projected value of 2,850.5 Million USD in 2025. As we look ahead to 2026, the market is poised to reach approximately 3,035.78 Million USD, reflecting a continued upward momentum.
This growth is not linear; it is fueled by specific structural factors. The increasing incidence of cUTIs associated with healthcare settings, the growing burden of urological procedures, and the recognition of cUTIs as a significant cause of morbidity are all contributing to expanded treatment volumes. Furthermore, the shift toward managing infections in outpatient and community settings, supported by advancements in oral antibiotic formulations and improved diagnostic capabilities, is reshaping the treatment paradigm. These dynamics are expected to sustain a Compound Annual Growth Rate of 6.5 Percent over the forecast period from 2026 to 2032, driving the market toward a projected valuation of 4,429.64 Million USD by the end of the forecast window.
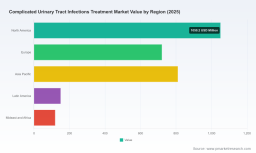
It is important to note that this growth is distributed across diverse therapeutic and geographic landscapes. While the aggregate figures highlight the scale of opportunity, the true strategic insight lies in understanding the relative performance and positioning of different regions and therapeutic categories. The market exhibits distinct regional characteristics, with North America maintaining a dominant position in terms of revenue contribution, followed by significant contributions from Europe and Asia Pacific. These regional variations reflect differences in healthcare infrastructure, prescription practices, reimbursement policies, and the local prevalence of resistant pathogens. Our report provides a detailed breakdown of these regional dynamics, offering stakeholders the ability to tailor their strategies to specific market environments without relying on generalized assumptions.
Therapeutic Evolution: Drug Class Segmentation and Innovation Pipeline
The cUTI treatment arsenal is diverse, encompassing established antibiotic classes and emerging novel therapies designed to combat resistance. The market segmentation by drug class reveals a competitive landscape where legacy agents continue to hold substantial share, while new entrant therapies and combination approaches are gaining momentum. Carbapenems remain a cornerstone of therapy for severe cUTIs, reflecting their broad-spectrum activity and reliability in treating complicated cases. Cephalosporins also command a significant portion of the market, supported by their widespread use and established clinical profiles. Fluoroquinolones, while facing increasing scrutiny due to resistance concerns and safety profiles, continue to be utilized in specific patient populations where appropriate.
Beyond these traditional classes, the market is witnessing the rise of novel combination therapies and specialized agents targeting resistant strains. The segment for novel combination therapies is expanding as clinicians seek more effective options for infections caused by multidrug-resistant Gram-negative bacteria. This shift is driven by the limitations of monotherapy in the face of evolving resistance mechanisms. Additionally, the "Others" category captures a range of emerging drugs and off-label uses that contribute to the overall market complexity. The interplay between these drug classes is dynamic, influenced by factors such as clinical guidelines, formulary placements, and the availability of new evidence supporting efficacy and safety.
Innovation remains a key catalyst for market evolution. Several companies are actively advancing their pipelines, introducing agents with differentiated mechanisms of action or improved pharmacokinetic profiles. For instance, the development of oral options for cUTI treatment represents a significant unmet need, offering the potential to reduce hospital stays and improve patient convenience. The progress of oral tebipenem HBr, which has shown positive topline results from Phase 3 trials and holds FDA Qualified Infectious Disease Product designation, underscores the industry's focus on delivering patient-centric solutions. Similarly, recent FDA approvals such as Xacduro for Acinetobacter infections, including cUTI, highlight the ongoing efforts to address specific resistant pathogens. These developments illustrate the importance of monitoring the pipeline closely, as today's clinical candidates may become tomorrow's market leaders.
Competitive Landscape: Key Players and Strategic Postures
The cUTI treatment market is characterized by a mix of established pharmaceutical giants and specialized biotech firms, each employing distinct strategies to capture value. Market concentration metrics indicate a moderately fragmented landscape, with the top five players holding a combined revenue share of approximately 48.2 Percent, and the top three accounting for 35.4 Percent. This structure suggests that while large incumbents wield significant influence, there is room for agile competitors to carve out niches through innovation, differentiation, and targeted commercialization.
Worldwide Complicated Urinary Tract Infections Treatment Market
Major multinational corporations continue to leverage their broad commercial infrastructure and robust R&D capabilities to maintain strong positions. Merck & Co., Inc. markets Zerbaxa (ceftolozane/tazobactam), an FDA-approved antibiotic for cUTI and complicated intra-abdominal infections, benefiting from its inclusion in CMS Medicare Part D formularies. GlaxoSmithKline plc offers Zavicefta (ceftazidime-avibactam), approved for cUTI and pyelonephritis in adults with limited treatment options, supported by regulatory authorizations in both the US and Europe. Pfizer Inc. provides Avycaz (ceftazidime-avibactam), indicated for cUTI including pyelonephritis, leveraging its global reach to expand access to this beta-lactam/beta-lactamase inhibitor combination. Allison (AbbVie Inc.) supplies Dalvance (dalbavancin), which has off-label utility in cUTI, alongside Imipenem/cilastatin/relebactam for cUTI, demonstrating a multi-faceted approach to infectious disease therapy. Basilea Pharmaceutica Ltd. has developed Cresemba primarily as an antifungal but partners on antibacterial agents for resistant cUTI, highlighting the collaborative nature of innovation in this space.
In parallel, specialized companies are making significant strides with targeted therapies. VenatoRx Pharmaceuticals received FDA approval for Xacduro (sulbactam-durlobactam) in 2023, with full approval granted in December 2023 for hospital-acquired and ventilator-associated bacterial pneumonia and cUTI caused by susceptible Acinetobacter baumannii. This approval addresses a critical gap in the treatment of multidrug-resistant Gram-negative infections. Spero Therapeutics is advancing tebipenem HBr oral pivoxil, which has achieved FDA QIDP designation and recently announced positive topline results from the Phase 3 ADAPT-PO trial for cUTI and acute pyelonephritis. These developments exemplify how focused innovation can disrupt the status quo and create new competitive pressures.
The competitive landscape is further shaped by regulatory and intellectual property dynamics. Key patents for ceftazidime-avibactam, marketed as Avycaz and Zavicefta, expire in 2033 in major markets, which could eventually open the door to generic entry and shift pricing pressures. Meanwhile, the FDA's QIDP designation for tebipenem HBr provides priority review and five-year regulatory exclusivity, incentivizing development and potentially accelerating patient access. These factors must be integrated into any competitive analysis, as they influence the timing and nature of market entry, exclusivity periods, and the long-term sustainability of revenue streams.
Distribution Channels and Market Access Dynamics
The route to market for cUTI treatments is multifaceted, reflecting the diverse settings in which these infections are managed. Hospital pharmacies continue to represent the largest distribution channel, capturing the majority of revenue. This dominance is driven by the clinical severity of many cUTI cases, the need for intravenous administration in acute care settings, and the role of hospitals in managing patients with comorbidities or resistant infections. Hospital formularies and antimicrobial stewardship programs play a crucial role in determining the adoption of specific therapies, making relationships with healthcare institutions a priority for commercial strategies.
Retail pharmacies constitute the second-largest channel, underscoring the importance of outpatient management. As the healthcare system increasingly emphasizes cost containment and patient convenience, the shift toward oral therapies and community-based care is gaining traction. Retail distribution enables broader access for patients completing treatment courses outside the hospital, and formulary positioning within retail networks can significantly impact prescription volume. Online pharmacies represent a growing segment, driven by the expansion of telemedicine, digital health platforms, and direct-to-patient delivery models. While currently a smaller portion of the market, the online channel is poised for acceleration as digital health adoption increases and regulatory frameworks evolve to support remote prescribing and dispensing.
Worldwide Urethritis Drugs Market
Reimbursement and market access remain critical considerations across all channels. The inclusion of key therapies in formularies, such as Zerbaxa in CMS Medicare Part D with tier 3 copay status, influences patient affordability and provider prescribing behavior. Payer policies, including prior authorization requirements and step therapy protocols, can create barriers to access or favor certain drug classes over others. Understanding the nuances of reimbursement landscapes is essential for forecasting uptake and designing effective market access strategies.
Operational Challenges and Supply Chain Considerations
Beyond demand and competition, market participants must navigate operational complexities that can impact product availability and cost structures. Recent reports indicate a global shortage of piperacillin-tazobactam API, which has impacted supply for cUTI treatments amid increased demand post-pandemic. Such supply chain disruptions highlight the vulnerability of the pharmaceutical ecosystem and the need for resilient sourcing strategies. Manufacturers and distributors must assess their exposure to raw material constraints, evaluate alternative supply routes, and consider inventory management practices that mitigate risk. These operational factors are not peripheral; they are integral to maintaining market share and ensuring consistent patient care. Furthermore, fluctuations in API availability can influence pricing dynamics and create opportunities for competitors with stable supply chains to capture displaced volume.
Report Overview: Actionable Intelligence for Strategic Execution
Our Worldwide Complicated Urinary Tract Infections Treatment Market research report is designed to provide a comprehensive, data-rich foundation for strategic planning. It goes beyond high-level trends to deliver granular analysis across multiple dimensions critical to business success. The report includes detailed segmentation by region, drug class, and distribution channel, offering insights into the relative performance and growth trajectories of each segment. Stakeholders can examine the market share dynamics, revenue contributions, and forecasted demand for specific categories, enabling precise portfolio alignment and resource allocation.
The competitive analysis section provides deep profiles of key companies, including their product portfolios, pipeline assets, recent developments, and strategic positioning. By evaluating the actions of major players and emerging entrants, organizations can anticipate competitive moves, identify potential partnership opportunities, and benchmark their own performance against industry leaders. The report also incorporates regulatory and reimbursement developments, patent expirations, and clinical trial updates, ensuring that decision-makers have a holistic view of the factors influencing market accessibility and innovation.
Additionally, the report addresses market dynamics such as the impact of antibiotic resistance trends, healthcare utilization patterns, and the role of antimicrobial stewardship. These qualitative and quantitative insights are synthesized to provide actionable recommendations for market entry, product positioning, pricing strategies, and commercialization planning. Whether the goal is to expand market share, launch a new therapy, optimize supply chain resilience, or assess M&A targets, the report delivers the intelligence necessary to execute with confidence.
Conclusion: Positioning for Success in the cUTI Treatment Market
The Worldwide Complicated Urinary Tract Infections Treatment Market presents a compelling landscape of growth and innovation, but realizing value in this environment requires more than informed speculation. It demands rigorous analysis, forward-looking insights, and a clear understanding of the forces shaping demand, supply, and competition. As we move through 2026, the organizations that succeed will be those that leverage data-driven intelligence to make strategic decisions with precision and agility. Our market research report offers the depth, breadth, and actionable focus needed to navigate this complex terrain. We invite industry leaders to explore the full findings and unlock the strategic advantages embedded within this critical therapeutic market.
For detailed analysis of this topic, please visit the official page: Worldwide Complicated Urinary Tract Infections Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com