

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global GCB Market to Hit $548 Million by 2032, 6.81% CAGR Through 2032

Navigating the Next Wave of Power Infrastructure: Strategic Insights from the Worldwide Digital Generator Circuit Breaker Market Study
The global energy transition is not merely shifting fuel sources; it is fundamentally rewiring the architecture of power generation and protection. As utilities and independent power producers navigate the dual pressures of decarbonization mandates and grid reliability, Generator Circuit Breakers (GCBs) have emerged as critical guardians of turbine integrity and plant uptime. Our newly released Worldwide Digital Generator Circuit Breaker Market report delivers a comprehensive, data-rich examination of this vital sector, equipping executive teams with the foresight required to optimize capital allocation, technology roadmaps, and competitive positioning through 2032.
A Market in Measured Expansion
The trajectory of the global GCB market reveals a steady, structurally sound growth curve that rewards early strategic alignment. Between 2020 and 2025, the sector expanded from a baseline of approximately $252.14 million to $345.5 million, navigating supply chain recalibrations and macroeconomic volatility without losing momentum. Looking ahead, our baseline forecast places 2026 revenues at roughly $360.3 million, with a projected compound annual growth rate of 6.81 percent carrying the market to $547.57 million by 2032. This expansion is not accidental; it reflects the compounding impact of aging infrastructure replacement cycles, the commissioning of next-generation generation assets, and the accelerating digitization of plant protection systems. For capital planning teams, the message is clear: demand visibility is strong, but capturing it requires differentiated value propositions that transcend commodity pricing wars.
Technology Shifts Reshaping the Asset Base
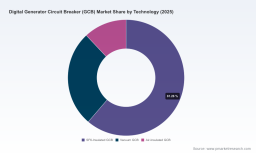
The technological composition of the GCB landscape is undergoing a quiet but decisive transformation. Traditional SF6-insulated designs continue to hold substantial installed share, yet the market is increasingly tilting toward vacuum-based and air-insulated alternatives. This migration is being driven less by pure performance economics and more by the regulatory and ESG calculus surrounding fluorinated greenhouse gas emissions. Operators are now evaluating lifecycle environmental impacts alongside traditional interrupting capacity and short-circuit withstand metrics, a shift that has accelerated the adoption of vacuum interrupter architectures in both new builds and life-cycle retrofits. The resulting technology mix is fragmenting into distinct application niches, where duty-cycle requirements, generator sizing, and grid code compliance dictate technology selection. Our study dissects these technology pathways, mapping the engineering trade-offs that procurement and engineering teams must weigh when specifying protection systems for diverse generation profiles.
End-User Diversification and Application Realities
GCB demand is not monolithic. The market supply chain interfaces with a heterogeneous end-user base spanning thermal generation, hydropower, nuclear facilities, and emerging integrated gas and renewable platforms. Each segment imposes unique operational stresses and protection philosophies. Thermal and nuclear assets, with their high continuous currents and stringent reliability mandates, demand breakers engineered to specialized duty cycles that far exceed distribution-class specifications. Hydropower installations, meanwhile, require solutions capable of withstanding long mechanical endurance cycles and harsh environmental exposures. As grid architectures incorporate more decentralized and hybrid generation, the protection logic surrounding generator isolation is evolving, pushing manufacturers to deliver smarter, more adaptive interrupting solutions that integrate seamlessly with plant-level control architectures. The report segments these application realities with granular operational context, enabling stakeholders to understand where growth will materialize and which capability gaps represent the greatest commercial opportunity.
Worldwide Digital Generator Circuit Breaker (GCB) Market
Regional Realignment and Infrastructure Investment Cycles
Geographic demand patterns are being rewritten by localized energy security priorities, grid modernization budgets, and the pace of generation fleet turnover. Asia Pacific continues to anchor a substantial share of global activity, reflecting sustained investment in baseload and peaking capacity alongside rapidly expanding transmission infrastructure. Europe’s market is characterized by a emphasis on sustainability-compliant technologies, retrofitting of aging assets, and alignment with regional decarbonization frameworks. North America’s demand profile is shaped by reliability mandates, nuclear fleet extensions, and the ongoing modernization of both fossil and hydro generation assets. Meanwhile, the Middle East and Africa and Latin America represent high-growth frontiers where capacity expansion programs are driving new procurement waves. Our geographic analysis connects these regional narratives to underlying investment cycles, policy environments, and supply-side dynamics, providing a structured lens for market entry, partnership strategy, and localized capacity planning.
The Rise of Digital GCBs: From Interrupting to Intelligence
The defining innovation in the current market cycle is the transition from purely electromechanical interrupting devices to digitally enabled protection assets. These Digital GCBs embed smart monitoring, predictive maintenance capabilities, and communication protocols that transform breakers from passive safety components into active contributors to plant availability. By aggregating health data, enabling on-premise and cloud connectivity, and feeding asset management systems with real-time condition indicators, digital platforms are helping operators move from reactive maintenance to condition-based interventions. This shift carries profound implications for total cost of ownership, spare parts logistics, and overall plant reliability metrics. Our study examines how digitalization is being embedded across the value chain, from sensor integration and health diagnostics to cybersecurity considerations and interoperability with substation automation systems. For OEMs, the digital layer is becoming a differentiator and a recurring revenue frontier; for operators, it represents a pathway to extract more operational certainty from critical protection assets.
Competitive Landscape: Architects of the Next Generation of Protection
The global GCB arena is shaped by a concentrated group of incumbent manufacturers that have built deep engineering heritage, global service networks, and increasingly sophisticated digital portfolios. Market concentration data indicates that a small cohort of players commands a dominant share of deliveries, underscoring the importance of long-term supplier relationships and technology alignment in procurement strategy.
- Hitachi Energy stands as a historically dominant force in GCB technology, with a legacy spanning decades and thousands of field installations across demanding generation environments. The company’s recent strategic emphasis centers on digital integration, sustainability, and lifecycle management, exemplified by dedicated digital GCB platforms that tie into smart monitoring ecosystems for health data aggregation and predictive maintenance. Celebrating seven decades of innovation in early 2025, the firm has reinforced its commitment to enhancing generator protection through lifecycle optimization and connected asset management, positioning digital readiness as a core pillar of its value proposition.
- GE Vernova brings a broad, application-diverse portfolio to the market, with thousands of installations covering power plants across a wide capacity spectrum. Its product philosophy integrates optimized digital cooling solutions and intelligent communication capabilities to support real-time operational adjustments and remote health monitoring. In late 2025, the company updated its service documentation to accentuate maintenance, retrofit, and digital monitoring offerings, signaling an intensifying focus on post-sale value creation and the extension of asset service life.
- Siemens has carved a strong position around vacuum-based GCB systems that emphasize SF6-free operation and extended maintenance intervals, appealing to operators pursuing sustainability targets and reduced operational expenditure. Its portfolio supports generator and transformer protection with an emphasis on reliability, lifecycle efficiency, and compatibility with renewable integration strategies, aligning its technology roadmap with the broader decarbonization agenda.
- Eaton addresses specific segments of the market with medium-voltage generator breaker solutions engineered around rigorous industry duty requirements. Its vacuum-based families are designed to deliver high continuous current carrying capability and robust performance for smaller to medium generator sets, reflecting a focused engineering approach to specialized application duties and compliance-driven design.
Beyond product portfolios, the competitive arena is being reshaped by collaboration models, service bundling, and digital platform ecosystems. Firms are increasingly competing on total lifecycle value rather than unit price alone, integrating health monitoring, retrofit services, and remote diagnostics into long-term service agreements. Our competitive analysis unpacks these positioning strategies, service architectures, and innovation trajectories, offering a structured framework for benchmarking vendor capabilities and identifying partnership opportunities that align with your operational objectives.
Regulatory and Engineering Mandates as Market Catalysts
Market evolution does not occur in a vacuum; it is guided by international standards, safety requirements, and material constraints that define what is technically permissible and commercially viable. International standards such as IEC/IEEE 62271-37-013:2021 establish the performance framework for high-voltage generator circuit-breakers, specifying design expectations for indoor and outdoor installations operating above 1 kV up to 38 kV at 50/60 Hz. These standards reinforce the specialized nature of GCB design, distinguishing generator-duty requirements from distribution-class equipment and ensuring that interrupting performance, short-circuit ratings, and continuous current capabilities are validated under rigorous conditions.
Electronic Circuit Breaker Market
At the same time, engineering specifications anchored in standards such as IEEE C37.013 compel manufacturers and specifiers to approach generator protection as a distinct discipline, with unique duty cycles and reliability expectations. The material dimension adds another layer of strategic importance: the industry’s move away from SF6 toward vacuum interrupter technologies reflects both environmental compliance imperatives and corporate carbon reduction targets, influencing specification decisions across new builds and life-cycle upgrades. The report connects these regulatory and material dynamics to real-world procurement behavior, showing how standards compliance and sustainability preferences are steering technology selection, certification requirements, and service expectations across global markets.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Making
The Worldwide Digital Generator Circuit Breaker Market study is structured to support strategic decision-making at multiple levels, from corporate planning and technology investment to procurement policy and competitive positioning. It combines historical performance analysis with forward-looking forecasts, enabling readers to calibrate expectations against realized market behavior and projected growth corridors. The report provides:
- A structured market size and growth framework covering historical performance and the 2026–2032 forecast horizon, grounded in transparent methodologies and scenario-aware assumptions.
- Technology-based and end-user-based segmentation that clarifies how different application demands and engineering preferences drive volume distribution across the asset base.
- Regional demand mapping that links procurement momentum to infrastructure investment cycles, energy policy trajectories, and fleet renewal timelines.
- A competitive and vendor landscape analysis that evaluates product philosophies, digital service offerings, and lifecycle value propositions across leading manufacturers.
- An examination of the regulatory, standards-based, and material constraints shaping specification behavior and technology adoption.
- Practical strategic implications for operators, OEMs, service providers, and investors seeking to align capabilities with high-probability growth vectors.
Every section is designed to translate data into action. Rather than presenting isolated statistics, the analysis ties market size evolution, technology trends, and competitive moves to concrete executive questions: Which application segments are expanding demand fastest, and what capability gaps do they reveal? How does the digital layer change the economics of ownership and service? Where do standards and sustainability considerations most strongly influence specification decisions? What supplier relationships and partnership models will matter most in a concentrated, high-expertise market?
Strategic Imperatives for the Year Ahead
As 2026 unfolds, three strategic imperatives stand out for organizations operating in or adjacent to the GCB market. First, technology alignment is becoming a strategic differentiator: the shift toward vacuum and air-insulated architectures, combined with embedded digital monitoring, is changing the value calculus of protection assets and rewarding suppliers and operators who can navigate lifecycle environmental performance alongside electrical reliability. Second, digital value capture is moving from pilot to practice: health data aggregation, predictive maintenance, and connected asset management are transitioning from experimental features to core components of service contracts and uptime guarantees, creating new commercial models and new risk dimensions around data integration and cybersecurity. Third, regional nuance matters more than ever: procurement outcomes will increasingly depend on localized investment timing, regulatory expectations, and the maturity of service and retrofit ecosystems, making geographic precision essential for both market entry and supplier selection.
The Worldwide Digital Generator Circuit Breaker Market report is built to help leadership teams navigate these imperatives with confidence. By combining rigorous market sizing, segmentation clarity, competitive intelligence, and forward-looking scenario context, it offers a decision-grade foundation for capacity planning, technology roadmap development, vendor evaluation, and growth strategy. The full study contains the detailed data tables, segmentation breakdowns, regional analyses, and vendor profiles that executives and analysts require to translate market dynamics into executable strategy.
To access the complete forecast models, segmentation depth, and competitive benchmarking, visit the source page for the full Worldwide Digital Generator Circuit Breaker Market research. Obtain the full intelligence set and position your organization to act decisively on the opportunities shaping the next phase of generator protection and digital power infrastructure.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Generator Circuit Breaker (GCB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com