

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Teslameter Market to Hit $303.25M by 2032, 6.5% CAGR

Global Magnetic Precision: Strategic Intelligence for the Worldwide Teslameter Market (2026–2032)
The Worldwide Teslameter Market stands at a critical inflection point. As industrial automation, electric vehicle development, medical imaging, and advanced materials research accelerate, the demand for high-precision magnetic field measurement instruments is no longer a niche technical requirement—it is a foundational enabler of product certification, quality assurance, and accelerated R&D cycles. Our latest Worldwide Teslameter Market report maps this evolution with granular rigor, translating macroeconomic momentum into actionable decision frameworks for engineering leaders, procurement directors, and strategic planners navigating 2026 and beyond.
The baseline trajectory is unmistakable. From 142.15 million USD in 2020, the market expanded through successive waves of electromagnetics-driven innovation, reaching 195.14 million USD in 2025. The forward window tells an equally clear story: revenue is projected to climb from 213.02 million USD in 2026 toward 303.25 million USD by 2032, sustaining a compound annual growth rate of 6.5 percent across the forecast horizon. These are not abstract indicators. They reflect a structural shift in how manufacturers validate magnetic performance, how research institutions calibrate particle environments, and how healthcare suppliers guarantee imaging fidelity. For organizations operating in this ecosystem, the strategic question is no longer whether the market is expanding, but where capital, supplier partnerships, and product development priorities must be deployed to capture disproportionate value.
Yet headline figures only scratch the surface. Market growth is fragmented across instrument form factors, application verticals, and regional manufacturing ecosystems, each carrying distinct pricing dynamics, adoption curves, and compliance pressures. The following sections outline how our research architecture converts this complexity into executable intelligence.
Structural Mapping: Regional Anchors, Instrument Categories, and Application Drivers
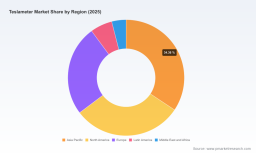
Precision magnetic measurement exhibits pronounced geographic concentration. The Asia Pacific corridor continues to anchor the largest revenue share, driven by dense electronics manufacturing, automotive electrification programs, and rapidly scaling semiconductor fabrication facilities. North America follows as a second major hub, supported by aerospace and defense procurement cycles, university research networks, and a mature ecosystem of specialized instrumentation vendors. European demand reflects a different profile: strong emphasis on medical technology, industrial automation, and stringent calibration standards that favor high-accuracy, traceable measurement platforms. Latin America and the Middle East and Africa represent emerging but strategically relevant demand pockets, often shaped by localized industrial modernization programs and cross-border technology transfers.
This geographic dispersion is mirrored in how the market segments by instrument architecture. Handheld teslameters dominate field-deployable measurement workflows, favored for rapid spot-checks, maintenance diagnostics, and on-site quality verification. Benchtop teslameters serve controlled laboratory and production-line environments where repeatability, resolution, and calibration traceability take precedence. Integrated and USB modules address the growing need for embedded magnetic sensing within broader test systems, enabling real-time data acquisition and seamless integration with automation software stacks.
Application-side demand reinforces this segmentation logic. Automotive and electric vehicle development programs require rigorous magnet characterization across motor design, battery management testing, and NVH analysis. Industrial and manufacturing operations depend on magnetic field validation for motor assembly, sensor calibration, and process control. Medical and healthcare applications push precision requirements higher, particularly around imaging system calibration and diagnostic equipment validation. Aerospace and scientific research impose the most exacting tolerance thresholds, driving adoption of absolute measurement platforms for particle accelerator environments, materials characterization, and advanced physics experimentation. Each vertical carries its own procurement cadence, specification depth, and certification requirements. Our report dissects how these demand streams interact, overlap, and diverge across the 2026–2032 forecast window.
Competitive Architecture: Precision Leaders, Distribution Shifts, and Portfolio Differentiation
The competitive landscape is defined by a mix of specialized precision instrument manufacturers and broader test-and-measurement suppliers, with concentration reflecting the technical barriers to high-accuracy magnetic field instrumentation. The market remains moderately consolidated, with the top three competitors accounting for roughly 38.5 percent of revenue and the top five capturing approximately 52.3 percent. This concentration signals that credibility, calibration pedigree, and application-specific validation are powerful moats. At the same time, the remaining addressable space is large enough to sustain a diverse set of regional players, niche specialists, and platform-oriented vendors.
Several firms anchor the high-precision tier. Lake Shore Cryotronics is recognized for DC and AC magnetic field measurement systems built around Hall probe architectures, serving industrial and scientific research contexts where measurement stability is non-negotiable. Metrolab Technology SA occupies a distinct position with precision NMR-based teslameters designed for absolute measurement at high resolution, a capability set that aligns closely with particle accelerator environments and MRI-related metrology. Caylar complements this precision orientation with NMR teslameter platforms aimed at MRI mapping and specialized semiconductor and accelerator applications. Group3 Technology Ltd and its North American entity, G3 Magnetics LLC, emphasize high-accuracy digital teslameters and gaussmeters, including multi-axis models that extend versatility across measurement geometries. Maurer Magnetic AG focuses on reliable residual magnetism detection through its M-Test LL platform, addressing inspection workflows where reproducibility matters as much as absolute accuracy. Senis AG and Hirst Magnetic Instruments Ltd broaden the handheld segment with portable 3-axis measurement solutions designed for field inspection and rapid magnetic field assessment. Meanwhile, Kanetec, PCE Instruments, Permag Products, Dexing Magnet Tech, and Tunkia extend the competitive field across Asia and global distribution networks, supplying digital gaussmeters and teslameters for industrial and general-purpose measurement tasks.
The competitive narrative is not static. Strategic moves in late 2024 demonstrate how companies are reshaping channel access and product visibility. Group3 Technology appointed Caylar SAS as its official distributor for digital teslameters and related magnetic measurement instruments across Europe, a channel expansion that strengthens regional reach for high-accuracy platforms. Around the same period, Hirst Magnetic Instruments announced a new 3-axis handheld gaussmeter at The Magnetics Show Europe, signaling continued investment in portable measurement form factors and direct engagement with the application community. These developments matter because distribution partnerships and product launches alter procurement options, shorten evaluation cycles, and reshape regional service coverage.
Worldwide Teslameter Market
Operational Coverage: What the Report Delivers Beyond Market Sizing
A credible market study must go beyond sizing to give decision-makers a usable operating picture. This report is structured to support that objective across multiple layers of strategic inquiry.
The instrument-level analysis breaks down handheld, benchtop, and integrated/USB segment dynamics, examining how form factor influences pricing, calibration cadence, integration complexity, and end-user procurement behavior. Rather than treating these categories as static buckets, the research evaluates where each architecture is gaining traction, which technical features are becoming table stakes, and how product roadmaps are adapting to application-specific measurement demands.
The application-side evaluation examines demand intensity across automotive and electric vehicles, industrial and manufacturing, medical and healthcare, and aerospace and scientific research. This section connects measurement requirements to product development cycles, quality certification processes, and R&D investment patterns, helping buyers and vendors anticipate specification shifts rather than react to them.
Multimeters Market
Regional analysis maps demand concentration, supply chain exposure, and localized procurement behavior. Special attention is given to how export control environments, material availability, and cross-border sourcing strategies influence instrument availability and total cost of ownership. Given the concentration of magnet-related materials and precision electronic components in certain manufacturing corridors, the report incorporates how regulatory changes are reshaping channel risk, lead-time expectations, and sourcing diversification efforts.
Competitor and channel intelligence covers company profiles, product positioning, and recent strategic events that influence market access. By aligning vendor capabilities with application requirements and regional coverage, the report helps organizations benchmark alternatives, evaluate substitution risk, and identify partnership opportunities that extend beyond conventional supplier comparisons.
Decision Value for 2026: Translating Trajectory into Strategy
For enterprises operating in or adjacent to magnetic measurement, the 2026–2032 window creates a clear strategic mandate: precision, portability, and supply resilience must be treated as interconnected priorities. The 6.5 percent CAGR and the projected expansion toward 303.25 million USD by 2032 indicate sustained demand, but sustained demand does not automatically translate into uniform opportunity. Value capture depends on understanding which application verticals are expanding fastest, which instrument categories are becoming the default choice for specific workflows, and how regional sourcing constraints alter procurement strategy.
Procurement leaders can use the research to evaluate whether to consolidate suppliers around instruments with stronger calibration support and regional service coverage, or to diversify across form factors to reduce operational downtime during inspection surges. Product and engineering teams can align development roadmaps with the measurement precision thresholds that high-growth applications are beginning to require, rather than designing to legacy specifications that may lose relevance as EV architectures, imaging platforms, and accelerator-adjacent research mature. Market-entry and expansion teams can assess where regional demand concentration intersects with distribution capacity, identifying areas where channel partnerships, local assembly, or service localization may create competitive leverage.
Risk-aware planning also demands attention to material and regulatory dynamics. Export controls affecting rare earth elements and permanent magnets have introduced new complexity into the supply of magnetic components and related electronics. These developments do not merely affect raw material pricing; they influence instrument availability, lead times, and the strategic calculus of sourcing from particular regions. Organizations that map these exposures early are better positioned to structure inventory strategies, qualify alternative components, and align product specifications with realistic supply conditions.
Why This Research Matters Now
The Worldwide Teslameter Market is evolving under overlapping pressures: technological precision requirements are rising, application demand is broadening, and supply-side dynamics are becoming more sensitive to regulatory and material constraints. In that environment, strategic decisions require more than aggregate market figures. They require a structured view of segmentation, competitive positioning, regional exposure, and the operational implications of recent industry moves.
Our report is designed to provide that view without oversimplifying it. It preserves analytical depth while keeping the focus on decisions that can be acted upon in 2026: where demand is concentrated, how instrument architectures are being selected, which vendors are shaping access and differentiation, and how regulatory and supply-chain developments alter planning assumptions. The full market intelligence, including detailed segmentation trajectories, competitor comparative analysis, and forecast breakdowns, is available through the complete report. For organizations seeking to align product strategy, procurement planning, and market positioning with the next phase of market expansion, the source intelligence offers the granularity needed to move from directional awareness to precise execution.
Access the Complete Worldwide Teslameter Market Report
For detailed analysis of this topic, please visit the official page: Worldwide Teslameter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com