

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global IT Infrastructure Outsourcing Market Hits $435.5B in 2025 with 6.74% CAGR to 2032

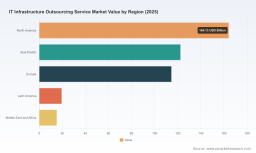
Navigating the Crossroads: Strategic Intelligence for the Global IT Infrastructure Outsourcing Market in 2026
In an era defined by rapid digital transformation, escalating cyber threats, and the convergence of artificial intelligence with core enterprise operations, IT infrastructure outsourcing has evolved from a cost-optimization tactic into a strategic imperative. As organizations worldwide recalibrate their technology stacks, the Worldwide IT Infrastructure Outsourcing Service Market has emerged as a critical battleground for competitive advantage, operational resilience, and regulatory compliance. This foundational industry analysis, grounded in rigorous historical tracking and forward-looking modeling, offers decision-makers a clear lens through which to evaluate one of the most consequential outsourcing segments of the decade.
Drawing on comprehensive data spanning 2020 through 2025 and projecting trends across a seven-year forecast horizon through 2032, the research captures not merely the trajectory of spending but the structural shifts redefining how enterprises consume, manage, and secure technology services. By synthesizing macroeconomic indicators, service-model evolution, and competitive positioning, this report equips executives with the contextual depth required to navigate procurement strategies, vendor selection, and long-term infrastructure roadmaps with confidence.
Worldwide Infrastructure as a Service Market
Historical Trajectory and the Scale of Transformation
The market has exhibited remarkable resilience and sustained growth throughout the tracking period. Starting from a baseline in 2020, the global revenue generated by IT infrastructure outsourcing services has expanded consistently, reflecting heightened enterprise dependency on outsourced operations amid cloud migration acceleration, legacy system modernization, and post-pandemic operational recalibrations. By the most recent measurement year, the market had crossed a significant threshold, signaling mature adoption patterns and the normalization of infrastructure outsourcing as a core business function rather than a peripheral support activity.
Looking ahead, the projected expansion through 2032 underscores a compounding growth dynamic. At a compounded annual growth rate of 6.74 percent, the market is positioned to traverse into materially higher revenue tiers over the forecast window. This trajectory is not merely a function of incremental spend; it reflects deepening enterprise commitments to integrated outsourcing models that bundle network operations, managed hosting, infrastructure management, and security oversight into cohesive delivery frameworks. For procurement leaders and C-suite strategists, such sustained expansion signals that the outsourcing landscape will remain highly active, competitively intense, and continuously reshaped by technological and regulatory forces.
Architectural Shifts Redefining Service Consumption
The composition of outsourced IT infrastructure has fundamentally restructured itself. What was once a spectrum dominated by standalone data center leases and routine help desk engagements has matured into a portfolio of sophisticated, interlocked service lines. Enterprises increasingly view outsourcing not as a series of discrete transactions but as an operational architecture that must deliver scalability, visibility, and risk mitigation simultaneously.
Managed hosting and data center services continue to anchor the market, reflecting enduring demand for reliable, geographically diversified compute environments. Yet the fastest-growing areas of investment are emerging where infrastructure services intersect with security postures, cloud orchestration, and AI-enabled monitoring. Network outsourcing remains essential for maintaining global connectivity and complex routing environments, while managed security services have become inseparable from infrastructure contracts as organizations confront the reality that uptime without protection carries unacceptable business risk. End-user support and help desk functions have also transformed; rather than being treated as reactive cost centers, they are being integrated into proactive service models that leverage automation, predictive diagnostics, and omnichannel engagement.
This structural rebalancing matters for strategy because it directly influences vendor evaluation criteria, contract architecture, and service-level expectations. Organizations that continue to evaluate outsourcing proposals through a narrow cost-per-ticket or per-server lens risk overlooking the value layers that now define market leadership: integrated threat detection, compliance assurance, hybrid environment orchestration, and AI-augmented operational intelligence.
Worldwide IT Infrastructure Outsourcing Service Market
Competitive Dynamics Among Enterprise-Scale Providers
The provider landscape is populated by global firms with distinct geographic footprints, delivery models, and strategic positioning. Market concentration, as measured by the combined share of leading participants, remains moderate, indicating a competitive field with room for differentiation and consolidation. This dispersion is significant for decision-makers because it implies that procurement leverage, specialized capability pairing, and partnership structuring can materially influence outcomes.
Several multinational integrators and technology consultancies anchor the upper tier of the market. Each brings a differentiated mix of managed services, cloud operations, hybrid infrastructure support, and cybersecurity integration. Providers headquartered in North America and Europe maintain strong enterprise relationships and compliance-oriented delivery frameworks, while firms based in India and other high-scalability regions contribute scale, depth in infrastructure operations, and expanding capabilities in digital transformation and automation. Japan-based organizations extend global reach through established enterprise relationships and group synergies that span infrastructure, cloud management, and end-to-end IT operations.
What distinguishes competitive positioning in this environment is rarely a single offering. Instead, differentiation emerges from how providers combine data center management, network and infrastructure management, hybrid cloud capabilities, security integration, and industry-specific solutioning. The ability to operate across multiple service domains while maintaining rigorous controls, geographic flexibility, and contractual transparency has become a decisive factor in vendor selection. Organizations evaluating partners must therefore assess portfolios holistically, prioritizing providers whose delivery models align with specific risk tolerances, compliance regimes, and operational ambitions.
Regulatory Pressure and Compliance as Operational Gatekeepers
The outsourcing environment is increasingly defined by regulatory expectations that transform compliance from an administrative afterthought into an operational gatekeeper. Cybersecurity now stands alongside infrastructure services as one of the most frequently outsourced functions, reflecting board-level recognition that external expertise is essential for maintaining resilient security postures across complex, distributed environments. This shift is amplified by mandatory standards and frameworks that span data protection, transaction integrity, and operational transparency.
Providers and their clients are navigating an expanding matrix of compliance requirements. Data privacy and security obligations tied to GDPR, HIPAA, PCI DSS, and SOX continue to shape contracting practices, service design, and audit expectations. In parallel, certification and governance regimes such as SOC 2, ISO 27001, and emerging AI governance standards are becoming baseline expectations for organizations seeking to de-risk third-party relationships. Continuous vendor risk assessment, documented control environments, and transparent audit trails are no longer optional enhancements; they are prerequisites for long-term outsourcing engagements.
Cross-border dynamics add further complexity. Recent regulatory instruments, including stringent controls on transactions involving bulk sensitive personal data, impose heightened cybersecurity obligations and record-keeping requirements on international service arrangements. As a result, enterprises must weigh not only cost and capability but also jurisdictional exposure, data residency considerations, and the regulatory readiness of prospective partners. For procurement teams, compliance literacy has become a core competency, and vendor assessments must include rigorous review of security architectures, incident response processes, and governance maturity.
Labor Economics, Geographic Strategy, and the Push Toward Intelligent Delivery
The economics of outsourcing delivery are undergoing a meaningful recalibration. Rising labor costs in traditional outsourcing hubs have begun to reshape location strategies and operating models. Providers are responding with a combination of nearshoring, automation, and intelligent service design. This evolution is not simply a cost-response measure; it reflects a broader rethinking of how infrastructure services are delivered, monitored, and optimized.
AI-enabled management and automation are increasingly embedded into delivery frameworks. Predictive maintenance, automated incident triage, policy-driven orchestration, and agentic workflow integration are transitioning from experimental initiatives to operational realities. Recent strategic moves by major providers illustrate this momentum, including acquisitions and partnerships designed to embed advanced AI capabilities into business-process and infrastructure delivery. These developments signal that competitive differentiation will increasingly depend on how effectively providers blend human expertise with automated intelligence to reduce latency, improve accuracy, and scale service delivery without proportionally escalating cost structures.
For enterprises, this dynamic creates both opportunity and caution. Automation can unlock efficiency, but it also raises questions about service quality assurance, exception handling, and the strategic role of in-house teams. Organizations must define where intelligent automation adds genuine value and where human oversight remains essential, particularly in environments with stringent uptime requirements or sensitive operational contexts.
Strategic Imperatives for Enterprise Decision-Makers in 2026
As the market expands and its architecture grows more complex, strategic decision-making must move beyond transactional procurement. Several imperatives stand out for organizations planning their infrastructure outsourcing strategies over the coming years.
- Evaluate providers against an integrated capability baseline that includes hybrid infrastructure management, security integration, compliance readiness, and cloud orchestration rather than isolated service checklists.
- Treat regulatory alignment as a primary selection criterion, ensuring that partners can demonstrate control maturity, audit transparency, and the ability to adapt to evolving cross-border data and cybersecurity requirements.
- Structure contracts to incentivize outcomes, not only cost containment. Service-level frameworks should reflect integrated monitoring, proactive threat response, and continuous improvement expectations.
- Incorporate AI-augmented delivery and automation into sourcing evaluations, assessing how providers use intelligent tools to improve reliability, reduce response times, and manage scale efficiently.
- Balance global scale with geographic flexibility. Where labor economics, data residency, and latency concerns intersect, nearshoring and multi-region delivery models may offer more resilient operating postures than single-hub dependency.
Why Comprehensive Intelligence Matters Now
The Worldwide IT Infrastructure Outsourcing Service Market is at an inflection point where growth, technology convergence, and regulatory pressure intersect. In such an environment, partial visibility can lead to suboptimal vendor selection, misaligned contract structures, and unanticipated compliance exposure. Executive teams require market intelligence that connects historical performance, forward-looking projections, service-model evolution, and competitive dynamics into a coherent strategic framework.
This research report delivers exactly that synthesis. It provides a structured foundation for evaluating market direction, understanding the forces reshaping service demand, and identifying the criteria that will separate reliable partners from commoditized providers. By integrating rigorous market sizing, segmentation architecture, competitive profiling, and industry-context dynamics, the analysis supports more disciplined planning across procurement, IT leadership, risk management, and enterprise strategy functions.
To access the complete segment breakdowns, detailed competitive profiles, methodology depth, and forward-looking scenario analysis that support these insights, readers should consult the full report. The complete dataset and proprietary intelligence are essential for organizations seeking to convert market awareness into actionable, differentiated strategy.
For detailed analysis of this topic, please visit the official page: Worldwide IT Infrastructure Outsourcing Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com