

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Diet Pet Food Hits $17.54B in 2025, Projected 7.12% CAGR to 2032

Strategic Imperatives in the Prescription Diet Pet Food Market: A 2026 Outlook
Executive Overview
The global prescription diet pet food market stands at a critical inflection point as we move through 2026. What was once a niche segment confined to clinical veterinary recommendations has evolved into a mainstream pillar of pet health management, driven by rising pet humanization, increased awareness of preventive nutrition, and a shift toward condition-specific therapeutic feeding. For industry stakeholders, understanding the trajectory of this market is no longer optional—it is a strategic necessity. Our latest comprehensive analysis, Worldwide Prescription Diet Pet Food Market, provides decision-makers with the granular intelligence required to navigate growth, competitive pressure, regulatory complexity, and supply chain volatility through 2032.
Over the historical analysis window from 2020 to 2025, the market demonstrated consistent and accelerating expansion, with total revenue climbing from approximately 12,450.6 million USD to 17,540.0 million USD. This trajectory underscores more than mere recovery from earlier disruptions; it reflects structural demand shifts that have fundamentally altered how pet owners, veterinarians, and manufacturers approach animal health nutrition. Looking forward, the forecast period spanning 2026 through 2032 projects the market reaching an estimated 28,387.13 million USD by the terminal forecast year, underpinned by a compound annual growth rate of 7.12 percent. These figures are not abstract projections—they represent the aggregate outcome of therapeutic adoption curves, channel expansion, and product innovation dynamics that our report dissects across multiple operational dimensions.
Macro Growth Trajectory and What It Means for 2026 Strategy
The market's upward momentum is not linear, and treating it as such creates strategic blind spots. The expansion observed between 2020 and 2025 reveals a segment that has built Resilience against economic headwinds while capitalizing on the growing preference for veterinary-supervised nutritional interventions. By 2026, the market has already crossed the 19,602.15 million USD threshold, signaling that the era of incremental growth has given way to a more aggressive adoption phase. Companies entering this window with outdated assumptions about market maturity will find themselves misaligned with both consumer behavior and veterinary prescribing habits.
The forecast arc from 2026 onward illustrates compounding growth, with revenue milestones reaching 20,227.39 million USD in 2027, 22,424.38 million USD in 2028, and continuing to escalate toward the late-2030s. This progression highlights the importance of timing in capacity planning, portfolio investment, and geographic prioritization. Manufacturers that scale too conservatively risk ceding shelf space and veterinary preference to competitors who move decisively. Conversely, those that overinvest without sufficient segmentation intelligence may find themselves burdened by misalignment between product formats and regional demand profiles. Our research isolates the inflection points where these decisions must be made, offering forward-looking indicators rather than backward-looking summaries.
Strategic planning for 2026 requires appreciation of how the growth rate is distributed across different market vectors. While top-line figures capture attention, the operational reality is that growth emanates from distinct drivers—veterinary channel consolidation, expanded condition coverage, format diversification between dry and wet therapeutic offerings, and the gradual penetration of emerging markets where pet healthcare infrastructure is still maturing. Each of these vectors carries its own risk-return profile, and our report maps them against practical decision frameworks.
Structural Demand Drivers Shaping Strategic Planning
Several interconnected forces are propelling the prescription diet segment beyond traditional boundaries. Pet owners increasingly view animals as family members, transforming purchasing behavior from cost-conscious commodity selection to value-driven health investment. This cultural shift has reinforced veterinary authority as the primary gatekeeper for therapeutic nutrition, ensuring that prescription diets retain a moat that over-the-counter wellness products cannot easily breach. At the same time, veterinary clinics themselves are evolving into broader wellness centers, integrating nutritional counseling into routine care and expanding the touchpoints where prescription diets are recommended.
Regulatory frameworks continue to shape market conduct in ways that reward compliance and penalize ambiguity. In the United States, prescription pet foods require veterinary authorization for sale under FDA guidelines to ensure that therapeutic claims are substantiated, reinforcing the clinical credibility of the category and limiting informal distribution pathways. Concurrently, AAFCO mandates nutritional adequacy statements and ingredient listing in descending order by weight for all complete and balanced pet foods, establishing baseline transparency expectations that influence consumer trust and formulation strategies. These standards do not merely constrain—they provide a structured environment in which brands can differentiate through verifiable efficacy and clear labeling discipline.
On the supply side, raw material volatility has introduced a new layer of strategic consideration. Chicken meal prices rose 8 percent year-over-year to 1,450 USD per metric ton due to avian influenza impacts, illustrating how protein ingredient markets can fluctuate in response to disease outbreaks and agricultural disruptions. For manufacturers of therapeutic diets, where consistency and nutritional precision are paramount, sourcing resilience is not a back-office concern—it is a product integrity issue. The report examines how leading players are adjusting procurement strategies, reformulation buffers, and supplier diversification to mitigate these exposures without compromising formulation integrity.
Regional and Segment Dynamics Without the Noise
The market's geographic footprint reflects differing stages of maturity, veterinary infrastructure, and consumer acceptance of therapeutic nutrition. North America continues to anchor a substantial share of global revenue, supported by high veterinary engagement rates, established prescription channels, and strong brand loyalty among consumers who trust clinician recommendations. Europe represents a similarly significant base, shaped by robust regulatory oversight, including EU Regulation (EC) No 183/2005, which requires registration of pet food establishments and imposes strict additive limits for imported veterinary diets. These regulatory conditions influence both market entry timing and formulation adaptation requirements for multinational players.
Asia Pacific, Latin America, and the Middle East and Africa collectively represent growth frontiers where the prescription diet concept is still gaining structural footholds. In these regions, the pace of expansion is influenced by the gradual professionalization of veterinary care, the spread of premium pet retail formats, and the extent to which local regulatory environments align with international standards. Our analysis avoids simplistic regional rankings and instead evaluates each geography across adoption readiness, channel accessibility, and competitive intensity, allowing leaders to prioritize investments where the marginal return justifies the execution complexity.
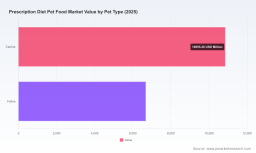
Segmentation across pet types reveals the relative weighting of canine and feline therapeutic demand, with canine prescriptions historically commanding a larger revenue contribution due to broader market penetration and a wider array of condition-specific formulations. Feline prescription diets, while smaller in absolute terms, are experiencing targeted growth as veterinary awareness of cat-specific health challenges—such as renal function, urinary tract maintenance, and weight management—continues to deepen. The report further dissects condition-level demand, where weight management, digestive care, renal and urinary care, skin and food sensitivities, and diabetes and other conditions each carry distinct formulation requirements, veterinarian engagement patterns, and consumer education needs. Rather than providing static percentage splits, we analyze how these condition categories interact with product format, pricing tolerance, and prescription frequency to reveal which therapeutic subcategories offer the most actionable growth opportunities in the current cycle.
Competitive Landscape: Concentration, Innovation, and Channel Control
The prescription diet market is characterized by a high degree of competitive concentration, with the top three players collectively accounting for 68.45 percent of market revenue and the top five extending that share to 82.12 percent. This concentration is not accidental—it reflects the structural advantages of established veterinary relationships, extensive clinical research portfolios, and manufacturing scale that creates barriers for newcomers. Yet concentration does not imply stagnation. The leading companies continue to compete aggressively on formulation innovation, channel reach, and brand trust, and our report evaluates each major player through the lens of strategic positioning rather than mere market share.
Hill's Pet Nutrition, headquartered in Topeka, Kansas, offers a Prescription Diet line with over 40 therapeutic formulas for dogs and cats addressing conditions like kidney disease, urinary health, obesity, and dermatology issues, available exclusively through veterinarians. This exclusive channel strategy reinforces clinical authority and limits dilution, while the breadth of formulas provides veterinarians with a comprehensive toolkit for varied cases. In October 2024, Hill's launched Prescription Diet k/d Chicken & Vegetable Stew for cats to support kidney health, demonstrating a focus on format innovation and palatability enhancement for hard-to-feed patients. For competitors, this signals that texture, flavor, and patient compliance are becoming as strategically relevant as nutrient profiles themselves.
Royal Canin, based in Aimargues, France, provides a Veterinary Diet range including formulas for gastrointestinal, cardiac, joint, and renal support in dogs and cats, sold via veterinary channels worldwide. Its global distribution footprint and condition-specific portfolio make it a persistent benchmark for international scalability. In June 2024, Royal Canin introduced new size options for Veterinary Diet Renal Support wet formulas, addressing a practical pain point in multi-pet households and varying patient appetites. This type of incremental product architecture improvement may appear modest, but it directly influences repeat purchase behavior and veterinary recommendation consistency.
Nestlé Purina PetCare, operating from St. Louis, Missouri, markets Pro Plan Veterinary Diets with specialized nutrition for allergies, critical care, weight management, and orthopedic needs in pets, distributed through vets. Its participation in major industry events underscores the importance of visibility and education in a category where veterinarian confidence drives adoption. In March 2024, Nestlé Purina showcased updated Pro Plan Veterinary Diets at Global Pet Expo, using the platform to communicate formulation advancements and reinforce relationships with the veterinary community. Such engagements are not just marketing—they are strategic investments in the prescription pathway itself.
Virbac, headquartered in Carros, France, focuses on Veterinary HPM diets targeting obesity, urinary, and skin conditions for dogs and cats through prescription-only therapeutic nutrition. Its positioning illustrates how specialized brands can compete by emphasizing distinct formulation philosophies and targeted condition coverage rather than attempting to match the breadth of larger portfolios. Together, these companies represent the competitive core that defines pricing norms, channel expectations, and innovation tempo across the category.
Beyond these headline players, the report maps adjacent competitors, private-label dynamics emerging through veterinary clinic partnerships, and the potential for regional challengers to gain traction where global brands face regulatory friction or distribution gaps. The FSMA Rule requiring preventive controls for pet food manufacturing, including allergen cross-contact prevention in prescription diets, adds an operational requirement that disproportionately affects smaller manufacturers lacking robust quality systems. This regulatory reality further reinforces the competitive advantages of established players while creating compliance costs that shape market entry calculations for new entrants.
Operational Intelligence Embedded in the Report
Our research is designed to translate market complexity into actionable decision support. The report structure moves beyond high-level summaries to provide operational depth across formulation trends, packaging and format shifts, veterinary channel economics, and regulatory compliance pathways. Readers will find detailed analysis of how therapeutic claims are substantiated and communicated, how manufacturing preventive controls intersect with allergen management, and how ingredient price volatility influences margin planning and reformulation timing. The study also covers distribution architectures, examining how veterinary clinics, specialty retailers, and authorized online channels differ in their prescription diet turnover, customer education responsibilities, and brand preference formation.
Worldwide Prescription Cat Food Market
Additionally, the report evaluates the strategic implications of labeling discipline under AAFCO and FDA expectations, the cross-border complexities introduced by EU registration and additive restrictions, and the practical impact of FSMA preventive control obligations on production scheduling and quality assurance. By integrating these compliance dimensions with commercial analysis, the study helps leaders assess not only where the market is going, but what it costs to operate competitively within it.
Worldwide Prescription Diet Pet Food Market
Why This Report Matters for 2026 Decision-Making
The prescription diet pet food market rewards organizations that combine scientific credibility with commercial discipline. In 2026, the companies that outperform will be those that understand how growth is distributed across conditions, formats, and channels; how regulatory requirements shape both product architecture and market entry timing; and how competitive concentration creates both barriers and opportunities depending on a player's strategic posture. Our report provides the structural intelligence needed to make those judgments with confidence, while deliberately preserving the detailed sub-segment data, regional revenue figures, and condition-level market splits for subscribers who require the full operational picture.
For executives, category managers, and strategy teams, this research functions as a decision calibration tool. It clarifies where demand is structurally strengthening, where competitive intensity is concentrated, and where regulatory and supply chain variables are most likely to affect margin and execution. The macro trajectory, competitive profiles, and dynamic context presented here represent only the visible portion of the analysis. The complete intelligence—segment-level sizing, regional breakdowns, channel-specific behavior, and forward indicators for formulation and compliance priorities—is available through the full report, enabling leaders to move from market awareness to precise strategic action.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Diet Pet Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com