

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Food Encapsulating Tech Market Hits $11.54B in 2025, Projected 8.12% CAGR to 2032

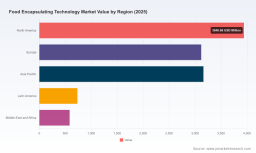
Global Food Encapsulating Technology Market: Strategic Intelligence for 2026 and Beyond
As the global food and beverage industry navigates an era of heightened consumer demand for functional nutrition, clean-label transparency, and shelf-stable delivery systems, encapsulating technologies have transitioned from niche academic applications to foundational manufacturing infrastructure. The Worldwide Food Encapsulating Technology Market is projected to reach US$19,932.09 million by 2032, reflecting a compound annual growth rate of 8.12 percent from the base year 2025 through the end of the forecast period. This trajectory is not merely a statistical projection; it represents a structural shift in how manufacturers protect sensitive bioactives, optimize flavor retention, and meet increasingly stringent regulatory labeling mandates across multiple jurisdictions.
For executive leadership, procurement strategists, and R&D directors preparing for 2026, understanding the mechanics behind this expansion is no longer optional. It is a prerequisite for capital allocation, partnership selection, and technology road mapping. This market intelligence briefing synthesizes historical performance data spanning 2020 through 2025 with forward-looking projections extending to 2032, offering a comprehensive view of market velocity, technological maturation, and competitive positioning. Yet, the full analytical architecture—segment-level revenue contributions, regional performance differentials, technology adoption curves, and phase-specific demand drivers—contains far more granular decision-support metrics than can be responsibly summarized in an introductory overview. To access the complete dataset, consult the full market research report.
Macro Market Trajectory and Structural Growth Drivers
The historical record demonstrates a clear inflection point beginning in 2022, with revenues climbing from approximately US$8,734.41 million that year to US$10,194.14 million in 2023, followed by continued expansion to US$11,540.0 million in the base year. This acceleration reflects the convergence of several macro forces. First, the functional food and beverage sector has matured beyond basic fortification, now demanding precision delivery systems that preserve the efficacy of probiotics, enzymes, and heat-sensitive vitamins through thermal processing, pasteurization, and extended shelf life. Second, consumer preference for sensory consistency in flavored and reduced-sugar formulations has elevated the strategic value of encapsulation as a masking and release-control mechanism. Third, regulatory frameworks governing nutritional labeling, additive transparency, and food safety compliance have incentivized manufacturers to adopt encapsulation as a risk-mitigation layer, particularly when stabilizing bioactives that degrade under standard storage or processing conditions.
Looking ahead to the 2026 to 2032 forecast horizon, the compound annual growth rate of 8.12 percent implies a market that will more than double its base-year valuation within seven years. This expansion will not be linear. It will be shaped by capital investment cycles in advanced manufacturing facilities, the commercial maturation of alternative wall material platforms, and the pace at which mid-tier manufacturers transition from conventional blending to controlled-release microencapsulation. The underlying data set tracks these inflection points across multiple dimensions, mapping growth vectors that allow decision-makers to anticipate capacity bottlenecks, evaluate technology adoption timing, and align procurement strategies with projected demand shifts. A detailed breakdown of these vectors—distinct from the headline CAGR—is essential for scenario planning and remains accessible within the complete research publication.
Technology Architecture and Core Phase Demand Patterns
Food encapsulation is fundamentally a materials science discipline, and the market is segmented by the primary processing technologies employed to achieve ingredient protection, controlled release, and sensory optimization. The dominant methodologies in the current landscape span spray drying, spray chilling, fluid bed coating, extrusion, and a portfolio of emerging or niche techniques. Each modality carries distinct trade-offs in terms of throughput, particle size distribution, wall material compatibility, and suitability for specific core ingredients. Spray drying remains a high-volume workhorse for flavor and colorant stabilization, particularly where rapid dehydration and cost efficiency are paramount. Fluid bed coating and extrusion offer more precise layer-by-layer deposition for functional ingredients requiring graded release profiles. Spray chilling serves specialized applications where thermal sensitivity rules out high-temperature drying.
Food Flavor Enhancer Market
Parallel to technology segmentation, the market is structured around the core phases being encapsulated. Flavors and colorants represent a substantial share of demand, driven by the need to maintain sensory integrity in complex matrices and alongside clean-label reformulation initiatives. Vitamins and minerals form another critical pillar, particularly as fortification requirements intersect with bioavailability optimization and stability under varied processing conditions. Enzymes, probiotics, sweeteners, and a range of other core phases complete the demand spectrum, each with unique encapsulation challenges related to activity preservation, carrier compatibility, and release timing. The interaction between technology type and core phase is not a simple one-to-one mapping; it is a multidimensional matrix that determines manufacturing feasibility, cost structure, and end-use performance. The full report dissects these intersections with segmentation-level revenue data, enabling stakeholders to identify which technology-phase combinations are gaining share, which are plateauing, and where innovation pipelines are likely to redirect investment flows in 2026 and beyond.
Competitive Dynamics and Strategic Positioning of Leading Players
The market structure exhibits moderate concentration, with the top three firms accounting for approximately 31.4 percent of overall revenue and the top five firms collectively representing roughly 46.8 percent. This concentration level signals a landscape where large-scale ingredient manufacturers and specialized technology providers coexist, each pursuing differentiation through proprietary wall materials, application-specific delivery systems, and targeted capacity expansions. The competitive environment is not defined by price competition alone; it is increasingly driven by formulation science, regulatory compliance enablement, and the ability to offer integrated ingredient-plus-encapsulation solutions that reduce downstream processing complexity for food manufacturers.
Several organizations have established particularly strong positions through deliberate portfolio strategies. Balchem Corporation, headquartered in New Hampton, New York, has built its brand around advanced microencapsulation platforms including BakeShure, ConfecShure, and MeatShure, each engineered for controlled release and ingredient protection in bakery, confectionery, meat, and broader food applications. In December 2025, the company announced the development of a new high-capacity microencapsulation manufacturing facility in Orange County, New York, with an expected opening in 2027, signaling a clear commitment to scaling capacity for these specialized technologies. Cargill, based in Minneapolis, leverages carbohydrate science and large-scale production infrastructure to provide encapsulation solutions for flavors, nutrients, and functional ingredients across food and beverage categories. Kerry Group, operating from Tralee, Ireland, combines flavor and nutrient encapsulation capabilities with extensive R&D resources focused on clean-label ingredient systems, positioning the firm at the intersection of sensory performance and labeling transparency.
Ingredion, headquartered in Westchester, Illinois, specializes in polysaccharide-based wall materials—primarily starch and modified starch—delivering customized encapsulation solutions tailored to dairy, beverage, and snack applications. BASF SE, from Ludwigshafen, Germany, supplies advanced encapsulation platforms that emphasize stability, bioavailability, and controlled release for vitamins, carotenoids, and other sensitive food ingredients, aligning closely with formulation requirements in functional and fortified products. DSM-Firmenich, operating from Heerlen, Netherlands, and Kaiseraugst, Switzerland, offers flavor delivery systems, premixes, probiotics, vitamins, and encapsulation technologies designed to optimize taste, texture, and nutrition in functional foods. Givaudan, based in Vernier, Switzerland, is widely recognized for flavor encapsulation and functional ingredient delivery systems, while International Flavors & Fragrances Inc., headquartered in New York, focuses on flavor and fragrance encapsulation for food and beverage products. Symrise AG, from Holzminden, Germany, develops encapsulated flavors and functional ingredients tailored to food industry requirements, and FrieslandCampina Kievit, operating from Amersfoort, Netherlands, provides spray-dried encapsulation solutions for flavors and creamers.
Worldwide Food Encapsulating Technology Market
The competitive field also includes specialized and emerging players whose technology focus addresses specific formulation gaps. Sensient Technologies Corporation, based in Milwaukee, Wisconsin, delivers color and flavor encapsulation technologies for food and beverage markets. TasteTech Ltd., from Bristol, United Kingdom, concentrates on microencapsulation for flavors and functional ingredients, while Xampla, headquartered in Cambridge, United Kingdom, has advanced plant protein-based microcapsules—utilizing materials such as pea protein—for nutrient encapsulation with enteric release properties. In May 2025, Xampla published peer-reviewed research demonstrating that its plant protein microcapsules effectively protect fat-soluble nutrients like Vitamin D2 through processing, storage, and simulated gastric digestion, releasing active ingredients in the intestine. This validation underscores a broader industry trajectory toward bio-based wall materials and targeted release mechanisms that align with clean-label expectations and regulatory preferences.
Understanding how these players position themselves across regions, technologies, and core phases is critical for partnership evaluation, supply chain diversification, and competitive benchmarking. The complete market research provides firm-level revenue estimates, addressable segment exposure, and technology portfolio mapping that enable granular competitive analysis. These insights are deliberately reserved for the full report to preserve analytical integrity and guide readers toward the complete intelligence package.
Wall Material Innovation, Regulatory Alignment, and Food Safety Implications
The effectiveness of any encapsulation system is fundamentally determined by the choice of wall material. Common materials in food encapsulation include polysaccharides such as starch, maltodextrin, and gum Arabic, alongside proteins like whey protein, soy protein, and pea protein. Each material class presents distinct functional attributes: polysaccharides often excel in film formation, moisture barrier properties, and compatibility with spray drying, while protein-based matrices can offer improved emulsification, nutrient binding, and, in certain formulations, targeted release behavior under specific pH or enzymatic conditions. The selection of wall material is rarely a single-variable decision; it is integrated with core ingredient characteristics, processing environment, desired release kinetics, and labeling considerations.
Regulatory alignment has become an increasingly important driver for encapsulation adoption. Food encapsulation technologies support compliance with nutritional labeling mandates by improving the stability and controlled release of vitamins, minerals, and bioactives in fortified foods, reducing degradation-related discrepancies between labeled and actual nutrient content. In parallel, encapsulation of bacteriocin-producing lactic acid bacteria and natural antimicrobials such as nisin is being researched to enhance food safety in higher-risk products, supporting compliance with FDA and USDA guidelines through more reliable antimicrobial delivery and activity retention. These regulatory and safety dimensions are not peripheral considerations; they are becoming embedded in product development timelines, quality assurance protocols, and go-to-market strategies.
The full research publication examines how these material science and regulatory forces shape segment-level demand, influence technology selection, and affect the competitive positioning of wall material specialists versus integrated ingredient suppliers. Detailed analysis of material adoption trends, formulation compatibility matrices, and compliance-related procurement drivers is available in the complete report.
Integration of Market Context Into 2026 Decision Frameworks
For organizations preparing for 2026, the encapsulation market presents both opportunity and execution complexity. Growth is robust, but it is unevenly distributed across technologies, core phases, and geographies. Capital deployment, supplier qualification, and R&D prioritization require a clear understanding of where demand is converging, where capacity is tightening, and which technological pathways are gaining validation through peer-reviewed research and commercial scaling. The historical data set covering 2020 through 2025 establishes a credible baseline, while the 2026 to 2032 forecast provides a structured lens for scenario modeling. Strategic decisions around facility investment, partnership selection, portfolio expansion, and formulation roadmap alignment should be grounded in the full segmentation architecture rather than headline figures alone.
The complete report delivers the operational detail necessary to convert market awareness into executable strategy. It includes technology-by-segment revenue distributions, regional performance differentials, core phase adoption patterns, concentration analysis across the competitive set, and detailed company profiles that map recent developments, capacity moves, and technology validation milestones. The two most recent developments highlighted in the intelligence set illustrate the kind of forward-looking signal embedded in the full publication: Balchem Corporation’s announced high-capacity microencapsulation facility in Orange County, New York, expected to open in 2027, and Xampla’s May 2025 peer-reviewed validation of plant protein microcapsules for fat-soluble nutrient protection and enteric release. These events are not isolated; they reflect capacity expansion logic and material science validation trends that influence regional supply dynamics, formulation feasibility, and competitive intensity. The full report contextualizes these developments within broader market trajectories and quantifies their likely impact on segment-level momentum.
Conclusion: Accessing Complete Strategic Intelligence
The Worldwide Food Encapsulating Technology Market is entering a phase where differentiation will be determined by formulation precision, wall material innovation, regulatory enablement, and the ability to scale specialized microencapsulation capabilities without compromising cost efficiency or performance reliability. An 8.12 percent compound annual growth rate through 2032, a base-year valuation of US$11,540.0 million, and a projected endpoint above US$19.9 billion all point to a maturing but still rapidly evolving market. Yet the headline metrics only frame the opportunity. The real strategic value lies in the segmentation detail, competitive positioning maps, technology-phase interaction analysis, regional differentiation, and company-level development tracking that enable precise decision-making.
This briefing has outlined the macro drivers, structural segmentation logic, competitive landscape, and regulatory and material science context that shape the market. To move from high-level awareness to actionable intelligence—complete with segment-level revenue splits, regional performance comparisons, technology adoption curves, and firm-specific strategic profiles—the full research report should be consulted. The complete dataset and analytical framework are designed to support capital planning, supplier evaluation, R&D prioritization, and competitive benchmarking for the 2026 decision cycle and the forecast horizon that follows.
For detailed analysis of this topic, please visit the official page: Worldwide Food Encapsulating Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com