

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global 5G-Advanced Chip Market Poised to Hit $41.5B by 2032 at 40.45% CAGR

Navigating the 5G-Advanced Chip Revolution: Strategic Intelligence for 2026 Enterprise Decisions
The global semiconductor landscape is undergoing a tectonic shift, driven by the transition from initial 5G deployment to the sophisticated capabilities of 5G-Advanced. As enterprises across telecommunications, automotive, industrial manufacturing, and consumer technology sectors evaluate their roadmaps for the latter half of the decade, the hardware foundation supporting these networks has become a critical variable in strategic planning. PW Consulting's latest Worldwide 5G-Advanced Chip Market report offers a comprehensive lens into this transformation, providing decision-makers with the data density required to navigate a market defined by rapid escalation and intense technological competition.
For stakeholders operating in 2026, understanding the trajectory of this market is not merely an academic exercise; it is a prerequisite for capital allocation, supply chain resilience, and product portfolio optimization. The market has moved from nascent experimentation to high-volume commercialization, creating a complex environment where timing and technological alignment determine competitive advantage. This introduction outlines the strategic value embedded within our latest research, highlighting the market dynamics, competitive currents, and technical specifications that will define success in the coming years.
Market Trajectory and Macroeconomic Scale
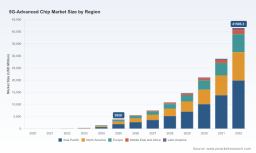
The velocity of growth in the 5G-Advanced chip sector is unprecedented. Our analysis tracks the market evolution from a historical baseline through a forecast period extending to 2032. The data reveals a steep adoption curve that underscores the accelerating integration of advanced wireless capabilities into diverse hardware ecosystems. Starting from a foundational period, the market crossed significant thresholds in the early 2020s, with revenue figures climbing sharply as infrastructure and devices began aligning with evolving 3GPP standards.
Worldwide 5G Processor Market
By 2025, the market had reached substantial scale, reflecting the culmination of years of research and development into commercially viable products. Looking forward to 2026, the projected revenue continues to expand at a pace that demands attention from investors and corporate strategists alike. The compound annual growth rate (CAGR) observed over the forecast period indicates a sustained surge, driven by the proliferation of high-performance applications that require more than legacy connectivity. This growth is not linear; it is compounded by the expanding addressable market as 5G-Advanced features move from premium segments to broader industrial and consumer use cases.
The forecast horizon through 2032 suggests that the peak of this investment cycle is still ahead. Organizations that analyze these trends now can position themselves to capture value before the market matures and competition intensifies further. The sheer magnitude of the revenue projections emphasizes that 5G-Advanced is not a niche enhancement but a foundational shift in how connectivity is engineered and monetized.
Segmentation Dynamics: Types, Applications, and Regions
A granular understanding of where value is being created is essential for targeted strategy. The market is diversified across chip types, application verticals, and geographic regions, each with distinct growth drivers and technical requirements. Our report dissects these segments to reveal the underlying forces shaping demand.
In terms of chip architecture, the market is dominated by baseband processing capabilities, which form the core of signal handling and protocol management. However, the ecosystem is equally dependent on radio frequency (RF) transceivers and front-end modules, as well as power management solutions that ensure efficiency in high-performance deployments. The balance between these components reflects the broader engineering challenges of 5G-Advanced, where bandwidth, latency, and energy consumption must be optimized simultaneously.
On the application side, mobile devices and wearables remain a primary consumption channel, leveraging advanced modems to deliver enhanced user experiences. Yet, the industrial sector is emerging as a powerful growth engine. Industrial IoT and robotics applications are increasingly reliant on robust, low-latency connections that 5G-Advanced chips enable, facilitating automation and real-time data analytics at the edge. Automotive and vehicle-to-everything (V2X) communications represent another critical vector, where safety and connectivity intersect to redefine transportation infrastructure. Fixed wireless access continues to play a role in bridging connectivity gaps, supported by chipsets designed for robust network performance.
Geographically, the market distribution highlights the concentration of manufacturing and deployment capabilities. Asia Pacific stands out as a significant hub, reflecting the region's dense manufacturing base and rapid technology adoption. North America and Europe also contribute substantial shares, driven by infrastructure investment and enterprise innovation. Emerging regions are beginning to integrate into this global supply chain, adding layers of complexity and opportunity for companies with international operational footprints.
The Competitive Arena: Leaders and Innovators
The competitive landscape of the 5G-Advanced chip market is characterized by a mix of established giants and specialized innovators, each pursuing distinct strategies to capture market share. Market concentration metrics indicate that a small number of players control a significant portion of the revenue, underscoring the high barriers to entry and the capital intensity of advanced semiconductor development. The top three players account for a dominant share, while the top five extend their influence further, shaping the standards and supply dynamics of the industry.
Qualcomm Technologies, Inc., based in San Diego, remains a pivotal force with its lineup of 5G-Advanced modem-RF systems. Their platforms, including the Snapdragon X85 and X80, support 3GPP Release 18 features across smartphones, fixed wireless access, automotive, and infrastructure segments. In March 2026, Qualcomm announced the Qualcomm X105 5G Modem-RF, described as the world's first 3GPP Release 19-ready modem. This launch integrates enhanced 5G-Advanced performance with AI capabilities, with sampling to customers underway and commercial devices anticipated in the second half of 2026. Such moves signal a continuous iteration cycle where leadership is maintained through rapid product evolution.
MediaTek Inc., headquartered in Hsinchu, Taiwan, offers a broad portfolio of 5G-Advanced solutions. Their M90 modem and T930 flagship platform for fixed wireless access and customer premises equipment support Release 18 standards. MediaTek has also emphasized MIMO enhancements, with 8Rx/3Tx configurations delivering significant spectrum efficiency gains. In March 2026, the company showcased the world's first 5G-Advanced CPE device with Wi-Fi 8 powered by the T930 chipset, highlighting improvements in uplink performance and AI-driven quality of service engines. Additionally, MediaTek introduced new 5G-Advanced telematics chipsets, expanding their reach into automotive applications.
Samsung Electronics Co., Ltd., in Suwon, South Korea, operates with a dual role in modem and smartphone integration. Their Exynos processors and 5G-Advanced chipsets leverage advances in GAA transistor technology and high-bandwidth memory to support high-performance wireless applications. This vertical integration allows Samsung to optimize performance across the device stack, a strategic advantage in the mobile and infrastructure sectors.
Broadcom Inc., located in San Jose, California, focuses on infrastructure-grade solutions. Their BroadPeak 5nm Massive MIMO SoC platform is designed for 5G-Advanced and 6G-ready infrastructure, incorporating RF and converter technology with FPGA interoperability for wideband radios. In February 2026, Broadcom completed interoperability testing of Agilex 7 FPGAs with the BroadPeak SoC platform at 32.44Gbps JESD204C, enabling scalable beamforming and AI-assisted signal processing. These collaborations highlight the importance of open architectures in scaling network capabilities.
Other notable players include GCT Semiconductor Holding Inc., which announced first commercial shipments of its 5G chipset in January 2026 for applications including air-to-ground networks, marking a milestone in niche deployment areas. Sequans Communications, based in Paris, is developing 5G NR eRedCap chipsets with platforms like Monarch 3 and Calliope 3, supporting the transition to 5G-Advanced IoT with low-energy designs. Huawei Technologies Co., Ltd., in Shenzhen, supplies 5G-Advanced chipsets and infrastructure solutions with demonstrated applications in robotics and healthcare. Intel Corporation, in Santa Clara, offers infrastructure-focused chipsets and network processors supporting edge computing and base station solutions. Together, these companies illustrate the breadth of innovation driving the market.
Industry Dynamics and Technological Catalysts
Beyond company actions, the market is shaped by broader industry dynamics including standardization, regulatory frameworks, and manufacturing infrastructure. The 3GPP Release 18 specifications define the core features of 5G-Advanced, introducing enhancements in advanced downlink and uplink MIMO, AI/ML data-driven designs, energy-efficient networks, evolved duplexing, RedCap evolution, and expanded positioning. These specifications form the technical backbone that chipsets must support, creating a standardized baseline for interoperability and performance.
The Global System for Mobile Communications Association (GSA) tracks the ecosystem's readiness, noting that as of May 2025, five modems supported 5G-Advanced features with 75 devices hardware-compatible with Release 18, primarily using Qualcomm Snapdragon platforms. Increased device launches are expected from late 2025 onward via Snapdragon X85 adoption, indicating a pipeline of products ready to absorb advanced chip capabilities.
Regulatory and investment environments also play a crucial role. The U.S. CHIPS Act has driven substantial semiconductor supply chain investments, including advanced packaging and GaN-on-SiC fabs for 5G/6G, radars, and satellite technologies. TSMC's Arizona facilities are producing advanced nodes such as 4nm, 3nm, and 2nm, supporting high-volume manufacturing of chips for 5G/6G smartphones and related applications. These infrastructure developments reduce supply bottlenecks and enable the production of the complex chips required for next-generation networks.
Worldwide 5G-Advanced Chip Market
Additionally, material science trends influence component selection. GaN RF chips account for over half of RF chips in telecom equipment and are projected to reach up to 90% market share due to requirements for high-frequency mmWave 5G-Advanced signal amplification. This shift impacts procurement strategies and supply chain planning for organizations involved in RF front-end design.
Strategic Imperatives for 2026 and Beyond
For enterprises operating in 2026, the insights contained in this report translate into actionable intelligence across several dimensions. Procurement teams must evaluate supplier capabilities against the backdrop of rapid product cycles and evolving standards. Understanding which chip types and architectures align with specific application requirements can optimize performance and cost. Supply chain managers need to assess the geographic distribution of manufacturing and the impact of government incentives on availability and lead times.
Product strategists should consider how 5G-Advanced features can be leveraged to differentiate offerings in competitive markets. The convergence of AI integration with modem technology, as seen in recent launches, opens new possibilities for intelligent connectivity and network optimization. Meanwhile, the growth in industrial IoT and automotive segments suggests opportunities for cross-industry collaboration and new business models.
Investors and analysts can use the market size projections and segmentation data to inform capital allocation and valuation models. The high CAGR and expanding revenue base indicate a sector with significant upside, but also one where competitive positioning and technological execution will determine long-term winners. The concentration of market share among top players suggests that partnerships, licensing, and ecosystem access may be as important as raw manufacturing capacity.
Risk management is another critical area. The reliance on specific standards, materials, and manufacturing nodes introduces vulnerabilities that must be mitigated through diversification and scenario planning. Regulatory changes and geopolitical factors can influence supply chain flows and market access, requiring continuous monitoring and adaptive strategies.
Accessing Comprehensive Intelligence
This overview provides a snapshot of the strategic landscape surrounding the Worldwide 5G-Advanced Chip Market. However, the full depth of analysis required for precise decision-making is contained within the complete report. Detailed segmentation data, historical trends, forecast models, and company profiles offer the granularity needed to validate hypotheses and build robust strategies.
PW Consulting's research is designed to serve as a foundational tool for executives, planners, and technical leaders who need to navigate the complexities of this high-growth market. The report integrates quantitative data with qualitative insights, covering the interplay of technology, competition, and regulation that defines the industry.
For organizations seeking to secure their position in the 5G-Advanced era, access to comprehensive market intelligence is not optional. We invite stakeholders to explore the full report for detailed figures, regional breakdowns, application-specific forecasts, and in-depth competitive analysis. Engaging with this intelligence now will ensure that your organization is prepared to capitalize on the opportunities of 2026 and beyond, with a clear view of where the market is heading and how to reach it.
Visit our research portal to access the complete Worldwide 5G-Advanced Chip Market report and equip your team with the insights needed to lead in this dynamic landscape.
For detailed analysis of this topic, please visit the official page: Worldwide 5G-Advanced Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com