

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Self-Checkout Market Hits $5.8B in 2025, Projects 13.01% CAGR to 2032

The Self-Checkout Revolution: Strategic Insights for the 2026 Retail Landscape
The retail sector stands at a critical inflection point. As we move through 2026, the integration of self-checkout technologies has transitioned from a novel convenience to a fundamental component of operational strategy. For enterprise leaders, investors, and technology partners, understanding the trajectory of this market is no longer optional—it is essential for navigating the complexities of modern commerce. PW Consulting's latest comprehensive study, the Worldwide Self-Checkout in Retail Market report, offers a definitive roadmap through this evolving terrain.
This analysis is not merely a collection of statistics; it is a strategic asset designed to inform capital allocation, technology procurement, and long-term planning. By examining the interplay between macroeconomic drivers, technological innovation, and competitive dynamics, this research equips decision-makers with the intelligence required to thrive in an increasingly automated retail environment.
Market Trajectory and Macroeconomic Context
The global self-checkout market has demonstrated remarkable resilience and growth over the past half-decade. Between 2020 and 2025, the market expanded significantly, rising from a baseline of approximately 3.12 billion USD to over 5.83 billion USD in 2025. This historical performance underscores the accelerating adoption of self-service technologies across diverse retail formats, driven by shifting consumer preferences and operational necessities.
Looking forward, the forecast period from 2026 to 2032 projects sustained momentum. The market is anticipated to reach new heights, with revenue expected to surpass 6.76 billion USD in 2026 and continue its ascent toward 13.73 billion USD by 2032. This growth path is underpinned by a compound annual growth rate of 13.01 percent, signaling a robust expansion phase that outpaces many traditional retail infrastructure segments. Such figures indicate that self-checkout is not peaking but rather entering a mature growth stage where innovation and integration become the primary value drivers.
The year 2025, serving as the base year for this analysis, captures a market that has already weathered significant macroeconomic volatility, including labor fluctuations and regulatory shifts. The transition into the 2026-2032 forecast window provides a critical lens for evaluating how retailers will adapt to these enduring pressures while scaling their self-checkout deployments.
Core Market Drivers and Industry Dynamics
Several converging forces are propelling the adoption of self-checkout systems globally. Chief among these is the persistent pressure on labor costs and availability. Retailers are increasingly seeking to optimize staffing levels at checkout lanes to manage operational expenses, a trend that continues to accelerate deployment rates. Concurrently, regulatory updates regarding overtime salary thresholds in major markets have prompted chains to revisit scheduling and automation strategies, further incentivizing the shift toward self-service models.
However, the landscape is not without its complexities. The regulatory environment is tightening, particularly concerning data privacy. Multiple new state privacy laws enacted in 2025 have increased compliance requirements for retailers utilizing systems that collect customer data via cameras, sensors, or payment integrations. Furthermore, the retail sector's privacy maturity currently lags behind global averages, with data breaches costing an average of 3.91 million USD. Self-checkout systems handling biometric or vision data necessitate enhanced security measures under these expanding laws, adding a layer of strategic consideration to technology selection and deployment.
Despite some retailers scaling back or limiting self-checkout in high-shrink locations due to theft concerns, overall global terminal shipments reached nearly 205,000 units in 2024, with continued adoption observed in Europe and other key regions. This dichotomy highlights the need for nuanced strategies that balance loss prevention with the efficiency gains of automation.
Worldwide Self-Checkout in Retail Market
Technology Evolution and Solution Segmentation
The technological backbone of the self-checkout market is diversifying rapidly. The market is broadly categorized by solution types, ranging from cashless systems to traditional cash-based interfaces. Cashless systems currently represent the larger share of revenue, reflecting the global shift toward digital payments and contactless transactions. However, cash-based systems remain relevant in specific markets and demographic segments, ensuring a inclusive approach to checkout technology.
Component-wise, the market is driven by hardware solutions, which encompass the physical kiosks and scanning equipment. Software solutions and associated services form the remaining critical pillars, enabling the intelligence, user interface, and maintenance ecosystems that keep these systems operational. The integration of these components determines the overall efficacy and customer experience of the self-checkout process.
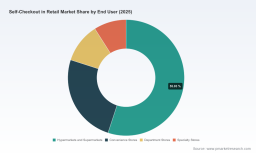
End-user adoption varies across retail formats. Hypermarkets and supermarkets remain the dominant segment, leveraging self-checkout to manage high transaction volumes and reduce queue times. Convenience stores are also a significant segment, adopting compact solutions to maximize floor space and throughput. Department stores and specialty stores follow, utilizing these systems to enhance the shopping experience in specific contexts. The ability to tailor solutions to these diverse environments is a key differentiator for technology providers.
Self-service Kiosk Market
Competitive Landscape: Innovation Among Key Players
The market is characterized by a concentrated competitive environment, with a few major players holding a significant share of the landscape. The top three companies account for a substantial portion of the market presence, while the top five entities collectively command over 86 percent of the market concentration. This consolidation highlights the high barriers to entry and the importance of scale, integration capabilities, and proven reliability in this sector.
Leading companies are actively reshaping the market through product innovation and strategic partnerships. NCR Voyix Corporation, based in Atlanta, continues to expand its footprint with cloud-based self-checkout solutions featuring modular hardware and real-time software updates. Their focus on AI-enabled kiosks and integration with loss prevention systems positions them at the forefront of adaptive checkout models. In early 2026, NCR Voyix highlighted its next-generation cloud-based solution, emphasizing enhanced efficiency and modular designs.
Diebold Nixdorf, Inc., headquartered in North Canton, Ohio, has made significant strides in AI-driven security and efficiency. Their introduction of Vynamic Smart Vision Shrink Reduction exemplifies the industry's move toward using computer vision to mitigate shrinkage, verify age-restricted items, and improve transaction speed for non-barcoded products. This enhancement addresses critical pain points for grocery and convenience retailers, bridging the gap between automation and loss prevention.
Toshiba Global Commerce Solutions, located in Durham, North Carolina, delivers customizable kiosks and software tailored to diverse retail formats. Their emphasis on operational efficiency and hybrid checkout models allows retailers to blend self-service with traditional assisted lanes, providing flexibility in store layouts.
In the Asia Pacific region, Fujitsu Limited supplies U-Scan systems, including RFID-enabled and computer vision solutions for fast, contactless scanning. Fujitsu, in collaboration with GK Software, recently conducted a hackathon to pioneer new retail solutions, including self-checkout enhancements, reflecting the growing adoption in European markets such as Germany, where fixed self-service checkouts have increased significantly.
Other notable players are carving niches through specialization. ITAB Group specializes in hardware and store solutions with a strong European presence. ECR Software Corporation develops hardware and CATAPULT software for traditional and departmental retail installations, supporting multiple payment types. StrongPoint ASA provides automation solutions with a focus on digitalizing physical commerce.
The hardware and component ecosystem is also robust. Zebra Technologies supplies rugged scanners and mobile integration for high-traffic settings. Honeywell International Inc. provides scanning and sensing technologies to improve accuracy. Datalogic S.p.A. delivers vision-based solutions for kiosks. Gilbarco Inc. focuses on convenience retail and fuel station integrations.
Emerging innovators are pushing the boundaries of user experience. Mashgin Inc. offers AI-powered computer vision solutions that bypass traditional barcodes for frictionless retail experiences. Partner Tech USA Inc. launched the 'Paula' compact tabletop AI-powered kiosk, focusing on efficiency and shrink reduction in retail and QSR environments. Companies like Pan-Oston Corporation, Pyramid Computer GmbH, MetroClick, Qingdao CCL Technology Co., Ltd., and Slabb Inc. contribute to the diverse hardware and software landscape, each bringing unique design and integration capabilities to the global market.
Regional Nuances and Deployment Strategies
While the market grows globally, regional dynamics play a crucial role in shaping deployment strategies. North America remains a primary engine of growth, reflecting the high penetration of technology and the mature retail infrastructure in the region. Europe follows as a significant market, driven by labor cost pressures and a strong acceptance of self-service technologies among consumers. The Asia Pacific region presents unique opportunities, with rapid urbanization and changing shopping habits fueling demand. Latin America and the Middle East and Africa, while smaller in current valuation, represent emerging frontiers where infrastructure development and retail expansion could unlock substantial growth over the forecast period.
Understanding these regional variations is essential for multinational retailers and technology vendors. Regulatory frameworks, cultural preferences, and payment infrastructures differ markedly across these geographies. A strategy that succeeds in North America may require adaptation for the European or Asian markets. This report provides the granular context needed to navigate these differences without relying on a one-size-fits-all approach.
Strategic Value for 2026 Decision-Making
For executives and strategists operating in 2026, this research offers actionable intelligence across several dimensions. First, it provides a clear benchmark for market sizing and growth expectations, enabling accurate revenue forecasting and investment planning. The projected trajectory through 2032 allows organizations to align their long-term roadmaps with market reality.
Second, the analysis of competitive dynamics helps identify potential partners, acquisition targets, or areas of differentiation. By understanding the capabilities and recent moves of key players, businesses can refine their vendor selection criteria or develop counter-strategies to maintain competitive advantage. The detailed profiles of companies reveal strategic focuses, such as AI integration, cloud architecture, or specific retail format specialization.
Third, the examination of market drivers and regulatory factors equips risk managers and compliance officers with the knowledge to anticipate challenges. The evolving landscape of data privacy laws and labor regulations requires proactive planning. This report highlights these dynamics, allowing organizations to build resilient operations that can adapt to regulatory changes without compromising efficiency.
Finally, the segmentation data offers insights into where the value lies within the market. Whether a company is focused on hardware manufacturing, software development, or end-user deployment, understanding the revenue distribution across components, solution types, and end-user segments is vital for targeting resources effectively. The report illuminates these splits, guiding stakeholders toward the most promising opportunities.
Conclusion and Access to Comprehensive Intelligence
The Worldwide Self-Checkout in Retail Market is a dynamic, high-growth sector poised to redefine the retail experience. As automation becomes increasingly intertwined with daily commerce, the ability to make informed, data-driven decisions will separate leaders from laggards. PW Consulting's latest research delivers the depth, breadth, and strategic context necessary to navigate this transformation with confidence.
While this overview highlights the macro trends, competitive landscape, and strategic implications, the full report contains the detailed quantitative analysis, specific segmentation data, and granular regional insights required for precise execution. To unlock the complete intelligence and secure a comprehensive understanding of the market's future, we invite you to explore the full study. Access the detailed report to gain the proprietary data and expert analysis needed to drive your strategy forward in this critical market.
For detailed analysis of this topic, please visit the official page: Worldwide Self-Checkout in Retail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com