

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive Torsional Vibrational Damper Market to Reach $3,362.02 Million by 2032

Strategic Imperatives in the Worldwide Automotive Torsional Vibrational Damper Market: Navigating Growth, Consolidation, and Technological Disruption Through 2032
The automotive industry is currently navigating a complex transitional phase defined by stringent emissions regulations, rapid electrification, and an unyielding consumer demand for refinement. Within this broader landscape, the torsional vibrational damper market occupies a critical, albeit often overlooked, niche. As internal combustion engines become increasingly downsized and hybridized to meet environmental targets, the management of crankshaft torsional vibrations has shifted from a secondary engineering consideration to a primary determinant of NVH performance, component durability, and overall vehicle reliability. PW Consulting’s newly released Worldwide Automotive Torsional Vibrational Damper Market study provides a comprehensive, data-driven roadmap for stakeholders seeking to capitalize on these shifting dynamics. Covering historical performance from 2020 through 2025 and projecting forward to 2032, this analysis is structured specifically to inform high-level procurement, R&D allocation, and geographic expansion strategies for the 2026 fiscal year and beyond.
Market Trajectory and Structural Evolution: A Decade of Measured Growth Amid Technological Flux
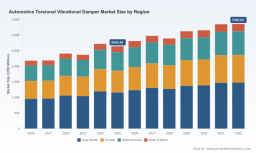
Over the past five years, the global torsional vibrational damper market has demonstrated a resilient growth trajectory, expanding from a revenue baseline of approximately 2.18 billion USD in 2020 to an estimated 2.72 billion USD in 2024 before consolidating slightly to 2.64 billion USD in 2025. This cyclical adjustment reflects the broader automotive production volatility experienced during the post-pandemic supply chain realignment, yet the underlying structural demand remains firmly intact. Moving into the forecast horizon, the market is projected to recover and steadily ascend, reaching 2.81 billion USD in 2026 and culminating at 3.36 billion USD by 2032. This expansion is underpinned by a compound annual growth rate of 3.5 percent, a figure that may appear moderate at first glance but carries profound strategic implications when dissected through the lens of powertrain evolution and component substitution rates.
The 3.5 percent CAGR should not be interpreted as a symptom of market stagnation, but rather as an indicator of a maturing ecosystem undergoing qualitative transformation. Revenue growth is increasingly decoupled from pure volume expansion and is instead being driven by value migration toward advanced materials, integrated multi-function modules, and higher-performance viscous and hybrid architectures. The base year of 2025 serves as a critical inflection point, capturing the market’s post-correction equilibrium before the accelerating adoption of electrification-enabling technologies begins to materially reshape demand curves. For automotive suppliers, tier-one manufacturers, and investment committees, understanding the velocity of this transition is paramount. The study provides granular visibility into how revenue streams are redistributing across product architectures, vehicle segments, and regional manufacturing footprints, enabling leadership teams to align capacity planning and technology roadmaps with actual commercial trajectories rather than speculative industry narratives.
Technology Inflection Points: Regulatory Pressure, Electrification, and Material Innovation Redefining Component Architectures
The fundamental drivers reshaping the torsional vibrational damper landscape are deeply intertwined with regulatory mandates and platform-level engineering shifts. EU fleet CO2 regulations and U.S. CAFE standards have systematically pushed original equipment manufacturers toward turbocharged small-displacement engines. While these powertrains deliver fuel efficiency gains, they simultaneously generate higher torsional excitations and more aggressive vibration spectra. Consequently, precisely engineered dampers are no longer optional accessories; they are critical stress-management components that protect crankshafts, drivetrains, and auxiliary belt systems from premature fatigue. This regulatory reality has elevated the functional requirements for damper durability, frequency targeting, and thermal resilience, directly influencing material selection and geometric design across the market.
Parallel to emissions-driven downsizing, the proliferation of 48-volt mild-hybrid architectures is introducing a new tier of integration complexity. With European market penetration of 48V systems projected to reach 35 percent of new vehicle sales by 2027, demand is accelerating for integrated belt-starter-generator torsional isolation units. These systems require dampers that can simultaneously manage engine firing pulses, starter-motor engagement shocks, and regenerative braking transients without compromising belt tension or alternator durability. The engineering response has been swift. Over 30 percent of companies have already launched hybrid dampers incorporating smart sensors, enabling real-time torque management and predictive maintenance capabilities. This sensorization trend hints at a broader industry trajectory where mechanical dampers evolve into data-generating nodes within vehicle health monitoring networks, opening adjacent revenue streams in software-defined diagnostic services and over-the-air maintenance forecasting.
Material innovation is equally transformative. Nearly 55 percent of new product developments in torsional vibration dampers now integrate lightweight composite materials, a shift designed to improve dynamic performance while simultaneously reducing noise, vibration, and harshness levels. Composite architectures allow engineers to tailor stiffness and damping coefficients with greater precision than traditional elastomeric formulations, particularly in high-frequency excitation zones. For competitors still reliant on legacy rubber-only designs, this material migration represents both a performance gap and a strategic vulnerability. The study dissects these technology adoption curves, mapping the pace at which advanced materials and sensor-integrated architectures are moving from pilot programs to series production, and identifying the supply chain bottlenecks that may delay or accelerate commercial viability.
Competitive Landscape and Porter’s Five Forces Realignment: Concentration, Differentiation, and the Rise of System-Level Integration
The torsional vibrational damper market operates under a moderately concentrated structure, with the top three enterprises collectively commanding approximately 42 percent of global revenue and the top five expanding that share to nearly 59 percent. This concentration reflects the capital intensity of damper manufacturing, the stringent validation cycles required by OEMs, and the long-term supply agreements that characterize automotive component procurement. However, concentration does not equate to complacency. The competitive battlefield has shifted from price-based volume competition to architectural differentiation, application-specific engineering, and system-level integration capabilities.
Vibracoustic SE has positioned itself prominently in the light-vehicle segment, offering pressed, vulcanized, and fluid torsional vibration dampers engineered to absorb crankshaft rotational vibrations. Their product philosophy emphasizes compatibility with decoupled pulleys, making their solutions particularly effective for downsized engines equipped with start-stop systems and auxiliary belt drive isolation. Continental AG has similarly expanded its OEM and aftermarket footprint with TVD and TVDi variants, leveraging flywheel, pulley, and elastomer track configurations to damp crankshaft vibrations and stabilize belt drives. In November 2024, Vibratech TVD reinforced its positioning in the high-performance segment by releasing OEM documentation highlighting dual viscous damper designs engineered for enhanced heat dissipation and durability. This move directly targets applications where elastomer-based alternatives struggle under high-temperature and high-load conditions. Continental followed a complementary trajectory in July 2024 with the launch of an integrated torsional vibration damper module tailored for 48V mild-hybrid engines, combining damper, pulley, and crank functions into a single architecture.
In the commercial and high-torque domain, ZF Friedrichshafen AG supplies DynaDamp torsional dampers utilizing dual mass flywheel technology, serving commercial vehicles, hybrids, and special applications with torque ratings extending up to 3,200 Nm. Their focus on decoupling engine vibrations and reducing rotational irregularities aligns closely with the durability and service-life expectations of heavy-duty platforms. Schaeffler AG, through its LuK and INA divisions, develops crankshaft torsional vibration dampers, spoke dampers, and pulley decouplers for both combustion and hybridized engines, targeting NVH reduction and crankshaft stress mitigation across diverse powertrain configurations. Viscous technology specialists such as Vibratech TVD and Hasse & Wrede GmbH continue to emphasize superior durability in demanding thermal environments, while Gates Corporation provides complete system solutions through its Micro-V and DriveAlign TVD lines, addressing crankshaft and engine vibration control for passenger cars and light commercial vehicles.
The competitive dynamic is increasingly defined by the ability to deliver validated, application-specific solutions rather than commoditized off-the-shelf components. Procurement teams are prioritizing suppliers that can demonstrate co-engineering capabilities, rapid prototyping cycles, and regulatory compliance documentation. The study maps these competitive differentiators, evaluates supplier risk profiles, and identifies white-space opportunities where regional manufacturing localization or material substitution could disrupt established supply relationships. For strategic planners, this competitive mapping is essential for negotiating long-term agreements, evaluating make-versus-buy scenarios, and anticipating consolidation events that may alter supply continuity.
Regional Demand Architecture and Application Segmentation: Navigating Heterogeneous Growth Engines
The geographic distribution of torsional vibrational damper demand reflects the uneven pace of automotive modernization across global markets. Asia Pacific remains the largest revenue contributor, anchored by high production volumes, expanding domestic consumer vehicle markets, and a growing base of commercial vehicle manufacturing. Europe represents a structurally distinct demand environment, where regulatory pressure, mild-hybrid adoption curves, and premium vehicle penetration create a high value-per-unit market characterized by stringent NVH expectations and rapid technology turnover. North America exhibits a more mixed profile, balancing light vehicle production with a substantial commercial vehicle segment and a persistent aftermarket demand curve that buffers OEM cycle volatility. The Rest of World segment, while smaller in absolute terms, is gaining strategic relevance as regional automotive clusters mature and localized content requirements influence component sourcing decisions.
Torsional Vibration Damper Market
The study deliberately avoids superficial regional or application-level aggregations in its executive disclosures, instead providing a structured analytical framework that allows strategists to construct scenario-based forecasts aligned with their specific portfolio exposure. Application segmentation reveals meaningful divergence in growth velocity across passenger cars, light commercial vehicles, and heavy commercial vehicles. Passenger car platforms continue to dominate absolute volume, but commercial vehicle segments are experiencing disproportionate value growth driven by torque escalation, extended service intervals, and stricter durability validation. Light commercial vehicle architectures are increasingly adopting passenger-car-derived vibration management strategies, while heavy commercial platforms are pushing the boundaries of dual-mass flywheel integration and high-torque viscous damping. Understanding how these application segments interact with regional production quotas, emissions compliance timelines, and electrification roadmaps is critical for capacity allocation and pricing strategy.
The 2026 Decision Framework: Translating Intelligence Into Capital Allocation, Sourcing Strategy, and R&D Prioritization
For executive teams formulating 2026 strategies, the torsional vibrational damper market presents a series of high-stakes decisions that extend far beyond conventional procurement optimization. Capital allocation must account for the steady migration toward sensor-integrated hybrid dampers, composite material formulations, and integrated belt-starter-generator modules, all of which require distinct tooling investments, validation protocols, and supplier qualification processes. Sourcing strategies must balance the stability of established tier-one relationships against the agility of regional suppliers capable of meeting localized content mandates and shorter lead-time requirements. R&D prioritization should focus on application-specific engineering capabilities that enable co-development with OEMs, particularly in mild-hybrid integration, thermal management of viscous architectures, and predictive diagnostics enabled by embedded sensor architectures.
The study is designed to operationalize these decisions by providing actionable intelligence across multiple analytical dimensions. It examines historical revenue behavior, forward-looking growth trajectories, technology adoption timelines, competitive positioning, and regulatory impact pathways, all structured to support portfolio planning, market entry evaluation, and risk mitigation. Readers gain access to a detailed mapping of product type evolution, vehicle segment utilization patterns, regional manufacturing dynamics, and supplier concentration metrics, alongside qualitative assessments of recent product launches, technical documentation releases, and material innovation roadmaps. The analysis also contextualizes market concentration within broader procurement risk frameworks, enabling supply chain leaders to stress-test continuity assumptions and identify secondary sourcing pathways before disruptions materialize.
Worldwide Automotive Torsional Vibrational Damper Market
Conclusion: Positioning for the Next Phase of Value Creation in Vibration Management Engineering
The worldwide automotive torsional vibrational damper market is entering a phase where incremental improvement yields diminishing strategic returns, and where structural differentiation, system-level integration, and regulatory-aligned engineering define competitive advantage. The 3.5 percent CAGR projected through 2032 masks the intensity of the underlying transformation: material migration toward composites, the sensorization of hybrid dampers, the integration of 48V mild-hybrid isolation units, and the recalibration of regional demand patterns in response to electrification timelines and emissions compliance deadlines. PW Consulting’s comprehensive study provides the analytical depth required to navigate this environment with confidence, equipping strategists, engineers, and procurement leaders with the intelligence necessary to translate market complexity into decisive action. For organizations seeking to secure supply continuity, accelerate technology adoption, and capture value from the evolving vibration management landscape, the complete report delivers the structured, decision-ready intelligence required to outperform in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Torsional Vibrational Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com