

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Strategic Intelligence for the Next Decade: Navigating the Global Nefopam Hydrochloride Landscape
The global pharmaceutical market is undergoing a structural recalibration, driven by a dual mandate: the escalating crisis of opioid dependency and the simultaneous demand for robust, effective pain management protocols. Within this complex environment, the Worldwide Nefopam Hydrochloride Market presents a compelling case study of niche specialization meeting broad clinical necessity. As enterprise decision-makers finalize their strategic roadmaps for the 2026 fiscal year and beyond, understanding the nuances of this non-opioid analgesic sector is no longer optional—it is imperative.
To support this critical decision-making process, PW Consulting has released a comprehensive Worldwide Nefopam Hydrochloride Market Research report. This document serves as more than a static snapshot; it is a dynamic strategic tool designed to illuminate the path from 2025 through 2032. By synthesizing historical performance data with forward-looking projections, this research equips stakeholders with the intelligence required to mitigate risk, identify partnership opportunities, and capitalize on emerging regulatory and clinical shifts.
Market Trajectory and Quantitative Outlook
The macroeconomic signals surrounding Nefopam Hydrochloride indicate a steady, resilient growth trajectory. Based on historical data captured between 2020 and 2025, the market has demonstrated a consistent ability to expand despite broader pharmaceutical supply chain volatility. The baseline year of 2025 sets a robust starting point for the forecast period, with total revenue figures reflecting a mature yet expanding market presence.
Our analysis projects a Compound Annual Growth Rate (CAGR) of 5.5% over the forecast window extending to 2032. This growth rate suggests that while the market may not be experiencing hyper-exponential expansion, it possesses a stable, predictable upward momentum that appeals to long-term investors and supply chain planners. The projected revenue scale by the end of the forecast period underscores the increasing integration of Nefopam into standard pain management protocols globally. For strategic leaders, this trajectory implies a need to scale production capabilities and distribution networks in lockstep with this anticipated rise, ensuring that capacity constraints do not become bottlenecks for market capture.
Understanding these macro trends is essential, but granular visibility is where competitive advantage is won. Our report dissects the revenue streams not just by total volume, but by the specific structural components that drive value, allowing clients to pinpoint exactly where growth is originating and where margin pressure may develop.
Product Form and Application Dynamics
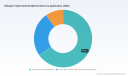
The market structure is defined by a bifurcation in product forms, primarily split between injectable solutions and oral tablet formulations. Each form factor serves distinct clinical pathways and operational requirements. Injections, often utilized in acute hospital settings for immediate pain relief, represent a significant portion of the revenue base, reflecting the high-intensity demand within surgical and emergency care environments. Conversely, tablets offer a pathway for outpatient management and chronic care regimens, providing a stable, recurring revenue stream that is less susceptible to the volatility of acute procedural volumes.
In terms of therapeutic application, the market is heavily anchored by Post-operative Pain Management. This segment remains the primary driver of volume, leveraging Nefopam's reputation as a non-opioid centrally-acting analgesic. Clinical data increasingly highlights its role in opioid-sparing strategies, where it helps reduce the total dosage of opioids required post-surgery—a metric that is becoming increasingly important for hospitals aiming to meet safety and recovery benchmarks. Beyond the operating theater, the report details the growing utilization in Chronic Pain Treatment and Acute Musculoskeletal Pain, segments that are expanding as clinicians seek alternatives to traditional NSAID or opioid therapies for long-term patient management.
Regional Revenue Concentration and Strategic Geography
Geographic diversification is a cornerstone of resilient market strategy. The research delineates revenue distribution across major global regions, revealing a landscape where established pharmaceutical markets hold significant weight, yet emerging regions present lucrative growth vectors. Europe currently commands a substantial share of the market revenue, underpinned by established healthcare infrastructure and favorable regulatory positioning for non-opioid analgesics within the EU member states.
Asia Pacific represents the next largest revenue block, reflecting both the massive patient population and the growing manufacturing capacity located within the region. Latin America and the Middle East and Africa, while currently representing smaller shares of the total revenue pie, offer strategic entry points for companies looking to expand their footprint in developing healthcare markets. For strategic planners, the key takeaway is not merely which region is largest, but how the growth rates differ across these geographies. The report provides the context needed to understand where regulatory hurdles might be lower, where reimbursement pathways are clearer, and where local manufacturing partnerships could yield the highest return on investment.
Competitive Landscape and Key Player Analysis
The Nefopam Hydrochloride market is characterized by a moderately concentrated competitive environment. With a CR3 of 58.4% and a CR5 of 74.2%, the market indicates that while there are dominant players, there remains room for specialized entrants and agile manufacturers to carve out niches. The barrier to entry is influenced significantly by regulatory certifications and the ability to maintain consistent API quality.
Several key companies define the current competitive architecture. Polpharma , based in Poland, stands out as a producer of Nefopam Hydrochloride API with a strong emphasis on regulatory compliance, holding GMP, EDMF/ASMF, and other certifications. They are positioned as an active commercial-scale supplier focused on the non-opioid analgesics sector. Similarly, PMC Isochem in France offers API manufacturing with CEP/COS and JDMF regulatory filings, catering to markets that require stringent European compliance documentation.
In the Indian pharmaceutical ecosystem, several manufacturers are active. Global Calcium operates as a manufacturer and exporter of Nefopam HCL, serving both domestic and international markets. Emcure Pharmaceuticals and Micro Labs Limited represent integrated and diversified healthcare companies with manufacturing capabilities for the API, while Maiden Group is engaged in the development and manufacturing of Nefopam-related products. Taj Pharma is notable for moving beyond API into finished formulations, manufacturing Nefopam Hydrochloride Injection and Tablet formulations. Additionally, Guangzhou Green Cross Pharmaceutical Co., Ltd. in China contributes to the global supply of Nefopam Hydrochloride API.
Other entities such as CF Pharma and PRG Pharma are listed as suppliers of the API, contributing to the broader supply chain availability. For procurement officers and business development teams, tracking the capacity expansions, certification renewals, and supply reliability of these specific entities is critical. The report provides detailed profiles and capability assessments for each, enabling stakeholders to vet potential partners or assess competitive threats with precision.
Recent Developments and Innovation Vectors
The landscape is not static; it is punctuated by specific events that can shift market positioning overnight. Our research integrates recent developments to provide a living view of the industry. In February 2025, Maxona Pharmaceuticals received a grant for their fifth patent regarding an optimized formulation of nefopam hydrochloride (MAX-001) intended for acute and chronic pain management, with plans for a Phase 2 clinical program. This signals ongoing R&D investment aimed at enhancing the therapeutic profile of the drug.
Worldwide Nefopam Hydrochloride Market
Simultaneously, clinical validation continues to accumulate. In June 2025, Siriraj Hospital published a randomized placebo-controlled double-blind clinical trial evaluating nefopam for analgesia following cardiac surgery. Positive outcomes in such specialized surgical contexts can accelerate formulary adoption and expand the addressable market within specific hospital networks. Furthermore, reimbursement and formulary positioning remain dynamic. In April 2025, the Lancashire and South Cumbria Formulary updated its new medicine assessment for Nefopam Hydrochloride 30 mg tablets, including cost and positioning data referencing the Drug tariff December 2024. In the UK, the drug tariff cost for a 90-tablet course is noted at £3.18 if taken daily as of December 2024, providing a concrete benchmark for cost-effectiveness analyses in that region.
Regulatory Framework and Market Access
Regulatory status is perhaps the most critical variable for international strategy. A key constraint identified in the market intelligence is that Nefopam Hydrochloride is not approved by the US FDA for marketing in the United States. This exclusion fundamentally shapes the strategic geography of the market, directing focus toward European, Asian, and other approved jurisdictions. Within the EU, Nefopam Hydrochloride 30 mg film-coated tablets hold nationally authorised medicinal product status in multiple countries under various marketing authorisation holders, including Crescent Pharma Limited and Generics [UK] Limited.
Additionally, regulatory nuances such as the paediatric investigation plan waiver granted by the EMA in January 2021 for a nefopam hydrochloride/paracetamol fixed-dose combination illustrate the evolving safety and usage profiles. Understanding these regulatory textures is vital for companies planning to launch new formulations or expand existing ones. Misalignment with local regulatory expectations can result in costly delays, making the regulatory analysis section of this report a high-value asset for compliance and market access teams.
Strategic Value for 2026 Decision-Making
Acquiring the Worldwide Nefopam Hydrochloride Market Research report is an investment in clarity amidst complexity. For 2026, the strategic priorities for pharmaceutical executives should revolve around three pillars: supply chain resilience, regulatory alignment, and clinical differentiation.
First, with revenue projections extending to 2032, manufacturers must assess whether their current production capacities for both API and finished formulations (injections and tablets) can meet the projected demand without compromising quality. The concentration levels in the market suggest that supply disruptions from key players could have outsized effects on the broader ecosystem.
Second, the regulatory landscape requires continuous monitoring. With specific approvals varying by region and the notable absence of US FDA approval, market entry strategies must be highly localized. Decision-makers need to know not just where the market is, but where it is legally permissible to operate, and where reimbursement structures support cost-effective patient access.
Third, clinical positioning is evolving. The reported opioid-sparing effect of 38% across reviewed studies provides a powerful value proposition for marketing and formulary committees. Aligning product messaging with this clinical benefit can differentiate offerings in a crowded analgesic market.
This report synthesizes these elements into a cohesive intelligence package. It moves beyond raw numbers to provide the narrative context necessary for strategic planning. Whether you are evaluating M&A targets, planning capacity expansion, negotiating supply contracts, or formulating market entry strategies, the granular data and competitive profiles contained within this research are designed to reduce uncertainty and accelerate decision velocity.
To access the full depth of segmentation data, complete competitive profiles, and detailed forecast models that underpin these insights, we invite you to download the complete Worldwide Nefopam Hydrochloride Market Research report from our portal. Equip your organization with the specific intelligence needed to lead in the 2026-2032 cycle.
Buprenorphine Hydrochloride Market
For detailed analysis of this topic, please visit the official page: Worldwide Nefopam Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pt Paste Market Hits $110M in 2025, Forecasts 6.45% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in a High-Growth Niche: Unpacking the Worldwide Pt Paste for Gas Sensor Market Outlook Through 2032
The global landscape for platinum-based thick film materials is currently navigating a period of pronounced reconfiguration. For stakeholders operating within the gas sensor value chain, the convergence of escalating automotive electrification, tightening environmental emissions standards, and persistent precious metal supply constraints has created a complex decision-making environment. Our latest comprehensive research, Worldwide Pt Paste for Gas Sensor Market, delivers a rigorous, data-driven assessment of this specialized sector. By tracing performance trajectories from the historical base period through the 2026 to 2032 forecast horizon, this study transforms fragmented industry signals into a coherent strategic framework. The market documented in this report has expanded from approximately 74.5 million USD in 2020 to a projected 119.95 million USD in 2026, reflecting a compound annual growth rate of 6.45% across the entire forecast window. This trajectory is not merely an indicator of steady expansion; it signals a structural re-rating of a material segment that serves as a critical enabler for combustion monitoring, industrial safety systems, and next-generation environmental detection platforms. Understanding where value is accumulating, which formulation architectures are outpacing legacy technologies, and how leading suppliers are navigating raw material volatility is essential for capacity planning, partnership evaluation, and long-term margin protection.
Macro Trajectory and Structural Expansion Drivers
Over the past half-decade, the Pt paste for gas sensor sector has demonstrated consistent upward momentum, with revenue climbing steadily from 82.4 million USD in 2021 through 86.02 million USD in 2022 and 94.71 million USD in 2023. Growth accelerated notably as 2024 recorded 105.73 million USD, followed by a base-year valuation of 110.0 million USD in 2025. The forward-looking phase indicates sustained capitalization, with the market scaling to 122.34 million USD by 2027, crossing 127.97 million USD in 2028, and reaching 141.26 million USD by 2029. Continued upward progression brings the valuation to 148.6 million USD in 2030, advancing to 154.45 million USD in 2031, and ultimately approaching 170.38 million USD by 2032. This pattern reflects more than cyclical demand recovery. It is anchored by durable investment in sensor infrastructure across regulated emission environments, expanding deployment of oxygen and nitrogen oxide detection systems in modern powertrain architectures, and broadening industrial utilization of continuous gas monitoring networks. Simultaneously, the research highlights how formulation differentiation is reshaping competitive positioning. High-temperature co-fired ceramic architectures continue to capture a substantial share of fabrication workflows due to their robustness under extreme thermal cycling, while low-temperature variants and thick film alternatives are carving out specialized roles in applications requiring distinct sintering profiles, finer line resolution, or modified conductivity thresholds. The study systematically maps these technical dichotomies, providing engineering and procurement leaders with a clear view of how material selection influences yield, long-term stability, and total cost of ownership.
Worldwide Pt Paste for Gas Sensor Market
Techno-Commercial Segmentation and Application Value Mapping
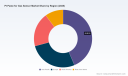
A central strength of this analysis lies in its ability to connect material architectures to end-use requirements without reducing complex engineering trade-offs to oversimplified comparisons. The report dissects the revenue distribution across primary categorization dimensions, revealing how distinct product families align with specific sensor performance mandates. High-temperature co-fired ceramic platinum paste formulations remain the dominant technical pathway, supported by their compatibility with aggressive firing schedules and proven reliability in harsh gas detection environments. Low-temperature co-fired ceramic variants represent a strategically important alternative, particularly where thermal budget constraints, substrate limitations, or multi-layer integration requirements dictate a gentler processing window. Thick film platinum paste solutions round out the landscape, offering manufacturers flexibility in screen-printing parameters, line definition, and post-firing conductivity characteristics. On the application side, the research underscores the heavy weighting of automotive oxygen and nitrogen oxide sensor deployments within overall consumption patterns, reflecting the ongoing tightening of tailpipe emissions regulations and the gradual but persistent penetration of advanced exhaust monitoring architectures. Industrial gas monitoring applications form a significant secondary pillar, driven by process safety mandates, chemical handling requirements, and facility environmental compliance programs. Environmental and home safety sensor deployments, while representing a smaller fraction of total material consumption, are gaining strategic relevance as residential and commercial building standards increasingly integrate continuous air quality and leak detection systems. By presenting these relationships through structured comparative frameworks rather than isolated percentage breakdowns, the study equips strategy teams with the analytical depth required to evaluate where capacity expansion, technology licensing, or targeted sales investments will generate the highest marginal returns.
Competitive Architecture and Supplier Capability Assessment
The vendor landscape for Pt paste in gas sensor applications is characterized by a concentrated yet highly differentiated competitive field. Our proprietary market concentration analysis indicates that the top three participants collectively command approximately 58.2% of industry revenue, while the leading five firms extend their combined footprint to roughly 74.5%. This concentration does not imply a homogeneous market. Rather, it reflects divergent material science competencies, regional manufacturing footprints, and specialized formulation capabilities that reward deep technical alignment over generalist positioning. Japanese materials specialists have built strong reputations by offering a broad portfolio of screen-printable platinum chemistries, ranging from low-resistance variants optimized for electrode and heater structures to high-resistance configurations tailored for thermal management subsystems. Their product engineering emphasizes high-temperature firing compatibility, RoHS-compliant compositions, and tightly controlled particle size distributions that support consistent print fidelity and reproducible electrical characteristics. European technology providers contribute complementary capabilities through thick film conductor systems that incorporate pure platinum and platinum-containing alloy architectures for gas sensing, positional sensing, and temperature measurement applications. Their recent documentation enhancements have further clarified performance parameters for solderable AuPtPd conductor pastes, highlighting surface uniformity, chemical resistance, and post-fabrication solderability as critical considerations for fuel sensor integration. British material developers have carved out distinct positioning with fritted platinum conductor pastes engineered for zirconia oxygen sensor circuitry and high-temperature dielectric substrates. Their formulations support firing windows spanning 850 to 1300 degrees Celsius, fine-line printing capability down to approximately 100 micrometers, and dense fired layer formation on alumina and advanced ceramic platforms. Additional participants from North America, Europe, and Asia extend the strategic portfolio through precision thick film engineering, platinum group metal recycling expertise, electrochemical material support, and specialized paste formulations targeting flat oxygen sensors and solid oxide fuel cell interfaces. The report evaluates these capabilities through a structured lens, enabling procurement leaders to benchmark particle fineness, solid content ratios, firing profile tolerance, and alloy customization potential against application-specific performance thresholds.
Material Economics, Regulatory Alignment, and Supply Chain Resilience
No strategic assessment of Pt paste demand can be conducted without addressing the upstream economics that govern cost structure and margin durability. Platinum metal serves as the foundational feedstock for paste production, with catalytic specifications, surface area requirements, and particle morphology commanding material premiums that directly influence formulation economics. The broader platinum supply environment has reinforced this sensitivity. Market data from recent reporting cycles highlights a third consecutive year of significant supply shortfall in 2025, with primary supply declining approximately 3% amid constraints in South African PGM output. This structural tightening coincided with a sharp price escalation through the year, driven by persistent deficits, geopolitical risk premiums, and reduced above-ground inventory levels. These dynamics elevate the strategic importance of sourcing discipline, hedging frameworks, and closed-loop recycling programs for manufacturers reliant on high-performance platinum architectures. At the same time, regulatory alignment remains a non-negotiable requirement for global market access. Contemporary Pt paste formulations must satisfy RoHS2 directive restrictions on lead and regulated substances, meaning that supplier qualification increasingly hinges on documented lead-free production standards, verified compliance documentation, and transparent material disclosures. The research integrates these feedstock, pricing, and compliance variables into a cohesive cost-risk narrative, helping organizations distinguish between temporary price fluctuations and longer-term structural pressures that require strategic inventory planning, dual-sourcing architecture, or formulation re-engineering. By treating raw material volatility as a strategic design parameter rather than a peripheral procurement concern, the study provides executive teams with the context needed to protect profitability across the full forecast horizon.
Operational Intelligence Built for 2026 Decision Cycles
This market study is designed to function as an operational reference for cross-functional teams that must translate market signals into executable strategy. The report delivers granular technology roadmaps that connect paste architecture choices to sensor performance expectations, integrating firing behavior, electrical conductivity profiles, adhesion characteristics, and compatibility with high-temperature dielectric substrates. It maps procurement pathways across formulation sourcing, alloy customization, and powders-to-paste manufacturing integration, allowing leadership to evaluate which supplier relationships offer the strongest alignment with volume scaling, technical support depth, and regulatory documentation standards. Competitive benchmarking modules assess product range breadth, application-specific customization capacity, and regional service infrastructure, giving strategy teams a structured way to compare incumbents and emerging participants without relying on superficial marketing claims. The analysis also incorporates forward-looking scenario modeling that links automotive emissions roadmap shifts, industrial monitoring adoption rates, and environmental safety sensor proliferation patterns to demand sensitivity across different formulation families. Combined with recent supplier documentation updates, market commentary on platinum deficits, and evolving compliance expectations, the study provides a consolidated platform for revenue forecasting, capacity planning, and risk-adjusted partnership evaluation. Decision-makers in manufacturing, R&D, supply chain governance, and corporate strategy will find a consistent analytical language that connects technical specifications, regional execution realities, and commercial viability within a single evaluative framework.
Electrode Paste Market
Why This Research Matters for 2026 Strategy Formation
The worldwide Pt paste for gas sensor market is entering a phase in which historical benchmarks and incremental forecasting are no longer sufficient for competitive advantage. Growth measured at a 6.45% CAGR across the 2026 to 2032 window, supported by a projected market trajectory advancing toward 170.38 million USD by the end of the forecast period, reflects durable structural demand rather than temporary expansion. Yet the real strategic challenge lies in identifying which formulation pathways, application segments, and supplier ecosystems will compound value most efficiently under realistic constraints of feedstock pricing, firing-process compatibility, and regulatory compliance. Our research removes ambiguity from that evaluation by delivering a complete diagnostic of technology differentiators, competitive concentration dynamics, and application-led demand sensitivities. This publication is structured to support direct integration into 2026 planning cycles, empowering stakeholders to align R&D roadmaps with material performance realities, optimize procurement exposure in a constrained platinum environment, and prioritize partnerships that translate formulation expertise into measurable cost and reliability advantages. Organizations that treat Pt paste selection as a strategic capability rather than a commoditized input will be best positioned to capture share in a market where technical differentiation and supply resilience increasingly determine long-term commercial outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Pt Paste for Gas Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Rail Components Market Reaches $72.45 Billion in 2025 to Hit $99.6 Billion by 2032 at 4.65% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Railway Era: Inside the Worldwide Rail Components Market 2026-2032
Executive Overview
The global railway components sector stands at a critical inflection point. As governments and private operators accelerate fleet modernisation, signalling digitisation, and heavy-haul capacity expansion, procurement leaders face a complex matrix of material volatility, evolving regulatory mandates, and shifting demand centres. Our latest Worldwide Rail Components Market study is designed to cut through this complexity, delivering a decision-ready intelligence framework that maps revenue trajectories, competitive positioning, and structural catalysts across the decade. Rather than offering static snapshots, the report translates historical momentum into forward-looking scenario planning, enabling executives to align capital allocation, supply chain resilience, and partnership strategy with verified market mechanics.
The Trajectory of Global Market Expansion
Historical revenue patterns reveal a market that has demonstrated remarkable resilience amid macroeconomic turbulence, supply chain realignments, and fluctuating infrastructure budgets. From 2020 through 2025, worldwide components revenue climbed from approximately 58.12 billion USD to a base-year level near 72.45 billion USD, reflecting sustained maintenance backlogs, fleet renewal cycles, and targeted public investment in high-capacity corridors. The forecast window extends through 2032, anchored by a compound annual growth rate of 4.65 percent and a projected end-period valuation approaching 99.6 billion USD. This trajectory is not linear; it is shaped by procurement pacing, delivery lead-time normalisation, and the interplay between legacy fleet upkeep and next-generation platform adoption. Readers examining the full report will encounter granular year-by-year revenue mapping that isolates organic volume growth from pricing effects, enabling precise budget forecasting and sensitivity testing across multiple procurement horizons.
Regionally Anchored Demand Patterns
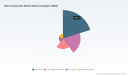
Market activity does not distribute uniformly across geographies. Asia Pacific continues to command the largest absolute revenue share, driven by high-speed network rollouts, metro system expansions, and domestic manufacturing scale. Europe maintains a substantial footprint shaped by cross-border interoperability requirements, signalling modernisation, and regulated tender cycles. North American component consumption remains tightly coupled to freight network efficiency programmes, heavy-haul infrastructure upgrades, and locomotive fleet optimisation. Latin America and the Middle East & Africa collectively represent growing but structurally distinct opportunity pools, often influenced by concession models, sovereign funding priorities, and targeted component substitution initiatives. The complete study breaks down regional revenue architecture without oversimplifying local procurement realities, mapping demand intensities, delivery channel preferences, and policy-driven procurement windows. Decision-makers requiring jurisdiction-specific pricing contexts, tender cycle timing, and regional supplier concentration metrics will find the full dataset essential for market entry, sourcing diversification, and partnership sequencing.
Worldwide Rail Components Market
Component Architecture and Train-Type Demand Correlations
The components landscape is defined by technical specialisation, lifecycle economics, and platform compatibility. Bogie and wheelsets constitute the largest component revenue segment, reflecting their centrality to ride quality, load distribution, and track interface performance. Propulsion and power systems follow closely, underscoring the industry-wide shift toward electrification, energy-efficient traction designs, and integrated power management architectures. Braking systems maintain a robust share, propelled by safety regulation mandates, friction material innovation, and retrofit demand on mature fleets. Interior and body structures, alongside couplers and ancillary hardware, round out the component palette, each responding to tailored operational profiles and route-specific performance requirements. Demand further diverges by train type, with passenger rolling stock capturing the broadest revenue pool, freight wagons sustaining steady procurement tied to logistics volume and wagon lifecycle replacement, and locomotives reflecting concentrated but high-value expenditure on traction, control, and reliability upgrades. Our full analysis dissects these relationships with component-level revenue mapping, technical substitution trends, and platform-specific procurement drivers, allowing engineering and sourcing teams to align specification strategies with verified demand patterns rather than generalised assumptions.
Competitive Dynamics in a Consolidated Landscape
The supplier ecosystem is characterised by meaningful concentration, yet it remains highly differentiated by technical capability, geographic reach, and vertical integration depth. Industry concentration metrics indicate that a relatively small group of multinational players commands a substantial share of total revenue, creating a market environment where scale, certification portfolios, and platform-standard compliance heavily influence winning positions. Alstom maintains a broad components portfolio spanning bogies, braking solutions, pantographs, couplers, and signalling-related hardware, with a strong foothold across both passenger and freight applications. Siemens Mobility reinforces its position through electrification, signalling, automation, and traction component offerings that increasingly intersect with digital rail operations. Wabtec Corporation and Knorr-Bremse compete at the core of braking, friction, and auxiliary system markets, while voestalpine Railway Systems holds notable influence in rail profiles, switches, turnouts, and track-side monitoring solutions. Thales contributes critical signalling, communication, and security technologies that increasingly shape component specification by enabling interoperability and operational automation. CRRC Corporation Limited and Hitachi Rail extend competitive pressure through high-speed and freight traction components, digital signalling integration, and large-scale platform supply capabilities. Additional specialists such as Lucchini RS, Greenbrier Companies, Trinity Industries, Titagarh Rail Systems, Stadler Rail, Nippon Steel, and ArcelorMittal Rails & Accessories reinforce the market with focused expertise in wheelsets, freight car structures, underframes, regional bogie designs, premium rail steels, and global infrastructure profiles.
Recent Catalyst Events Reshaping the Supplier Landscape
Recent corporate activity demonstrates how quickly competitive advantage can be reconfigured through product launches, strategic acquisitions, certification wins, and platform-level joint development. Siemens Mobility advanced driverless operational readiness by introducing GoA4 automation platform components for unattended rail operations, signalling a structural shift toward higher levels of automation in metro and regional contexts. Knorr-Bremse expanded its compact braking footprint by acquiring VYC Industrial, strengthening its portfolio for metro vehicle brake calipers and related subsystems. voestalpine achieved AREMA certification for its 390HH premium rail, reinforcing its eligibility for North American heavy-haul deployments and illustrating how standards compliance directly unlocks market access. Wabtec secured a supply agreement with Union Pacific for Trip Optimizer software and friction products, highlighting the growing intersection between digital optimisation tools and mechanical component supply. Alstom formalised a joint development agreement with Indian Railways to develop indigenous bogie designs, reflecting a broader push toward localisation, design sovereignty, and platform-specific engineering partnerships. The complete report places these events within a structured competitive analysis, mapping each move to market share implications, capability expansion, and downstream procurement effects.
Rail Market
Regulatory, Material, and Sustainability Forces Redefining Procurement
Beyond vendor dynamics, external forces are reshaping specification priorities, cost structures, and delivery planning. Raw material pressures remain a persistent concern, with pearlitic rail steel prices climbing year over year in Europe as energy costs and input volatility continue to influence alloy pricing. At the same time, demand for bainitic rail steels has risen for high-speed applications, reflecting performance requirements that reward durability and reduced maintenance overhead. On the regulatory front, the EU TSI LOC&PAS framework mandates ERTMS Baseline 3 compliance for new signalling components from 2025, creating a clear technical threshold that influences specification cycles and supplier qualification. In the United States, FRA requirements for PTC 2.0 interoperability introduce additional interoperability expectations across Class I networks, affecting both onboard and wayside component planning. From a trade and sustainability angle, the EU Carbon Border Adjustment Mechanism introduces meaningful cost implications for imported rail steel with embedded carbon intensity beginning in 2026, prompting procurement teams to reconsider sourcing geography, material certification, and lifecycle carbon accounting. The full study translates these dynamics into actionable procurement implications, linking regulatory deadlines, material pricing trends, and sustainability requirements to real-world sourcing and specification decisions.
What the Study Delivers for Strategic Decision-Makers
This research is built for executives, procurement directors, engineering leads, and competitive intelligence teams who require more than headline figures. The report integrates revenue forecasts, historical baselines, segmentation architecture, concentration metrics, and company-level profiling into a cohesive market operating picture. Readers will gain access to component-level demand mapping, train-type revenue correlations, regional consumption structures, and supplier capability comparisons, all organised to support scenario planning and internal alignment. The study also captures recent corporate developments that matter for sourcing strategy, including automation platform introductions, acquisition-driven capability expansion, standards-based certification milestones, major contract awards, and joint development agreements that signal localisation trends. By connecting these events to broader market structure, the report helps teams evaluate not just where revenue is heading, but who is best positioned to capture it and under what procurement conditions.
Conclusion: Why This Intelligence Matters for 2026 and Beyond
The worldwide rail components market is moving through a period where technical compliance, material economics, regional procurement rhythms, and competitive consolidation all influence winning strategy. For organisations planning fleet investments, component sourcing, platform specification, or market expansion, the difference between reactive and proactive decision-making lies in the quality of the underlying intelligence. Our Worldwide Rail Components Market study provides that foundation, combining verified market sizing, structured segmentation, competitive profiling, and regulatory context into a decision-ready format. To access the complete dataset, detailed segmentation breakdowns, and full company-level analysis, we invite readers to visit the source page and download the full report. In a market defined by long asset lifecycles and fast-moving specification requirements, timely intelligence is not an accessory to strategy; it is the basis of it.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cephalosporin Intermediates Market Projected to Reach USD 567 Million by 2032 at 5.4% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence Report: Navigating the 2026-2032 Cephalosporin Intermediates GCLE Market
The global pharmaceutical supply chain stands at a critical inflection point. As we move beyond the volatility of the early 2020s, the demand for essential antibiotic intermediates has stabilized into a trajectory of steady, calculated growth. For stakeholders in the pharmaceutical manufacturing sector, understanding the nuances of the Cephalosporin Intermediates GCLE Market is no longer optional; it is a prerequisite for resilient strategic planning. This article serves as an executive preview of our latest comprehensive market research, designed to equip leadership teams with the foresight needed to navigate the forecasting period of 2026 through 2032.
Our analysis indicates that the market is poised for expansion, driven by persistent healthcare demands and evolving manufacturing dynamics. However, surface-level growth figures often mask the complex interplay of raw material dependencies, regional concentration risks, and competitive maneuvering that define actual profitability. This report dissects those layers, offering a granular view of where value is created and where vulnerabilities lie.
Market Trajectory and Historical Context
The foundation of any strategic forecast lies in a robust understanding of historical performance. Our research tracks the market revenue from 2020 through the base year of 2025, providing a five-year historical lens against which future projections are calibrated. The data reveals a market that has demonstrated resilience despite global logistical disruptions. Starting from a valuation of approximately 312.45 Million USD in 2020, the sector climbed to 392.36 Million USD by 2025. This upward trend underscores the inelastic demand for cephalosporin antibiotics, which remain a cornerstone of global infectious disease treatment protocols.
Cephalosporin Market
Looking forward, our forecast models project a consistent Compound Annual Growth Rate (CAGR) of 5.4 percent over the forecast period. By 2032, the market is expected to reach a valuation of 566.97 Million USD. While these macro figures suggest a healthy environment, the strategic value for decision-makers lies in understanding the velocity and sustainability of this growth. A 5.4 percent CAGR implies a maturing market where share gain becomes increasingly difficult, shifting the focus from pure volume expansion to efficiency, quality differentiation, and supply chain security. The transition from the historical period to the forecast period marks a shift from recovery to optimization, requiring firms to adapt their capital allocation strategies accordingly.
Cephalosporin Intermediates GCLE Market
Operational Deep Dive: Report Contents and Methodology
To support high-stakes decision-making, this research report moves beyond top-line estimates. It is structured to provide actionable intelligence across several critical dimensions. The methodology integrates primary interviews with industry participants and secondary research from regulatory filings, trade analyses, and technical literature. The following components define the scope of our operational analysis:
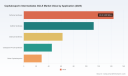
- Segmentation by Product Grade: The market is bifurcated into High Purity Grade, defined as above 99 percent, and Standard Grade, typically at 98 percent. The report analyzes the revenue contribution and strategic importance of each grade, highlighting how purity specifications influence downstream API manufacturing costs and regulatory compliance.
- Application-Specific Demand: We examine the consumption patterns across key synthesis pathways, including Cefixime, Cefdinir, Cefprozil, and Cefcapene Pivoxil. Understanding the specific demand drivers for each antibiotic synthesis route allows manufacturers to align production capacities with the most lucrative therapeutic segments.
- Regional Distribution Analysis: The study maps revenue flows across major geographical zones. While Asia Pacific remains a dominant force in volume, the report details the strategic nuances of Europe, North America, Latin America, and the Mideast and Africa, focusing on import dependencies and local manufacturing capabilities.
- Supply Chain Risk Assessment: A dedicated section evaluates the vulnerabilities in the raw material supply chain, specifically focusing on the procurement of key precursors and the impact of logistical factors on export expenses.
This structure ensures that readers do not merely see the size of the pie, but understand the ingredients, the bakers, and the distribution channels. For procurement officers and supply chain managers, the segmentation data offers a blueprint for negotiating contracts and securing supply lines. For strategic planners, the regional analysis highlights where capacity expansion might yield the highest return on investment relative to regulatory environments.
Competitive Landscape and Key Players
Market concentration is a vital indicator of competitive intensity and pricing power. Our analysis identifies a moderately concentrated market structure, where the top three players hold a significant portion of the revenue share, and the top five entities command a majority of the market. This concentration suggests that while there is room for new entrants, established players benefit from economies of scale and established supply chain relationships, particularly regarding critical raw materials.
The competitive field is characterized by specialized manufacturers who have invested heavily in the specific chemical synthesis routes required for GCLE production. Key companies shaping the landscape include:
- Otsuka Chemical Co., Ltd.: Headquartered in Osaka, Japan, this firm is a primary developer and manufacturer of GCLE. They operate dedicated production facilities, including a plant in India, positioning them as a critical link in the β-lactam intermediate supply chain. Their long-standing expertise makes them a benchmark for quality and technical capability.
- CSPC Cenway Tianjin Pharmaceuticals Co., Ltd. and Tianjin Gencom Pharmaceutical Co., Ltd.: Based in Tianjin, China, these entities are active suppliers of GCLE intermediates for cephalosporin API production. Their presence underscores the significance of the Tianjin region as a hub for pharmaceutical intermediates.
- Tianjin Jinkang, Ningbo Renjian Pharmaceuticals, Shandong Ruiying Pharmaceutical Group, Jiangsu Haici Biopharmaceuticals, and Xindi Bio: These listed global manufacturers represent a broad swath of production capacity across China. Their involvement in the GCLE market highlights the competitive pressure on pricing and the importance of scale in securing raw material contracts.
- Virchow Group / Virchow Petrochemicals Private Limited: Operating out of Telangana, India, this group manufactures and supplies GCLE for cephalosporin intermediates. Their presence adds a layer of diversification to the supply base outside of China, which is strategically relevant for buyers seeking to mitigate geographic concentration risk.
- Otsuka Chemical (India) Private Limited: Located in Haryana, this entity serves as a manufacturing plant focused on GCLE production, extending the Japanese parent company's reach into the Indian market, which is a key production base for export-oriented cefixime.
The presence of both Japanese technology leaders and large-scale Chinese manufacturers creates a dynamic competitive environment. Buyers must navigate the trade-offs between technical precision, cost efficiency, and supply security. The report provides detailed profiles on these entities, analyzing their production capacities, strategic positioning, and potential vulnerabilities.
Critical Market Dynamics and Constraints
Strategic decisions cannot be made in a vacuum. The GCLE market is subject to specific structural constraints and regulatory dynamics that significantly influence margin potential and supply reliability. Our research highlights several critical factors that industry leaders must monitor closely during the 2026-2032 period.
Raw Material Dependency and Penicillin-G: A fundamental constraint in GCLE production is the reliance on Penicillin-G as the key raw material. Industry data indicates that this precursor is entirely procured from China with no alternative sources currently available at scale. This creates a single-point-of-failure risk in the supply chain. Historical technical literature notes that domestic Chinese processes have faced challenges regarding high costs and quality issues in the past, leading to periods of continued reliance on imports in certain contexts. This dependency means that any disruption in the Penicillin-G supply chain directly impacts GCLE availability and pricing.
Regulatory Schemes and Export Orientation: Regulatory frameworks play a pivotal role in shaping market flows, particularly in India. Advanced authorization schemes have been implemented that allow GCLE suppliers to import Penicillin-G without minimum import price restrictions for export-oriented cefixime production. This regulatory nuance is crucial for manufacturers operating in India, as it affects the landed cost of raw materials and the competitiveness of the final exported product. Understanding these regulatory levers is essential for cost modeling and margin protection.
Logistical Factors and Regional Dominance: China dominates the export of cephalosporin API and intermediates. However, this dominance is not without friction. Logistical factors such as high international shipping costs and container shortages have historically affected export expenses. While supply chains have adapted, the potential for renewed logistical volatility remains a risk factor that must be priced into long-term contracts. The report analyzes how these logistical realities interact with regional market sizes to determine true net revenue potential for exporters versus domestic consumers.
Strategic Implications for 2026 and Beyond
As we enter the forecast period, the strategic imperative shifts from navigating crisis to managing growth amidst constraints. The projected growth from 397.57 Million USD in 2026 to nearly 567 Million USD by 2032 offers opportunity, but realizing this value requires sophisticated management of the underlying dynamics.
For procurement leaders, the concentration of raw material sourcing in China necessitates dual-sourcing strategies where possible, or stronger contractual safeguards with existing suppliers. For production planners, the distinction between High Purity and Standard Grade segments offers a pathway to margin improvement, as high-purity grades often command premium pricing in regulated markets. For executives evaluating market entry or expansion, the regional concentration suggests that proximity to key API manufacturing hubs in Asia Pacific may offer logistical advantages, though regulatory access in North America and Europe remains a key value driver.
Furthermore, the competitive landscape indicates that consolidation may continue as larger players leverage their scale to secure raw material advantages. Smaller players may need to find niches in specific application segments, such as Cefcapene Pivoxil Synthesis, where volume requirements are lower but specialization is higher. The interplay between the top five companies and the broader field of listed manufacturers will define price stability and innovation rates in the coming years.
Conclusion: The Value of Precision Intelligence
In a market defined by specific technical requirements, raw material dependencies, and regional regulatory nuances, general market intelligence is insufficient. Success in the Cephalosporin Intermediates GCLE Market during the 2026-2032 period will belong to those who understand the granular details of supply chain vulnerabilities, competitive capabilities, and segmentation dynamics.
This report provides the framework for that understanding. It bridges the gap between high-level market sizing and the operational realities of manufacturing and procurement. However, the full depth of the data, including precise revenue splits by region and application, detailed company profiles, and specific risk mitigation strategies, is contained within the full research document. For organizations committed to securing their supply chains and optimizing their market position, accessing the complete intelligence is the next logical step.
We invite stakeholders to review the full report to leverage these insights for their 2026 strategic planning cycles. The data presented here is the foundation; the complete analysis is the tool required to build a resilient future in the global pharmaceutical intermediates market.
For detailed analysis of this topic, please visit the official page: Cephalosporin Intermediates GCLE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
5.4% CAGR: Worldwide Vorinostat Market Reaches $312.42 Million by 2032
By pmarketresearch, 2026-09-16
Strategic Horizons in the Worldwide Vorinostat Market: A 2026 Perspective
The global oncology therapeutics landscape is undergoing a period of structural transition, driven by shifting patent regimes, expanding generic footprints, and evolving clinical guidelines. Within this environment, vorinostat remains a foundational histone deacetylase inhibitor, anchoring both historical treatment paradigms and emerging research applications across hematologic and solid tumor domains. As corporate planners, procurement leaders, and R&D strategists look toward 2026 and beyond, understanding the trajectory of this specialized market requires more than headline figures. It demands a disciplined examination of competitive positioning, regulatory tailwinds, manufacturing economics, and the subtle interplay between branded legacy products and cost-optimized alternatives. Our latest Worldwide Vorinostat Market study is designed to deliver precisely that operational intelligence, equipping decision-makers with the analytical rigor needed to navigate a market defined by steady expansion and intensifying portfolio competition.
This introduction previews the strategic architecture of the full report, highlighting the analytical dimensions that matter most for enterprise planning in 2026. Rather than offering surface-level volume snapshots, the publication dissects the forces shaping demand elasticity, pricing friction, supply-chain resilience, and therapeutic substitution patterns. The objective is clear: provide a reliable foundation for capacity allocation, market-entry sequencing, partnership evaluation, and portfolio prioritization in a therapeutic area where clinical advocacy, reimbursement alignment, and generic penetration converge.
The Macro Trajectory: A Verified Expansion Curve
From a strategic standpoint, the most immediate takeaway for planners is the consistency of the market’s upward momentum. Historical tracking from 2020 through 2025 demonstrates a resilient revenue arc that has weathered supply disruptions, regulatory recalibrations, and shifting procurement preferences. Starting from a baseline of approximately 172.5 million USD in 2020, the market progressed through year-over-year gains that reflect sustained utilization in cutaneous T-cell lymphoma management and incremental absorption by adjacent oncology research channels. By 2025, the recorded revenue reached roughly 216.2 million USD, establishing a credible platform for the forecast window.
The projection period spanning 2026 through 2032 extends this trajectory with measured confidence. The forecast anticipates growth advancing toward 228.99 million USD in the immediate outlook year and continuing upward to approximately 312.42 million USD by the close of the decade. This path corresponds to a compound annual growth rate of 5.4 percent, a pace that signals durable, rather than speculative, demand creation. For enterprise strategists, the implication is twofold. First, the expansion is robust enough to justify sustained investment in distribution infrastructure, clinical support programs, and market access initiatives. Second, the moderate growth rate underscores the importance of share capture, formulation differentiation, and pricing strategy, as incremental gains will likely be contested among established manufacturers and emerging generic suppliers rather than generated solely by volume expansion.
Strategic readers will recognize that a mid-single-digit CAGR in a niche oncology segment carries distinct planning implications. It invites disciplined resource deployment rather than aggressive overexpansion. It also rewards early visibility into regional procurement cycles, formulary inclusion timelines, and therapeutic interchange dynamics. The full report translates these macro signals into actionable frameworks, enabling teams to align capacity commitments with realistic demand windows and to calibrate competitive responses ahead of product-cycle inflection points.
Segment Architecture and the Logic of Demand Distribution
A market with a specialized therapeutic anchor inevitably concentrates value along specific formulation and indication pathways. Understanding where utilization is structurally concentrated, and why, is essential for actors evaluating manufacturing priorities, labeling strategy, or commercial launch sequencing. The analysis in our study maps these structural concentrations without reducing them to simplistic proportional breakdowns. Instead, it examines the operational logic behind formulation preferences, the therapeutic rationale driving application mix, and the regional factors that shape purchasing behavior.
From a formulation perspective, the market exhibits a clear dominance pattern in capsule-based delivery relative to powder formats. This distribution reflects both clinical convenience and established prescribing habits, particularly within localized treatment protocols where oral administration aligns with patient adherence objectives and outpatient management models. At the same time, powder-related demand persists in specialized research and compounding contexts, where formulation flexibility, dosing adjustments, and investigational protocols sustain a distinct but meaningful utilization footprint. The report evaluates how these formulation splits translate into manufacturing requirements, packaging investments, and supply-chain configuration choices, allowing readers to assess the operational consequences of the current demand architecture.
By application, the market’s center of gravity clearly lies in the management of cutaneous T-cell lymphoma, a segment that draws on the drug’s long-standing regulatory history and clinical guideline recognition. The inclusion of vorinostat in authoritative oncology treatment frameworks reinforces its positioning within relapse and refractory scenarios, supporting sustained prescription continuity where alternative options may be limited. Alongside this core oncology indication, secondary demand channels in broader oncology research and HIV latency investigation contribute additional, though comparatively smaller, utilization vectors. These ancillary applications matter strategically because they connect vorinostat to innovation pipelines, academic partnerships, and exploratory trial activity that can influence future label discussions, off-label utilization norms, and cross-therapeutic R&D attention.
The regional composition of demand further shapes commercial planning. In global terms, the market reflects a distribution pattern in which certain mature markets carry disproportionate revenue weight, while emerging procurement regions contribute incremental but strategically significant volume. The study examines these geographic layers through the lens of regulatory maturity, generic availability, formulary integration, and purchasing centralization, offering planners the context needed to prioritize outreach, adapt positioning, and anticipate timing differences across markets. Rather than presenting static regional shares in isolation, the report situates each zone within its own procurement rhythm and policy environment, enabling a more practical reading of where growth will materialize and how resistance or acceleration may unfold.
Competitive Dynamics: Branded Legacy, Generic Momentum, and Strategic Response
The vorinostat competitive landscape is defined by the interaction between a historic originator and a growing roster of generic manufacturers. This structure is central to market behavior in 2026 because it directly affects pricing benchmarks, procurement negotiations, supply reliability, and portfolio positioning. Our analysis traces how these players interact across regulatory milestones, commercial launches, and global distribution footprints, giving readers a realistic view of the market’s power dynamics.
Merck & Co., Inc. remains the foundational reference point in this space as the original developer and manufacturer of Zolinza, an FDA-approved oral HDAC inhibitor indicated for cutaneous T-cell lymphoma in patients with progressive, persistent, or recurrent disease. The brand’s historical role extends beyond product supply; it also informs the clinical narrative, guideline positioning, and physician familiarity that continue to shape utilization patterns. With the composition-of-matter patent protection expiring in 2011, the market entered a structural phase in which generic entry became feasible across multiple jurisdictions. That transition did not erase the originator’s relevance, but it did introduce new competitive variables around price erosion, tender participation, and formulary segmentation.
The generic segment now includes multiple internationally active manufacturers, each pursuing distinct regional strategies and cost-centric value propositions. Accord Healthcare markets generic vorinostat capsules in regions including Europe and India for oncology applications. In October 2023, the company advanced its European footprint by launching generic vorinostat 100 mg capsules in the UK market following EMA approval. This move illustrates how regulatory clearance, combined with established distribution channels, can accelerate generic adoption in pricing-sensitive procurement environments.
Dr. Reddy's Laboratories, headquartered in Hyderabad, produces and supplies generic vorinostat for global markets with a clear focus on affordable HDAC inhibitor alternatives after patent expiry. In June 2022, the company received US FDA approval for generic vorinostat capsules in 100 mg and 400 mg presentations as AB-rated equivalents to Zolinza. This approval represents a meaningful commercial milestone because it opens access to the US procurement system, where equivalence recognition can influence institutional purchasing decisions and competitive pricing structures. The broader Indian manufacturing base also includes Hetero Drugs and Natco Pharma, both active suppliers of generic vorinostat formulations in international markets. Hetero emphasizes availability of generic formulations for CTCL treatment across export-oriented channels, while Natco underscores cost-effective oncology generics across multiple destination countries. Together, these suppliers contribute to a supply environment in which price competition, regional targeting, and manufacturing scale increasingly influence procurement outcomes.
For strategic planners, this competitive configuration raises several practical questions. Which supply partners offer the most reliable continuity for procurement programs? Where do pricing pressures intensify fastest, and what contract structures can mitigate exposure? How do branded and generic offerings coexist within hospital formularies and institutional procurement lists? The full report addresses these questions by connecting company profiles, regulatory events, and distribution behavior to market-level outcomes, allowing readers to benchmark supplier options and anticipate competitive friction before it disrupts sourcing plans.
Regulatory and Clinical Context as Market Shapers
The vorinostat market cannot be evaluated purely as a commercial volume equation because its behavior is closely tied to regulatory milestones, safety expectations, and guideline recognition. These elements structure prescribing confidence, procurement eligibility, and the practical boundaries within which manufacturers and buyers operate. Our study integrates this context directly into the market assessment so that strategic conclusions are grounded in clinical and regulatory reality rather than abstract demand modeling.
A foundational element of the market’s credibility is the 2006 accelerated approval pathway for Zolinza, which established vorinostat as a treatment option for CTCL in patients who had progressive, persistent, or recurrent disease on or following two systemic therapies. That approval created an official therapeutic anchor and, over time, reinforced the drug’s clinical familiarity. Equally important for contemporary planning is the ongoing relevance of guideline alignment. Inclusion of Zolinza in NCCN guidance for relapsed and refractory CTCL, with a category 1 recommendation for certain subtypes, strengthens formulary justification in settings where evidence hierarchy and treatment standardization matter. This type of endorsement can influence institutional purchasing preferences, particularly in structured procurement environments that weigh guideline concordance alongside price.
Worldwide Azacitidine Market
Safety considerations also shape how vorinostat is deployed in practice. The product carries black box warnings related to thromboembolism risk and QT prolongation, which require ECG monitoring and DVT prophylaxis in clinical use. From a strategic standpoint, these requirements influence hospital workflow, prescribing oversight, and the operational burden associated with therapy administration. They also affect how procurement teams evaluate supplier support services, patient management resources, and risk-mitigation materials that may accompany product supply. In mature markets especially, the effective management of safety protocols can be as important to sustained utilization as the molecule’s therapeutic efficacy.
Worldwide Vorinostat Market
Patent expiry continues to function as a structural market catalyst. With composition-of-matter protections having lapsed in 2011, the environment has shifted toward generic participation, price competition, and multi-source supply. This reality does not eliminate branded relevance, but it reframes it. Originator products now compete within a broader ecosystem where equivalence recognition, procurement consolidation, and cost control strategies determine share distribution. Understanding how these dynamics interact across jurisdictions is critical for anyone forecasting demand stability, negotiating supply terms, or planning product positioning over the 2026 to 2032 horizon.
What the Report Delivers for 2026 Decision-Making
Market research earns its value when it reduces uncertainty in real planning contexts. The Worldwide Vorinostat Market report is structured to support that objective by combining top-line market sizing with deeper operational coverage. The full publication details the historical baseline, the forecast architecture, and the segmentation logic across region, type, and application, while also translating these dimensions into planning-relevant interpretations. It examines how demand is organized, where procurement pressure is likely to intensify, and how regulatory or competitive events can alter trajectory expectations.
Beyond the quantitative spine, the report provides practical assessments of supplier behavior, approval timelines, generic entry patterns, and the procurement consequences of guideline and reimbursement environments. It addresses the market concentration profile, including the extent to which a concentrated set of participants shapes pricing and availability dynamics, and it explores the implications of that concentration for buyers seeking supply resilience. The study also contextualizes the interplay between branded legacy positioning and generic cost competition, helping teams anticipate where negotiation leverage may shift and which commercial levers are most likely to influence share outcomes.
For strategy, R&D, supply-chain, and commercial teams, the publication is designed to function as a working reference rather than a static overview. It supports capacity planning by clarifying likely demand progression, aids market-access prioritization by mapping the environments where utilization drivers are strongest, and informs partnership or sourcing decisions by highlighting supplier structures and regulatory milestones that affect reliability and cost. The full report also includes the kind of scenario-sensitive framing that enterprise planners need when preparing for multiple possible outcomes, from faster generic diffusion to slower formulary adoption in particular geographies.
Why This Study Belongs in Your 2026 Planning Cycle
In a market characterized by steady growth, established clinical use, and expanding generic participation, the strategic challenge is less about recognizing that the market exists and more about understanding how its internal architecture will evolve. The worldwide vorinostat market will continue to be shaped by the tension between therapeutic continuity, cost optimization, regulatory accommodation, and competitive supply expansion. Navigating that tension successfully requires intelligence that connects numbers to mechanisms and mechanisms to decisions.
Our study provides that linkage. It offers the macro visibility needed to set direction, the segmentation interpretation needed to prioritize effort, and the competitive and regulatory context needed to anticipate disruption. It is built to help planners avoid overreacting to isolated events while still recognizing the cumulative significance of approval milestones, generic launches, guideline reinforcement, and regional procurement trends. For organizations preparing for 2026, that combination is not optional; it is the difference between reactive positioning and deliberate strategy.
The full Worldwide Vorinostat Market report expands every dimension previewed here into a comprehensive decision-support package, with detailed coverage of market sizing, segmentation logic, competitive profiles, recent regulatory and commercial developments, and the operational implications of each factor for procurement, supply, and portfolio strategy. Readers who require precise planning inputs, supplier comparisons, and scenario-ready interpretation will find the complete study structured to support those needs directly. The report is available through our official market intelligence portal, where the full dataset, analytical commentary, and strategic frameworks can be accessed in their complete form.
For detailed analysis of this topic, please visit the official page: Worldwide Vorinostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Machine Tool Control Transformer Market to Hit $1,228.67M by 2032, 4.6% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Corporate Agenda: Unlocking Latent Growth in Machine Tool Control Transformers
Navigating Macro Realities with Precision Data
As industrial manufacturing enters a phase of structural recalibration, the machine tool control transformer segment presents a unique blend of steady demand durability and hidden operational volatility. Our Worldwide Machine Tool Control Transformer Market study, anchored in a 2025 base year with historical tracking from 2020 to 2025 and a forward-looking trajectory extending through 2032, equips executive teams with the analytical scaffolding required to make informed, forward-looking decisions in 2026. The global market reached an estimated USD 896.84 million in 2025, having weathered a brief contraction in 2024 before resuming its upward momentum. Projections place the market at approximately USD 948.61 million in 2026, cascading toward a terminal valuation of USD 1,228.67 million by 2032. This long-arc expansion is underpinned by a compound annual growth rate of 4.6 percent, a figure that belies the underlying segmentation dynamics, pricing pressures, and engineering trade-offs that will define procurement strategies, capacity planning, and partnership decisions in the near term. For leadership teams operating at the intersection of automation investment, supply chain resilience, and cost optimization, the report delivers the contextual clarity necessary to move beyond headline figures and into actionable strategy.
Worldwide Machine Tool Control Transformer Market
Why This Study Matters for 2026 Decision-Making
The 2026 operating environment is characterized by intersecting forces: rising input costs, regional competitiveness shifts, and tightening automation cycles across discrete manufacturing. Machine tool control transformers sit at a critical juncture in factory electrical architecture, converting power to safe, stabilized voltages that enable motor starters, control relays, PLCs, and instrumentation to function reliably. Because these components are embedded in both legacy equipment retrofits and next-generation CNC and assembly-line deployments, demand does not simply track macro manufacturing output; it reflects nuanced decisions around maintenance cycles, production line modernization, and the replacement of aging electromagnetic control components. Understanding how the market is evolving across phase configurations, end-user applications, and geographic jurisdictions is no longer optional. The report maps these structural drivers with a granularity that supports scenario planning, contract negotiation, and product positioning. Rather than presenting a static snapshot, the analysis contextualizes historical performance from 2020 to 2025, identifies inflection patterns that shaped the 2024 correction, and walks through the 2026 to 2032 forecast window as a series of manageable, testable hypotheses. This framing allows procurement, engineering, and commercial teams to align internal assumptions with external market behavior before committing capital or renegotiating vendor terms.
Architecture of the Report: What Practitioners Can Deploy Immediately
The study is constructed to bridge high-level market intelligence with operational relevance. It opens with a consolidated market sizing and trend narrative, then layers in segmentation analysis across phase type, end-user application, and regional distribution. A dedicated competitive landscape section profiles key participants, comparing positioning, product-family breadth, compliance orientation, and engineering specialization. The report also integrates an input-cost and regulation mapping module designed to help readers anticipate margin shifts and compliance exposure rather than react to them after the fact. Each section includes structured takeaways intended for immediate transfer into business planning workflows, including demand-cycle interpretation, sourcing strategy mapping, and product-mix evaluation. By keeping the segmentation themes distinct yet interconnected, the document enables readers to trace how a change in one dimension, for example, regional procurement norms or phase configuration preferences, reverberates through pricing, specification requirements, and aftermarket service considerations. The emphasis throughout is on decision-useful clarity: enough analytical structure to support investment and sourcing choices, without reducing the market to oversimplified averages.
Segmentation Dynamics: Where Demand Is Concentrating
The demand base for machine tool control transformers is distributed across distinct configurations and use environments, each carrying different implications for specification, volume, and value capture. Across phase architectures, single-phase units have historically commanded the larger revenue share, reflecting their prevalence in control circuits for a broad range of industrial machinery and their alignment with common step-down requirements in distributed control panels. Three-phase configurations occupy a meaningful secondary position, typically associated with higher-power control applications and more demanding production-line environments. In end-user application terms, metal cutting machine tools represent a substantial demand anchor, consistent with the precision, repeatability, and electromagnetic stability requirements of CNC and machining centers. Metal forming machine tools contribute a significant second pillar, driven by press and stamping operations where control reliability intersects with equipment uptime and operator safety. Special purpose machines round out the application landscape, encompassing specialized automation and bespoke equipment where custom voltage transformation and inrush handling become differentiators. Geographically, the market spans multiple industrial regions, each with different competitive density, local compliance expectations, and procurement rhythms. The report examines how these regional and application-pattern differences interact with pricing sensitivity, specification customization, and lead-time tolerance, enabling readers to identify where demand resilience is structural and where it is more exposed to cycle risk.
Competitive Landscape: Strategic Posture Among Core Players
The market features a diversified set of manufacturers whose strategies reflect differing priorities in product architecture, compliance positioning, customization capacity, and geographic footprint. Hammond Power Solutions stands out in North America as a significant dry-type transformer manufacturer, offering molded machine tool industrial control transformers engineered for high inrush conditions across machine tools, conveyors, robotics, and production-line equipment. Its legacy molded styles also address electromagnetic components such as relays and solenoids, reinforcing breadth across control-circuit use cases. MCI Transformer Corporation operates from the United States with a focus on catalog and custom industrial control transformers designed to deliver low, safe control voltages for motor starters, timers, and similar electromagnetic devices, emphasizing adherence to stringent industry regulations. Controlled Magnetics provides a wide custom range from 100 VA to 500 kVA, targeting stepped-down voltages for machine tool control devices while highlighting inrush handling, energy efficiency, electrical isolation, and compliance with standards such as ANSI/NEMA ST-1, UL, and CSA for factory automation and machinery. SNC Manufacturing Co., Inc., now part of Allient Inc., produces single- and three-phase control transformers with step-up and step-down capabilities across specified primary and secondary voltage ranges and 50/60 Hz operation, supported by custom engineering services for industrial control circuits. Micron Industries contributes industrial control transformer offerings, including series designed for machine tool and industrial applications. PowerVolt Group Inc. designs and produces high-efficiency, UL-listed and CSA-certified control transformers for factory automation, industrial equipment, and machine tool control panels, with an emphasis on certification readiness and efficiency. Murrelektronik, with global operations anchored in Germany, offers isolation and control transformers suited to industrial and machine tool contexts. In Asia, Lushan China produces single-phase industrial control transformers for stepped-down voltages and high inrush applications, while ZHENGXI manufactures low-voltage dry-type machine tool control transformers in the 40 VA to 2500 VA range for CNC machines, automation panels, and industrial control. CNC Electric Group also competes in the Chinese market with control transformers developed using German technology for AC 50 to 60 Hz circuits. Boardman Transformers in the UK and SolaHD in the United States complete the landscape with offerings tailored to control circuits and special mounting requirements, respectively. The study examines how these players differentiate themselves through engineering focus, compliance profiles, customization capabilities, and regional presence, and it frames the competitive dynamics in terms of potential partnership, sourcing diversification, and specification strategy.
Cost Structure and Input Dynamics: The Margin Equation Under Pressure
Transformer economics are increasingly shaped by raw material trajectories and their interaction with design choices, order volumes, and regional sourcing flexibility. Copper remains a primary input for control transformers, and its price behavior directly affects production cost structures. In early 2026, copper prices briefly exceeded USD 14,500 per tonne intraday, with mid-year forecasts averaging near USD 12,075 per metric ton for the year, reflecting supply constraints and continued demand pull from electrification. At the same time, electrical steel costs have nearly doubled since 2020, driven by supply shortfalls and rising energy expenses, reinforcing cost-pressure dynamics across transformer manufacturing. Because grain-oriented silicon steel and copper together account for a substantial share of material costs in comparable transformer categories, these movements carry direct implications for pricing, margin management, and vendor negotiations. The report translates these input conditions into practical discipline for 2026 planning, emphasizing the need to evaluate specification trade-offs, volume commitments, and alternative sourcing pathways with an understanding of how material volatility may affect delivered cost over the contract horizon. It also contextualizes these pressures within broader electrification demand trends, helping readers separate cyclical price spikes from structural input-cost shifts that may persist into the forecast window.
Regulatory Context: Navigating Exemptions with Strategic Clarity
Regulatory frameworks can significantly influence testing, certification, and compliance planning, especially for components that sit close to the boundary between industrial control and distribution equipment. Importantly, U.S. Department of Energy energy conservation standards for distribution transformers explicitly exclude machine-tool control transformers from the definition and efficiency requirements. The latest final rule, published in April 2024, sets compliance obligations for covered distribution transformers beginning April 23, 2029, leaving machine-tool control transformers outside that direct mandate. Similarly, the California 2025 Energy Code exempts machine-tool control transformers from low-voltage dry-type distribution transformer certification requirements under Title 20 Appliance Efficiency Regulations. These distinctions matter because they shape how suppliers structure product documentation, how buyers evaluate efficiency claims, and where compliance resources are best allocated. The report consolidates this regulatory landscape so that engineering, quality, and procurement teams can avoid over-applying distribution-transformer assumptions to control-transformer procurement, while still tracking future rule-making that could shift the boundary over time. For companies operating across multiple jurisdictions, this clarity supports more precise compliance roadmaps and more informed evaluation criteria for both standard and custom units.
How to Use This Intelligence: From Market Map to Execution
The study is designed to feed directly into planning cycles, sourcing reviews, and competitive positioning discussions. Readers can use the segmentation and regional analysis to pressure-test demand assumptions, identify where application-specific requirements justify specification premium, and assess where procurement strategies may benefit from supplier diversification or regional nearshoring. The competitive profiles help teams benchmark their own product or sourcing positions against the broader field, highlighting where customization capability, certification readiness, or inrush-handling performance may function as competitive differentiators. The input-cost and regulatory sections provide a basis for more robust commercial modeling, enabling earlier identification of margin-risk scenarios and more disciplined compliance planning. Throughout, the report encourages a disciplined approach: use the macro trajectory and structural segmentation to frame expectations, then layer in the operational details that determine how a market-sized opportunity becomes a realized advantage in a specific product line, region, or customer segment.
A Note on Depth, Data Access, and the Next Step
This overview is intended to signal the scope, rigor, and practical orientation of the full study while preserving the detailed segmentation tables, regional breakdowns, and company-specific competitive metrics for the complete report. The strategic value of the analysis lies not only in aggregate market direction but in the way the study connects macro sizing, application and phase dynamics, regional demand patterns, input-cost pressure, and regulatory context into a single decision framework. For organizations preparing 2026 investment, procurement, or product strategy decisions, that integrated view is the difference between reacting to market headlines and anticipating the mechanics that drive them. The complete Worldwide Machine Tool Control Transformer Market report extends this foundation with the full segmentation detail, competitive comparison depth, and forecast scenarios needed to translate intelligence into execution. We invite decision-makers to access the full report to obtain the complete datasets and analytical structure required to support confident, well-timed strategic action.
Machine Tool Bearing Market
For detailed analysis of this topic, please visit the official page: Worldwide Machine Tool Control Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saddle Chairs Market Hits $310.5M in 2025, Projected to Grow at 5.85% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Outlook: The Saddle Chairs Market Through 2032
The global saddle chairs market is entering a phase of sustained expansion, driven by converging forces in ergonomic science, hybrid work adoption, and specialized healthcare requirements. At PW Consulting, our latest market research publication dissects this trajectory from 2020 through 2032, providing enterprise decision-makers with a rigorous, forward-looking framework to navigate procurement, product development, and competitive positioning. This article outlines the strategic architecture of the study, highlights the structural forces reshaping the landscape, and demonstrates how stakeholders can translate macro momentum into actionable advantage.
Macro Trajectory and Structural Context
Historical tracking reveals a market that has consistently outpaced general furniture trends. Between 2020 and 2025, total revenue climbed from approximately $245.2 million to $310.5 million, reflecting steady multi-year compounding rather than isolated spikes. Looking ahead, our forecast period (2026–2032) projects continued growth with a compound annual growth rate of 5.85%, positioning the market to reach roughly $462.27 million by 2032. This expansion is not merely a function of unit volume; it is structurally reinforced by rising institutional procurement of posture-optimized seating, the proliferation of sit–stand workstations, and a broader shift toward active sitting paradigms in professional environments.
Importantly, the growth pathway is unevenly distributed across segments and geographies, creating distinct pockets of opportunity and risk. Our analysis isolates the drivers behind these divergences while maintaining a disciplined focus on strategic implications rather than raw enumeration. Readers seeking complete segment-level breakdowns, regional revenue splits, and application-specific sizing will find those architectures fully detailed within the full report.
Intersecting Industry Dynamics
Supply-side realities and demand-side behavior are currently recalibrating the market’s operational rhythm. On the materials front, key cushion components such as polyurethane foam experienced supply constraints in early 2026, pressuring production costs and prompting manufacturers to refine sourcing strategies and cushion engineering alternatives. Regulatory monitoring for 2025–2026 indicates that ergonomic seating products continue to operate under standard furniture safety frameworks concerning stability and material compliance, with no sector-specific recalls recorded during the window. This regulatory clarity reduces friction for international distribution but simultaneously raises the baseline expectation for quality assurance and documentation.
From a demand perspective, the persistence of hybrid work models and the accelerating pairing of saddle chairs with standing desks are reshaping office furniture purchasing criteria. Procurement teams now weigh dynamic sitting benefits alongside conventional comfort metrics, expanding the addressable use cases for saddle-style seating beyond traditional clinical settings. These behavioral shifts are reinforced by end-user awareness of circulation, lumbar support, and fatigue reduction—factors that have moved from niche ergonomic claims to mainstream procurement considerations.
Segment Architecture and Application Divergence
The market’s composition reflects specialized design philosophies tailored to distinct end environments. Product offerings bifurcate around the presence or absence of a backrest, each aligning with different posture philosophies, workspace configurations, and user preferences. In practice, the no-backrest segment appeals to users seeking maximum pelvic mobility and unencumbered movement, while backrest-equipped variants address environments where additional lumbar reinforcement is prioritized during longer duty cycles.
Application-wise, medical and dental settings continue to represent a substantial share of demand, where saddle seating is leveraged for precision work, clinician ergonomics, and patient-proximity workflows. Office and commercial environments constitute another major demand cluster, increasingly influenced by activity-based working layouts and wellness-oriented procurement policies. Industrial and personal use forms a smaller but strategically distinct segment, with requirements centered on durability, adjustability, and compatibility with technical or protected-floor environments.
Regional demand patterns similarly reflect local workplace standards, healthcare infrastructure maturity, and furniture distribution dynamics. Our study maps these geographic nuances and identifies where localized pricing, channel access, and certification requirements create differentiated competitive conditions. The full report provides exhaustive segmentation tables and geographic breakdowns, enabling teams to model region-specific revenue potential and allocation scenarios.
Competitive Landscape and Strategic Positioning
The market remains moderately concentrated, with a compact group of internationally active manufacturers commanding a meaningful share of branded supply. Our analysis profiles the leading participants shaping product standards, channel relationships, and category perception. Notable players include Salli Systems, Score BV, HÅG (Flokk), Humanscale, Bambach Saddle Seat, Treston, Branch Furniture, ProNorth Medical, and RGP Dental. These firms span multiple headquarters regions and bring differentiated value propositions ranging from split-seat designs and dynamic sitting mechanics to specialized healthcare-focused ergonomics and sustainable material sourcing.
Strategic differentiation in this space rarely hinges on a single attribute. Instead, competitors are building advantage across several axes simultaneously:
Lift Chair Market
- Design architecture that targets spinal alignment, circulation, and reduced musculoskeletal strain for prolonged professional use.
- Manufacturing and sourcing strategies that balance performance requirements with cost stability amid variable material availability.
- Segment-specific productization, particularly in dental, medical, and technical industrial applications where duty cycles and hygiene considerations shape feature decisions.
- Go-to-market execution through direct channels, distributor networks, and professional practice partnerships that reinforce category credibility.
Recent corporate activity illustrates how the competitive set is adapting to these priorities. In October 2024, ProNorth Medical introduced a saddle stool aimed at medical applications, emphasizing posture improvement, comfort, and productivity gains. Later, in September 2025, Score published content on optimal dental practice setup that positioned its saddle chair solutions within broader clinical workflow discussions. These moves reflect a broader pattern in which incumbents invest in both product refreshes and educational content to shape specification behavior among professional buyers.
Concentration metrics indicate that the top participants collectively hold meaningful but not monopolistic share, leaving room for challenger brands, regional specialists, and design-led entrants to compete on niche performance, regional service, or material innovation. Our report evaluates the strategic maneuvering space available to each tier of participant and the conditions under which share shifts are most likely to occur.
Inside the Report: What Decision-Makers Will Find
This market study is engineered for strategic application rather than passive reference. Beyond top-line sizing, the document delivers an operational toolkit for planning, investment, and risk mitigation across the forecast horizon. Core contents include:
- Historical market reconstruction (2020–2025) with revenue progression and momentum drivers across the category.
- A five-year forecast (2026–2032) anchored in a defined growth rate, with scenario considerations for demand adoption, input cost variability, and regulatory stability.
- Segment-by-segment analysis spanning type distinctions, application verticals, and regional demand profiles, with explanatory context for where growth concentrates and why.
- Competitive profiles covering headquarters location, core product philosophies, target environments, and public-facing positioning for the principal market participants.
- Recent corporate developments and content moves that signal shifting emphasis in product strategy, professional education, and end-user engagement.
- Environmental and operational factors including material supply considerations, safety standard expectations, and evolving usage habits tied to hybrid work and active sitting.
- Strategic decision support for procurement planning, product roadmap prioritization, channel strategy, and specification targeting in high-value verticals.
Throughout the study, numerical precision is paired with interpretive context so that readers can assess not just what the market is doing, but how the underlying mechanics may influence operating decisions over time. The full publication provides complete segmentation structures and granular market values that are intentionally reserved for the comprehensive report experience.
Why This Research Matters for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to this market face a narrow window to align strategy with the next phase of category maturation. Procurement teams must weigh evolving ergonomic expectations against cost volatility and supply chain responsiveness. Product leaders need clarity on which posture features, adjustability options, and material choices will best match the demands of medical, office, and industrial use cases. Executives evaluating market entry, expansion, or partnerships require a realistic view of concentration dynamics, regional opportunity, and the specification behaviors that determine professional adoption.
Our research is designed to support these decisions with a single, coherent view of market size, growth path, segmentation logic, and competitive behavior. It connects macro momentum to operational reality by explaining where demand is structurally strongest, how leading firms are positioning themselves, and which external factors—materials, standards, and work habits—are likely to influence execution over the forecast period. The result is a planning foundation that can inform everything from volume commitments and channel investments to feature prioritization and vertical-specific go-to-market tactics.
Conclusion: From Macro Momentum to Advantaged Execution
The saddle chairs market offers a distinctive combination of ergonomic relevance, application specificity, and steady long-term growth. The trajectory from 2020 through 2032 signals a category that is expanding on the strength of specialized utility rather than broad commodity replacement. For firms seeking to participate in this expansion, the strategic question is not simply whether demand is rising, but where value is being created, how incumbents are defending their positions, and which operational variables will determine execution quality in the years ahead.
PW Consulting’s full market research publication delivers the depth required to answer those questions with confidence. It integrates historical context, forward forecast, competitive profiles, and environmental dynamics into one structured intelligence package. Readers who require complete segmentation figures, regional revenue distributions, and exhaustive market breakdowns will find those elements comprehensively presented in the full report. Access the complete study to translate market momentum into a tailored, execution-ready strategy for 2026 and beyond.
Saddle Chairs Market
For detailed analysis of this topic, please visit the official page: Saddle Chairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glufosinate Ammonium Market Hits $621.88M in 2025, 14.02% CAGR to $1.56B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence in a High-Concentration Herbicide Market: Why the 2026–2032 Outlook Matters Now
The global high concentration glufosinate ammonium market is entering a phase of structural acceleration that will separate the prepared from the reactive. From a base year of 2025, the sector is projected to expand from a 2020 baseline of USD 310.5 million to USD 1556.11 million by 2032, reflecting a compound annual growth rate of 14.02 percent over the 2026–2032 forecast period. This trajectory is not merely a function of volume growth. It represents the intersection of trait-driven demand, regulatory recalibration, geographic supply realignments, and a market structure in which competitive intensity is heavily concentrated. For executives evaluating procurement strategies, formulation roadmaps, and regional entry or exit decisions, the period ahead will reward those who can decode the market’s layered dynamics well before they become visible in quarterly results.
Our newly released Worldwide High Concentration Glufosinate Ammonium Market research translates these signals into operational clarity. The study is designed as a decision-grade platform, not a static snapshot. It maps the market’s evolution from 2020 through 2025, then projects forward across 2026 to 2032, with a particular emphasis on where concentration, pricing power, and regulatory exposure will shape margin profiles. In this preview, we outline the strategic contours of the report and explain why the coming years will demand a sharper reading of the market than historical trend extrapolation can provide.
A Market Defined by Concentrated Supply and Expanding Demand Architecture
High concentration glufosinate ammonium is increasingly positioned as a strategic herbicide active within the broader crop protection portfolio. Its growth appeal stems from its role in managing weed resistance, supporting trait-integrated cropping systems, and serving non-agricultural and specialty applications. Yet what makes this market especially consequential for 2026 decision-making is the way demand is distributed across use cases and geographies, while supply remains tightly held among a limited set of producers.
The overall revenue expansion observed over the historical window underscores a durable upward path rather than a temporary cycle. Revenue scaled from the 2020 level of USD 310.5 million to USD 621.88 million in 2025, and the forecast continues that ascent, reaching USD 706.6 million in 2026, USD 1188.37 million in 2030, and USD 1556.11 million in 2032. This slope implies that the market will not simply continue to grow; it will accelerate in strategic importance as integrated cropping systems and resistance management practices become more entrenched in major production regions.
That said, aggregate growth can obscure the operational realities that determine who captures value. The report therefore examines the market through a concentration lens, recognizing that competitive behavior, pricing, and availability are shaped by a limited number of dominant participants. With a CR3 of 58.4 percent and a CR5 of 72.15 percent, the landscape is not fragmented in the conventional sense. This degree of concentration creates both opportunity and vulnerability: it enables coordinated product stewardship, brand-led differentiation, and technical formulation leadership, but it also heightens the impact of capacity decisions, trade policy shifts, and regulatory actions on downstream users.
Worldwide High Concentration Glufosinate Ammonium Market
Glufosinate Ammonium Market
The 2026 Decision Window: Why Timing Is Now a Strategic Variable
The 2026–2032 outlook is particularly instructive because it captures the market at the point where several structural forces converge. First, trait-validated usage is expected to remain a core demand anchor. Glufosinate ammonium has gained durable relevance in systems where selective weed control must complement resistant crop platforms, especially in broad-acre crops such as soybean, corn, cotton, and canola. As resistance pressure increases, herbicide programs that depend on multiple modes of action are more likely to be standardized, and glufosinate’s role as a broad-spectrum partner is strengthened in that context.
Second, the report’s forecast period is shaped by policy and regulatory developments that directly influence sourcing economics and competitive positioning. In the near term, Chinese export incentives for glufosinate ammonium technical have been removed, effective April 1, 2026. This policy change altered immediate price dynamics and encouraged suppliers to re-evaluate channel strategies, contract structures, and destination-market focus. At roughly the same time, technical quotations have moved into a tighter supply posture, reflecting constraints on effective availability and upstream cost pressures. These conditions make it increasingly difficult to treat technical pricing as a stable input variable. Instead, procurement and planning functions need a forward-looking framework that accounts for volatility rather than assuming continuity.
Third, regulatory calibration continues to determine which use patterns can scale and which require reformulation or regional adaptation. Recent regulatory actions in the United States, including updated tolerance levels for glufosinate residues in rice and tea, and the registration of L-glufosinate as a distinct active ingredient for use in major crops, create new commercial pathways while also redefining compliance obligations. The emergence of L-glufosinate, or glufosinate-P, adds another layer of strategic complexity because it blurs the line between commodity active supply and differentiated technical offerings. Companies that can align product architecture with these regulatory and trait-related shifts will be better positioned to defend margin and expand share.
Inside the Report: What Decision-Makers Can Put to Work Immediately
Our Worldwide High Concentration Glufosinate Ammonium Market study is built as an operational reference for market entry, competitive response, supply chain design, and portfolio planning. Instead of offering only top-line projections, the report decomposes the market into the dimensions that determine where dollars are made and where exposure accumulates. The following elements are covered in detail:
- A full historical reconstruction from 2020 through 2025, paired with a forward forecast from 2026 to 2032, enabling users to compare realized performance with projected momentum and to test scenario assumptions against a consistent baseline.
- Segment-level mapping across region, product type, and application, so that buyers and suppliers can see where high concentration glufosinate ammonium is being deployed, where demand is most concentrated, and where growth is likely to be disproportionately driven by specific end uses and geographies.
- Competitive landscape analysis focused on the companies that shape pricing, availability, and product direction, with attention to their product families, geographic footprints, and strategic positioning in both technical and formulated supply chains.
- Market concentration assessment, including the implications of a highly consolidated supply structure for negotiation power, supply security, and new entry difficulty.
- Recent industry developments, from policy changes affecting trade economics to regulatory decisions that influence residue tolerances and active-ingredient registrations, with an emphasis on what these events mean for sourcing and product strategy.
- Supply-side context, including production capacity trends, conversion dynamics, and the relationship between technical availability and formulated product access across markets.
- Actionable diagnostic frameworks that enable executives to link market structure to commercial outcomes, such as pricing behavior, regional demand elasticity, and the strategic value of trait-compatible offers.
The report is structured so that strategy, R&D, procurement, and commercial teams can work from the same evidence base. Rather than isolating data into separate appendices, the analysis connects market size, segmentation patterns, and regulatory events to the practical questions that managers face: where to invest, what to source, which partnerships matter, and how to prepare for volatility in a market where effective supply and trade conditions can shift quickly.
Competitive Landscape: Who Shapes the Market and How
In a market with this level of concentration, competitive intelligence cannot be reduced to revenue comparison alone. The players that matter are those with the ability to influence technical supply, formulation quality, trait-linked commercialization, and channel reach. The report profiles the companies whose strategic conduct is most consequential to the high concentration glufosinate ammonium market.
BASF SE remains a central force in the global landscape, with deep-rooted herbicide brands and a strong emphasis on both broad-spectrum weed control and trait-compatible solutions. Its product heritage and integrated capabilities give it a prominent role in shaping how glufosinate ammonium is positioned across agricultural and non-crop applications. Bayer AG, through its crop science division, brings a similarly strong global footprint and an emphasis on high-efficacy formulations tied to resistance management in major row crops. The company’s presentation of glufosinate-based offerings alongside trait-integrated systems illustrates how the active has moved from a standalone chemistry story to part of a broader agronomic package.
On the supply side, several Chinese manufacturers are especially important because they combine technical-grade production scale with growing export presence. Lier Chemical Co., Ltd. and Zhejiang YongNong Chemical Co., Ltd. stand out as major producers of technical and high-concentration formulations, with capacity and commercial strategies that affect global availability. Jiangsu Huangma Agrochemicals Co., Ltd. also contributes actively to domestic and export supply through compliant technical and formulated products. Shandong Weifang Rainbow Chemical Co., Ltd. and Zhejiang Wynca Chemical Industry Group further add to the technical-grade production base, reinforcing the importance of China as a center of manufacturing gravity for this active.
International formulators and distributors also play a decisive role in translating technical supply into regional market access. UPL Limited operates global generic formulator and marketer channels that broaden distribution reach across multiple geographies. Adama Agricultural Solutions Ltd. focuses on tailored, more sustainable crop protection solutions and regionalized formulation strategies. Nufarm Limited supplies glufosinate-based products into agricultural, turf, and ornamental applications, with a market emphasis that includes Australia, New Zealand, and Europe. FMC Corporation participates through its broader crop protection portfolio, reinforcing the active’s relevance across multiple weed control contexts.
What ties these companies together in the report’s analysis is not merely their presence, but the way their strategies influence market outcomes. Recent developments highlight how fast this can happen. Lier Chemical’s 2025 financial forecast pointed to a substantial increase in net profit associated with L-glufosinate scale-up and strengthened multinational partnerships, signaling that technical differentiation and partnership architecture can generate disproportionate benefits when aligned with demand momentum. At the same time, policy changes such as the elimination of the export tax rebate in China have created immediate price and supply chain responses that ripple through global sourcing. Meanwhile, regulatory updates in the United States and trade measures in other markets continue to reshape the boundaries within which competitors can scale.
Market Dynamics That Will Define 2026 and Beyond
Several dynamic forces will determine whether companies navigate this market with advantage or expose themselves to avoidable risk. One is the relationship between technical availability and formulation access. Capacity growth in technical-grade production, including the scale of national technical capacity reached in China by late 2025, has expanded the underlying supply base, but that does not automatically translate into stable pricing or predictable distribution. Tight order schedules and upward price pressure in technical quotations show that effective supply can remain constrained even when headline capacity appears substantial. For buyers, this means that contract design, inventory strategy, and supplier selection must account for both physical availability and the commercial behavior of concentrated producers.
Another dynamic is the interaction between trait systems and herbicide demand. As resistance management becomes more central to cropping economics, glufosinate ammonium’s broad-spectrum utility supports its continued presence in integrated programs. However, the strategic value of the active increasingly depends on whether it is positioned as a standard chemical input or as part of a trait-compatible, high-efficacy package. Companies that can align product strength, formulation quality, and agronomic messaging with the needs of resistance-prone systems are more likely to capture premium positioning.
Trade and regulatory conditions add another layer of complexity. The removal of export tax incentives for certain glufosinate technicals has reshaped the economics of international supply, affecting price discovery and destination-market competitiveness. At the same time, minimum import price conditions and residue tolerance decisions influence which materials can enter specific channels and at what cost. The registration of L-glufosinate as a new active ingredient introduces both opportunity and differentiation risk. It opens space for more targeted product narratives while also raising expectations around technical purity, compliance, and crop-specific performance.
Taken together, these dynamics point to a market in which reactive planning is costly. The companies that perform best through 2032 will likely be those that treat volatility as a design parameter rather than a disruption to be absorbed after the fact. That means stress-testing sourcing strategies against regulatory change, monitoring how concentrated suppliers adjust output and pricing, and evaluating where formulation, registration, and partnership decisions can create defensible advantage.
What This Report Enables: From Intelligence to Execution
The value of this study lies in its ability to convert market structure into commercial choices. For procurement and supply chain leaders, the report provides a framework for understanding where technical price risk originates, how concentration affects negotiation leverage, and which supply relationships matter most under shifting trade and production conditions. For commercial and portfolio teams, it clarifies where demand is developing most strongly across applications and geographies, and where trait-linked use cases create more durable demand than price-sensitive volume plays. For strategy and corporate development functions, it maps the competitive field in a way that exposes not only who is present, but how value is created and defended through formulation, registration, and channel strategy.
Equally important, the report helps organizations prioritize what to watch. In a market where policy actions, tolerance updates, capacity expansions, and active-ingredient registrations can alter competitive conditions quickly, the difference between strong and weak positioning often comes down to early awareness and the ability to convert that awareness into action. By connecting historical performance, forward forecasts, competitive behavior, and recent market events, the study gives decision-makers a shared basis for scenario planning, sourcing strategy, and product roadmap decisions.
The Worldwide High Concentration Glufosinate Ammonium Market research is intended to support that process from the first wave of strategic review through ongoing execution. The macro trajectory suggests a market with strong growth momentum, but the operational reality is more nuanced. Concentration, trade policy, regulatory calibration, and trait-driven demand will determine how that growth is distributed. Understanding those forces now is the difference between following the market and shaping your position within it.
Conclusion: Why the 2026–2032 Outlook Deserves Disciplined Attention
The worldwide high concentration glufosinate ammonium market is moving into a period where growth is not the only question that matters. The more consequential issues are where value will accrue, which supply relationships will hold under pressure, how regulatory and trade shifts will alter cost structures, and which competitive strategies will be durable as technical and formulated markets continue to evolve. With revenue projected to expand from USD 706.6 million in 2026 to USD 1556.11 million in 2032 at a 14.02 percent CAGR, the stakes are high, and the margin for delayed action is shrinking.
This report is designed to help leaders act with precision. It provides the segmentation structure, competitive context, and market dynamics needed to make sourcing, product, and geographic decisions with greater confidence. For organizations that need to move beyond surface-level market descriptions and into the logic of pricing, concentration, regulation, and demand architecture, the full study offers the depth required to support 2026 planning and the years that follow.
For detailed analysis of this topic, please visit the official page: Worldwide High Concentration Glufosinate Ammonium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com