

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
5.4% CAGR: Worldwide Vorinostat Market Reaches $312.42 Million by 2032

Strategic Horizons in the Worldwide Vorinostat Market: A 2026 Perspective
The global oncology therapeutics landscape is undergoing a period of structural transition, driven by shifting patent regimes, expanding generic footprints, and evolving clinical guidelines. Within this environment, vorinostat remains a foundational histone deacetylase inhibitor, anchoring both historical treatment paradigms and emerging research applications across hematologic and solid tumor domains. As corporate planners, procurement leaders, and R&D strategists look toward 2026 and beyond, understanding the trajectory of this specialized market requires more than headline figures. It demands a disciplined examination of competitive positioning, regulatory tailwinds, manufacturing economics, and the subtle interplay between branded legacy products and cost-optimized alternatives. Our latest Worldwide Vorinostat Market study is designed to deliver precisely that operational intelligence, equipping decision-makers with the analytical rigor needed to navigate a market defined by steady expansion and intensifying portfolio competition.
This introduction previews the strategic architecture of the full report, highlighting the analytical dimensions that matter most for enterprise planning in 2026. Rather than offering surface-level volume snapshots, the publication dissects the forces shaping demand elasticity, pricing friction, supply-chain resilience, and therapeutic substitution patterns. The objective is clear: provide a reliable foundation for capacity allocation, market-entry sequencing, partnership evaluation, and portfolio prioritization in a therapeutic area where clinical advocacy, reimbursement alignment, and generic penetration converge.
The Macro Trajectory: A Verified Expansion Curve
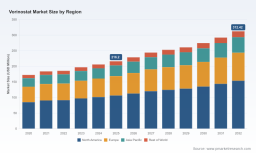
From a strategic standpoint, the most immediate takeaway for planners is the consistency of the market’s upward momentum. Historical tracking from 2020 through 2025 demonstrates a resilient revenue arc that has weathered supply disruptions, regulatory recalibrations, and shifting procurement preferences. Starting from a baseline of approximately 172.5 million USD in 2020, the market progressed through year-over-year gains that reflect sustained utilization in cutaneous T-cell lymphoma management and incremental absorption by adjacent oncology research channels. By 2025, the recorded revenue reached roughly 216.2 million USD, establishing a credible platform for the forecast window.
The projection period spanning 2026 through 2032 extends this trajectory with measured confidence. The forecast anticipates growth advancing toward 228.99 million USD in the immediate outlook year and continuing upward to approximately 312.42 million USD by the close of the decade. This path corresponds to a compound annual growth rate of 5.4 percent, a pace that signals durable, rather than speculative, demand creation. For enterprise strategists, the implication is twofold. First, the expansion is robust enough to justify sustained investment in distribution infrastructure, clinical support programs, and market access initiatives. Second, the moderate growth rate underscores the importance of share capture, formulation differentiation, and pricing strategy, as incremental gains will likely be contested among established manufacturers and emerging generic suppliers rather than generated solely by volume expansion.
Strategic readers will recognize that a mid-single-digit CAGR in a niche oncology segment carries distinct planning implications. It invites disciplined resource deployment rather than aggressive overexpansion. It also rewards early visibility into regional procurement cycles, formulary inclusion timelines, and therapeutic interchange dynamics. The full report translates these macro signals into actionable frameworks, enabling teams to align capacity commitments with realistic demand windows and to calibrate competitive responses ahead of product-cycle inflection points.
Segment Architecture and the Logic of Demand Distribution
A market with a specialized therapeutic anchor inevitably concentrates value along specific formulation and indication pathways. Understanding where utilization is structurally concentrated, and why, is essential for actors evaluating manufacturing priorities, labeling strategy, or commercial launch sequencing. The analysis in our study maps these structural concentrations without reducing them to simplistic proportional breakdowns. Instead, it examines the operational logic behind formulation preferences, the therapeutic rationale driving application mix, and the regional factors that shape purchasing behavior.
From a formulation perspective, the market exhibits a clear dominance pattern in capsule-based delivery relative to powder formats. This distribution reflects both clinical convenience and established prescribing habits, particularly within localized treatment protocols where oral administration aligns with patient adherence objectives and outpatient management models. At the same time, powder-related demand persists in specialized research and compounding contexts, where formulation flexibility, dosing adjustments, and investigational protocols sustain a distinct but meaningful utilization footprint. The report evaluates how these formulation splits translate into manufacturing requirements, packaging investments, and supply-chain configuration choices, allowing readers to assess the operational consequences of the current demand architecture.
By application, the market’s center of gravity clearly lies in the management of cutaneous T-cell lymphoma, a segment that draws on the drug’s long-standing regulatory history and clinical guideline recognition. The inclusion of vorinostat in authoritative oncology treatment frameworks reinforces its positioning within relapse and refractory scenarios, supporting sustained prescription continuity where alternative options may be limited. Alongside this core oncology indication, secondary demand channels in broader oncology research and HIV latency investigation contribute additional, though comparatively smaller, utilization vectors. These ancillary applications matter strategically because they connect vorinostat to innovation pipelines, academic partnerships, and exploratory trial activity that can influence future label discussions, off-label utilization norms, and cross-therapeutic R&D attention.
The regional composition of demand further shapes commercial planning. In global terms, the market reflects a distribution pattern in which certain mature markets carry disproportionate revenue weight, while emerging procurement regions contribute incremental but strategically significant volume. The study examines these geographic layers through the lens of regulatory maturity, generic availability, formulary integration, and purchasing centralization, offering planners the context needed to prioritize outreach, adapt positioning, and anticipate timing differences across markets. Rather than presenting static regional shares in isolation, the report situates each zone within its own procurement rhythm and policy environment, enabling a more practical reading of where growth will materialize and how resistance or acceleration may unfold.
Competitive Dynamics: Branded Legacy, Generic Momentum, and Strategic Response
The vorinostat competitive landscape is defined by the interaction between a historic originator and a growing roster of generic manufacturers. This structure is central to market behavior in 2026 because it directly affects pricing benchmarks, procurement negotiations, supply reliability, and portfolio positioning. Our analysis traces how these players interact across regulatory milestones, commercial launches, and global distribution footprints, giving readers a realistic view of the market’s power dynamics.
Merck & Co., Inc. remains the foundational reference point in this space as the original developer and manufacturer of Zolinza, an FDA-approved oral HDAC inhibitor indicated for cutaneous T-cell lymphoma in patients with progressive, persistent, or recurrent disease. The brand’s historical role extends beyond product supply; it also informs the clinical narrative, guideline positioning, and physician familiarity that continue to shape utilization patterns. With the composition-of-matter patent protection expiring in 2011, the market entered a structural phase in which generic entry became feasible across multiple jurisdictions. That transition did not erase the originator’s relevance, but it did introduce new competitive variables around price erosion, tender participation, and formulary segmentation.
The generic segment now includes multiple internationally active manufacturers, each pursuing distinct regional strategies and cost-centric value propositions. Accord Healthcare markets generic vorinostat capsules in regions including Europe and India for oncology applications. In October 2023, the company advanced its European footprint by launching generic vorinostat 100 mg capsules in the UK market following EMA approval. This move illustrates how regulatory clearance, combined with established distribution channels, can accelerate generic adoption in pricing-sensitive procurement environments.
Dr. Reddy's Laboratories, headquartered in Hyderabad, produces and supplies generic vorinostat for global markets with a clear focus on affordable HDAC inhibitor alternatives after patent expiry. In June 2022, the company received US FDA approval for generic vorinostat capsules in 100 mg and 400 mg presentations as AB-rated equivalents to Zolinza. This approval represents a meaningful commercial milestone because it opens access to the US procurement system, where equivalence recognition can influence institutional purchasing decisions and competitive pricing structures. The broader Indian manufacturing base also includes Hetero Drugs and Natco Pharma, both active suppliers of generic vorinostat formulations in international markets. Hetero emphasizes availability of generic formulations for CTCL treatment across export-oriented channels, while Natco underscores cost-effective oncology generics across multiple destination countries. Together, these suppliers contribute to a supply environment in which price competition, regional targeting, and manufacturing scale increasingly influence procurement outcomes.
For strategic planners, this competitive configuration raises several practical questions. Which supply partners offer the most reliable continuity for procurement programs? Where do pricing pressures intensify fastest, and what contract structures can mitigate exposure? How do branded and generic offerings coexist within hospital formularies and institutional procurement lists? The full report addresses these questions by connecting company profiles, regulatory events, and distribution behavior to market-level outcomes, allowing readers to benchmark supplier options and anticipate competitive friction before it disrupts sourcing plans.
Regulatory and Clinical Context as Market Shapers
The vorinostat market cannot be evaluated purely as a commercial volume equation because its behavior is closely tied to regulatory milestones, safety expectations, and guideline recognition. These elements structure prescribing confidence, procurement eligibility, and the practical boundaries within which manufacturers and buyers operate. Our study integrates this context directly into the market assessment so that strategic conclusions are grounded in clinical and regulatory reality rather than abstract demand modeling.
A foundational element of the market’s credibility is the 2006 accelerated approval pathway for Zolinza, which established vorinostat as a treatment option for CTCL in patients who had progressive, persistent, or recurrent disease on or following two systemic therapies. That approval created an official therapeutic anchor and, over time, reinforced the drug’s clinical familiarity. Equally important for contemporary planning is the ongoing relevance of guideline alignment. Inclusion of Zolinza in NCCN guidance for relapsed and refractory CTCL, with a category 1 recommendation for certain subtypes, strengthens formulary justification in settings where evidence hierarchy and treatment standardization matter. This type of endorsement can influence institutional purchasing preferences, particularly in structured procurement environments that weigh guideline concordance alongside price.
Worldwide Azacitidine Market
Safety considerations also shape how vorinostat is deployed in practice. The product carries black box warnings related to thromboembolism risk and QT prolongation, which require ECG monitoring and DVT prophylaxis in clinical use. From a strategic standpoint, these requirements influence hospital workflow, prescribing oversight, and the operational burden associated with therapy administration. They also affect how procurement teams evaluate supplier support services, patient management resources, and risk-mitigation materials that may accompany product supply. In mature markets especially, the effective management of safety protocols can be as important to sustained utilization as the molecule’s therapeutic efficacy.
Worldwide Vorinostat Market
Patent expiry continues to function as a structural market catalyst. With composition-of-matter protections having lapsed in 2011, the environment has shifted toward generic participation, price competition, and multi-source supply. This reality does not eliminate branded relevance, but it reframes it. Originator products now compete within a broader ecosystem where equivalence recognition, procurement consolidation, and cost control strategies determine share distribution. Understanding how these dynamics interact across jurisdictions is critical for anyone forecasting demand stability, negotiating supply terms, or planning product positioning over the 2026 to 2032 horizon.
What the Report Delivers for 2026 Decision-Making
Market research earns its value when it reduces uncertainty in real planning contexts. The Worldwide Vorinostat Market report is structured to support that objective by combining top-line market sizing with deeper operational coverage. The full publication details the historical baseline, the forecast architecture, and the segmentation logic across region, type, and application, while also translating these dimensions into planning-relevant interpretations. It examines how demand is organized, where procurement pressure is likely to intensify, and how regulatory or competitive events can alter trajectory expectations.
Beyond the quantitative spine, the report provides practical assessments of supplier behavior, approval timelines, generic entry patterns, and the procurement consequences of guideline and reimbursement environments. It addresses the market concentration profile, including the extent to which a concentrated set of participants shapes pricing and availability dynamics, and it explores the implications of that concentration for buyers seeking supply resilience. The study also contextualizes the interplay between branded legacy positioning and generic cost competition, helping teams anticipate where negotiation leverage may shift and which commercial levers are most likely to influence share outcomes.
For strategy, R&D, supply-chain, and commercial teams, the publication is designed to function as a working reference rather than a static overview. It supports capacity planning by clarifying likely demand progression, aids market-access prioritization by mapping the environments where utilization drivers are strongest, and informs partnership or sourcing decisions by highlighting supplier structures and regulatory milestones that affect reliability and cost. The full report also includes the kind of scenario-sensitive framing that enterprise planners need when preparing for multiple possible outcomes, from faster generic diffusion to slower formulary adoption in particular geographies.
Why This Study Belongs in Your 2026 Planning Cycle
In a market characterized by steady growth, established clinical use, and expanding generic participation, the strategic challenge is less about recognizing that the market exists and more about understanding how its internal architecture will evolve. The worldwide vorinostat market will continue to be shaped by the tension between therapeutic continuity, cost optimization, regulatory accommodation, and competitive supply expansion. Navigating that tension successfully requires intelligence that connects numbers to mechanisms and mechanisms to decisions.
Our study provides that linkage. It offers the macro visibility needed to set direction, the segmentation interpretation needed to prioritize effort, and the competitive and regulatory context needed to anticipate disruption. It is built to help planners avoid overreacting to isolated events while still recognizing the cumulative significance of approval milestones, generic launches, guideline reinforcement, and regional procurement trends. For organizations preparing for 2026, that combination is not optional; it is the difference between reactive positioning and deliberate strategy.
The full Worldwide Vorinostat Market report expands every dimension previewed here into a comprehensive decision-support package, with detailed coverage of market sizing, segmentation logic, competitive profiles, recent regulatory and commercial developments, and the operational implications of each factor for procurement, supply, and portfolio strategy. Readers who require precise planning inputs, supplier comparisons, and scenario-ready interpretation will find the complete study structured to support those needs directly. The report is available through our official market intelligence portal, where the full dataset, analytical commentary, and strategic frameworks can be accessed in their complete form.
For detailed analysis of this topic, please visit the official page: Worldwide Vorinostat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com