

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cephalosporin Intermediates Market Projected to Reach USD 567 Million by 2032 at 5.4% CAGR

Strategic Intelligence Report: Navigating the 2026-2032 Cephalosporin Intermediates GCLE Market
The global pharmaceutical supply chain stands at a critical inflection point. As we move beyond the volatility of the early 2020s, the demand for essential antibiotic intermediates has stabilized into a trajectory of steady, calculated growth. For stakeholders in the pharmaceutical manufacturing sector, understanding the nuances of the Cephalosporin Intermediates GCLE Market is no longer optional; it is a prerequisite for resilient strategic planning. This article serves as an executive preview of our latest comprehensive market research, designed to equip leadership teams with the foresight needed to navigate the forecasting period of 2026 through 2032.
Our analysis indicates that the market is poised for expansion, driven by persistent healthcare demands and evolving manufacturing dynamics. However, surface-level growth figures often mask the complex interplay of raw material dependencies, regional concentration risks, and competitive maneuvering that define actual profitability. This report dissects those layers, offering a granular view of where value is created and where vulnerabilities lie.
Market Trajectory and Historical Context
The foundation of any strategic forecast lies in a robust understanding of historical performance. Our research tracks the market revenue from 2020 through the base year of 2025, providing a five-year historical lens against which future projections are calibrated. The data reveals a market that has demonstrated resilience despite global logistical disruptions. Starting from a valuation of approximately 312.45 Million USD in 2020, the sector climbed to 392.36 Million USD by 2025. This upward trend underscores the inelastic demand for cephalosporin antibiotics, which remain a cornerstone of global infectious disease treatment protocols.
Cephalosporin Market
Looking forward, our forecast models project a consistent Compound Annual Growth Rate (CAGR) of 5.4 percent over the forecast period. By 2032, the market is expected to reach a valuation of 566.97 Million USD. While these macro figures suggest a healthy environment, the strategic value for decision-makers lies in understanding the velocity and sustainability of this growth. A 5.4 percent CAGR implies a maturing market where share gain becomes increasingly difficult, shifting the focus from pure volume expansion to efficiency, quality differentiation, and supply chain security. The transition from the historical period to the forecast period marks a shift from recovery to optimization, requiring firms to adapt their capital allocation strategies accordingly.
Cephalosporin Intermediates GCLE Market
Operational Deep Dive: Report Contents and Methodology
To support high-stakes decision-making, this research report moves beyond top-line estimates. It is structured to provide actionable intelligence across several critical dimensions. The methodology integrates primary interviews with industry participants and secondary research from regulatory filings, trade analyses, and technical literature. The following components define the scope of our operational analysis:
- Segmentation by Product Grade: The market is bifurcated into High Purity Grade, defined as above 99 percent, and Standard Grade, typically at 98 percent. The report analyzes the revenue contribution and strategic importance of each grade, highlighting how purity specifications influence downstream API manufacturing costs and regulatory compliance.
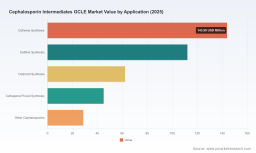
- Application-Specific Demand: We examine the consumption patterns across key synthesis pathways, including Cefixime, Cefdinir, Cefprozil, and Cefcapene Pivoxil. Understanding the specific demand drivers for each antibiotic synthesis route allows manufacturers to align production capacities with the most lucrative therapeutic segments.
- Regional Distribution Analysis: The study maps revenue flows across major geographical zones. While Asia Pacific remains a dominant force in volume, the report details the strategic nuances of Europe, North America, Latin America, and the Mideast and Africa, focusing on import dependencies and local manufacturing capabilities.
- Supply Chain Risk Assessment: A dedicated section evaluates the vulnerabilities in the raw material supply chain, specifically focusing on the procurement of key precursors and the impact of logistical factors on export expenses.
This structure ensures that readers do not merely see the size of the pie, but understand the ingredients, the bakers, and the distribution channels. For procurement officers and supply chain managers, the segmentation data offers a blueprint for negotiating contracts and securing supply lines. For strategic planners, the regional analysis highlights where capacity expansion might yield the highest return on investment relative to regulatory environments.
Competitive Landscape and Key Players
Market concentration is a vital indicator of competitive intensity and pricing power. Our analysis identifies a moderately concentrated market structure, where the top three players hold a significant portion of the revenue share, and the top five entities command a majority of the market. This concentration suggests that while there is room for new entrants, established players benefit from economies of scale and established supply chain relationships, particularly regarding critical raw materials.
The competitive field is characterized by specialized manufacturers who have invested heavily in the specific chemical synthesis routes required for GCLE production. Key companies shaping the landscape include:
- Otsuka Chemical Co., Ltd.: Headquartered in Osaka, Japan, this firm is a primary developer and manufacturer of GCLE. They operate dedicated production facilities, including a plant in India, positioning them as a critical link in the β-lactam intermediate supply chain. Their long-standing expertise makes them a benchmark for quality and technical capability.
- CSPC Cenway Tianjin Pharmaceuticals Co., Ltd. and Tianjin Gencom Pharmaceutical Co., Ltd.: Based in Tianjin, China, these entities are active suppliers of GCLE intermediates for cephalosporin API production. Their presence underscores the significance of the Tianjin region as a hub for pharmaceutical intermediates.
- Tianjin Jinkang, Ningbo Renjian Pharmaceuticals, Shandong Ruiying Pharmaceutical Group, Jiangsu Haici Biopharmaceuticals, and Xindi Bio: These listed global manufacturers represent a broad swath of production capacity across China. Their involvement in the GCLE market highlights the competitive pressure on pricing and the importance of scale in securing raw material contracts.
- Virchow Group / Virchow Petrochemicals Private Limited: Operating out of Telangana, India, this group manufactures and supplies GCLE for cephalosporin intermediates. Their presence adds a layer of diversification to the supply base outside of China, which is strategically relevant for buyers seeking to mitigate geographic concentration risk.
- Otsuka Chemical (India) Private Limited: Located in Haryana, this entity serves as a manufacturing plant focused on GCLE production, extending the Japanese parent company's reach into the Indian market, which is a key production base for export-oriented cefixime.
The presence of both Japanese technology leaders and large-scale Chinese manufacturers creates a dynamic competitive environment. Buyers must navigate the trade-offs between technical precision, cost efficiency, and supply security. The report provides detailed profiles on these entities, analyzing their production capacities, strategic positioning, and potential vulnerabilities.
Critical Market Dynamics and Constraints
Strategic decisions cannot be made in a vacuum. The GCLE market is subject to specific structural constraints and regulatory dynamics that significantly influence margin potential and supply reliability. Our research highlights several critical factors that industry leaders must monitor closely during the 2026-2032 period.
Raw Material Dependency and Penicillin-G: A fundamental constraint in GCLE production is the reliance on Penicillin-G as the key raw material. Industry data indicates that this precursor is entirely procured from China with no alternative sources currently available at scale. This creates a single-point-of-failure risk in the supply chain. Historical technical literature notes that domestic Chinese processes have faced challenges regarding high costs and quality issues in the past, leading to periods of continued reliance on imports in certain contexts. This dependency means that any disruption in the Penicillin-G supply chain directly impacts GCLE availability and pricing.
Regulatory Schemes and Export Orientation: Regulatory frameworks play a pivotal role in shaping market flows, particularly in India. Advanced authorization schemes have been implemented that allow GCLE suppliers to import Penicillin-G without minimum import price restrictions for export-oriented cefixime production. This regulatory nuance is crucial for manufacturers operating in India, as it affects the landed cost of raw materials and the competitiveness of the final exported product. Understanding these regulatory levers is essential for cost modeling and margin protection.
Logistical Factors and Regional Dominance: China dominates the export of cephalosporin API and intermediates. However, this dominance is not without friction. Logistical factors such as high international shipping costs and container shortages have historically affected export expenses. While supply chains have adapted, the potential for renewed logistical volatility remains a risk factor that must be priced into long-term contracts. The report analyzes how these logistical realities interact with regional market sizes to determine true net revenue potential for exporters versus domestic consumers.
Strategic Implications for 2026 and Beyond
As we enter the forecast period, the strategic imperative shifts from navigating crisis to managing growth amidst constraints. The projected growth from 397.57 Million USD in 2026 to nearly 567 Million USD by 2032 offers opportunity, but realizing this value requires sophisticated management of the underlying dynamics.
For procurement leaders, the concentration of raw material sourcing in China necessitates dual-sourcing strategies where possible, or stronger contractual safeguards with existing suppliers. For production planners, the distinction between High Purity and Standard Grade segments offers a pathway to margin improvement, as high-purity grades often command premium pricing in regulated markets. For executives evaluating market entry or expansion, the regional concentration suggests that proximity to key API manufacturing hubs in Asia Pacific may offer logistical advantages, though regulatory access in North America and Europe remains a key value driver.
Furthermore, the competitive landscape indicates that consolidation may continue as larger players leverage their scale to secure raw material advantages. Smaller players may need to find niches in specific application segments, such as Cefcapene Pivoxil Synthesis, where volume requirements are lower but specialization is higher. The interplay between the top five companies and the broader field of listed manufacturers will define price stability and innovation rates in the coming years.
Conclusion: The Value of Precision Intelligence
In a market defined by specific technical requirements, raw material dependencies, and regional regulatory nuances, general market intelligence is insufficient. Success in the Cephalosporin Intermediates GCLE Market during the 2026-2032 period will belong to those who understand the granular details of supply chain vulnerabilities, competitive capabilities, and segmentation dynamics.
This report provides the framework for that understanding. It bridges the gap between high-level market sizing and the operational realities of manufacturing and procurement. However, the full depth of the data, including precise revenue splits by region and application, detailed company profiles, and specific risk mitigation strategies, is contained within the full research document. For organizations committed to securing their supply chains and optimizing their market position, accessing the complete intelligence is the next logical step.
We invite stakeholders to review the full report to leverage these insights for their 2026 strategic planning cycles. The data presented here is the foundation; the complete analysis is the tool required to build a resilient future in the global pharmaceutical intermediates market.
For detailed analysis of this topic, please visit the official page: Cephalosporin Intermediates GCLE Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com