

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Sulfonated Polyethersulfone Market to Hit $1,036.42M by 2032, 8.51% CAGR
By pmarketresearch, 2026-09-16
Unlocking Strategic Value in the Sulfonated Polyethersulfone Market: A 2026 Outlook
Executive Summary: The Imperative for Data-Driven Decision Making
As industries across the globe pivot toward sustainable materials and advanced membrane technologies, the strategic landscape for specialty polymers is undergoing a profound transformation. For senior executives, procurement leaders, and R&D directors, the question is no longer whether to engage with sulfonated polyethersulfone (S-PES) supply chains, but how to navigate the accelerating demand with precision. PW Consulting presents a comprehensive market intelligence briefing designed to equip decision-makers with the analytical depth required for 2026 and beyond.
The sulfonated polyethersulfone market represents a critical intersection of water infrastructure, energy transition, and medical innovation. Organizations that attempt to forecast capacity planning, pricing strategies, or partnership opportunities without granular visibility into market dynamics risk suboptimal capital allocation. Our latest research publication delivers the structured intelligence necessary to turn uncertainty into competitive advantage.
Macro Trajectory: Growth Patterns and Historical Momentum
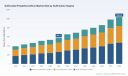
Understanding the market's velocity requires more than isolated snapshots. Our analysis anchors decision-making in a robust historical dataset spanning 2020 through 2025, establishing the baseline performance that informs forward-looking projections. Over this five-year window, the market demonstrated sustained expansion, climbing from approximately 390.45 million USD to 585.5 million USD. This upward trajectory reflects compounding demand across multiple end-use sectors and the gradual maturation of sulfonation technologies.
Looking ahead, the forecast period extends through 2032, offering a sufficiently long horizon to accommodate multi-year product development cycles, regulatory implementation timelines, and capital investment returns. Our projections indicate the market will advance to roughly 655.69 million USD in 2026, continuing its expansion to reach 1,036.42 million USD by the terminal forecast year. This path reflects a compound annual growth rate of 8.51 percent, a figure that signals a healthy, structurally supported expansion rather than a temporary cyclical spike. Such a CAGR demands that organizations institutionalize monitoring mechanisms and build strategic flexibility into their operational roadmaps.
For enterprises evaluating market entry, capacity expansion, or supply agreements, these figures provide an essential north star. Yet the macro view is only the beginning. The real strategic value lies in dissecting the drivers, constraints, and competitive variables that shape this growth curve.
Why 2026 Demands a Refined Analytical Lens
The year 2026 marks a pivotal inflection point for several reasons. Production technologies are transitioning from pilot and early-commercial stages into more scalable operations, particularly in Asia, where manufacturing capacity and process innovation are accelerating. At the same time, regulatory frameworks concerning polymer disposal and manufacturing processes are tightening globally, altering cost structures and influencing material selection decisions. Organizations that rely on legacy assumptions about feedstock availability, pricing stability, or application adoption rates will find themselves misaligned with the emerging reality.
Furthermore, the positioning of sulfonated polyethersulfone as a hydrocarbon-based alternative to perfluorocarbon sulfonic acid polymers introduces both opportunity and complexity. Cost considerations, environmental compliance expectations, and end-user preferences are simultaneously reshaping procurement criteria. Decision-makers need to understand not just where the market is heading, but how the underlying substitution dynamics will play out across specific application verticals and geographic corridors.
Inside the Report: Actionable Intelligence for Strategic Planning
Our publication is engineered for practical application. It is not merely a data repository; it is a structured analytical toolkit designed to support scenario planning, competitive positioning, and risk assessment. The report delivers a multi-layered examination of the market environment, integrating quantitative forecasting with qualitative interpretation of industry forces.
- Demand and Supply Integration: The analysis maps how production volumes, pricing benchmarks, and capacity expansions interact across the value chain. We examine the role of key intermediates and monomer precursors, including the contribution of diphenyl sulfone to sulfone polymer production, to illuminate cost drivers and supply sensitivity.
- Production Context and Unit Economics: Detailed context is provided on recent production milestones, including global output volumes and average selling price indicators, giving readers a grounded sense of the commercial landscape surrounding specialized sulfonated grades.
- Application and Technology Segmentation: The report breaks down market structures by sulfonation degree and by application, allowing executives to evaluate where value creation is concentrated and how technical specifications influence purchasing decisions. The inclusion of controlled sulfonation degrees and molecular weight considerations reflects the reality that performance requirements vary sharply across membrane blends, ion exchange systems, and separation processes.
- Regulatory and Environmental Dynamics: A dedicated examination of how stricter environmental regulations concerning polymer manufacturing and disposal shape market behavior ensures that compliance risk is treated as a strategic variable rather than a peripheral concern.
Competitive Landscape and Regional Dynamics
The market structure reflects a notable degree of concentration, yet one that still leaves substantial room for specialized players and regional innovators. Our competitive assessment addresses the interplay between established suppliers and emerging entities, highlighting how proprietary sulfonation technologies, molecular weight retention strategies, and process efficiencies differentiate participants in a technically demanding field.
The competitive environment is not monolithic. Companies are pursuing distinct technical pathways, from direct polymerization approaches that seek precise control over sulfonation degree and molecular weight to novel sulfonation methods that prioritize high molecular weight retention through multiple international patents. Some participants focus on pilot-stage offerings and specialized grades such as light brown powder formulations with targeted sulfonation levels, while others supply materials tailored for antibacterial blend composite membranes, dye separation applications, or nonfluorinated membrane solutions. This fragmentation of technical strategy creates both partnership opportunities and competitive friction points that executives must navigate with care.
Application Value Chains and Sulfonation Technology Spectrum
One of the most decision-relevant dimensions of this market lies in the relationship between sulfonation intensity and end-use suitability. Different applications impose different requirements for ion conductivity, membrane morphology, fouling resistance, and chemical stability. As a result, the market naturally segments into tiers defined by sulfonation degree, each with its own supply-demand equilibrium and technological trajectory.
Higher sulfonation ranges are often aligned with applications demanding elevated ion exchange capacity, while medium and lower ranges serve contexts where balance between hydrophilicity, mechanical integrity, and cost is critical. The report explores how these ranges map to real-world usage, including the development of antifouling blends for water treatment membranes, ion exchange membranes for redox flow batteries, and nonfluorinated alternatives for electrodialysis and cation exchange systems.
Sulfonated Polyethersulfone Market
Polysulfone Resin Market
On the application side, water and wastewater treatment stands as a primary demand pillar, reflecting ongoing infrastructure investment and the search for high-performance membrane materials. Proton exchange membrane applications represent another major axis of growth, tied to energy conversion and storage technologies. Medical and biotechnology uses add a performance-sensitive layer to the demand profile, while industrial gas separation and other specialized applications contribute additional pockets of differentiated demand. The report dissects these streams without overgeneralizing, ensuring that readers can identify which segments offer the most promising alignment with their product portfolios, capabilities, and strategic ambitions.
Strategic Implications for Market Entry, Expansion, and Partnership
For organizations evaluating 2026 planning cycles, the strategic implications of this market extend well beyond headline growth figures. The combination of an 8.51 percent CAGR, evolving production technologies, and a shifting regulatory backdrop means that static business cases can quickly become outdated. Executives need dynamic frameworks that can accommodate changes in feedstock availability, regional demand shifts, and the commercial readiness of competing material classes.
Success in this environment depends on several interconnected capabilities. First, it requires a clear understanding of where technical differentiation truly matters, whether through sulfonation process innovation, molecular weight control, or application-specific blend formulation. Second, it demands disciplined assessment of regional demand patterns and supply chain resilience, given the concentration and distribution of market activity across major geographic areas. Third, it calls for proactive scenario planning around substitution risk, especially as cost and environmental considerations continue to elevate the appeal of hydrocarbon-based membrane alternatives relative to perfluorocarbon options.
The report supports these needs by integrating market structure, competitive behavior, and technology development into a unified analytical narrative. Decision-makers can use the output to evaluate supplier qualification strategies, refine product roadmap priorities, and assess M&A or partnership targets with a more complete picture of market momentum and technical differentiation.
Conclusion: Converting Intelligence into Advantage
The sulfonated polyethersulfone market is entering a phase in which informed strategy will separate value creators from passive participants. Growth is real, technology is advancing, and competitive differentiation is increasingly tied to process innovation and application engineering. Yet the full strategic picture cannot be captured through summaries alone. The granularity required to make high-confidence decisions—down to the interaction of sulfonation degrees, application demand, regulatory responses, and competitive positioning—is contained within the full research analysis.
PW Consulting's market study offers the depth, structure, and forward-looking rigor that executive teams need to navigate 2026 with confidence. For organizations ready to move from general awareness to actionable intelligence, the complete report provides the detailed segmentation, competitive profiling, and scenario-based interpretation necessary to translate market momentum into measurable strategic outcomes.
For detailed analysis of this topic, please visit the official page: Sulfonated Polyethersulfone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Surface Water Measuring Instrument Market Hits $825.4M in 2025, Projects 6.72% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for Surface Water Measurement: Navigating the 2026–2032 Market Landscape
As global water security concerns intensify and regulatory frameworks demand higher precision in hydrological data, the surface water measuring instrument market stands at a critical inflection point. The latest Worldwide Surface Water Measuring Instrument Market study from PW Consulting provides a comprehensive, forward-looking view of this evolving sector, equipping decision-makers with the analytical rigor required to capitalize on emerging opportunities through 2032. Grounded in historical performance data from 2020 to 2025 and projecting a detailed forecast period from 2026 onward, this research delivers actionable intelligence for executives, investors, and strategic planners operating across environmental monitoring, industrial water management, and public infrastructure domains.
Macro Market Trajectory: Sustained Expansion Anchored by Technological and Regulatory Catalysts
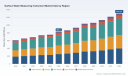
The global surface water measuring instrument market has demonstrated consistent revenue growth over the past half-decade, scaling from approximately 612.45 million USD in 2020 to an estimated 825.4 million USD in 2025. This trajectory reflects a compound annual growth rate of 6.72 percent across the forecast window extending to 2032, positioning the sector for continued expansion driven by infrastructure modernization, climate adaptation mandates, and the proliferation of real-time environmental monitoring networks. By 2032, market revenue is projected to reach 1.301 billion USD, underscoring the long-term commercial viability of precision hydrological instrumentation.
Several structural forces underpin this outlook. Municipalities and regulatory agencies are increasingly mandating continuous surface water monitoring to comply with evolving environmental standards, flood risk management protocols, and watershed protection initiatives. Simultaneously, industrial operators are investing in advanced effluent control and process water tracking to meet stricter discharge limits and operational efficiency targets. The integration of Internet of Things connectivity, low-maintenance radar sensing technologies, and multi-parameter data acquisition platforms has accelerated the replacement cycle for legacy gauging equipment, creating sustained demand across both public and private procurement channels. Corporate consolidation and targeted product launches further illustrate how market participants are refining their portfolios to capture higher-value monitoring segments while strengthening technical differentiation.
Concentration analysis within the competitive landscape also reveals a moderately fragmented yet increasingly strategic environment. The top three players account for approximately 31.5 percent of total market revenue, while the top five collectively represent 46.25 percent. This distribution indicates that while established incumbents maintain strong positioning through brand credibility, technical certifications, and long-standing agency relationships, there remains ample room for specialized innovators, regional integrators, and vertically focused manufacturers to capture niche demand. Understanding how these competitive dynamics evolve across product categories, application segments, and geographic regions will be essential for any organization seeking to optimize its market entry strategy, partnership roadmap, or procurement positioning.
The 2026 Decision Window: Why Timely Intelligence Matters Now
For enterprise stakeholders, the 2026 forecast period is not merely a numerical projection; it is a strategic planning anchor. Organizations evaluating capital allocation for environmental monitoring fleets, water infrastructure upgrades, or sensor technology integration must understand how demand patterns are expected to shift as climate resilience investments mature and regulatory pressure intensifies. This research is designed to reduce uncertainty in those decisions by mapping growth vectors across technology types, application domains, and regional deployment trends, enabling leadership teams to align product development, sales targeting, and supply chain planning with where demand is structurally expanding.
The strategic value of this study lies in its ability to connect high-level market momentum with operational realities. Decision-makers can use the analysis to assess whether their current instrumentation portfolios are aligned with the fastest-growing monitoring requirements, evaluate partnership or acquisition opportunities in a market where capability expansion is accelerating, and identify potential supply-side or demand-side risks that could affect pricing, lead times, or technology adoption curves. Rather than relying on broad sector narratives, the report delivers a structured framework for interpreting where competitive advantage will be earned over the next several years.
Inside the Research: Operational Content Built for Execution
This market study is structured as a decision-support tool rather than a static market summary. It integrates historical performance tracking with forward-looking scenario analysis, giving readers a clear view of how the market has evolved and where it is likely headed. The research methodology combines rigorous data triangulation with segmentation analysis that isolates the primary demand drivers shaping instrument procurement across multiple end-use environments.
Readers will find detailed coverage of the core instrument categories that define the market, including water level instruments, water quality sensors, flow and velocity meters, and integrated monitoring stations. Each category is examined through the lens of application demand, technology substitution trends, and procurement priorities, allowing stakeholders to understand not only which segments are expanding, but also why they are expanding and what specifications or capabilities are gaining preference. The report also maps application-driven demand patterns across hydrological monitoring and flood forecasting, agricultural irrigation management, environmental protection and research, and industrial process and effluent control, highlighting how distinct operational requirements influence product selection, deployment frequency, and long-term service expectations.
In addition to segmentation and demand analysis, the study explores the competitive architecture of the industry, profiling leading manufacturers and technology providers that are shaping market standards. These profiles assess each company's strategic positioning, technological focus, and recent activity, offering a practical reference for benchmarking, partnership evaluation, and competitive response planning. Recent corporate and product developments are integrated into the analysis to show how innovation cycles and consolidation activity are altering competitive dynamics in real time, rather than as abstract observations.
Regional perspective is provided to help stakeholders interpret where demand concentration is strongest and how deployment priorities differ across market environments. Rather than oversimplifying complex geographic trends, the analysis distinguishes among the major regions to clarify how local regulatory regimes, infrastructure investment cycles, and environmental monitoring needs shape instrument uptake. This regional framing is particularly valuable for organizations planning distribution expansion, localized product adaptation, or multi-market service strategies.
Competitive Landscape: Leading Companies Reshaping Market Standards
The surface water measuring instrument sector is defined by a mix of specialized instrument manufacturers, broad environmental monitoring providers, and established flow measurement companies. Each brings distinct strengths in sensor design, data acquisition architecture, durability under field conditions, and compliance alignment with agency accuracy expectations. Understanding these player profiles is essential for evaluating where procurement risk is lowest, where technology differentiation is most defensible, and where partnership or integration opportunities may offer the strongest return.
Campbell Scientific, headquartered in Logan, UT, USA, is recognized for rugged, unattended surface water monitoring systems designed for long-term deployment. Its portfolio includes radar water level sensors, pressure transducers, and dataloggers engineered to meet USGS Office of Surface Water accuracy requirements for rivers, lakes, and reservoirs, positioning the company as a trusted supplier for agency-grade hydrological monitoring. Solinst Canada Ltd., based in Georgetown, ON, Canada, manufactures high-quality surface water monitoring instruments spanning level measurement devices, dataloggers, and telemetry systems. Its recent expansion through the acquisition of Eureka Water Probes has strengthened its ability to deliver comprehensive water quality and level solutions within a unified monitoring framework.
Seametrics, operating under the TASI Flow Group and headquartered in Kent, WA, USA, designs and manufactures flow meters and submersible sensors for surface water, environmental, and water/wastewater monitoring applications, including electromagnetic and propeller meters. OTT HydroMet, based in Kempten, Germany, provides hydrological instrumentation for surface water level, flow, and flood monitoring, with radar level sensors and integrated flood monitoring systems tailored for streams, rivers, and tidal waters. In-Situ Inc., located in Fort Collins, CO, USA, specializes in water monitoring equipment for surface water level, quality, and flow, with solutions supporting coastal, estuarine, and harmful algal bloom monitoring requirements.
Badger Meter, headquartered in Milwaukee, WI, USA, offers flow measurement and level monitoring solutions, including SmartLevel Surface Level Monitoring, alongside water quality instrumentation for municipal and surface water applications. Xylem, based in Washington, DC, USA, provides surface water monitoring instrumentation through its YSI and Global Water brands, delivering level sensors, water quality probes, and multiparameter instruments for environmental and wastewater applications. Stevens Water Monitoring Systems, headquartered in Portland, OR, USA, has developed environmental data acquisition systems for hydrology and surface water resource management since 1911, reinforcing a long heritage in monitoring solution design. Aquaread Ltd., based in Broadstairs, Kent, UK, manufactures multi-parameter water quality testing equipment and water level and temperature loggers for surface water, groundwater, and wastewater monitoring. KISTERS, located in Aachen, Germany, supplies water and weather instrumentation, including sensors, data logging, and IoT technology for hydrology and surface water monitoring. Heron Instruments Inc., headquartered in Dundas, ON, Canada, produces premium water level meters, conductivity, temperature, and level meters, and related instruments for surface water and groundwater applications.
Competitive momentum in this market is not only a function of product breadth; it is increasingly shaped by targeted innovation and strategic consolidation. In February 2025, OTT HydroMet launched the OTT RLS 500, a next-generation smart radar level sensor using 80 GHz FMCW technology for accurate, low-maintenance surface water level measurements with ±2 mm accuracy. Shortly afterward, in April 2025, the company introduced the OTT Flood Monitoring System, integrating the OTT SensorLink 1000 IoT device with the OTT RLS 500 radar water level sensor to support flood monitoring and stream gauging in surface water applications. These releases illustrate how precision, connectivity, and reduced maintenance burdens are becoming central competitive differentiators in a market where uptime and data reliability directly influence procurement decisions.
Solinst Canada Ltd. also made a strategically significant move in February 2025 by acquiring Eureka Water Probes, effective February 1. This acquisition expanded its surface water monitoring portfolio with water quality probes and created tighter integration with its existing level and datalogger offerings. Such consolidation signals an industry-wide push toward more complete monitoring ecosystems rather than isolated instrument sales, a trend that procurement leaders and technology planners should monitor closely as they evaluate long-term supplier relationships and platform compatibility.
Market Dynamics and Structural Shifts Driving Demand
Beyond company-level activity, several structural dynamics are reshaping how surface water measuring instruments are specified, deployed, and valued. Regulatory expectations around measurement accuracy continue to influence sensor design, particularly for non-contact radar technologies used in river, lake, and reservoir monitoring. Accuracy requirements associated with USGS Office of Surface Water guidance, for example, are helping to steer adoption toward advanced radar sensor configurations that can deliver consistent performance in open-channel and still-water environments without the maintenance burden of submerged instrumentation.
Material durability is another critical factor influencing product selection in surface water environments. Water quality and level probes commonly utilize titanium or 316L stainless steel housings to provide corrosion resistance, with titanium often preferred for harsh or saline conditions. These material considerations are not merely engineering details; they affect total cost of ownership, service life, and suitability for deployment in challenging field conditions, all of which inform procurement strategy and risk assessment.
Water Analysis Instrumentation Market
At the same time, the broader shift toward IoT-enabled radar level sensors and integrated flood monitoring systems is expanding the value proposition of surface water instrumentation beyond standalone measurement. Real-time data delivery is increasingly central to flood warning, reservoir management, and watershed decision-making, making connectivity, remote telemetry, and data integration capabilities key components of competitive offerings. As a result, buyers are evaluating instruments not only on measurement performance, but also on how well the equipment integrates into broader monitoring networks and supports operational responsiveness.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Surface Water Measuring Instrument Market research from PW Consulting is designed to help organizations move beyond general market awareness and into precise, evidence-based planning. With historical data tracing performance from 2020 through 2025, a forecast horizon extending to 2032, and segmentation analysis covering instrument types, application areas, and regional dynamics, the study offers the depth required to support capital allocation, product strategy, competitive benchmarking, and acquisition or partnership evaluation.
In a market shaped by regulatory pressure, climate adaptation investment, and rapid innovation in sensor and connectivity technology, the organizations that succeed will be those that can interpret demand signals early and act on them decisively. This report provides the analytical foundation needed to make those decisions with confidence. To access the full segmentation detail, company-level assessments, regional growth pathways, and complete forecast tables that support targeted strategic planning, readers are encouraged to explore the complete research release on the PW Consulting website.
Worldwide Surface Water Measuring Instrument Market
For detailed analysis of this topic, please visit the official page: Worldwide Surface Water Measuring Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Intelligent TCM Diagnosis Market to Hit $1,750.26M by 2032 at 14.48% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence in the Era of Digital TCM: Navigating the 2026–2032 Intelligence-Driven Diagnostic Market
The global shift toward integrated, data-driven healthcare has placed intelligent diagnosis systems at the center of modernization strategies across both conventional and traditional medicine. Traditional Chinese Medicine, with its millennia of clinical heritage, is now undergoing a structural transformation driven by artificial intelligence, high-precision sensing, and multi-modal data fusion. Our Worldwide Intelligent TCM Diagnosis System Market research provides a comprehensive, decision-ready view of this transition—anchoring executive strategy in measurable growth dynamics, competitive positioning, and policy-driven demand shifts that will define the 2026–2032 horizon.
For executives, investors, and product leaders, the strategic imperative is no longer whether intelligent TCM diagnostics will scale, but how to align R&D pipelines, commercial go-to-market motions, and partnership ecosystems with a market that is compounding at a sustained mid-teens pace. This report is engineered to translate macro momentum into actionable intelligence, without exposing organizations to the blind spots that typically accompany rapid technology adoption in regulated clinical environments.
Macro Trajectory: A Compounding Market Built on Clinical Modernization
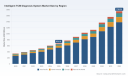
Between 2020 and 2025, the worldwide intelligent TCM diagnosis system market expanded from approximately $345 million to nearly $680 million, reflecting a decisive acceleration in adoption across clinical, research, and wellness-oriented use cases. The trajectory is expected to continue its upward arc through the forecast period, with revenue projected to surpass the $1.7 billion threshold by 2032. This expansion is underpinned by a robust compound annual growth rate of 14.48 percent, a figure that signals more than incremental adoption—it reflects a structural realignment in how diagnostic information is captured, interpreted, and operationalized within TCM practice.
Several forces are converging to support this growth profile. First, the clinical demand for objective, repeatable diagnostic signals is rising as TCM institutions seek to standardize assessments across practitioners and sites. Second, AI-enabled interpretation layers are turning previously subjective observations into quantifiable indicators that can be integrated into clinical workflows and screening programs. Third, the broader healthcare environment is increasingly rewarding systems that improve consistency, documentation quality, and operational efficiency, particularly in settings where reimbursement and cost-management pressures are intensifying.
Worldwide Intelligent TCM Diagnosis System Market
Importantly, the growth story is not purely technology-led. It is also policy- and economics-driven. In China, the nationwide rollout of the CHS-DRG payment framework has reshaped hospital economics, including within TCM institutions. DRG-based reform has shown effectiveness in managing length of stay and hospitalization costs, while unified reimbursement structures—accompanied by provisions for specially designated standards in certain TCM-dominant categories—create a more predictable environment for clinical decision-making. At the same time, the dual influence of DRG-based reimbursement and targeted subsidies for appropriate TCM techniques is shaping physician behavior toward treatment pathways that are both cost-conscious and clinically aligned. In this context, intelligent diagnostic tools are gaining relevance not only as clinical aids, but as enablers of documentation rigor, pathway consistency, and operational transparency.
What the Report Delivers: Decision-Ready Architecture, Not Just Headlines
This study is structured to support real strategic work: market entry planning, product roadmapping, partnership prioritization, and competitive risk assessment. Rather than stopping at high-level sizing, the report breaks down the market along the dimensions that matter most to commercial and clinical stakeholders. It examines demand patterns across institutional and consumer-facing environments, evaluates the relative significance of diagnostic modalities that are redefining the TCM equipment landscape, and maps geographic concentration where adoption intensity and ecosystem maturity differ materially.
The product-side analysis focuses on the categories that are reshaping procurement priorities and clinical integration requirements. These include integrated multi-modal diagnostic systems that combine multiple observation streams into a unified assessment workflow, pulse diagnosis devices built for higher measurement consistency, tongue image analysis systems that leverage visual data interpretation, and acupoint detection and treatment systems that connect diagnostic insight with intervention support. Each category is assessed in terms of adoption logic, workflow fit, and the practical requirements that determine whether a system moves from pilot interest to repeated procurement.
Intelligent Control Market
On the demand side, the report analyzes how different end-user environments influence purchasing behavior and deployment expectations. Hospitals and TCM clinics represent the most concentrated adoption base, reflecting their role as primary sites for standardized diagnosis, patient throughput, and institutional modernization. Rehabilitation centers form a distinct demand node, often prioritizing tools that support longer-term recovery monitoring and functional assessment. Scientific research institutions contribute a different dynamic altogether, driven by protocol-based data collection, validation studies, and academic-industrial collaboration. Home healthcare and personal use, while smaller in current scale, point to an emerging frontier where portability, usability, and consumer trust become decisive adoption factors.
Geographic analysis is handled with the same operational intent. The report identifies where market activity is most densely concentrated, how regional ecosystems differ in terms of clinical adoption culture and procurement pathways, and which environments present the most immediate commercial opportunity versus longer-term build-out potential. Rather than offering shallow regional snapshots, the analysis connects geography to underlying drivers such as institutional modernization pace, policy alignment, and the maturity of distribution and service networks.
Equally important, the study examines market concentration dynamics. With a consolidated share held by a limited group of leading participants, the competitive environment reflects both the benefits of scale and the risks of entrenched positioning. This concentration context is critical for anyone evaluating entry timing, partnership strategy, or differentiation opportunities in a market where credibility, regulatory navigation, and clinical validation can create durable barriers.
Competitive Landscape: A field Shaped by AI Capability, Clinical Credibility, and Ecosystem Reach
The intelligent TCM diagnosis system market is populated by companies spanning pure-play device developers, AI-centric diagnostic toolmakers, established TCM service brands extending into digital diagnosis, and academic research centers translating high-precision sensing concepts into clinical instruments. What distinguishes the leading players is not simply the presence of AI, but the ability to combine diagnostic objectivity, workflow integration, and demonstrable clinical relevance in environments where trust is earned through repeatability and evidence.
Several Chinese enterprises form the operational core of this landscape. Beijing Aizhenyun Health Technology has built its focus around AI-driven diagnostic equipment covering tongue, pulse, and facial analysis, positioning itself within the broader TCM intelligent diagnostic equipment segment. Yimai Artificial Intelligence Medical Technology contributes a complementary profile, emphasizing AI-based clinical diagnosis support tailored for TCM settings. Shanghai Baosongtang Biotechnology centers on objective data collection for the traditional four-diagnosis methods—inspection, auscultation, inquiry, and palpation—addressing one of the field’s most persistent modernization challenges: converting practitioner-dependent observation into consistent, documented signals.
Shanghai Zhiyun Medical Technology and Shanghai Zhenkang Medical Technology both reflect the hospital- and clinic-oriented demand pattern, with systems designed to support precision pulse and tongue diagnostics and meridian- and pulse-oriented analysis respectively. Kangway Medical and Shanghai Shanghuai Medical Instrument Manufacturing extend the ecosystem further, the former with a clinical-use orientation and the latter with hardware component and system-level manufacturing capabilities that support broader device development. Shanghai Daosheng Medical Technology and Tonghua Highend High-tech add depth to the product landscape through AI-assisted screening and diagnostic applications as well as specialized tongue and pulse analysis equipment. Zhongke Xinchuang Medical Technology contributes an integration-focused profile, emphasizing AI-enhanced platforms designed for modern clinical environments. Anhui Tatfook Technology and Huaxi Jingchuang Medical Technology round out the competitive set with strong manufacturing and innovation identities, the latter distinguishing itself through tongue diagnosis emphasis and AI integration.
A particularly notable dimension of the competitive field is the involvement of established TCM institutions and academic centers. Beijing Tong Ren Tang Chinese Medicine Co., Ltd. represents the extension of a historically significant TCM brand into AI-supported diagnostic and wellness platforms, illustrating how legacy reputation can intersect with digital transformation. Equally important is the role of Shanghai University of Traditional Chinese Medicine, particularly its Research Center for TCM Information Science and Technology, which has advanced an Intelligent TCM Diagnostic Instrument built on high-precision sensors and AI for objective pulse, tongue, and facial analysis. This academic-clinical linkage matters because it signals a pathway to clinical credibility that purely commercial entrants may find difficult to replicate quickly.
Recent developments reinforce this direction. In March 2026, SHUTCM progressed the deployment and clinical use of its AI-assisted Intelligent TCM Diagnostic Instrument for objective data collection across pulse, tongue, and facial indicators, supporting the modernization of TCM practice in hospitals and health screening centers. Around the same time, coverage highlighted the instrument’s role in converting traditional diagnostic techniques into precise, data-driven diagnostics, with both government and industry support. These milestones are strategically significant because they demonstrate that intelligent TCM diagnostics are moving beyond demonstration-phase innovation into real clinical application, where reliability, usability, and institutional endorsement become the differentiators.
Market Dynamics: Policy, Economics, and the Demand for Objective Diagnostics
The commercial trajectory of intelligent TCM diagnosis systems cannot be separated from the policy and reimbursement environment in which they operate. China’s push toward full nationwide implementation of the CHS-DRG payment system in hospitals, including TCM hospitals, has introduced a more standardized cost-and-outcome framework across institutional care. This reform matters for diagnostic technology providers because standardized reimbursement and cost-management expectations tend to increase the value of tools that Improve documentation quality, support consistent clinical assessment, and help institutions manage care pathways more efficiently.
Within this framework, TCM hospitals operate under a unified DRG structure alongside modern medicine institutions, with special provisions for reimbursement standards in certain TCM-dominant disease categories. The interaction between DRG-based reimbursement and subsidies for appropriate TCM techniques further shapes how physicians choose treatment methods, creating an environment where diagnostic clarity can influence both clinical decisions and economic outcomes. In practice, this means intelligent diagnostics are not merely optional enhancements; they can become enablers of pathway alignment, documentation integrity, and service-line consistency in institutions navigating payment reform.
Beyond policy, the broader dynamic is shaped by the clinical appetite for measurable, repeatable assessments. TCM diagnostics have historically relied heavily on practitioner interpretation, which can create variability across providers and settings. Intelligent systems address this through sensor-based data capture, image analysis, and AI-supported interpretation, helping institutions standardize assessment practices while preserving the conceptual framework of TCM diagnosis. The result is a market in which adoption is being driven not only by technological novelty, but by the operational need to reduce variability, improve clinical documentation, and support modernization goals without losing diagnostic identity.
Why This Research Matters for 2026 Decision-Making
As organizations plan for the 2026–2032 period, the key strategic question is how to position against a market that is expanding rapidly while still maturing in terms of standards, clinical validation expectations, and procurement maturity. The report is designed to support that planning with depth rather than speculation. It helps decision-makers understand where demand is most concentrated, which product categories align with different institutional priorities, how competitive positions are forming, and what policy and reimbursement dynamics are likely to influence adoption behavior.
For technology developers, the analysis clarifies where innovation must translate into practical workflow value, not just algorithmic sophistication. For distributors and system integrators, it maps the environments in which procurement is most likely to favor integrated, service-supported diagnostic platforms. For institutional leaders and investors, it frames the market in terms of concentration, growth consistency, and the momentum behind clinical modernization initiatives. And for companies evaluating partnerships, it identifies the types of organizations—commercial, academic, and brand-backed—that are shaping the credibility structure of the field.
This intelligence is especially valuable when navigating a market where visibility matters. Because the landscape includes both fast-moving AI entrants and established players with deep clinical or manufacturing roots, competitive assumptions can quickly become outdated. The report provides a structured way to evaluate who is building durable positioning, where differentiation is most credible, and which adoption drivers are likely to persist beyond short-term technology cycles.
Conclusion: From Momentum to Strategy
The worldwide intelligent TCM diagnosis system market is entering a phase in which growth, policy pressure, clinical modernization, and AI-enabled objectivity are reinforcing one another. The combination of strong revenue expansion, a high-growth trajectory through 2032, and increasing institutional demand for standardized diagnostic support creates a market with meaningful strategic relevance for 2026 planning. Yet the real value for decision-makers lies in the details: how demand is distributed across end users, how product categories differ in adoption logic, how competition is concentrating, and how regulatory and reimbursement dynamics are shaping behavior in real clinical settings.
Those details are what separate informed market entry from reactive positioning. Our full Worldwide Intelligent TCM Diagnosis System Market study provides the segment-level intelligence, competitive profiling, regional context, and operational dynamics needed to convert macro momentum into executable strategy. For executives who need to see not just where the market is going, but how to act within it, the complete report offers the depth required to move from awareness to advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Intelligent TCM Diagnosis System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smartphone Panel Market Hits $45.5B in 2025, Projected 5.19% CAGR to $64.9B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Decision-Maker: Navigating the Worldwide Smartphone Panel Market
The global smartphone panel industry stands at a critical inflection point. As device manufacturers grapple with shifting consumer preferences, supply chain realignments, and accelerating technological transitions, the need for precise, forward-looking intelligence has never been greater. Our newly released Worldwide Smartphone Panel Market research study provides a comprehensive, data-driven roadmap for navigating this complex landscape through 2032. Designed specifically for executives, strategy teams, and procurement leaders, this report translates macro-level trajectories into actionable insights that can shape capital allocation, partnership strategies, and product roadmap decisions throughout 2026 and beyond.
The Macro Trajectory: Growth, Scale, and Structural Shifts
The worldwide smartphone panel market has demonstrated remarkable resilience and expansion over the past half-decade. Historical data from 2020 through 2025 reveals a steady upward trajectory, with the market climbing from approximately 40.85 billion USD in 2023 to an estimated 45.52 billion USD in 2025. This momentum is projected to continue, with the market reaching 47.89 billion USD in 2026 and advancing to 64.91 billion USD by 2032. The forecast period reflects a compound annual growth rate of 5.19 percent, signaling sustained demand driven by device refresh cycles, premiumization trends, and the ongoing integration of advanced display capabilities across diverse smartphone tiers.
For strategic planners, these figures represent more than headline numbers. They underscore a market where volume and value are increasingly decoupled from traditional growth drivers. The expansion is not merely a function of unit shipments but reflects deeper structural changes in how displays are engineered, manufactured, and deployed. Understanding the underlying forces that will sustain this trajectory requires granular analysis of technology transitions, regional supply dynamics, and competitive positioning—precisely the kind of intelligence embedded in our full study.
Report Architecture: What Strategic Leaders Will Find Inside
This research publication is structured to deliver immediate operational value alongside long-range strategic clarity. Rather than offering static snapshots, the report is built around dynamic analytical frameworks that enable readers to stress-test assumptions, benchmark performance, and identify emerging opportunities before they become mainstream. The study encompasses several interconnected dimensions that collectively paint a complete picture of the smartphone panel ecosystem.
Core Analytical Dimensions
- Technology segmentation analysis that tracks the evolution of display architectures, including the relative positioning of emissive and non-emissive panel types across premium, mid-range, and entry-level segments.
- Form factor transitions that examine the commercial and manufacturing implications of rigid versus flexible designs, with particular attention to how foldable and bendable configurations are reshaping production economics and consumer adoption curves.
- Geographic supply chain mapping that evaluates regional manufacturing concentrations, export-import dependencies, and the strategic implications of localized production investments by key industry participants.
- Competitive intensity assessment that profiles the strategic moves, capacity expansions, technology roadmaps, and partnership networks of leading panel suppliers, providing context for pricing dynamics and supply availability.
- Forward-looking scenario modeling that projects market evolution under varying assumptions about technology adoption rates, material availability, and regulatory developments, enabling teams to prepare for multiple plausible futures.
Each section is anchored by primary research, proprietary dataset integration, and expert interpretation, ensuring that readers receive not just raw figures but the strategic context necessary to act on them. The report also includes detailed methodology notes, data validation procedures, and clear definitions of all analytical parameters, guaranteeing transparency and reproducibility for internal decision-making processes.
Competitive Landscape: Dominance, Disruption, and Strategic Positioning
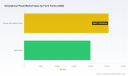
The smartphone panel sector is characterized by high concentration and intense rivalry. The top five suppliers collectively command more than 82 percent of market revenue, while the leading three firms alone account for approximately 68 percent. This concentration creates a landscape where a small number of players wield significant influence over pricing, capacity allocation, and technology standardization. Yet the competitive dynamics are far from static. Regional suppliers are expanding their technological footprints, established players are revisiting investment cycles, and new collaborations are reshaping the allocation of high-value orders.
Key Incumbents and Their Strategic Footprints
Samsung Display continues to anchor the premium segment with its advanced flexible and rigid AMOLED offerings. The company maintains a dominant position in high-end LTPO technology and supplies critical display components for flagship devices, including iPhone OLED implementations and foldable smartphones. Recent capacity reviews indicate potential additional investment to expand foldable OLED production, signaling continued confidence in the premium foldable trajectory. The firm has also demonstrated forward-looking technologies at major industry events, including privacy-enhancing display features and slidable screen concepts that hint at future smartphone form factors.
LG Display remains a major provider of OLED panels for smartphones, with particular strength in flexible AMOLED manufacturing and an expanding share of premium bar-type device supply. The company's focus on advanced OLED architectures positions it as a critical partner for manufacturers seeking to differentiate flagship products through display quality and innovation.
BOE Technology Group operates as the largest volume smartphone panel supplier globally, with extensive production capabilities spanning a-Si LCD, LTPS LCD, and flexible AMOLED technologies. The company's ability to serve mid-to-high-end devices, including iPhone OLED programs, underscores its integrated scale and technological breadth. The activation of a fifth Gen-8-plus OLED line reflects continued capacity expansion aimed at supporting broader smartphone and display production demands.
TCL China Star Optoelectronics Technology (CSOT) holds a significant position in LCD manufacturing while accelerating its AMOLED capabilities for both mid-range and flagship smartphone models. The company's partnerships and product integration milestones, including contributions to innovative subpixel architectures, highlight its growing relevance in advanced display supply chains.
Tianma Microelectronics focuses on LTPS LCD and AMOLED panels for small-to-medium device sizes, maintaining competitive offerings tailored to mid-range segments. Visionox Technology specializes in flexible AMOLED panels and continues to invest in higher-generation production lines for consumer electronics applications. These Chinese suppliers collectively reinforce the region's volume leadership while pursuing differentiated technological niches.
Beyond these major players, the competitive field includes numerous specialized manufacturers. AU Optronics (AUO) provides LCD solutions and is developing OLED panels for mobile applications. Innolux Corporation manufactures TFT-LCD panels primarily serving entry-to-mid-range smartphones. Japan Display Inc. (JDI) supplies advanced LCD and emerging OLED panels targeting premium and specialty applications, while Sharp Corporation produces LCD panels for mobile devices. HannStar Display Corporation offers TFT-LCD solutions for smartphones and related mobile applications, and HKC Corporation has grown as a supplier of a-Si LCD panels focused on entry-level devices. Together, these firms create a multi-tiered competitive environment where scale, specialization, and regional positioning all influence market outcomes.
Industry Dynamics and Emerging Pressures
The smartphone panel market does not operate in isolation. Recent developments and structural trends are reshaping supply-demand balances, cost structures, and strategic priorities across the value chain. Leaders must account for multiple overlapping forces when planning for 2026 and beyond.
Technology Adoption and Mid-Range Transformation
A notable acceleration is underway in the transition from LTPS LCD to AMOLED technologies within mid-range smartphone segments. Industry projections indicate that AMOLED panels are expected to capture a substantially larger share of total smartphone panel shipments in 2026, reflecting broader consumer acceptance, manufacturing efficiencies, and the desire of brands to differentiate products through display quality. This shift carries significant implications for panel suppliers, device manufacturers, and component procurement strategies. Companies that can navigate this transition—whether by expanding AMOLED capacity, optimizing LTPS LCD portfolios for residual demand, or developing hybrid supply approaches—will be better positioned to capture value as the technology mix evolves.
Worldwide Smartphone Panel Market
Supply Chain Vulnerabilities and Material Concentration
Critical raw materials and processing capabilities introduce important risk dimensions into panel market planning. China maintains dominant control over the processing of essential minerals such as indium, which is used in indium tin oxide (ITO) for touch layers and electrodes in smartphone displays, as well as gallium and germanium. Past and potential export restrictions on these materials have raised awareness of supply chain fragility and cost volatility risks for panel production globally. Indium tin oxide serves as a key conductive layer in touchscreens, and supply concentration in a limited number of processing hubs means that geopolitical developments, trade policy adjustments, or logistical disruptions can quickly affect production economics.
Compounding these material dynamics, regulatory scrutiny is intensifying. A U.S. Section 232 investigation into imports of processed critical minerals and derivatives, including those relevant to display manufacturing, has been ongoing through late 2025, with potential tariffs or import adjustments under consideration for national security reasons. These developments could influence sourcing strategies, cost structures, and the geographic distribution of panel manufacturing investments. For companies operating across multiple regions, understanding the interplay between material availability, regulatory trajectories, and supply continuity is essential for resilient planning.
Innovation Pathways and Future Form Factors
Beyond current production configurations, the industry is actively exploring next-generation display capabilities. Recent technology showcases have featured privacy-enhancing screen features, slidable display concepts, and improved flexible panel architectures that leverage polyimide substrates and ultra-thin glass to reduce crease visibility in foldable devices. These innovations suggest that the definition of mainstream smartphone displays will continue to expand, creating new requirements for materials science, manufacturing precision, and integration engineering. Companies that monitor these experimentation tracks and assess their commercial viability can anticipate shifts in consumer expectations and align their product development cycles accordingly.
Why 2026 Demands Precision Intelligence
The convergence of technology transitions, competitive intensity, supply chain reconfiguration, and regulatory uncertainty makes 2026 a pivotal year for strategic decision-making in the smartphone panel sector. Organizations that rely on fragmented data sources, outdated assumptions, or generalized market narratives risk misallocating resources, missing partnership opportunities, or underestimating competitive threats. In contrast, leaders who ground their strategies in comprehensive, validated, and forward-looking intelligence can move with greater confidence and precision.
Our Worldwide Smartphone Panel Market research study is designed to meet this need. It provides the analytical rigor required to evaluate investment priorities, the competitive context necessary to anticipate supplier and customer behavior, and the scenario frameworks that support agile planning in an environment where multiple outcomes remain plausible. Whether the objective is to optimize procurement strategies, assess entry or expansion opportunities in specific technology segments, benchmark against incumbents, or prepare for regulatory and material supply shifts, the report delivers the structured intelligence that executive teams require.
Worldwide Smartwatch Display Panel Market
Access the Full Intelligence Architecture
The insights summarized here represent only a fraction of the analysis contained in the complete study. Detailed segmentation trajectories, proprietary market sizing across technology and form factor categories, in-depth competitive profiles, scenario modeling outputs, and granular regional supply chain assessments are all integrated into the full report. To explore the complete dataset, access interactive analytical frameworks, and leverage the full strategic context for your 2026 planning, request the comprehensive Worldwide Smartphone Panel Market research publication. Equip your team with the depth of intelligence required to navigate a market defined by rapid innovation, concentrated competition, and evolving global dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide Smartphone Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cloud VPN Market to Reach $42.16B by 2032 with 15% CAGR
By pmarketresearch, 2026-09-16
Navigating the Secure Cloud Frontier: Strategic Insights from the 2026 Worldwide Cloud VPN Market Report
The enterprise networking landscape is undergoing a structural transformation. As organizations accelerate their migration to hybrid and multi-cloud environments, the traditional perimeter has dissolved, replaced by dynamic, identity-centric security models. At the heart of this shift lies the Cloud VPN market, a critical infrastructure layer that ensures secure connectivity across distributed assets. PW Consulting is proud to introduce our latest comprehensive study, the Worldwide Cloud VPN Market Report, designed to equip C-suite executives, network architects, and investment strategists with the intelligence needed to navigate the complexities of 2026 and beyond.
This report is not merely a collection of statistics. It is a strategic roadmap intended to decode the velocity of market evolution, the intensifying competitive dynamics, and the regulatory headwinds that will define the next seven years. By analyzing historical trajectories from 2020 through 2025 and projecting forward to 2032, we provide a clear lens through which to evaluate opportunity costs and growth vectors.
Worldwide Cloud VPN Market
Macro Trajectory and Market Magnitude
The scale of the opportunity is substantial. Our analysis indicates that the global Cloud VPN market has experienced robust expansion over the past half-decade, driven by the relentless adoption of cloud services and the heightened necessity for secure remote access protocols. Starting from a foundation of approximately 7.85 billion USD in 2020, the market has climbed steadily to reach an estimated 15.85 billion USD in 2025. This historical growth underscores the critical dependency organizations now place on encrypted tunneling solutions to maintain operational continuity.
Looking ahead, the forecast period from 2026 to 2032 suggests continued momentum. Projections indicate the market will surpass 18.16 billion USD in 2026, accelerating towards a valuation exceeding 42.16 billion USD by the end of the forecast window in 2032. This trajectory implies a Compound Annual Growth Rate (CAGR) of roughly 15.0 percent over the forecast period. For strategic planners, this rate signals more than just revenue potential; it indicates a maturing ecosystem where consolidation, technological differentiation, and regulatory compliance will become the primary battlegrounds for market share.
Architectural Shifts and Segmentation Dynamics
Understanding where value is generated within this ecosystem is vital for allocation decisions. The market is broadly defined by distinct component categories, primarily split between Software and Platform solutions and Professional and Managed Services. Our deep dive reveals how the balance between these components is shifting as enterprises seek turnkey security stacks rather than discrete tools.
Furthermore, connectivity types are evolving. The market encompasses both Site-to-Site Cloud VPN solutions, which remain critical for hybrid cloud architectures, and Remote Access Cloud VPN, which has seen sustained demand due to persistent flexible work models. However, the nuance lies in how these segments interact with emerging Zero Trust frameworks. The report details how traditional tunneling is being augmented, and in some cases replaced, by identity-aware proxies and software-defined perimeters. We analyze the revenue implications of these architectural transitions without oversimplifying the complex trade-offs between performance, latency, and security posture.
Regional dynamics also play a pivotal role in shaping demand. While North America continues to represent a significant portion of market activity, reflecting its high density of cloud infrastructure and enterprise adoption, other regions are exhibiting unique growth patterns driven by local data sovereignty laws and digital transformation initiatives. Europe and Asia Pacific present distinct challenges and opportunities, particularly regarding infrastructure capacity and regulatory alignment. The report contextualizes these regional variances, helping global organizations tailor their deployment strategies to local realities rather than applying a one-size-fits-all approach.
Competitive Landscape and Strategic Positioning
The vendor ecosystem is a mix of hyperscale cloud providers, established security giants, and innovative niche players. The market concentration is notable, with the top three players holding a significant share of the landscape, while the top five approach half of the total market value. This consolidation suggests that scale and interoperability are becoming increasingly important differentiators.
Key industry participants include technology behemoths such as Cisco Systems, Microsoft Corporation, Amazon Web Services, and Google LLC. These companies leverage their existing cloud ecosystems to embed VPN capabilities directly into broader networking and security portfolios. For instance, solutions like Azure VPN Gateway and AWS VPN Concentrator are designed to streamline hybrid connectivity within their respective clouds. Similarly, Cisco and Google focus on integrating secure connectivity into wider SASE and dynamic routing frameworks.
The competitive field also includes specialized security vendors like Palo Alto Networks, Fortinet, Zscaler, and Check Point Software Technologies. These players often emphasize the convergence of VPN with next-generation firewall capabilities or Zero Trust Network Access (ZTNA). Zscaler and Cloudflare, for example, are positioning cloud-native alternatives that challenge traditional VPN paradigms by offering secure application access without backhauling traffic through centralized tunnels. Oracle Corporation and Huawei Technologies also maintain significant footprints, catering to specific enterprise cloud environments and regional networking needs. Array Networks rounds out the competitive view with specialized application delivery and secure access gateways.
Strategic moves within this cohort are frequent and telling. Recent industry activity highlights the pace of innovation. In November 2025, Amazon Web Services launched a VPN Concentrator for Site-to-Site VPN, enabling efficient connections for up to 100 low-bandwidth remote sites via a single Transit Gateway attachment. This product launch illustrates the industry focus on simplifying scale and reducing operational overhead for distributed enterprises. Meanwhile, in February 2026, Cloudflare partnered with Mastercard to extend comprehensive cyber defense capabilities, including application security tools relevant to secure cloud connectivity, specifically targeting critical infrastructure and small businesses. Such developments signal a broader trend where VPN technology is becoming intertwined with broader cyber resilience and partnership ecosystems.
Ssl Vpn Gateway Market
Regulatory and Infrastructure Headwinds
No strategic assessment of the Cloud VPN market is complete without addressing the external forces that constrain and shape deployment. Our report dedicates significant attention to the regulatory and infrastructure realities that executives must factor into their 2026 roadmaps.
Data sovereignty and regulatory compliance are no longer optional considerations. Initiatives requiring local data processing and storage are expanding globally, influencing cloud VPN deployment strategies to ensure adherence to local laws. In the European Union, the Digital Operational Resilience Act (DORA), effective January 2025, imposes strict requirements on ICT providers including cloud services for financial entities. This impacts the resilience and auditability of cloud VPN solutions, requiring vendors and users alike to demonstrate robust risk management frameworks.
Simultaneously, the United States has introduced new data transfer restrictions. The U.S. Department of Justice Bulk Data Rule, effective in 2025 with full compliance mandated by October 2025, restricts certain bulk sensitive personal data transfers to countries of concern. This directly affects cross-border cloud data flows used in VPN architectures, compelling multinational organizations to rethink their tunneling paths and data routing policies to avoid compliance violations.
Infrastructure constraints also loom large. The physical backbone supporting cloud VPN services faces significant pressure. U.S. data centers are projected to see electricity demand nearly double from 80 GW to 150 GW between 2025 and 2028. This surge significantly impacts operational costs for cloud infrastructure supporting VPN services. In regions with high data center concentration, such as parts of Virginia, data centers accounted for nearly 40 percent of total electricity consumption in 2024, contributing to localized wholesale electricity price increases of up to 267 percent over five years. These cost dynamics influence pricing models and availability, making energy efficiency a hidden but critical variable in vendor selection and architecture design.
Operationalizing the Intelligence for 2026 Decision-Making
The value of this report lies in its actionable granularity. We move beyond high-level aggregates to provide the specific intelligence needed for tactical execution. The study includes detailed profiles of key companies, analyzing their product portfolios, strategic focus, and recent developments. This allows competitive intelligence teams to benchmark their positions against rivals and identify potential partnership or acquisition targets.
Our segmentation analysis breaks down the market by component, connectivity type, and organization size, providing a multi-dimensional view of demand drivers. This helps product managers understand which layers of the stack are seeing the most investment and where service gaps may exist. The regional analysis offers a nuanced look at market maturity and growth catalysts across North America, Europe, Asia Pacific, and emerging regions, enabling leaders to prioritize geographic expansion or resource allocation.
Additionally, the report integrates industry context noise, such as labor cost fluctuations and infrastructure constraints, into the market dynamics discussion. By understanding how electricity costs and regulatory shifts impact the supply side of cloud VPN services, procurement and strategy teams can better negotiate contracts and plan for long-term scalability.
Conclusion: The Imperative for Informed Strategy
As we move through 2026, the Worldwide Cloud VPN market stands at a critical juncture. The convergence of legacy connectivity needs with modern Zero Trust principles, coupled with stringent regulatory environments and infrastructure cost pressures, creates a complex decision matrix for enterprise leaders. Relying on outdated assumptions or generalized market data is a risk that organizations cannot afford.
This PW Consulting report provides the depth, accuracy, and strategic context required to make informed choices. Whether you are evaluating vendor partnerships, planning network architecture upgrades, or assessing market entry opportunities, the insights contained herein are calibrated to support high-stakes decision-making. We invite you to access the full report to unlock the complete dataset, detailed forecasts, and comprehensive competitive profiles that will define your strategy for the remainder of the decade. The future of secure cloud connectivity is being written now; ensure your organization has the blueprint to navigate it successfully.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud VPN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fire and Gas Detection Market Hits $7.5B in 2025, Driven by 6.5% CAGR to $11.65B by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Navigating the Global Fire and Gas Detection System Market 2026-2032
In an era where operational safety, regulatory compliance, and technological integration define industrial resilience, the fire and gas detection sector stands at a critical inflection point. For executives, investors, and engineering leaders charting strategy through the remainder of the decade, understanding the structural trajectory of this market is no longer optional—it is a prerequisite for risk mitigation and growth allocation. Our latest research publication, Worldwide Fire and Gas Detection System Market , delivers a comprehensive, data-backed assessment designed to translate macro-level momentum into actionable corporate strategy for 2026 and beyond.
Gas Detectors Market
This analysis does not merely project numbers. It maps the interplay between evolving safety standards, sensor innovation cycles, regional deployment pacing, and competitive positioning. By aligning historical performance with forward-looking modeling, the report equips decision-makers with the clarity required to prioritize capital, evaluate supply chain exposure, and anticipate where value creation will concentrate over the 2026–2032 forecast horizon.
Market Trajectory and Growth Architecture
The global fire and gas detection ecosystem has demonstrated consistent expansion over the past half-decade, underpinned by tightening occupational safety mandates, accelerated industrial automation, and heightened risk awareness in high-hazard environments. Historical tracking from 2020 through 2025 reveals a mature yet resilient revenue curve, with the market establishing a firm baseline as it enters the current forecast cycle.
Building on this foundation, our forward-looking modeling projects sustained valuation growth through 2032. The compound annual growth rate (CAGR) is estimated at 6.5 percent across the forecast window, reflecting steady demand pull from process industries, infrastructure modernization programs, and the integration of advanced detection platforms into broader safety instrumented systems. By 2026, projected revenue climbs to approximately 7,987.5 million USD, and the trajectory continues upward, reaching an estimated 11,654.91 million USD by 2032.
These figures are not abstract benchmarks. They represent converging investment signals: capital expenditure tied to facility compliance, retrofit cycles for aging detection infrastructure, and the gradual migration from legacy standalone alarms to networked, software-enabled monitoring architectures. The report dissects the structural drivers behind this arc, enabling leaders to separate cyclical noise from durable growth fundamentals.
Structural Segmentation and Value Concentration
Effective strategy requires understanding where revenue originates, how it is distributed across technology families, and which application verticals anchor demand. Our segmentation analysis isolates the primary axes that shape procurement behavior, pricing dynamics, and competitive targeting.
From a product architecture perspective, the market is anchored by gas detection solutions, flame detection hardware, and the control systems and software layer that orchestrates them. Gas detection continues to command the largest revenue share, reflecting the breadth of hazardous gas monitoring requirements across chemical processing, refining, and confined-space operations. Flame detection maintains a critical niche in high-speed fire scenarios, particularly where hydrocarbon, hydrogen, and outdoor exposure conditions demand rapid optical response. Meanwhile, control systems and software represent the integration layer that is increasingly dictating total cost of ownership, maintenance efficiency, and regulatory reporting capability.
Application-side, oil and gas remains the dominant deployment context, driven by the sector’s risk profile, asset density, and stringent process safety expectations. Industrial and manufacturing follows as a substantial demand center, where continuous production environments require reliable detection coverage and seamless integration with plant automation. Commercial and institutional facilities contribute a meaningful share as building safety codes evolve and multi-hazard monitoring becomes standard practice. Energy and power installations round out the application base, with detection systems supporting generation, transmission, and distribution infrastructure where uninterrupted monitoring is mission-critical.
Regional demand patterns further illuminate deployment priorities and supply chain considerations. North America maintains a leading revenue position, supported by mature industrial bases, active compliance ecosystems, and sustained capital programs. Asia Pacific represents a substantial and rapidly expanding footprint, shaped by industrialization scales, infrastructure build-out, and growing adoption of integrated safety systems. Europe continues to reflect high regulatory discipline and technology-led procurement, while Latin America and the Middle East and Africa contribute emerging growth vectors tied to energy development, mining activity, and industrial modernization initiatives.
Importantly, the market exhibits moderate-to-firm concentration among leading providers, with the top three firms accounting for an estimated 42.5 percent of revenue and the top five reaching approximately 58.75 percent. This concentration has strategic implications: it signals the presence of scaled platforms, established certification portfolios, and entrenched customer relationships, while also highlighting the space for specialized innovators and regional challengers to compete on technology differentiation, service models, and application-specific performance.
Competitive Landscape: Incumbents, Specialists, and the Innovation Race
The fire and gas detection market is defined by a layered competitive structure. Global incumbents bring breadth across hardware, software, and service networks. Mid-tier specialists and technology-focused players compete through sensor performance, detection range, and environmental resilience. Automation and building safety conglomerates extend the category by embedding detection into wider control and facility platforms.
Honeywell International Inc. continues to advance comprehensive fixed and portable fire and gas detection portfolios, spanning flame detectors, toxic and combustible gas sensors, and integrated safety solutions for oil and gas, chemical, and industrial use cases. MSA Safety Incorporated reinforces its industrial safety positioning with fixed gas and flame detection platforms, open path and ultrasonic gas detection capabilities, and integrated solutions aligned with standards such as NFPA. Drägerwerk AG & Co. KGaA brings specialized expertise in optical flame detection, multi-gas instruments, and fixed monitoring systems engineered for hazardous environments across maritime, oil and gas, and industrial settings. Emerson Electric Co. delivers detection as part of process automation and safety instrumented systems, with emphasis on integrated solutions for oil and gas and petrochemical operations. Siemens AG contributes fire detection and gas monitoring offerings, including Cerberus platforms for industrial and building applications, while ABB Ltd. supplies detection systems integrated with automation and control solutions for process safety. Johnson Controls International expands the addressable space through fire detection and suppression systems with gas detection capabilities within broader building and industrial safety portfolios. Autronica Fire and Security AS maintains a strong global footprint in detection systems tailored for maritime, oil and gas, and commercial sectors, and Teledyne Gas and Flame Detection provides advanced instruments and systems for industrial safety applications.
The competitive field also includes highly specialized providers that compete on performance engineering rather than scale alone. Fire & Gas Detection Technologies Inc. focuses on UV/IR and IR3 flame detectors designed for hydrocarbon, hydrogen, and high-speed industrial fires. ESP Safety Inc. concentrates on detection technologies and systems for hazardous environments, while Industrial Scientific emphasizes portable and fixed gas detection with connected safety and real-time monitoring capabilities.
Recent industry activity underscores the pace of differentiation. In June 2026, MSA Safety exhibited at the NFPA Conference & Expo with a session addressing NFPA 72 updates that integrate gas detection, open path gas detection, ultrasonic gas detection, and smoke detection technologies into fire alarm standards. In April 2026, Patol / Optect introduced the world’s first optically enhanced long-range flame detector, the LR16, targeting specialist fire detection applications. In February 2026, Macurco Gas Detection was scheduled to exhibit at the AHR Expo, showcasing gas detection systems for HVACR professionals. These developments illustrate a broader pattern: competition is increasingly won on sensor performance, integration readiness, standards alignment, and application-specific engineering rather than commodity hardware alone.
Worldwide Fire and Gas Detection System Market
Dynamics Shaping the Next Cycle
Several forces are converging to reshape procurement priorities and technology roadmaps across the fire and gas detection sector. Understanding these dynamics is essential for evaluating supplier selection, product lifecycle planning, and market entry timing.
Regulatory and standards evolution remains a primary demand catalyst. Stringent occupational safety requirements and industry-specific benchmarks, including API and IEC frameworks, continue to drive demand for reliable detection in high-risk sectors such as oil and gas and chemicals. At the same time, updates to fire alarm standards are increasingly incorporating gas detection, open path gas detection, ultrasonic gas detection, and smoke detection technologies, expanding the scope of integrated compliance and pushing end users toward multi-sensor architectures.
Technology advancement is accelerating along multiple vectors. Sensor development emphasizes miniaturization, IoT connectivity, wireless capabilities, and AI-enabled predictive maintenance. These capabilities are transforming detection from a passive alarm function into an active monitoring and diagnostics layer, reducing false alarms, extending service intervals, and enabling centralized visibility across distributed assets. The implications for lifecycle cost, uptime, and operator safety are significant, especially for organizations managing large, dispersed, or remote installations.
Raw material and component dependencies also influence supply chain strategy. Gas detection systems rely heavily on specialized sensors—including electrochemical, infrared, semiconductor, and catalytic types—whose manufacturing involves semiconductor materials and precision optics components. As demand scales and performance expectations rise, sourcing resilience, component qualification, and manufacturing precision become differentiators that affect lead times, reliability, and total cost of ownership.
The result is a market where value is increasingly determined by how well detection platforms connect to broader operational systems, how effectively they adapt to complex hazard profiles, and how efficiently they can be deployed, maintained, and upgraded over time. Companies that treat detection as a standalone accessory risk underinvesting in integration, while those that treat it as a core safety and data layer are better positioned to capture sustained demand.
What the Report Delivers for 2026 Decision-Makers
This market study is built to support concrete strategic action. Rather than providing a high-level overview, it delivers a structured intelligence framework that connects market sizing, segmentation, competitive behavior, and technology direction to business decision processes. Key practical components include:
- Detailed revenue tracking and forecast modeling across the 2026–2032 period, anchored in a 6.5 percent CAGR and supported by historical continuity from 2020–2025.
- Segment-level analysis covering type, application, and regional demand structures, clarifying where revenue concentrates and how deployment priorities differ by sector and geography.
- Competitive profiling of leading and specialized providers, with coverage of product orientation, application focus, and strategic positioning across the global landscape.
- Assessment of recent industry developments, including standards-related updates, product launches, and exhibition activity that signal near-term commercialization and compliance trends.
- Examination of market dynamics such as sensor innovation, connectivity adoption, predictive maintenance, regulatory integration, and component supply considerations.
- Concentration analysis that helps evaluate incumbent strength, barriers to entry, and opportunities for differentiation.
For corporate strategists, the report supports market entry evaluation, competitive benchmarking, and capital allocation planning. For technology and procurement leaders, it provides context on integration requirements, sensor technology direction, and standards alignment. For investors and analysts, it offers a structured basis for assessing growth durability, segment attractiveness, and the shifting balance between scale players and specialized innovators.
How to Use This Intelligence
The value of this research lies in its applicability. Leadership teams can use the forecast trajectory to test expansion assumptions, evaluate partnership opportunities, and stress-test revenue models against realistic demand pacing. Engineering and safety leaders can align architecture decisions with the direction of integration, connectivity, and multi-sensor compliance. Procurement and supply chain teams can use the segmentation and concentration insights to anticipate vendor dynamics, specification requirements, and sourcing constraints.
Most importantly, the study is designed to prevent decision-making in the dark. In a market where safety performance, regulatory expectations, and technological capability are evolving simultaneously, relying on fragmented information creates strategic exposure. A consolidated, forward-looking view enables organizations to act earlier, prioritize more precisely, and align investments with the segments and capabilities most likely to shape the next phase of market growth.
The complete report provides the full depth of segmentation data, detailed forecasts by segment and region, comprehensive competitive profiles, and extended analysis of market dynamics and recent industry developments. Organizations seeking to operationalize this intelligence for 2026 planning can access the full dataset and methodology through the source publication, where the complete intelligence package is available for download and review.
For detailed analysis of this topic, please visit the official page: Worldwide Fire and Gas Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Glass Fiber Sizing Agent Market to Reach $1,059.21M by 2032, Growing at 6.18% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Glass Fiber Sizing Agent Market: Navigating Growth and Innovation Through 2032
The glass fiber sizing agent market stands at a critical inflection point, driven by the escalating demand for high-performance composites across transportation, renewable energy, and advanced manufacturing sectors. As materials science evolves to meet stricter regulatory standards and performance thresholds, the role of sizing agents has shifted from a mere processing aid to a foundational element determining composite integrity, resin compatibility, and environmental compliance. This analysis synthesizes the trajectory of the market through 2032, highlighting the strategic nuances that decision-makers must address to capitalize on emerging opportunities.
Market Trajectory and Macroeconomic Context
The global market for glass fiber sizing agents has demonstrated resilient expansion over the past half-decade, transitioning from a post-pandemic recovery phase into a sustained growth cycle. Valued at approximately 515.42 million USD in 2020, the market reached 696.12 million USD by 2025, reflecting a compound annual growth rate that underscores the sector's maturity and expanding application base. Looking ahead, the forecast period from 2026 to 2032 projects continued momentum, with the market size anticipated to approach 1.06 billion USD by the end of the decade. This growth is underpinned by a CAGR of 6.18 percent, signaling steady demand escalation rather than volatile spikes. Such a trajectory suggests that investments in sizing technology are no longer optional but essential for manufacturers aiming to secure supply chain stability and performance reliability.
Segmentation Dynamics: Type, Chemistry, and Application Drivers
Understanding the structural composition of the market reveals where value is being created and where competitive pressures are intensifying. The segmentation landscape is defined by distinct categories that reflect both historical usage patterns and emerging technological shifts.
Type-Based Segmentation
The market is broadly categorized by the functional role of the sizing agent. Film formers constitute the largest share of the market, reflecting their critical function in protecting glass fibers during processing and ensuring optimal adhesion to resin matrices. Coupling agents follow as a significant segment, vital for enhancing interfacial strength between inorganic fibers and organic polymers. Lubricants and antistatic agents, while smaller in volume, play indispensable roles in processing efficiency and safety, particularly in high-speed manufacturing environments. The interplay between these types dictates formulation strategies, with leading manufacturers often blending multiple functionalities to meet specific customer requirements.
Chemistry-Based Segmentation
Chemistry defines the performance envelope of sizing agents. Epoxy-based formulations lead the chemistry segment, driven by their prevalence in high-strength composite applications where thermal and mechanical stability are paramount. Polyurethane-based chemistries represent a robust secondary segment, prized for their versatility in both thermoset and thermoplastic systems, as well as their compatibility with waterborne formulations that align with environmental regulations. Polyester, polypropylene, and vinyl ester-based agents serve niche but critical roles, often selected for specific resin compatibility or cost-performance balances. The shift toward low-VOC and waterborne polyurethanes is particularly notable, reflecting industry-wide pressure to reduce emissions without compromising performance.
Application-Based Segmentation
The demand for sizing agents is inextricably linked to the health and direction of end-use industries. Transportation remains the dominant application driver, fueled by the lightweighting initiatives in automotive and aerospace sectors that rely on glass fiber-reinforced composites to improve fuel efficiency and reduce emissions. Wind energy stands as a second pillar of growth, with the expansion of turbine blade manufacturing requiring sizing agents that can withstand extreme environmental stresses while maintaining structural integrity during production. Aerospace and defense applications demand high-specification sizing solutions that meet rigorous certification standards. Construction and infrastructure, electrical and electronics, and industrial applications round out the demand profile, each imposing unique requirements on durability, processing speed, and chemical resistance. The diversity of applications suggests that suppliers must maintain a broad portfolio or specialize deeply to capture value in specific verticals.
Worldwide Glass Fiber Sizing Agent Market
Regional Analysis and Geographic Concentration
Geographically, the market exhibits a clear concentration of activity, with Asia Pacific commanding the largest share of revenue. This dominance is attributable to the region's massive manufacturing base, rapid industrialization, and significant investments in infrastructure and renewable energy. Europe and North America represent mature but steadily growing markets, where demand is driven by high-performance applications, stringent regulatory environments, and the presence of advanced composite manufacturers. Latin America and the Middle East and Africa, while smaller in absolute terms, offer pockets of growth aligned with specific industrial development and energy projects. The regional distribution highlights the importance of localized supply chains and formulation adaptations to meet varying regulatory and climatic conditions.
Competitive Landscape: Key Players and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment. The top three companies account for approximately 38.45 percent of the market, while the top five firms capture around 56.12 percent. This concentration indicates that while consolidated players hold significant influence, there remains ample room for specialized competitors and regional players to carve out niches. The strategies of leading companies reveal distinct approaches to value creation, ranging from product innovation and regulatory compliance to global supply chain integration.
Glass Fibers Market
Company Profiles and Strategic Moves
Several key enterprises define the competitive contours of the industry. Celanese stands as a benchmark for quality in thermoset reinforcement, offering emulsion polymers such as Resyn and Vinamul for glass fiber sizing. Their products are supplied to producers across Europe, the Americas, and Asia, emphasizing superior handling and composite performance. Michelman provides a comprehensive suite of film-forming dispersions, binders, and lubricants, including the Hydrolube series and FGLASS X90, specifically engineered for chopped and continuous fiberglass. Their solutions optimize protection, adhesion, and compatibility with both thermoplastic and thermoset resins. Notably, in February 2026, Michelman introduced Hydrosize 1202, a single sizing solution designed to serve both chopped strand and continuous fibers across various types, signaling a push toward versatility and process simplification.
Evonik Industries supplies silane-based DYNASYLAN and VPS additives that are critical for glass fiber sizing and protection. Their products prevent breakage during high-speed production and enable strong bonding with polymer matrices, addressing key pain points in manufacturing efficiency and composite quality. BYK, part of the ALTANA Group, produces MAH-grafted polymers and film formers exclusively for glass fiber sizing of chopped strands and continuous fibers. Their offerings are distinguished by the lowest VOC content available, enhancing mechanical properties in polyolefin composites while maintaining regulatory compliance. Production capabilities span Europe, the USA, and China, supporting a global customer base.
Covestro contributes to the market with Baybond waterborne polyurethane dispersions, which function as film formers and crosslinkers for glass fiber sizing. These products are tailored for protection and adhesion in thermoplastic and thermoset composites, with specific grades approved for food contact, reflecting the growing intersection of composite materials and consumer safety standards. Great Eastern Resins Industrial, based in Taiwan, manufactures aqueous polyurethane dispersions for fiberglass sizing agents characterized by high solid content, low viscosity, and excellent chemical and weather resistance, catering to specialized formulation needs. Emsland Group offers starch-based sizing solutions, such as the Emglass series derived from pea and potato starches, primarily for pre-sizing and warp sizing of glass fibers in the electronics industry textiles sector. This diversification into bio-based options highlights a broader industry trend toward sustainable raw materials.
Industry Dynamics: Regulation, Raw Materials, and Innovation
The operational environment for glass fiber sizing agents is shaped by a confluence of regulatory pressures, raw material considerations, and technological innovation. Regulation plays a pivotal role, with the EU REACH legislation driving the development of compliant chemicals in sizing formulations. This regulatory framework aims to enhance human and environmental protection while maintaining the performance standards required by composite manufacturers. Compliance is no longer a checkbox but a strategic differentiator, influencing formulation choices and supply chain decisions.
In terms of raw materials, sizing formulations typically comprise water, silane coupling agents for glass, film formers, and a suite of additives including surfactants, plasticizers, anti-static agents, antifoams, and rheology modifiers. These components are applied at a concentration of 0.5 to 5 percent of the composite weight, making the efficiency and selection of sizing agents critical to the overall economics and performance of the final product. The industry is witnessing a pronounced shift toward waterborne polyurethane dispersions, which support low-VOC and food-contact compliance under standards such as EU 10/2011. This transition aligns with broader sustainability goals and customer demands for safer manufacturing environments. Furthermore, the adoption of MAH-grafted polymer film formers from suppliers like BYK exemplifies the push for lowest VOC content, demonstrating how chemical innovation can address both performance and environmental objectives simultaneously.
Strategic Value of Comprehensive Market Intelligence
For organizations operating in or adjacent to the glass fiber sizing agent market, the complexity of these dynamics necessitates a depth of intelligence that goes beyond surface-level data. The strategic value of a rigorous market study lies in its ability to translate macro trends into actionable insights. Decision-makers need to understand not just the size of the market or the headline CAGR, but the underlying forces shaping segmentation growth, the specific technological advancements that are resetting competitive benchmarks, and the regional nuances that affect supply chain resilience and market entry strategies.
A detailed analysis provides the granularity required to identify high-growth pockets within the application landscape, evaluate the threat posed by regulatory shifts on specific chemistries, and assess the positioning of competitors who are leveraging innovation to capture market share. The data on market concentration, for instance, hints at the competitive intensity and the potential for consolidation or fragmentation depending on how companies respond to trends like bio-based sizing or low-VOC formulations. Similarly, understanding the regional revenue distributions helps in prioritizing investment in manufacturing capacity, sales infrastructure, and R&D focus.
Conclusion: Positioning for the Future
The glass fiber sizing agent market is poised for sustained growth through 2032, driven by the structural demands of lightweighting, renewable energy expansion, and advanced material requirements. However, realizing value in this environment requires more than passive observation. It demands a proactive strategy that integrates regulatory foresight, chemistry innovation, and application-specific expertise. Companies that can navigate the trade-offs between performance, cost, and compliance will be best positioned to thrive. The insights contained within our full market research report offer the comprehensive roadmap needed to make these strategic decisions with confidence. By delving into the detailed segmentation analysis, competitive profiling, and regional breakdowns, stakeholders can uncover the specific opportunities and risks that will define their success in the coming years. The market is moving forward; the question is whether your strategy is aligned with the trajectory of innovation and demand that lies ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Fiber Sizing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 1-Decanol Market to Reach USD 436.36 Million by 2032 at 6.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Decade Ahead: Inside the Worldwide 1-Decanol Market Research 2026-2032
The global chemical landscape is undergoing a structural rewiring. Border adjustments, feedstock volatility, and sustainability mandates are no longer peripheral concerns; they are central drivers of competitive positioning. For executives navigating the specialty chemicals and oleochemical sectors, clarity on 1-Decanol requires more than a snapshot of today's prices. It demands a disciplined view of how capacity, regulation, and demand vectors will interact through 2032. Our newly released Worldwide 1-Decanol Market research is built for that purpose.
This introduction previews the analytical architecture of the report and explains why it is designed as a decision-grade instrument for 2026 strategy cycles. The objective is not to overwhelm with fragmented figures, but to equip leadership teams with a coherent framework for capacity planning, supplier selection, regulatory preparedness, and regional prioritization. Select data points are shared here to establish the report's scope and rigor. The complete segmentation, scenario modeling, and company-level intelligence are reserved for the full publication, where they can be evaluated in context.
Why This Research Matters for 2026 Decision-Making
2026 is a hinge year. Several forces converge: trade policy recalibration, evolving chemical safety requirements, and an accelerating shift toward certified sustainable feedstocks. Companies that rely on ad hoc market intelligence risk misreading margin trajectories, overcommitting to suboptimal sourcing routes, or underestimating compliance timelines. This report is structured to reduce those blind spots.
The study covers historical performance from 2020 through 2025 and extends forecasts to 2032. Revenue is expressed in USD Million. The framework integrates top-down market sizing with bottom-up validation from capacity announcements, feedstock behavior, and application-side demand signals. Rather than presenting a single line of forecast, the analysis layers in sensitivity considerations so that procurement, strategy, and finance teams can test how changes in input costs, trade tariffs, or certification adoption alter outcomes.
For 2026 specifically, the research translates macro trends into operational questions: Which applications are expanding fastest in volume versus value? Where do regional cost structures and regulatory burdens create advantage or risk? How should buyers balance natural versus synthetic sourcing in a year when sustainability claims and trade measures both carry financial weight? These are the questions the report is built to answer.
Market Trajectory: A Decade of Structural Growth
The market has moved through a clear growth arc. Between 2020 and 2025, revenue progressed from 205.14 to 280.8, reflecting consistent demand expansion across multiple end-use sectors. The trajectory does not plateau after 2025. The forecast indicates a rise to 290.35 in 2026, followed by continued expansion to 319.31 in 2027, 338.1 in 2028, 362.35 in 2029, and 409.71 in 2030. The path continues toward 395.7 in 2031 and reaches 436.36 by 2032.
The compound annual growth rate across the forecast horizon is 6.5 percent. That figure is not merely a headline; it is a planning anchor. For capital allocation, it suggests that demand volume will continue to justify capacity reinforcement and route optimization. For procurement, it signals that securing resilient supply chains will matter as much as unit price negotiation. For commercial teams, it frames the importance of aligning product grades and certifications with the applications that are driving incremental growth.
Importantly, the forecast is presented alongside the structural factors that could accelerate or temper realized outcomes. Feedstock behavior, certification adoption, and regulatory submission deadlines are integrated into the narrative so that readers can see where upside and downside pressures originate. The full report isolates these forces by region and application, but the overarching message is consistent: growth is durable, yet unevenly distributed across pathways.
Segmentation Logic and What the Numbers Reveal
A market of this scale only becomes actionable when it is decomposed correctly. The report segments the 1-Decanol market by region, by source, and by application, then cross-references these lenses to identify where volume, value, and strategic relevance are concentrated.
Regional Structure
The regional view captures how demand and production economics diverge across major markets. The study maps the relative weight of Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, then examines what drives those shares in terms of end-use demand, manufacturing footprint, and trade flows. Rather than presenting isolated percentage splits, the analysis connects each region to its dominant applications, its exposure to feedstock origins, and its sensitivity to policy changes. That approach helps leadership teams decide where to prioritize distributor relationships, where to monitor tariff exposure, and where certification requirements are most likely to alter sourcing strategies.
Source Pathways: Natural Versus Synthetic
The source segmentation distinguishes between natural oleochemical routes and synthetic petrochemical routes. The report quantifies the respective market contributions of each pathway and then explores the operational and strategic implications. The natural route is closely tied to fatty alcohol portfolios derived from vegetable oil feedstocks, while the synthetic route relies on processes designed for high-purity industrial grades.
This distinction matters for 2026 because the two pathways face different pressure points. Natural-sourced supply is influenced by vegetable oil markets and certification dynamics, while synthetic supply is shaped by petrochemical feedstock availability and process economics. The research does not treat these as interchangeable. It evaluates them as distinct strategic options with different risk profiles, sustainability narratives, and cost behaviors under changing conditions.
Application Demand: Where Value and Volume Intersect
The application view breaks down the market across plasticizers, lubricants and greases, surfactants and detergents, and flavor and fragrances. The report examines not only how these segments compare in size, but also how their growth logic differs. Some applications are driven by industrial formulation requirements and process performance. Others are shaped by consumer-facing product trends, regulatory scrutiny, or downstream substitution dynamics.
By separating volume behavior from value behavior, the study helps clients identify where demand is structurally expanding versus where it is being reshaped by reformulation, certification, or regulatory compliance. That distinction is crucial for anyone planning product grades, packaging, or long-term offtake arrangements, because the same market size can hide very different underlying forces.
Competitive Landscape: Concentration, Capability, and Recent Moves
The 1-Decanol market is not fragmented in the way some commodity chemicals are. The report measures concentration and uses it to frame competitive behavior. The top three participants account for 42.5 percent of the market, while the top five collectively represent 61.8 percent. That level of concentration indicates that pricing, capacity signaling, and certification positioning can be influenced by a relatively small group of capable manufacturers, even as regional and application-specific niches create room for specialized players.
The study profiles the companies shaping this landscape, including BASF SE, Evonik Industries AG, KLK Oleo, Musim Mas Group, PT Sinar Mas Oleochemical, Eco Services Operations, LLC, and Godrej Industries Limited. Rather than offering generic corporate summaries, the report connects each profile to its strategic relevance in 1-Decanol: the applications it serves, the source pathway it emphasizes, and the geographic markets where its footprint matters most.
Recent company developments are integrated directly into the competitive analysis so that readers can interpret moves in context:
- In November 2024, KLK Oleo announced an expansion of fatty alcohol production capacity, including 1-Decanol, at its Seri Ulu Langat facility to meet Asia-Pacific demand.
- In September 2024, Evonik Industries received RSPO Mass Balance certification for sustainable 1-Decanol grades supplied to European markets.
- In June 2024, Musim Mas launched a high-purity 1-Decanol variant for pharmaceutical excipient applications.
These moves are not isolated news items. They illustrate three distinct strategic levers: capacity reinforcement in a high-growth region, sustainability certification to secure access to regulated demand, and grade specialization to enter higher-value application niches. The report evaluates each move in terms of its likely impact on regional supply balance, competitive positioning, and downstream procurement options.
Market Dynamics and External Pressures Shaping 2026 Outcomes
No forecast is useful if it ignores the environment in which it will play out. The research embeds market dynamics as active variables, not background commentary. Several developments are particularly relevant for 2026 planning.
Feedstock Volatility and Cost Exposure
Natural 1-Decanol production is closely linked to coconut oil and lauric acid markets. Coconut oil prices, a key feedstock for natural 1-Decanol, rose 12 percent to 1,450 per metric ton in the fourth quarter of 2025 due to supply constraints in the Philippines. At the same time, lauric acid, an upstream material for 1-Decanol hydrogenation, averaged 1,200 per metric ton FOB Indonesia in February 2026. These cost signals are presented in the report not as temporary noise, but as indicators of where margin pressure and sourcing resilience will be tested. The study maps how such movements affect the relative attractiveness of natural versus synthetic routes in different applications and regions.
Regulation and Compliance Timelines
Regulatory frameworks are becoming more prescriptive, and the report treats compliance as a strategic variable. EU REACH regulation requires 1-Decanol producers to submit updated exposure scenarios by the second quarter of 2026 for surfactant uses. That deadline has direct implications for suppliers serving European markets and for buyers who depend on those grades for downstream formulations. The analysis explains how submission requirements can affect time-to-market, grade availability, and the relative attractiveness of certified supply options.
The study also addresses labeling and consumer-product exposure. California Proposition 65 lists 1-Decanol for potential reproductive toxicity labeling in consumer products as of the 2025 update. While this does not equate to a blanket restriction, it introduces new considerations for formulation, risk communication, and product positioning in markets where consumer sensitivity and retailer standards are tightening. The report examines how such listings can alter demand patterns in sensitive applications without triggering broad market disruption.
Trade Policy and Regional Cost Structures
Trade measures continue to reshape cost competitiveness across regions. US tariffs on Chinese fatty alcohols, including 1-Decanol, increased to 25 percent under Section 301 in January 2026. For buyers and manufacturers with cross-border supply chains, this change alters landed-cost comparisons and may accelerate shifts toward alternative sourcing origins or regional supply partnerships. The report incorporates this development into its regional assessment so that teams can evaluate how tariff exposure interacts with existing logistics, certification status, and application requirements.
Worldwide 1-Decanol Market
What the Report Delivers: Practical Intelligence for Strategy Teams
The full research is organized to support concrete decisions rather than abstract observation. It combines market sizing, segmentation, competitive profiling, and environmental analysis into one integrated reference. The content is designed for use across strategy, procurement, sales, and compliance functions.
Key operational contents include:
- Historical market sizing and forecast pathways with explicit base year, historical coverage, and forecast horizon parameters
- Segment-level analysis by region, source, and application, presented with strategic interpretation rather than raw splits alone
- Company profiles that connect portfolio focus, geographic presence, and recent strategic actions to competitive impact
- A market concentration assessment that frames pricing influence, supply reliability, and niche positioning
- Integration of raw material trends, regulatory deadlines, and trade changes as decision-relevant variables
- Scenario-aware commentary that helps readers test how changes in feedstock costs, tariffs, or certification adoption could alter outcomes
The report is written for readers who need to move from insight to action. It does not simply describe the market; it explains where the leverage points are likely to be in 2026 and beyond, and where the risks of relying on outdated assumptions are greatest.
Who Should Use This Research and How
This study is most valuable for teams responsible for market entry, expansion, sourcing strategy, product grading, and regulatory readiness. For strategy leaders, it provides a structured view of where growth is concentrated and where competitive dynamics are intensifying. For procurement and supply chain teams, it offers context on source pathways, feedstock sensitivity, and the implications of certification and trade measures. For commercial and marketing teams, it clarifies application-side demand trends and the role of sustainability claims in securing preferred supplier status.
1-Octanol Market
The analysis is also intended to support coordination across functions. Because the report ties market structure to external pressures, it gives leadership a common reference point for discussing capacity commitments, supplier diversification, grade selection, and compliance timelines. That shared framework reduces the risk of decisions made in silos.
How to Read the Full Study for Maximum Value
The preview above highlights the structure and strategic logic of the research. What it does not do is expose the full density of the dataset. The complete report contains the detailed segmentation, regional interpretation, application-level trajectory, and company-specific intelligence needed to turn the macro view into operational plans. Those details matter because market growth is only useful when it is connected to where, how, and for whom it is occurring.
For teams preparing 2026 plans, the full publication provides the granularity required to evaluate sourcing trade-offs, anticipate regulatory impacts, and assess where competitor actions are likely to reshape supply and demand conditions. The macro figures establish the scale and growth rate of the opportunity. The segmented and company-level analysis explains how to position for it.
Closing Perspective
The Worldwide 1-Decanol Market research is built around a simple premise: in a market shaped by feedstock volatility, sustainability certification, trade policy, and regulatory deadlines, strategy quality depends on the depth of intelligence behind it. The market is expanding at a 6.5 percent CAGR through 2032, but the strategic story is not just about growth. It is about concentration, source pathways, application differentiation, and the external pressures that will determine which participants capture value most effectively.
This introduction offers the framework. The complete report delivers the full intelligence set needed to translate that framework into 2026 decisions. For organizations that need to move beyond general market awareness into precise, actionable planning, the full study is the next step.
For detailed analysis of this topic, please visit the official page: Worldwide 1-Decanol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com