

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Surface Water Measuring Instrument Market Hits $825.4M in 2025, Projects 6.72% CAGR to 2032

Strategic Intelligence for Surface Water Measurement: Navigating the 2026–2032 Market Landscape
As global water security concerns intensify and regulatory frameworks demand higher precision in hydrological data, the surface water measuring instrument market stands at a critical inflection point. The latest Worldwide Surface Water Measuring Instrument Market study from PW Consulting provides a comprehensive, forward-looking view of this evolving sector, equipping decision-makers with the analytical rigor required to capitalize on emerging opportunities through 2032. Grounded in historical performance data from 2020 to 2025 and projecting a detailed forecast period from 2026 onward, this research delivers actionable intelligence for executives, investors, and strategic planners operating across environmental monitoring, industrial water management, and public infrastructure domains.
Macro Market Trajectory: Sustained Expansion Anchored by Technological and Regulatory Catalysts
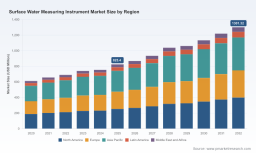
The global surface water measuring instrument market has demonstrated consistent revenue growth over the past half-decade, scaling from approximately 612.45 million USD in 2020 to an estimated 825.4 million USD in 2025. This trajectory reflects a compound annual growth rate of 6.72 percent across the forecast window extending to 2032, positioning the sector for continued expansion driven by infrastructure modernization, climate adaptation mandates, and the proliferation of real-time environmental monitoring networks. By 2032, market revenue is projected to reach 1.301 billion USD, underscoring the long-term commercial viability of precision hydrological instrumentation.
Several structural forces underpin this outlook. Municipalities and regulatory agencies are increasingly mandating continuous surface water monitoring to comply with evolving environmental standards, flood risk management protocols, and watershed protection initiatives. Simultaneously, industrial operators are investing in advanced effluent control and process water tracking to meet stricter discharge limits and operational efficiency targets. The integration of Internet of Things connectivity, low-maintenance radar sensing technologies, and multi-parameter data acquisition platforms has accelerated the replacement cycle for legacy gauging equipment, creating sustained demand across both public and private procurement channels. Corporate consolidation and targeted product launches further illustrate how market participants are refining their portfolios to capture higher-value monitoring segments while strengthening technical differentiation.
Concentration analysis within the competitive landscape also reveals a moderately fragmented yet increasingly strategic environment. The top three players account for approximately 31.5 percent of total market revenue, while the top five collectively represent 46.25 percent. This distribution indicates that while established incumbents maintain strong positioning through brand credibility, technical certifications, and long-standing agency relationships, there remains ample room for specialized innovators, regional integrators, and vertically focused manufacturers to capture niche demand. Understanding how these competitive dynamics evolve across product categories, application segments, and geographic regions will be essential for any organization seeking to optimize its market entry strategy, partnership roadmap, or procurement positioning.
The 2026 Decision Window: Why Timely Intelligence Matters Now
For enterprise stakeholders, the 2026 forecast period is not merely a numerical projection; it is a strategic planning anchor. Organizations evaluating capital allocation for environmental monitoring fleets, water infrastructure upgrades, or sensor technology integration must understand how demand patterns are expected to shift as climate resilience investments mature and regulatory pressure intensifies. This research is designed to reduce uncertainty in those decisions by mapping growth vectors across technology types, application domains, and regional deployment trends, enabling leadership teams to align product development, sales targeting, and supply chain planning with where demand is structurally expanding.
The strategic value of this study lies in its ability to connect high-level market momentum with operational realities. Decision-makers can use the analysis to assess whether their current instrumentation portfolios are aligned with the fastest-growing monitoring requirements, evaluate partnership or acquisition opportunities in a market where capability expansion is accelerating, and identify potential supply-side or demand-side risks that could affect pricing, lead times, or technology adoption curves. Rather than relying on broad sector narratives, the report delivers a structured framework for interpreting where competitive advantage will be earned over the next several years.
Inside the Research: Operational Content Built for Execution
This market study is structured as a decision-support tool rather than a static market summary. It integrates historical performance tracking with forward-looking scenario analysis, giving readers a clear view of how the market has evolved and where it is likely headed. The research methodology combines rigorous data triangulation with segmentation analysis that isolates the primary demand drivers shaping instrument procurement across multiple end-use environments.
Readers will find detailed coverage of the core instrument categories that define the market, including water level instruments, water quality sensors, flow and velocity meters, and integrated monitoring stations. Each category is examined through the lens of application demand, technology substitution trends, and procurement priorities, allowing stakeholders to understand not only which segments are expanding, but also why they are expanding and what specifications or capabilities are gaining preference. The report also maps application-driven demand patterns across hydrological monitoring and flood forecasting, agricultural irrigation management, environmental protection and research, and industrial process and effluent control, highlighting how distinct operational requirements influence product selection, deployment frequency, and long-term service expectations.
In addition to segmentation and demand analysis, the study explores the competitive architecture of the industry, profiling leading manufacturers and technology providers that are shaping market standards. These profiles assess each company's strategic positioning, technological focus, and recent activity, offering a practical reference for benchmarking, partnership evaluation, and competitive response planning. Recent corporate and product developments are integrated into the analysis to show how innovation cycles and consolidation activity are altering competitive dynamics in real time, rather than as abstract observations.
Regional perspective is provided to help stakeholders interpret where demand concentration is strongest and how deployment priorities differ across market environments. Rather than oversimplifying complex geographic trends, the analysis distinguishes among the major regions to clarify how local regulatory regimes, infrastructure investment cycles, and environmental monitoring needs shape instrument uptake. This regional framing is particularly valuable for organizations planning distribution expansion, localized product adaptation, or multi-market service strategies.
Competitive Landscape: Leading Companies Reshaping Market Standards
The surface water measuring instrument sector is defined by a mix of specialized instrument manufacturers, broad environmental monitoring providers, and established flow measurement companies. Each brings distinct strengths in sensor design, data acquisition architecture, durability under field conditions, and compliance alignment with agency accuracy expectations. Understanding these player profiles is essential for evaluating where procurement risk is lowest, where technology differentiation is most defensible, and where partnership or integration opportunities may offer the strongest return.
Campbell Scientific, headquartered in Logan, UT, USA, is recognized for rugged, unattended surface water monitoring systems designed for long-term deployment. Its portfolio includes radar water level sensors, pressure transducers, and dataloggers engineered to meet USGS Office of Surface Water accuracy requirements for rivers, lakes, and reservoirs, positioning the company as a trusted supplier for agency-grade hydrological monitoring. Solinst Canada Ltd., based in Georgetown, ON, Canada, manufactures high-quality surface water monitoring instruments spanning level measurement devices, dataloggers, and telemetry systems. Its recent expansion through the acquisition of Eureka Water Probes has strengthened its ability to deliver comprehensive water quality and level solutions within a unified monitoring framework.
Seametrics, operating under the TASI Flow Group and headquartered in Kent, WA, USA, designs and manufactures flow meters and submersible sensors for surface water, environmental, and water/wastewater monitoring applications, including electromagnetic and propeller meters. OTT HydroMet, based in Kempten, Germany, provides hydrological instrumentation for surface water level, flow, and flood monitoring, with radar level sensors and integrated flood monitoring systems tailored for streams, rivers, and tidal waters. In-Situ Inc., located in Fort Collins, CO, USA, specializes in water monitoring equipment for surface water level, quality, and flow, with solutions supporting coastal, estuarine, and harmful algal bloom monitoring requirements.
Badger Meter, headquartered in Milwaukee, WI, USA, offers flow measurement and level monitoring solutions, including SmartLevel Surface Level Monitoring, alongside water quality instrumentation for municipal and surface water applications. Xylem, based in Washington, DC, USA, provides surface water monitoring instrumentation through its YSI and Global Water brands, delivering level sensors, water quality probes, and multiparameter instruments for environmental and wastewater applications. Stevens Water Monitoring Systems, headquartered in Portland, OR, USA, has developed environmental data acquisition systems for hydrology and surface water resource management since 1911, reinforcing a long heritage in monitoring solution design. Aquaread Ltd., based in Broadstairs, Kent, UK, manufactures multi-parameter water quality testing equipment and water level and temperature loggers for surface water, groundwater, and wastewater monitoring. KISTERS, located in Aachen, Germany, supplies water and weather instrumentation, including sensors, data logging, and IoT technology for hydrology and surface water monitoring. Heron Instruments Inc., headquartered in Dundas, ON, Canada, produces premium water level meters, conductivity, temperature, and level meters, and related instruments for surface water and groundwater applications.
Competitive momentum in this market is not only a function of product breadth; it is increasingly shaped by targeted innovation and strategic consolidation. In February 2025, OTT HydroMet launched the OTT RLS 500, a next-generation smart radar level sensor using 80 GHz FMCW technology for accurate, low-maintenance surface water level measurements with ±2 mm accuracy. Shortly afterward, in April 2025, the company introduced the OTT Flood Monitoring System, integrating the OTT SensorLink 1000 IoT device with the OTT RLS 500 radar water level sensor to support flood monitoring and stream gauging in surface water applications. These releases illustrate how precision, connectivity, and reduced maintenance burdens are becoming central competitive differentiators in a market where uptime and data reliability directly influence procurement decisions.
Solinst Canada Ltd. also made a strategically significant move in February 2025 by acquiring Eureka Water Probes, effective February 1. This acquisition expanded its surface water monitoring portfolio with water quality probes and created tighter integration with its existing level and datalogger offerings. Such consolidation signals an industry-wide push toward more complete monitoring ecosystems rather than isolated instrument sales, a trend that procurement leaders and technology planners should monitor closely as they evaluate long-term supplier relationships and platform compatibility.
Market Dynamics and Structural Shifts Driving Demand
Beyond company-level activity, several structural dynamics are reshaping how surface water measuring instruments are specified, deployed, and valued. Regulatory expectations around measurement accuracy continue to influence sensor design, particularly for non-contact radar technologies used in river, lake, and reservoir monitoring. Accuracy requirements associated with USGS Office of Surface Water guidance, for example, are helping to steer adoption toward advanced radar sensor configurations that can deliver consistent performance in open-channel and still-water environments without the maintenance burden of submerged instrumentation.
Material durability is another critical factor influencing product selection in surface water environments. Water quality and level probes commonly utilize titanium or 316L stainless steel housings to provide corrosion resistance, with titanium often preferred for harsh or saline conditions. These material considerations are not merely engineering details; they affect total cost of ownership, service life, and suitability for deployment in challenging field conditions, all of which inform procurement strategy and risk assessment.
Water Analysis Instrumentation Market
At the same time, the broader shift toward IoT-enabled radar level sensors and integrated flood monitoring systems is expanding the value proposition of surface water instrumentation beyond standalone measurement. Real-time data delivery is increasingly central to flood warning, reservoir management, and watershed decision-making, making connectivity, remote telemetry, and data integration capabilities key components of competitive offerings. As a result, buyers are evaluating instruments not only on measurement performance, but also on how well the equipment integrates into broader monitoring networks and supports operational responsiveness.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Surface Water Measuring Instrument Market research from PW Consulting is designed to help organizations move beyond general market awareness and into precise, evidence-based planning. With historical data tracing performance from 2020 through 2025, a forecast horizon extending to 2032, and segmentation analysis covering instrument types, application areas, and regional dynamics, the study offers the depth required to support capital allocation, product strategy, competitive benchmarking, and acquisition or partnership evaluation.
In a market shaped by regulatory pressure, climate adaptation investment, and rapid innovation in sensor and connectivity technology, the organizations that succeed will be those that can interpret demand signals early and act on them decisively. This report provides the analytical foundation needed to make those decisions with confidence. To access the full segmentation detail, company-level assessments, regional growth pathways, and complete forecast tables that support targeted strategic planning, readers are encouraged to explore the complete research release on the PW Consulting website.
Worldwide Surface Water Measuring Instrument Market
For detailed analysis of this topic, please visit the official page: Worldwide Surface Water Measuring Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com