

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Glass Fiber Sizing Agent Market to Reach $1,059.21M by 2032, Growing at 6.18% CAGR

Strategic Imperatives in the Global Glass Fiber Sizing Agent Market: Navigating Growth and Innovation Through 2032
The glass fiber sizing agent market stands at a critical inflection point, driven by the escalating demand for high-performance composites across transportation, renewable energy, and advanced manufacturing sectors. As materials science evolves to meet stricter regulatory standards and performance thresholds, the role of sizing agents has shifted from a mere processing aid to a foundational element determining composite integrity, resin compatibility, and environmental compliance. This analysis synthesizes the trajectory of the market through 2032, highlighting the strategic nuances that decision-makers must address to capitalize on emerging opportunities.
Market Trajectory and Macroeconomic Context
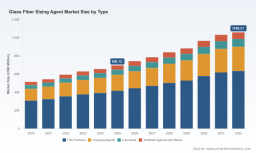
The global market for glass fiber sizing agents has demonstrated resilient expansion over the past half-decade, transitioning from a post-pandemic recovery phase into a sustained growth cycle. Valued at approximately 515.42 million USD in 2020, the market reached 696.12 million USD by 2025, reflecting a compound annual growth rate that underscores the sector's maturity and expanding application base. Looking ahead, the forecast period from 2026 to 2032 projects continued momentum, with the market size anticipated to approach 1.06 billion USD by the end of the decade. This growth is underpinned by a CAGR of 6.18 percent, signaling steady demand escalation rather than volatile spikes. Such a trajectory suggests that investments in sizing technology are no longer optional but essential for manufacturers aiming to secure supply chain stability and performance reliability.
Segmentation Dynamics: Type, Chemistry, and Application Drivers
Understanding the structural composition of the market reveals where value is being created and where competitive pressures are intensifying. The segmentation landscape is defined by distinct categories that reflect both historical usage patterns and emerging technological shifts.
Type-Based Segmentation
The market is broadly categorized by the functional role of the sizing agent. Film formers constitute the largest share of the market, reflecting their critical function in protecting glass fibers during processing and ensuring optimal adhesion to resin matrices. Coupling agents follow as a significant segment, vital for enhancing interfacial strength between inorganic fibers and organic polymers. Lubricants and antistatic agents, while smaller in volume, play indispensable roles in processing efficiency and safety, particularly in high-speed manufacturing environments. The interplay between these types dictates formulation strategies, with leading manufacturers often blending multiple functionalities to meet specific customer requirements.
Chemistry-Based Segmentation
Chemistry defines the performance envelope of sizing agents. Epoxy-based formulations lead the chemistry segment, driven by their prevalence in high-strength composite applications where thermal and mechanical stability are paramount. Polyurethane-based chemistries represent a robust secondary segment, prized for their versatility in both thermoset and thermoplastic systems, as well as their compatibility with waterborne formulations that align with environmental regulations. Polyester, polypropylene, and vinyl ester-based agents serve niche but critical roles, often selected for specific resin compatibility or cost-performance balances. The shift toward low-VOC and waterborne polyurethanes is particularly notable, reflecting industry-wide pressure to reduce emissions without compromising performance.
Application-Based Segmentation
The demand for sizing agents is inextricably linked to the health and direction of end-use industries. Transportation remains the dominant application driver, fueled by the lightweighting initiatives in automotive and aerospace sectors that rely on glass fiber-reinforced composites to improve fuel efficiency and reduce emissions. Wind energy stands as a second pillar of growth, with the expansion of turbine blade manufacturing requiring sizing agents that can withstand extreme environmental stresses while maintaining structural integrity during production. Aerospace and defense applications demand high-specification sizing solutions that meet rigorous certification standards. Construction and infrastructure, electrical and electronics, and industrial applications round out the demand profile, each imposing unique requirements on durability, processing speed, and chemical resistance. The diversity of applications suggests that suppliers must maintain a broad portfolio or specialize deeply to capture value in specific verticals.
Worldwide Glass Fiber Sizing Agent Market
Regional Analysis and Geographic Concentration
Geographically, the market exhibits a clear concentration of activity, with Asia Pacific commanding the largest share of revenue. This dominance is attributable to the region's massive manufacturing base, rapid industrialization, and significant investments in infrastructure and renewable energy. Europe and North America represent mature but steadily growing markets, where demand is driven by high-performance applications, stringent regulatory environments, and the presence of advanced composite manufacturers. Latin America and the Middle East and Africa, while smaller in absolute terms, offer pockets of growth aligned with specific industrial development and energy projects. The regional distribution highlights the importance of localized supply chains and formulation adaptations to meet varying regulatory and climatic conditions.
Competitive Landscape: Key Players and Strategic Positioning
The market is characterized by a moderately concentrated competitive environment. The top three companies account for approximately 38.45 percent of the market, while the top five firms capture around 56.12 percent. This concentration indicates that while consolidated players hold significant influence, there remains ample room for specialized competitors and regional players to carve out niches. The strategies of leading companies reveal distinct approaches to value creation, ranging from product innovation and regulatory compliance to global supply chain integration.
Glass Fibers Market
Company Profiles and Strategic Moves
Several key enterprises define the competitive contours of the industry. Celanese stands as a benchmark for quality in thermoset reinforcement, offering emulsion polymers such as Resyn and Vinamul for glass fiber sizing. Their products are supplied to producers across Europe, the Americas, and Asia, emphasizing superior handling and composite performance. Michelman provides a comprehensive suite of film-forming dispersions, binders, and lubricants, including the Hydrolube series and FGLASS X90, specifically engineered for chopped and continuous fiberglass. Their solutions optimize protection, adhesion, and compatibility with both thermoplastic and thermoset resins. Notably, in February 2026, Michelman introduced Hydrosize 1202, a single sizing solution designed to serve both chopped strand and continuous fibers across various types, signaling a push toward versatility and process simplification.
Evonik Industries supplies silane-based DYNASYLAN and VPS additives that are critical for glass fiber sizing and protection. Their products prevent breakage during high-speed production and enable strong bonding with polymer matrices, addressing key pain points in manufacturing efficiency and composite quality. BYK, part of the ALTANA Group, produces MAH-grafted polymers and film formers exclusively for glass fiber sizing of chopped strands and continuous fibers. Their offerings are distinguished by the lowest VOC content available, enhancing mechanical properties in polyolefin composites while maintaining regulatory compliance. Production capabilities span Europe, the USA, and China, supporting a global customer base.
Covestro contributes to the market with Baybond waterborne polyurethane dispersions, which function as film formers and crosslinkers for glass fiber sizing. These products are tailored for protection and adhesion in thermoplastic and thermoset composites, with specific grades approved for food contact, reflecting the growing intersection of composite materials and consumer safety standards. Great Eastern Resins Industrial, based in Taiwan, manufactures aqueous polyurethane dispersions for fiberglass sizing agents characterized by high solid content, low viscosity, and excellent chemical and weather resistance, catering to specialized formulation needs. Emsland Group offers starch-based sizing solutions, such as the Emglass series derived from pea and potato starches, primarily for pre-sizing and warp sizing of glass fibers in the electronics industry textiles sector. This diversification into bio-based options highlights a broader industry trend toward sustainable raw materials.
Industry Dynamics: Regulation, Raw Materials, and Innovation
The operational environment for glass fiber sizing agents is shaped by a confluence of regulatory pressures, raw material considerations, and technological innovation. Regulation plays a pivotal role, with the EU REACH legislation driving the development of compliant chemicals in sizing formulations. This regulatory framework aims to enhance human and environmental protection while maintaining the performance standards required by composite manufacturers. Compliance is no longer a checkbox but a strategic differentiator, influencing formulation choices and supply chain decisions.
In terms of raw materials, sizing formulations typically comprise water, silane coupling agents for glass, film formers, and a suite of additives including surfactants, plasticizers, anti-static agents, antifoams, and rheology modifiers. These components are applied at a concentration of 0.5 to 5 percent of the composite weight, making the efficiency and selection of sizing agents critical to the overall economics and performance of the final product. The industry is witnessing a pronounced shift toward waterborne polyurethane dispersions, which support low-VOC and food-contact compliance under standards such as EU 10/2011. This transition aligns with broader sustainability goals and customer demands for safer manufacturing environments. Furthermore, the adoption of MAH-grafted polymer film formers from suppliers like BYK exemplifies the push for lowest VOC content, demonstrating how chemical innovation can address both performance and environmental objectives simultaneously.
Strategic Value of Comprehensive Market Intelligence
For organizations operating in or adjacent to the glass fiber sizing agent market, the complexity of these dynamics necessitates a depth of intelligence that goes beyond surface-level data. The strategic value of a rigorous market study lies in its ability to translate macro trends into actionable insights. Decision-makers need to understand not just the size of the market or the headline CAGR, but the underlying forces shaping segmentation growth, the specific technological advancements that are resetting competitive benchmarks, and the regional nuances that affect supply chain resilience and market entry strategies.
A detailed analysis provides the granularity required to identify high-growth pockets within the application landscape, evaluate the threat posed by regulatory shifts on specific chemistries, and assess the positioning of competitors who are leveraging innovation to capture market share. The data on market concentration, for instance, hints at the competitive intensity and the potential for consolidation or fragmentation depending on how companies respond to trends like bio-based sizing or low-VOC formulations. Similarly, understanding the regional revenue distributions helps in prioritizing investment in manufacturing capacity, sales infrastructure, and R&D focus.
Conclusion: Positioning for the Future
The glass fiber sizing agent market is poised for sustained growth through 2032, driven by the structural demands of lightweighting, renewable energy expansion, and advanced material requirements. However, realizing value in this environment requires more than passive observation. It demands a proactive strategy that integrates regulatory foresight, chemistry innovation, and application-specific expertise. Companies that can navigate the trade-offs between performance, cost, and compliance will be best positioned to thrive. The insights contained within our full market research report offer the comprehensive roadmap needed to make these strategic decisions with confidence. By delving into the detailed segmentation analysis, competitive profiling, and regional breakdowns, stakeholders can uncover the specific opportunities and risks that will define their success in the coming years. The market is moving forward; the question is whether your strategy is aligned with the trajectory of innovation and demand that lies ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Glass Fiber Sizing Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com