

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Fire and Gas Detection Market Hits $7.5B in 2025, Driven by 6.5% CAGR to $11.65B by 2032

Strategic Intelligence for the Decade Ahead: Navigating the Global Fire and Gas Detection System Market 2026-2032
In an era where operational safety, regulatory compliance, and technological integration define industrial resilience, the fire and gas detection sector stands at a critical inflection point. For executives, investors, and engineering leaders charting strategy through the remainder of the decade, understanding the structural trajectory of this market is no longer optional—it is a prerequisite for risk mitigation and growth allocation. Our latest research publication, Worldwide Fire and Gas Detection System Market , delivers a comprehensive, data-backed assessment designed to translate macro-level momentum into actionable corporate strategy for 2026 and beyond.
Gas Detectors Market
This analysis does not merely project numbers. It maps the interplay between evolving safety standards, sensor innovation cycles, regional deployment pacing, and competitive positioning. By aligning historical performance with forward-looking modeling, the report equips decision-makers with the clarity required to prioritize capital, evaluate supply chain exposure, and anticipate where value creation will concentrate over the 2026–2032 forecast horizon.
Market Trajectory and Growth Architecture
The global fire and gas detection ecosystem has demonstrated consistent expansion over the past half-decade, underpinned by tightening occupational safety mandates, accelerated industrial automation, and heightened risk awareness in high-hazard environments. Historical tracking from 2020 through 2025 reveals a mature yet resilient revenue curve, with the market establishing a firm baseline as it enters the current forecast cycle.
Building on this foundation, our forward-looking modeling projects sustained valuation growth through 2032. The compound annual growth rate (CAGR) is estimated at 6.5 percent across the forecast window, reflecting steady demand pull from process industries, infrastructure modernization programs, and the integration of advanced detection platforms into broader safety instrumented systems. By 2026, projected revenue climbs to approximately 7,987.5 million USD, and the trajectory continues upward, reaching an estimated 11,654.91 million USD by 2032.
These figures are not abstract benchmarks. They represent converging investment signals: capital expenditure tied to facility compliance, retrofit cycles for aging detection infrastructure, and the gradual migration from legacy standalone alarms to networked, software-enabled monitoring architectures. The report dissects the structural drivers behind this arc, enabling leaders to separate cyclical noise from durable growth fundamentals.
Structural Segmentation and Value Concentration
Effective strategy requires understanding where revenue originates, how it is distributed across technology families, and which application verticals anchor demand. Our segmentation analysis isolates the primary axes that shape procurement behavior, pricing dynamics, and competitive targeting.
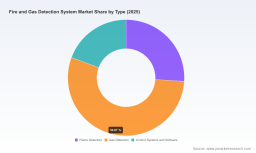
From a product architecture perspective, the market is anchored by gas detection solutions, flame detection hardware, and the control systems and software layer that orchestrates them. Gas detection continues to command the largest revenue share, reflecting the breadth of hazardous gas monitoring requirements across chemical processing, refining, and confined-space operations. Flame detection maintains a critical niche in high-speed fire scenarios, particularly where hydrocarbon, hydrogen, and outdoor exposure conditions demand rapid optical response. Meanwhile, control systems and software represent the integration layer that is increasingly dictating total cost of ownership, maintenance efficiency, and regulatory reporting capability.
Application-side, oil and gas remains the dominant deployment context, driven by the sector’s risk profile, asset density, and stringent process safety expectations. Industrial and manufacturing follows as a substantial demand center, where continuous production environments require reliable detection coverage and seamless integration with plant automation. Commercial and institutional facilities contribute a meaningful share as building safety codes evolve and multi-hazard monitoring becomes standard practice. Energy and power installations round out the application base, with detection systems supporting generation, transmission, and distribution infrastructure where uninterrupted monitoring is mission-critical.
Regional demand patterns further illuminate deployment priorities and supply chain considerations. North America maintains a leading revenue position, supported by mature industrial bases, active compliance ecosystems, and sustained capital programs. Asia Pacific represents a substantial and rapidly expanding footprint, shaped by industrialization scales, infrastructure build-out, and growing adoption of integrated safety systems. Europe continues to reflect high regulatory discipline and technology-led procurement, while Latin America and the Middle East and Africa contribute emerging growth vectors tied to energy development, mining activity, and industrial modernization initiatives.
Importantly, the market exhibits moderate-to-firm concentration among leading providers, with the top three firms accounting for an estimated 42.5 percent of revenue and the top five reaching approximately 58.75 percent. This concentration has strategic implications: it signals the presence of scaled platforms, established certification portfolios, and entrenched customer relationships, while also highlighting the space for specialized innovators and regional challengers to compete on technology differentiation, service models, and application-specific performance.
Competitive Landscape: Incumbents, Specialists, and the Innovation Race
The fire and gas detection market is defined by a layered competitive structure. Global incumbents bring breadth across hardware, software, and service networks. Mid-tier specialists and technology-focused players compete through sensor performance, detection range, and environmental resilience. Automation and building safety conglomerates extend the category by embedding detection into wider control and facility platforms.
Honeywell International Inc. continues to advance comprehensive fixed and portable fire and gas detection portfolios, spanning flame detectors, toxic and combustible gas sensors, and integrated safety solutions for oil and gas, chemical, and industrial use cases. MSA Safety Incorporated reinforces its industrial safety positioning with fixed gas and flame detection platforms, open path and ultrasonic gas detection capabilities, and integrated solutions aligned with standards such as NFPA. Drägerwerk AG & Co. KGaA brings specialized expertise in optical flame detection, multi-gas instruments, and fixed monitoring systems engineered for hazardous environments across maritime, oil and gas, and industrial settings. Emerson Electric Co. delivers detection as part of process automation and safety instrumented systems, with emphasis on integrated solutions for oil and gas and petrochemical operations. Siemens AG contributes fire detection and gas monitoring offerings, including Cerberus platforms for industrial and building applications, while ABB Ltd. supplies detection systems integrated with automation and control solutions for process safety. Johnson Controls International expands the addressable space through fire detection and suppression systems with gas detection capabilities within broader building and industrial safety portfolios. Autronica Fire and Security AS maintains a strong global footprint in detection systems tailored for maritime, oil and gas, and commercial sectors, and Teledyne Gas and Flame Detection provides advanced instruments and systems for industrial safety applications.
The competitive field also includes highly specialized providers that compete on performance engineering rather than scale alone. Fire & Gas Detection Technologies Inc. focuses on UV/IR and IR3 flame detectors designed for hydrocarbon, hydrogen, and high-speed industrial fires. ESP Safety Inc. concentrates on detection technologies and systems for hazardous environments, while Industrial Scientific emphasizes portable and fixed gas detection with connected safety and real-time monitoring capabilities.
Recent industry activity underscores the pace of differentiation. In June 2026, MSA Safety exhibited at the NFPA Conference & Expo with a session addressing NFPA 72 updates that integrate gas detection, open path gas detection, ultrasonic gas detection, and smoke detection technologies into fire alarm standards. In April 2026, Patol / Optect introduced the world’s first optically enhanced long-range flame detector, the LR16, targeting specialist fire detection applications. In February 2026, Macurco Gas Detection was scheduled to exhibit at the AHR Expo, showcasing gas detection systems for HVACR professionals. These developments illustrate a broader pattern: competition is increasingly won on sensor performance, integration readiness, standards alignment, and application-specific engineering rather than commodity hardware alone.
Worldwide Fire and Gas Detection System Market
Dynamics Shaping the Next Cycle
Several forces are converging to reshape procurement priorities and technology roadmaps across the fire and gas detection sector. Understanding these dynamics is essential for evaluating supplier selection, product lifecycle planning, and market entry timing.
Regulatory and standards evolution remains a primary demand catalyst. Stringent occupational safety requirements and industry-specific benchmarks, including API and IEC frameworks, continue to drive demand for reliable detection in high-risk sectors such as oil and gas and chemicals. At the same time, updates to fire alarm standards are increasingly incorporating gas detection, open path gas detection, ultrasonic gas detection, and smoke detection technologies, expanding the scope of integrated compliance and pushing end users toward multi-sensor architectures.
Technology advancement is accelerating along multiple vectors. Sensor development emphasizes miniaturization, IoT connectivity, wireless capabilities, and AI-enabled predictive maintenance. These capabilities are transforming detection from a passive alarm function into an active monitoring and diagnostics layer, reducing false alarms, extending service intervals, and enabling centralized visibility across distributed assets. The implications for lifecycle cost, uptime, and operator safety are significant, especially for organizations managing large, dispersed, or remote installations.
Raw material and component dependencies also influence supply chain strategy. Gas detection systems rely heavily on specialized sensors—including electrochemical, infrared, semiconductor, and catalytic types—whose manufacturing involves semiconductor materials and precision optics components. As demand scales and performance expectations rise, sourcing resilience, component qualification, and manufacturing precision become differentiators that affect lead times, reliability, and total cost of ownership.
The result is a market where value is increasingly determined by how well detection platforms connect to broader operational systems, how effectively they adapt to complex hazard profiles, and how efficiently they can be deployed, maintained, and upgraded over time. Companies that treat detection as a standalone accessory risk underinvesting in integration, while those that treat it as a core safety and data layer are better positioned to capture sustained demand.
What the Report Delivers for 2026 Decision-Makers
This market study is built to support concrete strategic action. Rather than providing a high-level overview, it delivers a structured intelligence framework that connects market sizing, segmentation, competitive behavior, and technology direction to business decision processes. Key practical components include:
- Detailed revenue tracking and forecast modeling across the 2026–2032 period, anchored in a 6.5 percent CAGR and supported by historical continuity from 2020–2025.
- Segment-level analysis covering type, application, and regional demand structures, clarifying where revenue concentrates and how deployment priorities differ by sector and geography.
- Competitive profiling of leading and specialized providers, with coverage of product orientation, application focus, and strategic positioning across the global landscape.
- Assessment of recent industry developments, including standards-related updates, product launches, and exhibition activity that signal near-term commercialization and compliance trends.
- Examination of market dynamics such as sensor innovation, connectivity adoption, predictive maintenance, regulatory integration, and component supply considerations.
- Concentration analysis that helps evaluate incumbent strength, barriers to entry, and opportunities for differentiation.
For corporate strategists, the report supports market entry evaluation, competitive benchmarking, and capital allocation planning. For technology and procurement leaders, it provides context on integration requirements, sensor technology direction, and standards alignment. For investors and analysts, it offers a structured basis for assessing growth durability, segment attractiveness, and the shifting balance between scale players and specialized innovators.
How to Use This Intelligence
The value of this research lies in its applicability. Leadership teams can use the forecast trajectory to test expansion assumptions, evaluate partnership opportunities, and stress-test revenue models against realistic demand pacing. Engineering and safety leaders can align architecture decisions with the direction of integration, connectivity, and multi-sensor compliance. Procurement and supply chain teams can use the segmentation and concentration insights to anticipate vendor dynamics, specification requirements, and sourcing constraints.
Most importantly, the study is designed to prevent decision-making in the dark. In a market where safety performance, regulatory expectations, and technological capability are evolving simultaneously, relying on fragmented information creates strategic exposure. A consolidated, forward-looking view enables organizations to act earlier, prioritize more precisely, and align investments with the segments and capabilities most likely to shape the next phase of market growth.
The complete report provides the full depth of segmentation data, detailed forecasts by segment and region, comprehensive competitive profiles, and extended analysis of market dynamics and recent industry developments. Organizations seeking to operationalize this intelligence for 2026 planning can access the full dataset and methodology through the source publication, where the complete intelligence package is available for download and review.
For detailed analysis of this topic, please visit the official page: Worldwide Fire and Gas Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com