

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smartphone Panel Market Hits $45.5B in 2025, Projected 5.19% CAGR to $64.9B by 2032

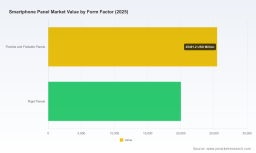
Strategic Intelligence for the 2026 Decision-Maker: Navigating the Worldwide Smartphone Panel Market
The global smartphone panel industry stands at a critical inflection point. As device manufacturers grapple with shifting consumer preferences, supply chain realignments, and accelerating technological transitions, the need for precise, forward-looking intelligence has never been greater. Our newly released Worldwide Smartphone Panel Market research study provides a comprehensive, data-driven roadmap for navigating this complex landscape through 2032. Designed specifically for executives, strategy teams, and procurement leaders, this report translates macro-level trajectories into actionable insights that can shape capital allocation, partnership strategies, and product roadmap decisions throughout 2026 and beyond.
The Macro Trajectory: Growth, Scale, and Structural Shifts
The worldwide smartphone panel market has demonstrated remarkable resilience and expansion over the past half-decade. Historical data from 2020 through 2025 reveals a steady upward trajectory, with the market climbing from approximately 40.85 billion USD in 2023 to an estimated 45.52 billion USD in 2025. This momentum is projected to continue, with the market reaching 47.89 billion USD in 2026 and advancing to 64.91 billion USD by 2032. The forecast period reflects a compound annual growth rate of 5.19 percent, signaling sustained demand driven by device refresh cycles, premiumization trends, and the ongoing integration of advanced display capabilities across diverse smartphone tiers.
For strategic planners, these figures represent more than headline numbers. They underscore a market where volume and value are increasingly decoupled from traditional growth drivers. The expansion is not merely a function of unit shipments but reflects deeper structural changes in how displays are engineered, manufactured, and deployed. Understanding the underlying forces that will sustain this trajectory requires granular analysis of technology transitions, regional supply dynamics, and competitive positioning—precisely the kind of intelligence embedded in our full study.
Report Architecture: What Strategic Leaders Will Find Inside
This research publication is structured to deliver immediate operational value alongside long-range strategic clarity. Rather than offering static snapshots, the report is built around dynamic analytical frameworks that enable readers to stress-test assumptions, benchmark performance, and identify emerging opportunities before they become mainstream. The study encompasses several interconnected dimensions that collectively paint a complete picture of the smartphone panel ecosystem.
Core Analytical Dimensions
- Technology segmentation analysis that tracks the evolution of display architectures, including the relative positioning of emissive and non-emissive panel types across premium, mid-range, and entry-level segments.
- Form factor transitions that examine the commercial and manufacturing implications of rigid versus flexible designs, with particular attention to how foldable and bendable configurations are reshaping production economics and consumer adoption curves.
- Geographic supply chain mapping that evaluates regional manufacturing concentrations, export-import dependencies, and the strategic implications of localized production investments by key industry participants.
- Competitive intensity assessment that profiles the strategic moves, capacity expansions, technology roadmaps, and partnership networks of leading panel suppliers, providing context for pricing dynamics and supply availability.
- Forward-looking scenario modeling that projects market evolution under varying assumptions about technology adoption rates, material availability, and regulatory developments, enabling teams to prepare for multiple plausible futures.
Each section is anchored by primary research, proprietary dataset integration, and expert interpretation, ensuring that readers receive not just raw figures but the strategic context necessary to act on them. The report also includes detailed methodology notes, data validation procedures, and clear definitions of all analytical parameters, guaranteeing transparency and reproducibility for internal decision-making processes.
Competitive Landscape: Dominance, Disruption, and Strategic Positioning
The smartphone panel sector is characterized by high concentration and intense rivalry. The top five suppliers collectively command more than 82 percent of market revenue, while the leading three firms alone account for approximately 68 percent. This concentration creates a landscape where a small number of players wield significant influence over pricing, capacity allocation, and technology standardization. Yet the competitive dynamics are far from static. Regional suppliers are expanding their technological footprints, established players are revisiting investment cycles, and new collaborations are reshaping the allocation of high-value orders.
Key Incumbents and Their Strategic Footprints
Samsung Display continues to anchor the premium segment with its advanced flexible and rigid AMOLED offerings. The company maintains a dominant position in high-end LTPO technology and supplies critical display components for flagship devices, including iPhone OLED implementations and foldable smartphones. Recent capacity reviews indicate potential additional investment to expand foldable OLED production, signaling continued confidence in the premium foldable trajectory. The firm has also demonstrated forward-looking technologies at major industry events, including privacy-enhancing display features and slidable screen concepts that hint at future smartphone form factors.
LG Display remains a major provider of OLED panels for smartphones, with particular strength in flexible AMOLED manufacturing and an expanding share of premium bar-type device supply. The company's focus on advanced OLED architectures positions it as a critical partner for manufacturers seeking to differentiate flagship products through display quality and innovation.
BOE Technology Group operates as the largest volume smartphone panel supplier globally, with extensive production capabilities spanning a-Si LCD, LTPS LCD, and flexible AMOLED technologies. The company's ability to serve mid-to-high-end devices, including iPhone OLED programs, underscores its integrated scale and technological breadth. The activation of a fifth Gen-8-plus OLED line reflects continued capacity expansion aimed at supporting broader smartphone and display production demands.
TCL China Star Optoelectronics Technology (CSOT) holds a significant position in LCD manufacturing while accelerating its AMOLED capabilities for both mid-range and flagship smartphone models. The company's partnerships and product integration milestones, including contributions to innovative subpixel architectures, highlight its growing relevance in advanced display supply chains.
Tianma Microelectronics focuses on LTPS LCD and AMOLED panels for small-to-medium device sizes, maintaining competitive offerings tailored to mid-range segments. Visionox Technology specializes in flexible AMOLED panels and continues to invest in higher-generation production lines for consumer electronics applications. These Chinese suppliers collectively reinforce the region's volume leadership while pursuing differentiated technological niches.
Beyond these major players, the competitive field includes numerous specialized manufacturers. AU Optronics (AUO) provides LCD solutions and is developing OLED panels for mobile applications. Innolux Corporation manufactures TFT-LCD panels primarily serving entry-to-mid-range smartphones. Japan Display Inc. (JDI) supplies advanced LCD and emerging OLED panels targeting premium and specialty applications, while Sharp Corporation produces LCD panels for mobile devices. HannStar Display Corporation offers TFT-LCD solutions for smartphones and related mobile applications, and HKC Corporation has grown as a supplier of a-Si LCD panels focused on entry-level devices. Together, these firms create a multi-tiered competitive environment where scale, specialization, and regional positioning all influence market outcomes.
Industry Dynamics and Emerging Pressures
The smartphone panel market does not operate in isolation. Recent developments and structural trends are reshaping supply-demand balances, cost structures, and strategic priorities across the value chain. Leaders must account for multiple overlapping forces when planning for 2026 and beyond.
Technology Adoption and Mid-Range Transformation
A notable acceleration is underway in the transition from LTPS LCD to AMOLED technologies within mid-range smartphone segments. Industry projections indicate that AMOLED panels are expected to capture a substantially larger share of total smartphone panel shipments in 2026, reflecting broader consumer acceptance, manufacturing efficiencies, and the desire of brands to differentiate products through display quality. This shift carries significant implications for panel suppliers, device manufacturers, and component procurement strategies. Companies that can navigate this transition—whether by expanding AMOLED capacity, optimizing LTPS LCD portfolios for residual demand, or developing hybrid supply approaches—will be better positioned to capture value as the technology mix evolves.
Worldwide Smartphone Panel Market
Supply Chain Vulnerabilities and Material Concentration
Critical raw materials and processing capabilities introduce important risk dimensions into panel market planning. China maintains dominant control over the processing of essential minerals such as indium, which is used in indium tin oxide (ITO) for touch layers and electrodes in smartphone displays, as well as gallium and germanium. Past and potential export restrictions on these materials have raised awareness of supply chain fragility and cost volatility risks for panel production globally. Indium tin oxide serves as a key conductive layer in touchscreens, and supply concentration in a limited number of processing hubs means that geopolitical developments, trade policy adjustments, or logistical disruptions can quickly affect production economics.
Compounding these material dynamics, regulatory scrutiny is intensifying. A U.S. Section 232 investigation into imports of processed critical minerals and derivatives, including those relevant to display manufacturing, has been ongoing through late 2025, with potential tariffs or import adjustments under consideration for national security reasons. These developments could influence sourcing strategies, cost structures, and the geographic distribution of panel manufacturing investments. For companies operating across multiple regions, understanding the interplay between material availability, regulatory trajectories, and supply continuity is essential for resilient planning.
Innovation Pathways and Future Form Factors
Beyond current production configurations, the industry is actively exploring next-generation display capabilities. Recent technology showcases have featured privacy-enhancing screen features, slidable display concepts, and improved flexible panel architectures that leverage polyimide substrates and ultra-thin glass to reduce crease visibility in foldable devices. These innovations suggest that the definition of mainstream smartphone displays will continue to expand, creating new requirements for materials science, manufacturing precision, and integration engineering. Companies that monitor these experimentation tracks and assess their commercial viability can anticipate shifts in consumer expectations and align their product development cycles accordingly.
Why 2026 Demands Precision Intelligence
The convergence of technology transitions, competitive intensity, supply chain reconfiguration, and regulatory uncertainty makes 2026 a pivotal year for strategic decision-making in the smartphone panel sector. Organizations that rely on fragmented data sources, outdated assumptions, or generalized market narratives risk misallocating resources, missing partnership opportunities, or underestimating competitive threats. In contrast, leaders who ground their strategies in comprehensive, validated, and forward-looking intelligence can move with greater confidence and precision.
Our Worldwide Smartphone Panel Market research study is designed to meet this need. It provides the analytical rigor required to evaluate investment priorities, the competitive context necessary to anticipate supplier and customer behavior, and the scenario frameworks that support agile planning in an environment where multiple outcomes remain plausible. Whether the objective is to optimize procurement strategies, assess entry or expansion opportunities in specific technology segments, benchmark against incumbents, or prepare for regulatory and material supply shifts, the report delivers the structured intelligence that executive teams require.
Worldwide Smartwatch Display Panel Market
Access the Full Intelligence Architecture
The insights summarized here represent only a fraction of the analysis contained in the complete study. Detailed segmentation trajectories, proprietary market sizing across technology and form factor categories, in-depth competitive profiles, scenario modeling outputs, and granular regional supply chain assessments are all integrated into the full report. To explore the complete dataset, access interactive analytical frameworks, and leverage the full strategic context for your 2026 planning, request the comprehensive Worldwide Smartphone Panel Market research publication. Equip your team with the depth of intelligence required to navigate a market defined by rapid innovation, concentrated competition, and evolving global dynamics.
For detailed analysis of this topic, please visit the official page: Worldwide Smartphone Panel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com