

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Saddle Chairs Market Hits $310.5M in 2025, Projected to Grow at 5.85% CAGR Through 2032

Strategic Outlook: The Saddle Chairs Market Through 2032
The global saddle chairs market is entering a phase of sustained expansion, driven by converging forces in ergonomic science, hybrid work adoption, and specialized healthcare requirements. At PW Consulting, our latest market research publication dissects this trajectory from 2020 through 2032, providing enterprise decision-makers with a rigorous, forward-looking framework to navigate procurement, product development, and competitive positioning. This article outlines the strategic architecture of the study, highlights the structural forces reshaping the landscape, and demonstrates how stakeholders can translate macro momentum into actionable advantage.
Macro Trajectory and Structural Context
Historical tracking reveals a market that has consistently outpaced general furniture trends. Between 2020 and 2025, total revenue climbed from approximately $245.2 million to $310.5 million, reflecting steady multi-year compounding rather than isolated spikes. Looking ahead, our forecast period (2026–2032) projects continued growth with a compound annual growth rate of 5.85%, positioning the market to reach roughly $462.27 million by 2032. This expansion is not merely a function of unit volume; it is structurally reinforced by rising institutional procurement of posture-optimized seating, the proliferation of sit–stand workstations, and a broader shift toward active sitting paradigms in professional environments.
Importantly, the growth pathway is unevenly distributed across segments and geographies, creating distinct pockets of opportunity and risk. Our analysis isolates the drivers behind these divergences while maintaining a disciplined focus on strategic implications rather than raw enumeration. Readers seeking complete segment-level breakdowns, regional revenue splits, and application-specific sizing will find those architectures fully detailed within the full report.
Intersecting Industry Dynamics
Supply-side realities and demand-side behavior are currently recalibrating the market’s operational rhythm. On the materials front, key cushion components such as polyurethane foam experienced supply constraints in early 2026, pressuring production costs and prompting manufacturers to refine sourcing strategies and cushion engineering alternatives. Regulatory monitoring for 2025–2026 indicates that ergonomic seating products continue to operate under standard furniture safety frameworks concerning stability and material compliance, with no sector-specific recalls recorded during the window. This regulatory clarity reduces friction for international distribution but simultaneously raises the baseline expectation for quality assurance and documentation.
From a demand perspective, the persistence of hybrid work models and the accelerating pairing of saddle chairs with standing desks are reshaping office furniture purchasing criteria. Procurement teams now weigh dynamic sitting benefits alongside conventional comfort metrics, expanding the addressable use cases for saddle-style seating beyond traditional clinical settings. These behavioral shifts are reinforced by end-user awareness of circulation, lumbar support, and fatigue reduction—factors that have moved from niche ergonomic claims to mainstream procurement considerations.
Segment Architecture and Application Divergence
The market’s composition reflects specialized design philosophies tailored to distinct end environments. Product offerings bifurcate around the presence or absence of a backrest, each aligning with different posture philosophies, workspace configurations, and user preferences. In practice, the no-backrest segment appeals to users seeking maximum pelvic mobility and unencumbered movement, while backrest-equipped variants address environments where additional lumbar reinforcement is prioritized during longer duty cycles.
Application-wise, medical and dental settings continue to represent a substantial share of demand, where saddle seating is leveraged for precision work, clinician ergonomics, and patient-proximity workflows. Office and commercial environments constitute another major demand cluster, increasingly influenced by activity-based working layouts and wellness-oriented procurement policies. Industrial and personal use forms a smaller but strategically distinct segment, with requirements centered on durability, adjustability, and compatibility with technical or protected-floor environments.
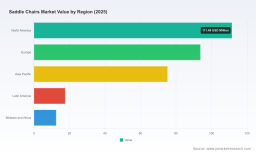
Regional demand patterns similarly reflect local workplace standards, healthcare infrastructure maturity, and furniture distribution dynamics. Our study maps these geographic nuances and identifies where localized pricing, channel access, and certification requirements create differentiated competitive conditions. The full report provides exhaustive segmentation tables and geographic breakdowns, enabling teams to model region-specific revenue potential and allocation scenarios.
Competitive Landscape and Strategic Positioning
The market remains moderately concentrated, with a compact group of internationally active manufacturers commanding a meaningful share of branded supply. Our analysis profiles the leading participants shaping product standards, channel relationships, and category perception. Notable players include Salli Systems, Score BV, HÅG (Flokk), Humanscale, Bambach Saddle Seat, Treston, Branch Furniture, ProNorth Medical, and RGP Dental. These firms span multiple headquarters regions and bring differentiated value propositions ranging from split-seat designs and dynamic sitting mechanics to specialized healthcare-focused ergonomics and sustainable material sourcing.
Strategic differentiation in this space rarely hinges on a single attribute. Instead, competitors are building advantage across several axes simultaneously:
Lift Chair Market
- Design architecture that targets spinal alignment, circulation, and reduced musculoskeletal strain for prolonged professional use.
- Manufacturing and sourcing strategies that balance performance requirements with cost stability amid variable material availability.
- Segment-specific productization, particularly in dental, medical, and technical industrial applications where duty cycles and hygiene considerations shape feature decisions.
- Go-to-market execution through direct channels, distributor networks, and professional practice partnerships that reinforce category credibility.
Recent corporate activity illustrates how the competitive set is adapting to these priorities. In October 2024, ProNorth Medical introduced a saddle stool aimed at medical applications, emphasizing posture improvement, comfort, and productivity gains. Later, in September 2025, Score published content on optimal dental practice setup that positioned its saddle chair solutions within broader clinical workflow discussions. These moves reflect a broader pattern in which incumbents invest in both product refreshes and educational content to shape specification behavior among professional buyers.
Concentration metrics indicate that the top participants collectively hold meaningful but not monopolistic share, leaving room for challenger brands, regional specialists, and design-led entrants to compete on niche performance, regional service, or material innovation. Our report evaluates the strategic maneuvering space available to each tier of participant and the conditions under which share shifts are most likely to occur.
Inside the Report: What Decision-Makers Will Find
This market study is engineered for strategic application rather than passive reference. Beyond top-line sizing, the document delivers an operational toolkit for planning, investment, and risk mitigation across the forecast horizon. Core contents include:
- Historical market reconstruction (2020–2025) with revenue progression and momentum drivers across the category.
- A five-year forecast (2026–2032) anchored in a defined growth rate, with scenario considerations for demand adoption, input cost variability, and regulatory stability.
- Segment-by-segment analysis spanning type distinctions, application verticals, and regional demand profiles, with explanatory context for where growth concentrates and why.
- Competitive profiles covering headquarters location, core product philosophies, target environments, and public-facing positioning for the principal market participants.
- Recent corporate developments and content moves that signal shifting emphasis in product strategy, professional education, and end-user engagement.
- Environmental and operational factors including material supply considerations, safety standard expectations, and evolving usage habits tied to hybrid work and active sitting.
- Strategic decision support for procurement planning, product roadmap prioritization, channel strategy, and specification targeting in high-value verticals.
Throughout the study, numerical precision is paired with interpretive context so that readers can assess not just what the market is doing, but how the underlying mechanics may influence operating decisions over time. The full publication provides complete segmentation structures and granular market values that are intentionally reserved for the comprehensive report experience.
Why This Research Matters for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to this market face a narrow window to align strategy with the next phase of category maturation. Procurement teams must weigh evolving ergonomic expectations against cost volatility and supply chain responsiveness. Product leaders need clarity on which posture features, adjustability options, and material choices will best match the demands of medical, office, and industrial use cases. Executives evaluating market entry, expansion, or partnerships require a realistic view of concentration dynamics, regional opportunity, and the specification behaviors that determine professional adoption.
Our research is designed to support these decisions with a single, coherent view of market size, growth path, segmentation logic, and competitive behavior. It connects macro momentum to operational reality by explaining where demand is structurally strongest, how leading firms are positioning themselves, and which external factors—materials, standards, and work habits—are likely to influence execution over the forecast period. The result is a planning foundation that can inform everything from volume commitments and channel investments to feature prioritization and vertical-specific go-to-market tactics.
Conclusion: From Macro Momentum to Advantaged Execution
The saddle chairs market offers a distinctive combination of ergonomic relevance, application specificity, and steady long-term growth. The trajectory from 2020 through 2032 signals a category that is expanding on the strength of specialized utility rather than broad commodity replacement. For firms seeking to participate in this expansion, the strategic question is not simply whether demand is rising, but where value is being created, how incumbents are defending their positions, and which operational variables will determine execution quality in the years ahead.
PW Consulting’s full market research publication delivers the depth required to answer those questions with confidence. It integrates historical context, forward forecast, competitive profiles, and environmental dynamics into one structured intelligence package. Readers who require complete segmentation figures, regional revenue distributions, and exhaustive market breakdowns will find those elements comprehensively presented in the full report. Access the complete study to translate market momentum into a tailored, execution-ready strategy for 2026 and beyond.
Saddle Chairs Market
For detailed analysis of this topic, please visit the official page: Saddle Chairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com