

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Rail Components Market Reaches $72.45 Billion in 2025 to Hit $99.6 Billion by 2032 at 4.65% CAGR

Strategic Intelligence for the Railway Era: Inside the Worldwide Rail Components Market 2026-2032
Executive Overview
The global railway components sector stands at a critical inflection point. As governments and private operators accelerate fleet modernisation, signalling digitisation, and heavy-haul capacity expansion, procurement leaders face a complex matrix of material volatility, evolving regulatory mandates, and shifting demand centres. Our latest Worldwide Rail Components Market study is designed to cut through this complexity, delivering a decision-ready intelligence framework that maps revenue trajectories, competitive positioning, and structural catalysts across the decade. Rather than offering static snapshots, the report translates historical momentum into forward-looking scenario planning, enabling executives to align capital allocation, supply chain resilience, and partnership strategy with verified market mechanics.
The Trajectory of Global Market Expansion
Historical revenue patterns reveal a market that has demonstrated remarkable resilience amid macroeconomic turbulence, supply chain realignments, and fluctuating infrastructure budgets. From 2020 through 2025, worldwide components revenue climbed from approximately 58.12 billion USD to a base-year level near 72.45 billion USD, reflecting sustained maintenance backlogs, fleet renewal cycles, and targeted public investment in high-capacity corridors. The forecast window extends through 2032, anchored by a compound annual growth rate of 4.65 percent and a projected end-period valuation approaching 99.6 billion USD. This trajectory is not linear; it is shaped by procurement pacing, delivery lead-time normalisation, and the interplay between legacy fleet upkeep and next-generation platform adoption. Readers examining the full report will encounter granular year-by-year revenue mapping that isolates organic volume growth from pricing effects, enabling precise budget forecasting and sensitivity testing across multiple procurement horizons.
Regionally Anchored Demand Patterns
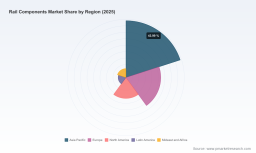
Market activity does not distribute uniformly across geographies. Asia Pacific continues to command the largest absolute revenue share, driven by high-speed network rollouts, metro system expansions, and domestic manufacturing scale. Europe maintains a substantial footprint shaped by cross-border interoperability requirements, signalling modernisation, and regulated tender cycles. North American component consumption remains tightly coupled to freight network efficiency programmes, heavy-haul infrastructure upgrades, and locomotive fleet optimisation. Latin America and the Middle East & Africa collectively represent growing but structurally distinct opportunity pools, often influenced by concession models, sovereign funding priorities, and targeted component substitution initiatives. The complete study breaks down regional revenue architecture without oversimplifying local procurement realities, mapping demand intensities, delivery channel preferences, and policy-driven procurement windows. Decision-makers requiring jurisdiction-specific pricing contexts, tender cycle timing, and regional supplier concentration metrics will find the full dataset essential for market entry, sourcing diversification, and partnership sequencing.
Worldwide Rail Components Market
Component Architecture and Train-Type Demand Correlations
The components landscape is defined by technical specialisation, lifecycle economics, and platform compatibility. Bogie and wheelsets constitute the largest component revenue segment, reflecting their centrality to ride quality, load distribution, and track interface performance. Propulsion and power systems follow closely, underscoring the industry-wide shift toward electrification, energy-efficient traction designs, and integrated power management architectures. Braking systems maintain a robust share, propelled by safety regulation mandates, friction material innovation, and retrofit demand on mature fleets. Interior and body structures, alongside couplers and ancillary hardware, round out the component palette, each responding to tailored operational profiles and route-specific performance requirements. Demand further diverges by train type, with passenger rolling stock capturing the broadest revenue pool, freight wagons sustaining steady procurement tied to logistics volume and wagon lifecycle replacement, and locomotives reflecting concentrated but high-value expenditure on traction, control, and reliability upgrades. Our full analysis dissects these relationships with component-level revenue mapping, technical substitution trends, and platform-specific procurement drivers, allowing engineering and sourcing teams to align specification strategies with verified demand patterns rather than generalised assumptions.
Competitive Dynamics in a Consolidated Landscape
The supplier ecosystem is characterised by meaningful concentration, yet it remains highly differentiated by technical capability, geographic reach, and vertical integration depth. Industry concentration metrics indicate that a relatively small group of multinational players commands a substantial share of total revenue, creating a market environment where scale, certification portfolios, and platform-standard compliance heavily influence winning positions. Alstom maintains a broad components portfolio spanning bogies, braking solutions, pantographs, couplers, and signalling-related hardware, with a strong foothold across both passenger and freight applications. Siemens Mobility reinforces its position through electrification, signalling, automation, and traction component offerings that increasingly intersect with digital rail operations. Wabtec Corporation and Knorr-Bremse compete at the core of braking, friction, and auxiliary system markets, while voestalpine Railway Systems holds notable influence in rail profiles, switches, turnouts, and track-side monitoring solutions. Thales contributes critical signalling, communication, and security technologies that increasingly shape component specification by enabling interoperability and operational automation. CRRC Corporation Limited and Hitachi Rail extend competitive pressure through high-speed and freight traction components, digital signalling integration, and large-scale platform supply capabilities. Additional specialists such as Lucchini RS, Greenbrier Companies, Trinity Industries, Titagarh Rail Systems, Stadler Rail, Nippon Steel, and ArcelorMittal Rails & Accessories reinforce the market with focused expertise in wheelsets, freight car structures, underframes, regional bogie designs, premium rail steels, and global infrastructure profiles.
Recent Catalyst Events Reshaping the Supplier Landscape
Recent corporate activity demonstrates how quickly competitive advantage can be reconfigured through product launches, strategic acquisitions, certification wins, and platform-level joint development. Siemens Mobility advanced driverless operational readiness by introducing GoA4 automation platform components for unattended rail operations, signalling a structural shift toward higher levels of automation in metro and regional contexts. Knorr-Bremse expanded its compact braking footprint by acquiring VYC Industrial, strengthening its portfolio for metro vehicle brake calipers and related subsystems. voestalpine achieved AREMA certification for its 390HH premium rail, reinforcing its eligibility for North American heavy-haul deployments and illustrating how standards compliance directly unlocks market access. Wabtec secured a supply agreement with Union Pacific for Trip Optimizer software and friction products, highlighting the growing intersection between digital optimisation tools and mechanical component supply. Alstom formalised a joint development agreement with Indian Railways to develop indigenous bogie designs, reflecting a broader push toward localisation, design sovereignty, and platform-specific engineering partnerships. The complete report places these events within a structured competitive analysis, mapping each move to market share implications, capability expansion, and downstream procurement effects.
Rail Market
Regulatory, Material, and Sustainability Forces Redefining Procurement
Beyond vendor dynamics, external forces are reshaping specification priorities, cost structures, and delivery planning. Raw material pressures remain a persistent concern, with pearlitic rail steel prices climbing year over year in Europe as energy costs and input volatility continue to influence alloy pricing. At the same time, demand for bainitic rail steels has risen for high-speed applications, reflecting performance requirements that reward durability and reduced maintenance overhead. On the regulatory front, the EU TSI LOC&PAS framework mandates ERTMS Baseline 3 compliance for new signalling components from 2025, creating a clear technical threshold that influences specification cycles and supplier qualification. In the United States, FRA requirements for PTC 2.0 interoperability introduce additional interoperability expectations across Class I networks, affecting both onboard and wayside component planning. From a trade and sustainability angle, the EU Carbon Border Adjustment Mechanism introduces meaningful cost implications for imported rail steel with embedded carbon intensity beginning in 2026, prompting procurement teams to reconsider sourcing geography, material certification, and lifecycle carbon accounting. The full study translates these dynamics into actionable procurement implications, linking regulatory deadlines, material pricing trends, and sustainability requirements to real-world sourcing and specification decisions.
What the Study Delivers for Strategic Decision-Makers
This research is built for executives, procurement directors, engineering leads, and competitive intelligence teams who require more than headline figures. The report integrates revenue forecasts, historical baselines, segmentation architecture, concentration metrics, and company-level profiling into a cohesive market operating picture. Readers will gain access to component-level demand mapping, train-type revenue correlations, regional consumption structures, and supplier capability comparisons, all organised to support scenario planning and internal alignment. The study also captures recent corporate developments that matter for sourcing strategy, including automation platform introductions, acquisition-driven capability expansion, standards-based certification milestones, major contract awards, and joint development agreements that signal localisation trends. By connecting these events to broader market structure, the report helps teams evaluate not just where revenue is heading, but who is best positioned to capture it and under what procurement conditions.
Conclusion: Why This Intelligence Matters for 2026 and Beyond
The worldwide rail components market is moving through a period where technical compliance, material economics, regional procurement rhythms, and competitive consolidation all influence winning strategy. For organisations planning fleet investments, component sourcing, platform specification, or market expansion, the difference between reactive and proactive decision-making lies in the quality of the underlying intelligence. Our Worldwide Rail Components Market study provides that foundation, combining verified market sizing, structured segmentation, competitive profiling, and regulatory context into a decision-ready format. To access the complete dataset, detailed segmentation breakdowns, and full company-level analysis, we invite readers to visit the source page and download the full report. In a market defined by long asset lifecycles and fast-moving specification requirements, timely intelligence is not an accessory to strategy; it is the basis of it.
For detailed analysis of this topic, please visit the official page: Worldwide Rail Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com