

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Machine Tool Control Transformer Market to Hit $1,228.67M by 2032, 4.6% CAGR

Strategic Intelligence for the 2026 Corporate Agenda: Unlocking Latent Growth in Machine Tool Control Transformers
Navigating Macro Realities with Precision Data
As industrial manufacturing enters a phase of structural recalibration, the machine tool control transformer segment presents a unique blend of steady demand durability and hidden operational volatility. Our Worldwide Machine Tool Control Transformer Market study, anchored in a 2025 base year with historical tracking from 2020 to 2025 and a forward-looking trajectory extending through 2032, equips executive teams with the analytical scaffolding required to make informed, forward-looking decisions in 2026. The global market reached an estimated USD 896.84 million in 2025, having weathered a brief contraction in 2024 before resuming its upward momentum. Projections place the market at approximately USD 948.61 million in 2026, cascading toward a terminal valuation of USD 1,228.67 million by 2032. This long-arc expansion is underpinned by a compound annual growth rate of 4.6 percent, a figure that belies the underlying segmentation dynamics, pricing pressures, and engineering trade-offs that will define procurement strategies, capacity planning, and partnership decisions in the near term. For leadership teams operating at the intersection of automation investment, supply chain resilience, and cost optimization, the report delivers the contextual clarity necessary to move beyond headline figures and into actionable strategy.
Worldwide Machine Tool Control Transformer Market
Why This Study Matters for 2026 Decision-Making
The 2026 operating environment is characterized by intersecting forces: rising input costs, regional competitiveness shifts, and tightening automation cycles across discrete manufacturing. Machine tool control transformers sit at a critical juncture in factory electrical architecture, converting power to safe, stabilized voltages that enable motor starters, control relays, PLCs, and instrumentation to function reliably. Because these components are embedded in both legacy equipment retrofits and next-generation CNC and assembly-line deployments, demand does not simply track macro manufacturing output; it reflects nuanced decisions around maintenance cycles, production line modernization, and the replacement of aging electromagnetic control components. Understanding how the market is evolving across phase configurations, end-user applications, and geographic jurisdictions is no longer optional. The report maps these structural drivers with a granularity that supports scenario planning, contract negotiation, and product positioning. Rather than presenting a static snapshot, the analysis contextualizes historical performance from 2020 to 2025, identifies inflection patterns that shaped the 2024 correction, and walks through the 2026 to 2032 forecast window as a series of manageable, testable hypotheses. This framing allows procurement, engineering, and commercial teams to align internal assumptions with external market behavior before committing capital or renegotiating vendor terms.
Architecture of the Report: What Practitioners Can Deploy Immediately
The study is constructed to bridge high-level market intelligence with operational relevance. It opens with a consolidated market sizing and trend narrative, then layers in segmentation analysis across phase type, end-user application, and regional distribution. A dedicated competitive landscape section profiles key participants, comparing positioning, product-family breadth, compliance orientation, and engineering specialization. The report also integrates an input-cost and regulation mapping module designed to help readers anticipate margin shifts and compliance exposure rather than react to them after the fact. Each section includes structured takeaways intended for immediate transfer into business planning workflows, including demand-cycle interpretation, sourcing strategy mapping, and product-mix evaluation. By keeping the segmentation themes distinct yet interconnected, the document enables readers to trace how a change in one dimension, for example, regional procurement norms or phase configuration preferences, reverberates through pricing, specification requirements, and aftermarket service considerations. The emphasis throughout is on decision-useful clarity: enough analytical structure to support investment and sourcing choices, without reducing the market to oversimplified averages.
Segmentation Dynamics: Where Demand Is Concentrating
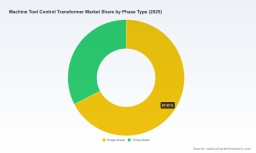
The demand base for machine tool control transformers is distributed across distinct configurations and use environments, each carrying different implications for specification, volume, and value capture. Across phase architectures, single-phase units have historically commanded the larger revenue share, reflecting their prevalence in control circuits for a broad range of industrial machinery and their alignment with common step-down requirements in distributed control panels. Three-phase configurations occupy a meaningful secondary position, typically associated with higher-power control applications and more demanding production-line environments. In end-user application terms, metal cutting machine tools represent a substantial demand anchor, consistent with the precision, repeatability, and electromagnetic stability requirements of CNC and machining centers. Metal forming machine tools contribute a significant second pillar, driven by press and stamping operations where control reliability intersects with equipment uptime and operator safety. Special purpose machines round out the application landscape, encompassing specialized automation and bespoke equipment where custom voltage transformation and inrush handling become differentiators. Geographically, the market spans multiple industrial regions, each with different competitive density, local compliance expectations, and procurement rhythms. The report examines how these regional and application-pattern differences interact with pricing sensitivity, specification customization, and lead-time tolerance, enabling readers to identify where demand resilience is structural and where it is more exposed to cycle risk.
Competitive Landscape: Strategic Posture Among Core Players
The market features a diversified set of manufacturers whose strategies reflect differing priorities in product architecture, compliance positioning, customization capacity, and geographic footprint. Hammond Power Solutions stands out in North America as a significant dry-type transformer manufacturer, offering molded machine tool industrial control transformers engineered for high inrush conditions across machine tools, conveyors, robotics, and production-line equipment. Its legacy molded styles also address electromagnetic components such as relays and solenoids, reinforcing breadth across control-circuit use cases. MCI Transformer Corporation operates from the United States with a focus on catalog and custom industrial control transformers designed to deliver low, safe control voltages for motor starters, timers, and similar electromagnetic devices, emphasizing adherence to stringent industry regulations. Controlled Magnetics provides a wide custom range from 100 VA to 500 kVA, targeting stepped-down voltages for machine tool control devices while highlighting inrush handling, energy efficiency, electrical isolation, and compliance with standards such as ANSI/NEMA ST-1, UL, and CSA for factory automation and machinery. SNC Manufacturing Co., Inc., now part of Allient Inc., produces single- and three-phase control transformers with step-up and step-down capabilities across specified primary and secondary voltage ranges and 50/60 Hz operation, supported by custom engineering services for industrial control circuits. Micron Industries contributes industrial control transformer offerings, including series designed for machine tool and industrial applications. PowerVolt Group Inc. designs and produces high-efficiency, UL-listed and CSA-certified control transformers for factory automation, industrial equipment, and machine tool control panels, with an emphasis on certification readiness and efficiency. Murrelektronik, with global operations anchored in Germany, offers isolation and control transformers suited to industrial and machine tool contexts. In Asia, Lushan China produces single-phase industrial control transformers for stepped-down voltages and high inrush applications, while ZHENGXI manufactures low-voltage dry-type machine tool control transformers in the 40 VA to 2500 VA range for CNC machines, automation panels, and industrial control. CNC Electric Group also competes in the Chinese market with control transformers developed using German technology for AC 50 to 60 Hz circuits. Boardman Transformers in the UK and SolaHD in the United States complete the landscape with offerings tailored to control circuits and special mounting requirements, respectively. The study examines how these players differentiate themselves through engineering focus, compliance profiles, customization capabilities, and regional presence, and it frames the competitive dynamics in terms of potential partnership, sourcing diversification, and specification strategy.
Cost Structure and Input Dynamics: The Margin Equation Under Pressure
Transformer economics are increasingly shaped by raw material trajectories and their interaction with design choices, order volumes, and regional sourcing flexibility. Copper remains a primary input for control transformers, and its price behavior directly affects production cost structures. In early 2026, copper prices briefly exceeded USD 14,500 per tonne intraday, with mid-year forecasts averaging near USD 12,075 per metric ton for the year, reflecting supply constraints and continued demand pull from electrification. At the same time, electrical steel costs have nearly doubled since 2020, driven by supply shortfalls and rising energy expenses, reinforcing cost-pressure dynamics across transformer manufacturing. Because grain-oriented silicon steel and copper together account for a substantial share of material costs in comparable transformer categories, these movements carry direct implications for pricing, margin management, and vendor negotiations. The report translates these input conditions into practical discipline for 2026 planning, emphasizing the need to evaluate specification trade-offs, volume commitments, and alternative sourcing pathways with an understanding of how material volatility may affect delivered cost over the contract horizon. It also contextualizes these pressures within broader electrification demand trends, helping readers separate cyclical price spikes from structural input-cost shifts that may persist into the forecast window.
Regulatory Context: Navigating Exemptions with Strategic Clarity
Regulatory frameworks can significantly influence testing, certification, and compliance planning, especially for components that sit close to the boundary between industrial control and distribution equipment. Importantly, U.S. Department of Energy energy conservation standards for distribution transformers explicitly exclude machine-tool control transformers from the definition and efficiency requirements. The latest final rule, published in April 2024, sets compliance obligations for covered distribution transformers beginning April 23, 2029, leaving machine-tool control transformers outside that direct mandate. Similarly, the California 2025 Energy Code exempts machine-tool control transformers from low-voltage dry-type distribution transformer certification requirements under Title 20 Appliance Efficiency Regulations. These distinctions matter because they shape how suppliers structure product documentation, how buyers evaluate efficiency claims, and where compliance resources are best allocated. The report consolidates this regulatory landscape so that engineering, quality, and procurement teams can avoid over-applying distribution-transformer assumptions to control-transformer procurement, while still tracking future rule-making that could shift the boundary over time. For companies operating across multiple jurisdictions, this clarity supports more precise compliance roadmaps and more informed evaluation criteria for both standard and custom units.
How to Use This Intelligence: From Market Map to Execution
The study is designed to feed directly into planning cycles, sourcing reviews, and competitive positioning discussions. Readers can use the segmentation and regional analysis to pressure-test demand assumptions, identify where application-specific requirements justify specification premium, and assess where procurement strategies may benefit from supplier diversification or regional nearshoring. The competitive profiles help teams benchmark their own product or sourcing positions against the broader field, highlighting where customization capability, certification readiness, or inrush-handling performance may function as competitive differentiators. The input-cost and regulatory sections provide a basis for more robust commercial modeling, enabling earlier identification of margin-risk scenarios and more disciplined compliance planning. Throughout, the report encourages a disciplined approach: use the macro trajectory and structural segmentation to frame expectations, then layer in the operational details that determine how a market-sized opportunity becomes a realized advantage in a specific product line, region, or customer segment.
A Note on Depth, Data Access, and the Next Step
This overview is intended to signal the scope, rigor, and practical orientation of the full study while preserving the detailed segmentation tables, regional breakdowns, and company-specific competitive metrics for the complete report. The strategic value of the analysis lies not only in aggregate market direction but in the way the study connects macro sizing, application and phase dynamics, regional demand patterns, input-cost pressure, and regulatory context into a single decision framework. For organizations preparing 2026 investment, procurement, or product strategy decisions, that integrated view is the difference between reacting to market headlines and anticipating the mechanics that drive them. The complete Worldwide Machine Tool Control Transformer Market report extends this foundation with the full segmentation detail, competitive comparison depth, and forecast scenarios needed to translate intelligence into execution. We invite decision-makers to access the full report to obtain the complete datasets and analytical structure required to support confident, well-timed strategic action.
Machine Tool Bearing Market
For detailed analysis of this topic, please visit the official page: Worldwide Machine Tool Control Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com