

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Photosensitive Resin Market Hits $6.75B in 2025, Expands at 12.45% CAGR to 2032
By pmarketresearch, 2026-09-16
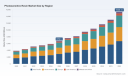
Strategic Horizons in the Photosensitive Resin Market: Navigating the 2026–2032 Growth Cycle
The global photosensitive resin market is entering a pivotal phase of expansion, driven by converging forces in advanced manufacturing, electronics miniaturization, and stringent sustainability mandates. For corporate decision-makers, capital allocators, and product strategists operating in 2026, understanding this trajectory is no longer optional—it is a prerequisite for competitive positioning. Our newly released Worldwide Photosensitive Resin Market research provides a structured, data-grounded framework for translating macroeconomic momentum into actionable commercial strategy. This introduction outlines the market's architectural shifts, highlights the operational intelligence embedded in the full report, and demonstrates why timing and precision matter as the industry moves through its next growth cycle.
Between 2020 and 2025, the sector demonstrated consistent upward momentum, expanding from approximately 3,885 million USD to 6,750 million USD. That historical arc establishes a clear baseline of demand intensification across multiple end-use verticals. Looking ahead, the forecast window from 2026 through 2032 projects a compound annual growth rate of 12.45 percent, with total revenue anticipated to surpass 15,000 million USD by the close of the period. These figures are not merely indicators of volume; they reflect structural upgrades in material performance, application diversification, and geographic redistribution of manufacturing capacity. For leadership teams, the implication is straightforward: strategies anchored to legacy demand profiles will rapidly lose relevance as performance-grade formulations and specialty chemical architectures capture disproportionate value.
Macro Trajectory and the 2026 Decision Window
The transition from historical expansion to forward-looking growth is characterized by a shift from commoditized photopolymer supply toward engineered resin systems that meet tighter tolerances in thermal stability, mechanical elongation, and regulatory compliance. The 2026–2032 forecast period coincides with a wave of product introductions, capacity expansions, and environmental standard adjustments that collectively reshape procurement economics. As production capacity for UV-curable resins continues to scale, particularly across Asia Pacific, the cost environment for critical inputs such as photoinitiators and oligomers has moderated. This moderation does not uniformly translate into margin expansion, however, because raw material volatility remains a persistent variable. Acrylate monomers, a foundational derivative in photocurable systems, experienced price swings of roughly forty percent in 2023 due to shelf-life constraints and supply chain disruptions. The lesson for procurement and R&D leadership is that cost optimization must be paired with formulation flexibility and supplier diversification.
Worldwide Water Washed Photosensitive Resin Market
At the same time, regulatory trajectories in the United States and European Union are accelerating the adoption of lower-toxicity and higher-recyclability resin formulations. Compliance is becoming a market-access requirement rather than a differentiator, and companies that anticipate certification pathways early will secure faster time-to-market for next-generation grades. Over the past year, resin developers introduced more than 120 new photopolymer grades, including heat-resistant variants rated above 150°C and flexible formulations with elongation reaching 25 percent. This pace of innovation signals that performance envelopes are widening rapidly, allowing photosensitive resins to penetrate applications previously dominated by thermoplastics or engineered elastomers. Decision-makers evaluating portfolio expansion or M&A targets should therefore weigh not only current volume but also the capability to iterate formulations at scale.
Structural Demand Drivers Across High-Growth Verticals
Market growth is being propelled by a cluster of application domains that share a common need for precision patterning, rapid curing, and material customization. Additive manufacturing continues to anchor demand, with 3D printing workflows increasingly relying on specialized photopolymer formulations for prototyping, tooling, and end-use part production. The electronics and printed circuit board segment represents another durable demand pillar, as miniaturization and high-density interconnect requirements push substrate and imaging materials toward finer resolution and improved adhesion characteristics. Dental and medical applications contribute a substantial and fast-evolving share of demand, driven by biocompatible grades, regulatory clearances, and the expansion of digital dentistry workflows. Automotive and aerospace applications, while currently representing a smaller revenue base, are gaining strategic importance as lightweighting initiatives and complex geometry requirements create new openings for stereolithography and high-resolution curing technologies.
Rather than treating these verticals in isolation, the full report maps cross-segment dependencies, substitution risks, and pricing sensitivities. This is critical because photosensitive resin demand is rarely linear; it responds to equipment adoption cycles, regulatory milestones, and downstream OEM specification changes. A formulation that performs well in laboratory conditions may face commercial friction if its curing profile is incompatible with production-line throughput, or if its material cost structure undermines total cost of ownership for the end customer. The research therefore emphasizes application-level economics, procurement seasonality, and the interplay between printer or exposure-system capabilities and resin chemistry.
Worldwide Photosensitive Resin Market
Competitive Dynamics and Strategic Positioning
The competitive landscape reflects a broad geographic and technological spread, with active participants spanning China, Japan, the United States, Austria, and the Netherlands. Several manufacturers have concentrated their efforts on LCD, MSLA, and DLP 3D printing ecosystems, engineering resin grades optimized for resolution, surface finish, and mechanical reliability. Others are building portfolios around UV curing chemistry for broader industrial use, while a distinct group of Japanese and global materials specialists continues to dominate photoresist and electronics patterning applications for semiconductor and display manufacturing. This dual-track structure—additive manufacturing resins on one side and semiconductor-grade photosensitive materials on the other—creates both competitive tension and partnership opportunities, especially as additive processes move closer to production-grade certification.
Recent corporate activity illustrates how rapidly the field is evolving. In mid-2025, one materials company expanded its UV-curable resin sales channels while reporting growth in its specialty and performance materials segment, underscoring the shift toward higher-margin formulations. More recently, another supplier disclosed a significant year-over-year increase in post-consumer recycled resin sales within photoresist and related materials activities, reflecting the growing commercial relevance of circular-content strategies. In product development, a major paper and materials group advanced a biomass-derived photoresist intended for advanced semiconductor patterning, signaling that sustainability-driven chemistry is moving from concept to tangible R&D pipelines. Meanwhile, a leading dental resin supplier secured regulatory clearance for a next-generation clear dental material, reinforcing the importance of compliance milestones in unlocking clinical and commercial adoption. These events are not isolated; they form a pattern in which channel expansion, recycled-content integration, biomass chemistry, and regulatory certification are becoming central levers of competitive advantage.
Market concentration data further contextualizes strategic choices. The three largest participants collectively account for approximately 38.4 percent of revenue, while the top five firms represent roughly 52.15 percent. This level of concentration suggests that scale, distribution reach, and formulation IP remain decisive, but it also leaves meaningful space for specialized players to compete through performance differentiation, regional partnerships, or application-specific certification. The strategic question for 2026 is not whether to participate, but how to position a product roadmap that can withstand raw material volatility, meet evolving compliance expectations, and align with the technical requirements of high-growth end markets.
What the Full Report Delivers for 2026 Strategy Teams
The complete Worldwide Photosensitive Resin Market study is designed to support concrete decisions rather than abstract trend-watching. It consolidates historical performance data, forward forecasts, and segmentation insights into a usable strategic structure. Readers will find a detailed examination of resin types, application categories, and regional demand patterns, with emphasis on the factors that determine where value is created and where margin pressure intensifies. The report also integrates supply-side dynamics, including capacity trends, raw material input sensitivity, and the impact of environmental and safety standards on formulation adoption.
In addition to quantitative modeling, the research provides a structured competitive scan that profiles companies across the additive manufacturing and electronics materials spectrum. Each profile is evaluated in the context of product specialization, application coverage, and recent commercial or regulatory developments, allowing strategy teams to benchmark capabilities, identify potential partnership candidates, and assess vulnerability to substitution. The study further incorporates industry-context intelligence on raw material volatility, capacity expansion, new grade introductions, and sustainability-oriented product development, ensuring that forecasts are anchored in operational realities rather than idealized assumptions.
For teams planning capacity investments, formulation roadmaps, sales-channel expansion, or market-entry assessments, the report offers a consolidated view of where growth is most concentrated and where competitive intensity is likely to rise. It is structured to support scenario comparison, procurement planning, and product positioning discussions without requiring readers to reconcile disconnected data sources or reconcile conflicting market narratives.
Why the 2026–2032 Window Demands Precision Intelligence
The photosensitive resin market is expanding, but expansion alone does not guarantee profitability or market share gains. The sectors capturing the strongest momentum are those where material performance, regulatory readiness, and application integration align. Companies that treat resin selection as a commodity decision will face increasing pressure from suppliers offering differentiated grades with clearer certification pathways, more stable curing behavior, and better alignment with downstream manufacturing constraints. Conversely, organizations that invest early in application-specific formulations, supplier redundancy, and compliance foresight will be better positioned to convert market growth into sustainable margin.
This research was built to reduce uncertainty in exactly those areas. It connects the macro growth trajectory with the operational details that determine commercial outcomes: which resin categories are gaining traction, which applications are driving specification changes, which competitive moves are reshaping channel dynamics, and how raw material and regulatory shifts are altering the cost and risk environment. By consolidating these layers into a single analytical framework, the study enables leadership teams to make more informed choices about R&D prioritization, capital deployment, and market focus.
For a complete view of segmentation detail, competitive profiling, regional momentum, and forward forecasts, the full Worldwide Photosensitive Resin Market report is available through our research portal. The document is intended for strategy, product, and procurement teams that need a reliable basis for 2026 decision-making and for planning across the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Photosensitive Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Security Camera Market Hits $1.45B in 2025, Poised for $3.91B by 2032 at 15.3% CAGR
By pmarketresearch, 2026-09-16
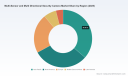
Beyond Blind Spots: Strategic Imperatives in the Global Multi-Sensor and Multi-Directional Security Camera Landscape
The physical security industry has crossed a definitive threshold. For decades, surveillance relied on single-lens optics that forced trade-offs between coverage area and detail resolution. Today, the paradigm has shifted toward intelligent, multi-sensor architectures capable of eliminating blind spots while delivering forensic-grade clarity across wide-area environments. As enterprises and public entities navigate an increasingly complex threat landscape in 2026, investing in the right surveillance infrastructure is no longer a maintenance decision; it is a core component of operational resilience and strategic risk management.
The market has demonstrated remarkable momentum over the past five years. From a baseline of 712.45 million USD in 2020, the sector accelerated through the pandemic recovery period, reaching 1,447.53 million USD by 2025. This trajectory reflects a compound annual growth rate of 15.26 percent, signaling sustained demand that shows no signs of plateauing. Forecasts project the market to expand significantly through 2032, surpassing substantial valuation milestones as technological convergence accelerates adoption across diverse environments. However, recognizing headline figures is only the first step. Understanding the granular drivers, competitive maneuvers, and compliance frameworks that shape this growth is where true strategic advantage is realized.
PW Consulting's latest Worldwide Multi-Sensor and Multi Directional Security Camera Market report provides the comprehensive intelligence necessary to navigate this evolution. As a decision-maker in 2026, you require more than historical context. You need precise forecasting, segmentation depth, and competitive analysis to allocate capital, select partners, and anticipate regulatory shifts. This article serves as an executive overview of the landscape, highlighting the structural dynamics and industry developments that define the current moment, while outlining the actionable insights available in our full study.
The Momentum Behind the Expansion
The growth trajectory of multi-sensor and multi-directional camera adoption is underpinned by a convergence of technological maturity and expanding use cases. Over the historical period from 2020 to 2025, the market expanded rapidly, driven by decreasing hardware costs, improved processing power at the edge, and the urgent need for comprehensive visibility in post-pandemic operational models. The surge from 2023 to 2025 particularly underscores a transition from pilot projects to scaled deployments in critical environments.
Looking ahead to the forecast period of 2026 through 2032, the projected CAGR suggests that the market will more than double in size from its 2025 baseline. This expansion is not merely a function of increased camera shipments. It is fueled by the integration of artificial intelligence, the demand for seamless panoramic views without mechanical moving parts, and the necessity to reduce infrastructure complexity by covering multiple zones with a single device. Organizations are increasingly recognizing that multi-sensor solutions offer a lower total cost of ownership despite higher unit costs, due to reduced cabling, simplified mounting, and fewer failure points compared to multiple single-lens units.
Yet, the aggregate numbers tell only part of the story. The distribution of this growth varies significantly based on technology types, end-user priorities, and geographic maturity. Understanding which segments are driving the highest value density versus volume is critical for supply chain planning and product portfolio alignment. Our full report dissects these nuances without the ambiguity often found in broader industry summaries, providing the clarity needed to prioritize investments effectively.
PTZ Camera Market
Architectural Shifts: Types and Applications
The market is segmented into distinct camera architectures, each addressing specific operational requirements. Multi-sensor fixed cameras represent a substantial portion of the ecosystem, offering high-resolution stitched views for static wide-area monitoring. Multi-directional adjustable cameras provide flexibility for environments where focus areas may change seasonally or operationally, allowing remote reconfiguration without physical intervention. Meanwhile, multi-sensor PTZ hybrid cameras combine the benefits of panoramic context with the magnification capabilities of pan-tilt-zoom functionality, catering to applications requiring both broad situational awareness and detailed investigation capabilities.
On the demand side, end-user segmentation reveals where the pressure for advanced surveillance is most acute. Public infrastructure and smart city initiatives continue to be a primary catalyst, leveraging these technologies for traffic management, public safety, and urban monitoring. Commercial and retail enterprises are increasingly adopting multi-sensor solutions to protect high-value inventory, ensure customer safety, and optimize operational analytics. Transportation hubs and logistics centers utilize these cameras to monitor complex cargo areas and secure perimeters efficiently. Additionally, industrial and energy facilities require robust imaging solutions capable of withstanding harsh environments while providing continuous oversight of critical assets.
Each of these segments carries unique requirements regarding resolution, low-light performance, weather resistance, and integration capabilities. A generic deployment strategy often fails to optimize return on investment. By analyzing the specific value drivers within each end-user category and technology type, organizations can tailor their procurement strategies to match their operational realities. The detailed breakdowns within our market study illuminate these preferences, helping stakeholders identify where the highest growth opportunities lie for their specific business models.
Worldwide Multi-Sensor and Multi Directional Security Camera Market
Competitive Arena and Strategic Moves
The competitive landscape is characterized by a mix of established security giants, specialized imaging innovators, and regional powerhouses. Market concentration data indicates that the top three competitors hold a significant share, while the top five collectively command a majority of the market. This concentration suggests an environment where scale, brand reputation, and ecosystem integration play vital roles, yet there remains ample room for specialized players who introduce disruptive technologies or niche compliance solutions.
Key incumbents such as Hanwha Vision, Axis Communications, i-PRO, Avigilon, and Pelco maintain strong positions through continuous innovation and robust global support networks. Hanwha Vision, based in Seoul with significant Americas operations, has been actively pushing the boundaries of onboard AI processing. Notably, in November 2024, the company unveiled a new 4-channel AI multi-sensor camera featuring WAVE VMS powered by the NVIDIA Jetson platform. This development delivered substantial AI performance capabilities for serverless recording and onboard analytics, signaling a strategic shift toward edge intelligence that reduces reliance on centralized servers.
Axis Communications in Sweden continues to offer flexible multidirectional and multisensor panoramic options that appeal to integrators seeking interoperability and ease of configuration. i-PRO, operating globally from Osaka, specializes in multi-directional PTZ solutions with edge AI and advanced imaging for challenging conditions, emphasizing AI auto-tracking features that enhance active monitoring. Avigilon, as part of Motorola Solutions, delivers AI-powered multi-sensor cloud cameras with adjustable sensors, focusing on high-security applications where coverage of multiple distinct areas from a single mount is essential.
In the Americas, Pelco and Rhombus Systems have strengthened their market presence through compliance-focused portfolios. Pelco recently updated its product catalog in March 2026 to include NDAA-compliant multisensor camera lineup enhancements, addressing a critical requirement for government and enterprise deployments in the US market. Rhombus Systems offers cloud-managed 20MP multisensor cameras with PoE++ installation and strict compliance standards, targeting organizations that prioritize ease of management and regulatory adherence. OpenEye provides ONVIF-compliant HD multisensor cameras that support interoperability, a key factor for heterogeneous security ecosystems.
Other notable players such as Digital Watchdog, Honeywell, and Bosch Security contribute diverse product lines ranging from panoramic IP cameras with easy image stitching to high-resolution multi-imager sensors with advanced analytics. Honeywell's Series 20MP multi-sensor cameras emphasize smart analytics and low-light performance for wide-area surveillance. Bosch Security provides FLEXIDOME multi and panoramic series with AI capabilities, catering to the European and global markets with a focus on high-quality imaging.
Regional manufacturers like Hikvision, Dahua Technology, and Vivotek offer extensive multi-sensor panoramic options, including models with motorized lenses and WDR capabilities. Hikvision's PanoVu and TandemVu series, along with Dahua's WizMind multi-sensor panoramic cameras, provide high-definition stitched views for 180° and 360° coverage. Vivotek delivers multi-sensor panoramic cameras with IR capabilities, addressing varied environmental needs. ACTi, based in Taipei, released a 2026 Q1 product matrix highlighting panoramic and multi-imager solutions with NDAA options, reflecting the ongoing adaptation to regulatory landscapes. AV Costar and ACTi continue to pioneer surround video and multi-imager options for wide-area coverage in both indoor and outdoor settings.
Recent developments illustrate the pace of innovation. Beyond the specific launches mentioned, the industry is witnessing a broader trend where hardware specifications are increasingly becoming table stakes, and differentiation is emerging through software integration, analytics accuracy, and compliance readiness. Companies are updating catalogs and product matrices to ensure alignment with evolving standards, ensuring that deployments remain viable in a tightening regulatory environment.
Regulatory Headwinds and Market Dynamics
The operational environment for multi-sensor security cameras is heavily influenced by regulatory frameworks. As of 2026, NDAA compliance remains a key requirement for many government and enterprise deployments in the US market. Organizations procuring surveillance equipment for federal projects, public infrastructure, or sensitive enterprise environments must verify that hardware and software components meet these standards. The regulation has reshaped sourcing strategies, pushing integrators and end-users to prioritize vendors who can provide clear compliance documentation and maintain updated product lines accordingly.
Furthermore, international dynamics continue to play a role. US export controls and restrictions involving certain foreign entities influence the sourcing of security camera components and systems. This has led to a bifurcated market where compliant supply chains are valued at a premium, and organizations must balance cost considerations with risk mitigation. Multi-sensor cameras must also adhere to ONVIF standards for interoperability, ensuring that devices from different manufacturers can communicate within a unified network video system. Compliance with these protocols is essential for scalable deployments and future-proofing security infrastructure.
These regulatory factors do not merely constrain the market; they also create opportunities for vendors who can demonstrate robust compliance and transparency. Companies that proactively address these requirements in their product development cycles are better positioned to capture high-value segments. The interplay between regulation and technology adoption is a dynamic area that requires constant monitoring, as shifts in policy can rapidly alter procurement eligibility and market access.
Navigating 2026 and Beyond
For strategic leaders, the multi-sensor and multi-directional security camera market represents both a significant investment and a critical enabler of safety and efficiency. The data indicates a clear upward trajectory, but realizing the full value of this growth requires detailed intelligence. Decision-makers must evaluate not only the hardware specifications but also the long-term implications of vendor partnerships, the total cost of ownership across the device lifecycle, and the alignment of technology with specific operational use cases.
The insights presented in PW Consulting's Worldwide Multi-Sensor and Multi Directional Security Camera Market report go beyond surface-level analysis. We provide investors, manufacturers, integrators, and end-users with the granular data needed to make informed decisions. This includes precise market sizing for relevant segments, detailed competitive profiling, and forward-looking assessments of technological trends. Our research is designed to answer the questions that general industry briefs leave open, such as the relative performance of specific camera types in different operational contexts, the strategic implications of market concentration, and the evolving impact of compliance requirements on procurement choices.
To access the full depth of this analysis, including detailed segmentation data and comprehensive profiles of key industry players, we invite you to explore the complete market research. Understanding the nuances of this rapidly evolving landscape is essential for securing a competitive edge in 2026 and beyond. The complete intelligence is available through our official research portal, where you can download the full report and leverage these insights to drive your strategic initiatives forward.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Sensor and Multi Directional Security Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Microbial Fuel Cell Market to Hit $37.23M by 2032 with 11.25% CAGR
By pmarketresearch, 2026-09-16
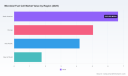
Strategic Intelligence for the Next Decade: Inside the Worldwide Microbial Fuel Cell Market Outlook 2026-2032
The global transition toward decentralized, energy-positive infrastructure has reached a decisive inflection point. Microbial fuel cell (MFC) technology, once confined to academic laboratories and conceptual pilots, is now positioned as a commercially viable bridge between wastewater management, biosensing, and distributed power generation. As industrial operators, municipal planners, and venture capital allocators navigate an increasingly complex regulatory and sustainability landscape, the need for rigorous, forward-looking market intelligence has never been more critical. This analysis introduces our newly published Worldwide Microbial Fuel Cell Market research, a comprehensive strategic assessment designed to equip executive teams with the analytical frameworks required to make confident capital allocation, partnership, and product development decisions throughout the 2026-2032 forecast horizon.
Our research anchors its trajectory analysis in a five-year historical baseline spanning 2020 through 2025, capturing the market's evolution from early-stage validation to structured commercial scaling. The global MFC market established a foundational valuation of USD 10.45 million in 2020, progressed to USD 11.34 million in 2021, reached USD 12.74 million by 2022, and climbed to USD 13.75 million in 2023. Accelerated deployment activity and growing institutional interest drove the figure to USD 15.8 million in 2024, with the base year evaluation settling at USD 17.65 million in 2025. Looking ahead, the forecast window projects sustained expansion, beginning at USD 19.93 million in 2026, advancing to USD 21.28 million in 2027, USD 24.17 million in 2028, USD 26.88 million in 2029, USD 29.52 million in 2030, USD 32.67 million in 2031, and ultimately reaching USD 37.23 million by 2032. This growth pathway reflects a compound annual growth rate of 11.25 percent, signaling a structural shift rather than a cyclical anomaly. The figures underscore an industry transitioning from grant-dependent experimentation to revenue-generating deployments, yet they also reveal the scale of opportunity that remains untapped without disciplined strategic positioning.
Navigating the Structural Dynamics Shaping Commercial Viability
Technological maturity and regulatory tailwinds are converging to redefine the operational boundaries of microbial fuel cells. Recent efficiency benchmarks documented by the U.S. Department of Energy's Bioenergy Technologies Office indicate that advanced MFC architectures now deliver power densities approaching 5 W/m³ within continuous-flow wastewater reactors. This performance threshold transforms MFCs from passive treatment adjuncts into active energy recovery assets, particularly for facilities processing high-strength organic effluents. At the same time, material economics remain a pivotal variable. Industry sourcing data from late 2024 places carbon cloth electrode pricing between USD 45 and USD 75 per square meter, reinforcing the importance of lifecycle cost modeling and surface-area optimization in system design. Capital planners who overlook electrode durability, replacement cadence, and reactor geometry risk overestimating net energy yields and mispricing total cost of ownership.
Worldwide Microbial Fuel Cell Market
Regulatory momentum further amplifies the commercial case. The European Union's Urban Waste Water Treatment Directive 91/271/EEC continues to mandate energy-efficient treatment solutions, creating a policy-aligned pathway for MFC integration into secondary treatment workflows. Municipalities and industrial operators seeking compliance while reducing grid dependency are actively evaluating bioelectrochemical alternatives that combine chemical oxygen demand removal with simultaneous electricity generation. However, deployment realities temper enthusiasm with operational pragmatism. Current commercial constraints restrict most field installations to pilot-scale configurations operating below 1 kW, primarily due to electrode fouling dynamics and the inherent limitations of low power output at smaller scales. Organizations must therefore structure their adoption roadmaps around modular scaling, targeted use-case validation, and phased capital exposure rather than assuming immediate full-capacity substitution of conventional treatment infrastructure.
What the Report Delivers: Operational Frameworks for Decision-Makers
Our Worldwide Microbial Fuel Cell Market study is engineered to translate macroeconomic trajectory into actionable corporate strategy. The publication provides a multi-dimensional breakdown of market architecture, examining how technological configurations, application verticals, and regional deployment patterns interact to shape competitive positioning. Readers gain access to granular demand-driver analysis that isolates the operational and regulatory catalysts influencing adoption velocity across wastewater treatment facilities, biosensing deployments, power generation initiatives, and adjacent use cases. The research maps the technology readiness curve, identifies integration bottlenecks, and evaluates the economic logic of mediator-less versus mediator-based architectures without reducing complex engineering trade-offs to simplistic rankings.
Beyond top-line sizing, the report delivers a comprehensive competitive landscape assessment, profiling the strategic footprint, technological differentiators, and commercialization readiness of key market participants. It examines partnership ecosystems, deployment models, and the operational philosophies that distinguish early movers from late-stage entrants. The analysis further incorporates scenario-building frameworks that enable strategic teams to stress-test investment assumptions against variables such as electrode material pricing volatility, regulatory tightening timelines, and scaling constraints. Executive summaries, technical evaluation matrices, and go-to-market pathway assessments are structured to support cross-functional alignment between engineering, finance, and business development teams.
Competitive Landscape: Strategic Positioning Among Emerging Leaders
The microbial fuel cell sector is characterized by a concentrated yet highly differentiated competitive field. Market concentration metrics indicate that the top three firms command a combined share of 38.5 percent, while the top five operators collectively control 52.15 percent of total market revenue. This distribution reveals an industry where established players have secured meaningful footholds, yet substantial white space remains for agile entrants and collaborative ecosystem builders. Understanding the operational mandates and technological philosophies of these core companies is essential for organizations evaluating supply partnerships, licensing opportunities, or direct market entry.
Worldwide Marine Fuel Cell Market
Aquacycl Ltd., headquartered in Didcot, United Kingdom, has built its commercial narrative around the USABR bioelectrochemical reactor platform, specifically engineered for energy recovery from high-strength industrial wastewater streams. The company's value proposition centers on transforming treatment liabilities into measurable energy assets, appealing to industrial operators seeking to reduce both discharge compliance costs and external power consumption. Plant-e B.V., based in Wageningen, Netherlands, pursues a distinct technological pathway by commercializing plant-microbial fuel cell systems that extract electricity from organic matter released through plant root systems via electro-active bacteria. This approach positions the firm at the intersection of green infrastructure, urban landscaping, and low-voltage power generation, opening niche deployment opportunities in environmentally integrated settings.
Microbenergy S.L., operating from Valladolid, Spain, emphasizes modularity and decentralized deployment through its BEE-BOX unit architecture, which couples wastewater treatment functionality with simultaneous electricity generation in a containerized or skid-mounted format. The modular approach addresses a critical market need: scalable implementation for remote facilities, decentralized industrial parks, and municipalities that require phased capacity expansion without massive civil engineering commitments. Nijhuis Saur Industries, headquartered in Doetinchem, Netherlands, contributes to the competitive field with its BeeVe membrane-free bioelectrochemical wastewater treatment system, which applies microbial fuel cell principles to chemical oxygen demand removal and energy production. By eliminating membrane dependencies, the company targets operational simplification and reduced maintenance overhead, directly addressing two persistent pain points in conventional bioelectrochemical deployments.
These players illustrate the strategic breadth of the current landscape. Some prioritize industrial wastewater integration, others focus on modular decentralization or biological interface innovation. For prospective market participants, the lesson is clear: competitive advantage will not derive from generic MFC adoption, but from precise alignment between technological architecture, target effluent profiles, site constraints, and regulatory incentive structures. The full report dissects these strategic postures in greater detail, mapping each company's deployment history, technological emphasis, and likely evolution over the forecast period.
Translating Trajectory Into Actionable Strategy
The 11.25 percent compound annual growth rate projected across the 2026-2032 window is not merely a statistical indicator; it is a strategic signal. It implies that microbial fuel cell technology is transitioning from fragmented pilots to structured commercial pathways, driven by converging efficiency gains, regulatory alignment, and growing organizational appetite for energy-positive treatment solutions. For executive decision-makers, this trajectory raises several priority questions. Which application segments offer the most favorable risk-adjusted return profiles? How should organizations sequence pilot deployments to validate performance while preserving capital flexibility? What partnership models will accelerate scaling without overexposing firms to electrode degradation risks or sub-1 kW power limitations? How will regional regulatory frameworks and material supply economics reshape competitive dynamics over the next several years?
Our research is built to answer these questions with analytical precision. It provides the structural breakdown, competitive intelligence, and scenario modeling required to convert market growth from an abstract forecast into a deployable strategy. The report does not simply track where the market has been; it maps where value creation is likely to concentrate, which technological and operational choices will separate scalable initiatives from stranded pilots, and how organizations can position themselves to capture share in a market that is expanding but still highly selective in its adoption criteria.
The Worldwide Microbial Fuel Cell Market study is now available for executive teams, investment analysts, technology strategists, and operations leaders who require uncompromising clarity on the forces shaping the next phase of bioelectrochemical commercialization. Detailed segmentation evaluations, regional deployment intelligence, application-level demand analysis, and comprehensive competitive profiling are presented in full within the complete publication. Readers seeking the precise figures, granular breakdowns, and proprietary analytical frameworks that underpin this strategic outlook are encouraged to access the full report through our official research portal. In a market defined by rapid capability evolution and shifting regulatory expectations, informed strategy is the decisive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Microbial Fuel Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 2D Ablation Catheter Market Hits $552.48M in 2025, Projects 4.58% CAGR to 2032
By pmarketresearch, 2026-09-16
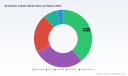
Global 2D Ablation Catheter Market 2026: Strategic Imperatives in a Consolidating Electrophysiology Landscape
The worldwide market for 2D ablation catheters is entering a decisive growth phase, shaped by epidemiological demand, technological evolution, and a highly concentrated competitive field. As cardiac arrhythmias continue to drive procedural volumes across healthcare systems, manufacturers and investors must navigate a landscape where precise segmentation intelligence determines capital allocation, partnership strategy, and commercialization timing. This analysis previews the strategic value of our latest Worldwide 2D Ablation Catheter Market research, a comprehensive assessment designed to equip executive teams with the operational clarity required for 2026 planning cycles.
Market Trajectory and Structural Growth Drivers
The sector has demonstrated resilient expansion over the past half-decade, with total market revenue climbing from approximately 442.15 million USD in 2020 to an estimated 552.48 million USD in 2025. Forward projections indicate sustained momentum, with the market expected to reach 558.58 million USD in 2026 and advance toward 755.93 million USD by 2032. This trajectory translates to a compound annual growth rate of 4.58 percent across the 2026 to 2032 forecast window, reflecting a market that is neither hyper-aggressive nor stagnant, but steadily compounding through procedural volume growth, device iteration, and geographic penetration.
Several structural forces underpin this expansion. The rising prevalence of atrial fibrillation and other tachyarrhythmias continues to expand the addressable patient pool, while electrophysiology laboratories seek standardized, cost-effective workflows that integrate mapping and ablation capabilities. Energy-source diversification has also intensified, with radiofrequency platforms maintaining a dominant share of clinical practice, cryoablation systems sustaining a strong niche in pulmonary vein isolation protocols, and laser and microwave catheters capturing incremental adoption for specialized lesion sets. Competitive positioning increasingly hinges on how effectively manufacturers align catheter geometry, contact assessment, and irrigation design with operator preferences and institutional procurement frameworks.
Regional deployment patterns reveal a mature core alongside high-growth frontier markets. North America and Europe anchor absolute revenue due to established reimbursement structures, dense electrophysiology center networks, and early adoption of advanced mapping integration. Asia Pacific, Latin America, and the Middle East and Africa collectively represent accelerating procedural uptake, driven by expanding cardiac care infrastructure and localized commercialization efforts. The report dissects these geographic gradients without reducing them to static snapshots, instead mapping how pricing dynamics, tendering cycles, and regulatory timelines shape revenue realization over the forecast horizon.
Competitive Architecture and Strategic Positioning
Market concentration remains pronounced, with the top three participants commanding approximately 62.45 percent of total revenue and the top five firms consolidating around 78.12 percent. This concentration does not imply immobility; rather, it highlights a field where differentiation is earned through product integration, clinical evidence generation, and regulatory execution. The incumbents have built formidable moats by coupling ablation catheters with mapping ecosystems, imaging modalities, and navigation workflows, creating sticky purchasing patterns within hospital procurement and physician preference structures.
Biosense Webster, operating under Johnson and Johnson MedTech, continues to leverage its THERMOCOOL SMARTTOUCH SF radiofrequency portfolio alongside CARTO 3D mapping integration, while reinforcing procedural visualization through the SOUNDSTAR CRYSTAL 2D ICE ultrasound catheter. This dual emphasis on lesion formation and real-time imaging reflects a broader industry trend: catheters are no longer evaluated solely by energy delivery, but by how seamlessly they fit into image-guided, efficiency-oriented operating workflows.
Worldwide Cardiac Radiofrequency Catheter Market
Boston Scientific maintains a strong electrophysiology footprint through the BLAZER and INTELLATIP MIFI families, emphasizing open-irrigated designs and contact force sensing, while also participating in pulsed field ablation development with the Farapoint catheter. Abbott has advanced sensor-enabled contact force technology through its TactiFlex Duo and Volt platforms, with recent CE Mark approval for the TactiFlex Duo ablation catheter in atrial fibrillation and complex arrhythmia treatment, signaling continued expansion of its multi-energy strategy. Medtronic continues to balance radiofrequency and pulsed field approaches via the Sphere-9 mapping and ablation catheter within the Affera system, complemented by its Arctic Front family of cryoablation catheters for pulmonary vein isolation.
Emerging and regionally focused players are reshaping competitive pressure through targeted innovation and cost-competitive manufacturing. Shanghai MicroPort EP MedTech has expanded its multi-energy portfolio with the FireMagic and PulseMagic TrueForce ablation catheters, integrating pressure sensing and saline irrigation, alongside the Columbus 3D mapping system and robotic navigation collaborations. Its recent NMPA approval and launch of the PulseMagic TrueForce pulsed field ablation catheter demonstrates how rapid regulatory execution can accelerate platform relevance. Biotronik contributes the AlCath family of steerable irrigated and non-irrigated radiofrequency catheters with gold-tip technology, reinforcing reliability-focused value propositions. Japan Lifeline supplies disposable electrode catheters for diagnosis and radiofrequency ablation, reflecting enduring demand for standardized single-use solutions in high-throughput environments.
Specialized navigation and robotic approaches also shape competitive differentiation. Stereotaxis has secured FDA approval for the MAGiC Magnetic Interventional Ablation Catheter, enabling robotically navigated radiofrequency ablation for complex cases including supraventricular tachycardia in congenital heart disease patients where conventional navigation is constrained. Osypka Medical and APT Medical continue to serve electrophysiology programs with specialized ablation catheters and steerable irrigated designs, respectively, underscoring the importance of tailored form factors and procedural flexibility. CardioFocus rounds out the field with focal and balloon pulsed field ablation catheters such as QuickShot Nav and OptiShot, targeting pulmonary vein isolation in atrial fibrillation and illustrating how energy modality innovation can open new adoption pathways.
Report Scope: Operational Intelligence for Commercial and Clinical Strategy
The study is structured to convert market complexity into actionable planning inputs. It begins with a quantitative baseline and forecast model that tracks revenue evolution across the 2020 to 2032 period, anchoring decision-makers in a defensible trajectory rather than isolated data points. This framework is paired with segmentation analysis that examines product type, clinical application, and regional deployment in a manner designed to inform portfolio prioritization and go-to-market sequencing.
The report also delivers a detailed competitive benchmarking module that evaluates product architecture, mapping and imaging integration, energy modality coverage, and geographic execution capability. Rather than reducing competitors to headline metrics, the analysis examines how product families align with procedural workflows, how innovation pipelines intersect with regulatory roadmaps, and where partnership or acquisition opportunities may arise for firms seeking to broaden their electrophysiology footprint.
Worldwide 2D Ablation Catheter Market
Clinical and operational context is embedded throughout. The assessment integrates reimbursement dynamics, including how procedure coding structures influence lab economics and how mapping billing practices interact with catheter selection. It also addresses regulatory realities, including the role of clearance pathways in shaping U.S. market entry and product iteration cycles. These elements are presented as strategic variables, not background noise, enabling teams to anticipate margin pressure, procurement friction, and adoption barriers before they affect execution timelines.
In addition, the study includes a technology and workflow lens that explores how catheter design, contact assessment, irrigation strategies, and visualization tools influence procedural efficiency and operator confidence. This section is particularly relevant for organizations evaluating next-generation platform development, clinical evidence generation, or cross-selling strategies within hospital systems. By linking device characteristics to practical adoption drivers, the report supports more precise positioning and more realistic commercialization assumptions.
Regulatory, Reimbursement, and Workflow Dynamics
The market does not evolve in a vacuum. Regulatory frameworks, reimbursement architecture, and institutional workflow expectations collectively determine how quickly innovation translates into revenue. In the United States, the FDA 510(k) clearance process remains the primary pathway for most 2D ablation and related ICE catheters, with recent activity reflecting ongoing enhancements to mapping system compatibility and ultrasound-guided ablation workflows. These regulatory nuances matter because they influence time-to-market, labeling scope, and the pace at which manufacturers can introduce incremental improvements that strengthen competitive positioning.
Reimbursement conditions further shape adoption economics. Current procedural coding for intracardiac catheter ablation does not differentiate by energy source or by 2D versus 3D mapping, and 2D mapping remains separately billable only when no 3D mapping is performed. This structure has direct implications for how manufacturers frame value propositions, particularly in settings where institutions balance clinical outcomes against resource utilization. Meanwhile, CMS maintains MS-DRG classifications for inpatient cardiac ablation procedures, with periodic updates to practice expense inputs affecting physician payments and electrophysiology lab economics. These reimbursement dynamics are not static; they require continuous monitoring, especially for organizations planning pricing strategies, volume forecasts, or multi-market rollout plans.
Workflow integration remains a decisive adoption factor. Electrophysiology teams increasingly prioritize devices that reduce setup complexity, improve lesion consistency, and align with existing mapping or imaging infrastructure. As a result, competitive advantage often derives from the coherence of the overall solution rather than isolated catheter performance. The report examines these dynamics to help teams anticipate where procurement decisions will be won or lost, particularly in cost-sensitive environments or regions with developing electrophysiology capacity.
Strategic Takeaways for 2026 Decision-Making
For organizations operating in or entering this market, the 2026 outlook calls for disciplined prioritization. Growth is real, but it is distributed unevenly across regions, indications, and product categories. Firms that treat the market as a single block risk misallocating resources, while those that understand where procedural volume, reimbursement stability, and adoption readiness intersect can deploy capital with greater precision. The concentration of revenue among leading players also means that competitive responses can move quickly; product launches, regulatory approvals, and mapping integration enhancements can shift purchasing patterns faster than traditional forecasting cycles anticipate.
The study is designed to support that discipline. It provides a structured view of where demand is expanding, which technologies are gaining procedural traction, how incumbents and challengers are differentiating, and what regulatory and reimbursement variables may alter execution timelines. By grounding these insights in a consistent forecast framework and competitive analysis, the report enables teams to stress-test assumptions, refine pipeline priorities, and align commercial strategy with the realities of electrophysiology procurement and clinical adoption.
To access the full segmentation detail, regional breakdowns, application-level analysis, and company-specific strategic profiles that underpin these conclusions, we invite stakeholders to explore the complete Worldwide 2D Ablation Catheter Market report. The full intelligence package is intended for teams that require granular, decision-grade data to guide product planning, market entry, partnership evaluation, and investment allocation through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Ablation Catheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Borated Polyethylene Market Hits USD 217.04M in 2025, Projected 5.18% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in Industrial Grade Borated Polyethylene Materials: A 2026 Market Intelligence Preview
The industrial grade borated polyethylene market stands at a critical inflection point as of 2026. With global revenue projections indicating steady expansion from approximately 217 million USD in the base year of 2025 toward over 309 million USD by the end of the forecast window in 2032, the sector demonstrates a compound annual growth rate that underscores sustained demand for neutron shielding solutions across nuclear, medical, and defense verticals. For strategic planners, procurement leaders, and competitive intelligence teams, navigating this landscape requires more than top-line figures. It demands a granular understanding of material formulations, regulatory compliance pathways, regional supply dynamics, and the evolving positioning of key manufacturers. This preview outlines the strategic architecture of our newly released market research study and explains why access to its full analytical framework will be indispensable for enterprise decision-making throughout 2026 and beyond.
Worldwide Industrial Grade Ammonium Pentaborate Market
The Macro Trajectory: Reading Growth Beyond the Headline
Historical revenue patterns from 2020 through 2025 reveal a market that has consistently navigated raw material volatility, shifting nuclear energy policies, and evolving medical radiation protection standards. The transition into the 2026-2032 forecast period suggests that growth will not be linear. Instead, it will be shaped by uneven adoption cycles across applications, divergent regional procurement rhythms, and material substitution pressures that reward manufacturers capable of balancing cost efficiency with certified shielding performance. The study maps these inflection points without relying on surface-level percentage breakdowns. Instead, it contextualizes how revenue concentration, formulation preferences, and application-specific procurement behaviors interact to create pockets of margin expansion and competitive vulnerability. Readers who engage with the complete report will gain a structured view of where volume growth converges with pricing resilience, and where commoditization risks threaten undifferentiated producers.
Segmentation Dynamics: Boron Loading, Applications, and Regional Realities
The commercial architecture of borated polyethylene is fundamentally defined by boron concentration, application criticality, and geographic supply chain maturity. Formulations ranging from lighter boron loadings to high-concentration variants serve distinct shielding requirements, with procurement decisions often dictated by neutron flux profiles, spatial constraints, and regulatory specifications. Similarly, end-use environments span from nuclear power reactors and medical radiotherapy facilities to research accelerators, nuclear propulsion systems, and radioactive waste containment. Each vertical imposes unique certification demands, thickness tolerances, and fabrication expectations that directly influence supplier selection.
Regional supply and demand patterns further complicate the competitive picture. Manufacturing footprints, logistics infrastructure, and local regulatory frameworks create divergent cost structures and delivery timelines. The study disentangles these regional dynamics by examining how procurement hubs interface with production clusters, how import-export flows respond to certification bottlenecks, and how localized content requirements shape sourcing strategies. Rather than presenting static regional revenue splits, the analysis focuses on the operational mechanisms that determine which suppliers can reliably serve which markets, under what compliance conditions, and at what total cost of ownership.
Competitive Landscape: Strategic Positioning Among Core Players
The industry features a concentrated but differentiated supplier base, with leading manufacturers distinguished by proprietary processing methods, certification portfolios, customization capabilities, and vertical market focus. Several organizations have built recognizable identities around specific product architectures and application specializations, creating defensible niches within a market that increasingly rewards technical reliability and supply chain consistency.
-
King Plastic Corporation has reinforced its market presence through targeted exhibition participation, including appearances at the International Sign Expo and the NRPA Annual Conference, signaling continued engagement with both industrial and specialized material buyers. Its product positioning emphasizes trademarked shielding formulations and proprietary processing techniques designed to deliver flatness and dimensional consistency in large-format sheets and custom configurations.
Industrial Grade Borated Polyethylene Materials Market -
MarShield Custom Radiation Products has expanded its strategic alignment with nuclear energy initiatives by joining Canadians for CANDU, while maintaining a broad offering of borated polyethylene sheets, pellets, and custom shapes. Its certification ratings and fabrication services position it as a solutions-oriented supplier for nuclear, medical, and industrial neutron shielding requirements.
-
Emco Plastics maintains a strong compliance-oriented profile, offering borated HDPE sheets with multiple boron content options and adherence to military and ASTM specifications. Its ITAR registration and thickness/size versatility support demand from nuclear power plants, medical facilities, aerospace, and radioactive material storage and transport applications.
-
A&L Shielding focuses on cost-effective, lightweight neutron and gamma shielding solutions, emphasizing standard large-format sheet configurations for medical and industrial environments where installation efficiency and material economy are priorities.
-
Radiation Protection Products, Inc. supplies a recognizable purple-hued borated polyethylene line in standard and custom formats, serving nuclear reactors, medical vaults, linear accelerators, and research facilities with an emphasis on accessible standard inventory and custom fabrication flexibility.
-
NELCO Worldwide addresses security and propulsion-adjacent applications with both standard and higher boron content options, supporting cargo screening, border protection, and nuclear submarine-related shielding needs through configurable sheet formats and machining services.
-
Shandong Yasu New Material Co., Ltd. stands out for its highly customizable boron content range and broad product formats, including sheets, rods, and pellets, targeting nuclear power, medical therapy rooms, particle accelerators, and aerospace/defense applications. Its formulation flexibility positions it as a responsive supplier in markets where shielding specifications vary significantly across projects.
The full study evaluates these players through a structured competitive assessment framework, examining product differentiation, certification coverage, regional service reach, fabrication capabilities, and recent strategic moves. Rather than simply cataloging company profiles, the analysis identifies where competitive advantages are likely to persist, where price competition may intensify, and how recent partnerships and trade show engagements signal shifting commercial priorities.
Market Dynamics and Strategic Variables
Several operational and regulatory forces continue to shape procurement behavior and supplier competitiveness. Material pricing illustrates the premium associated with higher boron loadings, with standard 5% boron sheets carrying materially different cost profiles than 30% boron variants. This pricing gradient influences application selection, especially in projects where shielding performance requirements can be met through formulation optimization rather than blanket upsizing. Understanding these cost-performance tradeoffs is essential for buyers seeking to balance compliance, weight, spatial constraints, and budget.
Regulatory compliance remains a decisive filter in competitive access. Military specifications such as MIL-P-23536A and EB2562E continue to govern neutron shielding expectations for naval and defense-related deployments, while nuclear sector standards impose additional requirements on hydrogen density, aging effects, and spent fuel storage system compositions. Suppliers that can demonstrate consistent certification adherence, documentation rigor, and test-backed performance claims gain preferential access to high-assurance procurement channels. The study examines how these regulatory layers affect market entry barriers, customer retention, and the economics of qualification-led selling.
Supply chain resilience also warrants close attention. Fabrication services, custom machining, stocking strategies, and cut-to-size capabilities increasingly differentiate suppliers in contexts where end users prioritize project-ready materials over commodity sheet purchases. Companies that combine certified material supply with CNC or waterjet cutting, custom block and slab production, and responsive inventory positioning are better equipped to capture value in complex procurement environments. These capabilities are not merely service add-ons; they are increasingly central to supplier selection in medical, nuclear, and defense applications where installation precision and lead-time reliability carry substantial operational weight.
What the Study Delivers: Operational Intelligence for Decision-Makers
This market research is structured to translate market complexity into actionable strategic guidance. Beyond baseline sizing and trend mapping, the report provides a working view of how material technology, regulatory expectations, and procurement behavior intersect across the forecast period. It is designed for teams that need to evaluate supplier risk, prioritize market entry or expansion, calibrate product development roadmaps, and align sourcing strategies with evolving shielding requirements.
Key components of the study include:
-
A detailed segment architecture that explains how boron loading choices, application criticality, and regional procurement habits shape demand trajectories and margin dynamics.
-
A competitive positioning map that evaluates core manufacturers on formulation range, certification coverage, fabrication capabilities, and strategic signaling through partnerships and exhibition activity.
-
An analysis of pricing structure logic, showing how standard and high-concentration formulations create differentiated procurement economics across use cases.
-
A regulatory and compliance overlay that clarifies the role of military specifications, nuclear standards, and documentation requirements in shaping buyer preference and supplier eligibility.
-
Forward-looking scenario framing for the 2026-2032 period, highlighting where volume growth, application diversification, and supply chain maturity are likely to reshape competitive access.
The full report is built to support both strategic planning and execution-level decisions. It provides the contextual depth needed to interpret market movements, assess supplier capabilities, and anticipate where procurement standards and material specifications will tighten or evolve.
Why Strategic Access Matters in 2026
As enterprises navigate a market defined by steady growth, concentrated competition, and rising technical expectations, the cost of incomplete intelligence is increasingly measurable. Procurement teams that lack visibility into formulation economics may overspend on over-specified materials or under-specify shielding performance. Market expansion teams that rely on generic segmentation may misjudge regional readiness or overestimate the transferability of product offerings. Competitive analysts who overlook certification pathways and fabrication capabilities may misread which suppliers are truly positioned to win high-assurance contracts.
The study addresses these blind spots by connecting market structure to decision quality. It offers a disciplined framework for interpreting growth signals, assessing supplier reliability, and anticipating where regulatory or application-specific demands will alter purchasing behavior. For organizations operating in nuclear energy, medical radiation protection, research infrastructure, defense, or radioactive material handling, this intelligence provides a practical foundation for sourcing strategy, product planning, and competitive positioning.
Conclusion: Moving from Market Awareness to Strategic Action
The industrial grade borated polyethylene market is not simply expanding; it is maturing in ways that reward technical precision, compliance readiness, and supply chain flexibility. The trajectory through 2032 suggests continued demand growth, but the distribution of that growth will favor participants who can align formulation choices, certification strength, fabrication capability, and regional service capacity with the specific requirements of each application. Our full market research unpacks these dynamics with the depth required for confident strategic action. For decision-makers who need more than headline sizing and broad trend statements, the complete study offers the structured intelligence necessary to convert market momentum into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Industrial Grade Borated Polyethylene Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Venetoclax API Market to Hit $593.85M by 2032, 12.51% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the Global Venetoclax API Market Through 2032
The global oncology landscape is undergoing a structural transformation, driven by an aging population, increasing prevalence of hematologic malignancies, and the relentless pursuit of targeted therapies. At the heart of this shift lies Venetoclax, a BCL-2 inhibitor that has redefined treatment protocols for Chronic Lymphocytic Leukemia (CLL) and Acute Myeloid Leukemia (AML). As the patent cliffs approach and generic pathways open, the supply chain dynamics for the Active Pharmaceutical Ingredient (API) have become a critical focal point for stakeholders. Our latest Worldwide Venetoclax API Market research study provides a comprehensive lens into these evolving dynamics, offering the granular intelligence necessary to navigate the period from 2026 through 2032.
For strategic decision-makers, investors, and supply chain architects, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation and risk mitigation. This article serves as a strategic preview of our full report, highlighting the macro-economic currents and competitive forces shaping the industry, while underscoring the depth of analysis available in our complete forecast model.
Market Trajectory and Growth Vectors
The economic signal emanating from the Venetoclax API sector is unequivocally strong. Reflecting a robust compound annual growth rate, the market has demonstrated consistent expansion over the historical review period and is projected to maintain significant momentum throughout the forecast horizon. Our analysis indicates that revenue generation in this segment has moved beyond early adoption phases into a period of scaled commercialization and supply chain maturation.
Between 2020 and 2025, the market experienced a substantial valuation increase, mirroring the broader adoption of Venetoclax-based regimens in clinical settings. Looking forward, our forecast models project a continued upward trajectory. The valuation metrics suggest that the market will sustain double-digit growth percentages, driven by the dual engines of branded demand persistence and the imminent influx of cost-effective generic alternatives. However, capitalizing on this growth requires more than observing headline numbers; it demands an understanding of the volume-to-value shifts that occur as patent exclusivity wanes.
Key strategic observations from the historical data include:
- Sustained Expansion: The market size has consistently outpaced initial conservative estimates, reflecting strong clinical confidence in BCL-2 inhibition mechanisms.
- Forecast Confidence: Probabilistic models indicate high certainty in growth continuation, contingent on regulatory approvals in key territories and manufacturing capacity scaling.
- Value Migration: As the market matures, revenue centers are expected to shift from purely branded channels toward hybrid models involving authorized generics and third-party API suppliers.
Competitive Landscape and Manufacturing Dynamics
The supply side of the Venetoclax API market is characterized by a concentrated yet dynamic ecosystem. Our report provides detailed profiling of key market participants who are positioning themselves to capture value as the competitive landscape evolves. The concentration of market share among top players underscores the barriers to entry, primarily related to technical synthesis complexity and regulatory compliance.
Leading manufacturers, particularly those based in India and China, have established robust footprints in this sector. Companies such as MSN Laboratories Pvt. Ltd., Hetero Drugs Ltd., and Aurobindo Pharma Ltd. have invested heavily in regulatory infrastructure, including US FDA filings and European Certificate of Suitability (CEP) certifications. These entities are not merely producing volumes; they are building compliance architectures designed to withstand stringent inspection regimes. Similarly, players like Senova Technology Co., Ltd. in China represent the growing technical capability within the Asian manufacturing hub to handle complex oncology intermediates.
The strategic significance of these players extends beyond production capacity. Their ability to navigate Drug Master File (DMF) processes and maintain Good Manufacturing Practice (GMP) compliance determines the reliability of the global supply chain. Our research delves into the operational capabilities of these firms, analyzing their capacity utilization, regulatory standing, and strategic partnerships with finished dosage manufacturers.
Recent legal and regulatory developments have also reshaped the competitive outlook. Notably, patent settlement agreements between originator companies and generic manufacturers, such as the settlement involving AbbVie and MSN Laboratories in late 2022, have signaled potential pathways for generic entry post-2026. These legal milestones are critical indicators for supply planning, as they dictate when additional API capacity might be required to support downstream generic formulations.
Regulatory and Cost Pressures Shaping the Supply Chain
No strategic analysis of the Venetoclax API market is complete without addressing the regulatory and cost structures that define profitability. The synthesis of Venetoclax is chemically complex, relying on specialized intermediates such as indole and pyrazole derivatives. This complexity contributes to production costs that remain high, particularly in small-batch scenarios where economies of scale are not fully realized. Industry data suggests that API production costs can exceed significant thresholds per kilogram, placing a premium on process optimization and yield improvement.
Furthermore, Intellectual Property (IP) rights continue to exert influence over market access. While key composition-of-matter patents have defined expiry dates, extensions via pediatric exclusivity can prolong market exclusivity periods. For example, certain US patents are scheduled to expire in the later part of the decade, with exclusivity extensions pushing potential generic competition into the early 2030s. This timeline creates a nuanced operational window where manufacturers must balance capacity expansion against the risk of uncertain entry dates.
Reimbursement landscapes also play a pivotal role in demand forecasting. In major healthcare markets like the United States, the pricing of branded formulations influences the viability of generic alternatives. Medicare Average Sales Price (ASP) data for branded Venetoclax indicates high per-cycle costs, which theoretically supports the economic case for generics once available. However, the realized demand for API will depend on how payers, providers, and patients navigate the transition from branded to generic supply chains.
Our report integrates these regulatory and cost factors into a cohesive risk assessment framework, allowing clients to model scenarios based on varying assumptions about patent challenges, import alerts, and raw material price volatility.
Worldwide Regorafenib API Market
Regional Dynamics and Supply Chain Resilience
Geographically, the Venetoclax API market exhibits distinct regional characteristics. While demand for finished oncology products is global, the production of the API is heavily concentrated in specific manufacturing hubs. A significant portion of global capacity originates from regions with established chemical synthesis infrastructure, particularly India and China.
This concentration offers efficiencies but also introduces supply chain vulnerabilities. Regulatory scrutiny in key import markets, such as the United States, remains high. Import alerts and inspection trends can impact the flow of materials from specific facilities, necessitating robust contingency planning for downstream manufacturers. Our analysis maps these regional dependencies, evaluating the risk exposure for companies reliant on single-source or region-specific supply chains.
Europe remains a critical market for regulatory certification and consumption, while Asia Pacific represents both a manufacturing base and a growing consumption region. Latin America and the Middle East and Africa present emerging opportunities, though volume contributions from these regions are currently smaller compared to established markets. Understanding the flow of API from manufacturing centers to formulation sites across these regions is essential for optimizing logistics and inventory management.
Worldwide Venetoclax API Market
Inside the Report: Analytical Depth and Strategic Tools
The full Worldwide Venetoclax API Market research study goes beyond macro trends to provide actionable intelligence. We understand that strategic decisions require data granularity that cannot be summarized in a high-level overview. Therefore, the report is structured to serve multiple functional needs within an organization, from R&D planning to commercial strategy.
Key components included in the comprehensive study are:
- Segmented Market Sizing: Detailed breakdown of market value by purity grades, distinguishing between standard and high-purity requirements which command different pricing structures and regulatory pathways.
- Application-Specific Forecasts: Analysis of demand drivers across key therapeutic indications, including CLL, AML, and clinical research usage, allowing for precise alignment of production capacity with end-user needs.
- Competitive Benchmarking: In-depth profiles of key companies, assessing their manufacturing capabilities, regulatory filings, and strategic positioning relative to peers.
- Regulatory Roadmap: A timeline of key patent expirations, exclusivity periods, and regulatory milestones that impact market entry and supply availability.
- Supply Chain Risk Assessment: Evaluation of raw material dependencies, manufacturing concentration risks, and regulatory inspection trends that could disrupt supply continuity.
- Financial Modeling Inputs: Data structures suitable for integrating into internal valuation models, including cost drivers and margin analysis frameworks.
Strategic Imperatives for 2026 and Beyond
As organizations plan their portfolios for the 2026-2032 period, several strategic imperatives emerge from our analysis. First, supply chain diversification is critical. Given the concentration of API production in specific geographic zones, companies should evaluate multi-sourcing strategies to mitigate regulatory and operational risks. Second, regulatory intelligence must be proactive. Monitoring DMF status, patent litigation outcomes, and inspection trends will provide early warning signals for capacity adjustments.
Third, technology transfer and process optimization should be prioritized. With production costs influenced by complex synthesis routes, manufacturers that can improve yields and reduce waste will hold a competitive advantage, particularly as price pressure increases with generic entry. Finally, understanding the reimbursement environment is vital for forecasting end-market demand. The interplay between branded pricing, generic adoption rates, and payer policies will determine the velocity of market growth.
Our report is designed to empower stakeholders with the insights needed to address these imperatives. By combining historical data, forward-looking forecasts, and qualitative industry analysis, we provide a holistic view of the Venetoclax API market ecosystem.
Conclusion: Accessing the Complete Intelligence
The Worldwide Venetoclax API Market represents a high-stakes environment where regulatory precision, manufacturing excellence, and strategic foresight converge. The growth trajectory suggests significant opportunities, but realizing them requires navigating complex patent landscapes, cost structures, and supply chain vulnerabilities. Our comprehensive research study offers the detailed evidence base required to make informed decisions in this dynamic sector.
While this overview highlights the strategic contours and macro dynamics, the full report contains the specific segmentation data, quantitative forecasts, and proprietary analysis necessary for operational planning. For organizations seeking to secure their position in the evolving oncology supply chain, accessing the complete dataset is the next logical step. We invite you to explore the full findings of our Worldwide Venetoclax API Market research to gain the comprehensive intelligence needed to drive your strategy forward.
For detailed analysis of this topic, please visit the official page: Worldwide Venetoclax API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Silver Coated FEP Film Market Hits $144.13M in 2025, 6.82% CAGR Toward 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Space Economy: Inside the Worldwide Silver Coated FEP Film Market 2026–2032
As the global space economy accelerates toward sustained lunar operations, deep-space exploration, and advanced satellite constellations, material selection has shifted from a supporting engineering decision to a critical strategic variable. Silver coated FEP (fluorinated ethylene propylene) film has emerged as a cornerstone material for spacecraft thermal management, multi-layer insulation, and second-surface mirror applications. Yet for executives, procurement leaders, and investment committees, the real challenge is not identifying the material but interpreting the market forces that will shape procurement costs, supplier resilience, and long-term competitive positioning through the end of the decade.
Our newly released Worldwide Silver Coated FEP Film Market study is designed to bridge that gap. Spanning historical analysis from 2020 through the base year of 2025 and extending a forward-looking forecast to 2032, the report translates complex supply-demand dynamics into actionable intelligence for 2026 decision-making. Rather than offering superficial trend commentary, the study maps where capital, capacity, and technological expertise are concentrating, equipping leadership teams with a structured framework to navigate a market defined by high technical barriers, mission-critical performance requirements, and persistent raw material volatility.
Market Trajectory and Structural Signals
The market has demonstrated consistent expansion over the past half-decade, with revenue climbing from approximately $104.22 million in 2020 to an estimated $144.13 million in 2025. This historical trajectory reflects sustained aerospace program pipelines, the proliferation of small satellite deployments, and growing application requirements in cryogenic and deep-space systems. Looking ahead, the global market is projected to grow at a compound annual growth rate of 6.82% through 2032, with revenue advancing from roughly $146.5 million in 2026 toward $228.73 million by the close of the forecast horizon.
These figures are not merely snapshots; they encode strategic signals. The growth path suggests that demand expansion is being driven by a combination of program repeats, evolving mission architectures, and gradual qualification of next-generation thermal control materials. At the same time, the pace of growth indicates that capacity, manufacturing precision, and supply continuity will become increasingly decisive differentiators. For organizations planning multi-year procurement strategies or evaluating market entry, understanding the shape of this trajectory is essential to balancing cost exposure against performance mandates.
Worldwide Silver Coated Powder Market
The report further examines how historical volatility across the 2020–2025 period provides context for near-term planning. By linking revenue movement to program cycles, qualification timelines, and broader aerospace demand patterns, the analysis helps decision-makers separate structural growth from short-term fluctuations and anticipate where procurement timing may influence total cost of ownership.
Competitive Concentration and Strategic Positioning
A defining feature of the worldwide silver coated FEP film market is its concentrated supplier landscape. The study reports a CR3 of 62.4% and a CR5 of 81.15%, indicating that a relatively small group of specialized manufacturers commands the majority of market revenue. This concentration reflects the technical intensity of the sector: decades of application experience, stringent qualification requirements for space-grade thermal control materials, and sustained investment in proprietary coating and lamination processes create substantial barriers to entry.
Among the most prominent participants is Dunmore Aerospace, based in Bristol, Pennsylvania. With more than 35 years of experience, the company has established itself as a leading manufacturer of silver coated FEP (Teflon™) films, ITO coated silver FEP, and SiO2 silver FEP films engineered specifically for aerospace thermal control, satellite multi-layer insulation, and second surface mirror applications. Its long operational history and application-specific portfolio illustrate how incumbents build defensibility through mission-proven material performance and deeply integrated customer relationships.
SQUID3 Space, headquartered in the United States, represents another strategically important player. The company manufactures silver Teflon FEP tape and ITO coated silver Teflon FEP tape designed for spacecraft thermal control, Flexible Optical Solar Reflector applications, cryogenic systems, and optical uses across space and defense programs. Its focus on tape-format products highlights the diversity of form factors within the market and underscores how suppliers differentiate not only by coating chemistry but also by product geometry, process consistency, and application readiness.
Sheldahl, integrated through acquisition and ongoing operational consolidation, brings a historical production base in silver coated one-side FEP films and tapes with Inconel overcoat for second surface mirrors in MLI blankets and thermal control applications. Its trajectory demonstrates how consolidation, capability transfer, and operational integration can reshape supply options and influence regional manufacturing footprints within a mature, specialized market.
For buyers and competitors alike, the concentration profile carries practical implications. Limited supplier pools can enhance supply assurance when relationships are managed strategically, but they also elevate the importance of qualification continuity, dual-sourcing assessments, and risk-mitigated procurement planning. The report evaluates these dynamics in detail, helping stakeholders anticipate where supplier negotiations, capacity constraints, or program-specific requirements may affect access and pricing over the forecast period.
Macroeconomic Pressure Points: Raw Material Exposure and Cost Dynamics
Beyond demand and concentration, the market is highly sensitive to input cost dynamics, particularly silver pricing. Silver is a core component of the conductive and reflective coatings that give the film its thermal and optical performance characteristics, making price movements a direct factor in manufacturing economics and downstream procurement cost structures.
Recent market context underscores the relevance of this exposure. According to J.P. Morgan Global Research in February 2026, silver prices averaged significantly higher in 2025, with 2026 forecasts averaging around $81 per ounce, driven by industrial demand. The broader trend has proven volatile: pv magazine reported that silver reached $95 per ounce in early March 2026 amid a renewed upward trajectory and heightened geopolitical tensions. These conditions create a material cost environment in which price stability cannot be assumed and procurement strategies must account for potential fluctuations across multi-year program horizons.
The strategic question for enterprises is not whether raw material costs matter, but how to structure procurement, inventory, and supplier engagement to manage exposure without compromising mission-critical performance. The report examines these cost dynamics as part of the broader market framework, linking material input trends to revenue patterns, supplier behavior, and the economic logic behind different procurement approaches. By mapping the intersection of commodity volatility and specialized manufacturing, the study helps organizations anticipate cost pressure points and evaluate where strategic sourcing or specification decisions may generate long-term resilience.
What the Report Delivers: Operational Intelligence for 2026 Planning
The Worldwide Silver Coated FEP Film Market study is built to support practical decision-making rather than abstract observation. It combines historical reconstruction, forward-looking forecast modeling, and market structure analysis into a unified reference for executives, technical leaders, and commercial teams. The report is organized to help readers move from high-level market understanding to operational implications, with a clear focus on how structural trends affect sourcing, capacity planning, competitive positioning, and investment prioritization.
Key elements of the report include:
- A full historical and forecast revenue timeline from 2020 through 2032, providing a consistent basis for evaluating growth momentum, inflection points, and long-range planning assumptions.
- A segmentation framework that examines how market value distributes across thickness categories, application domains, and regional demand centers, with a focus on the commercial and technical logic behind each split rather than isolated data points.
- Competitive profiling of leading manufacturers, including company capability summaries, application focus areas, and the strategic significance of their market positions within a concentrated supplier landscape.
- Contextual analysis of raw material price conditions and their relevance to cost structure, procurement timing, and supplier negotiation strategy in the current industrial environment.
- Strategic interpretation designed to support merger and acquisition evaluation, capacity and supply assurance planning, technical specification decisions, and market-entry feasibility assessment.
By combining these components, the study enables stakeholders to connect market-level developments with operational consequences. Procurement leaders can better evaluate supplier options and negotiation timing. Product and engineering leaders can align material specifications with evolving application requirements and supply realities. Strategy and corporate development teams can assess where concentration, growth momentum, and input-cost exposure create both risk and opportunity.
Worldwide Silver Coated FEP Film Market
Why This Study Matters for 2026 Decisions
The 2026 planning cycle sits at a pivotal point for organizations operating in or adjacent to the silver coated FEP film market. Historical growth has established a strong demand foundation, but the forward environment will be shaped by a combination of program execution, material input volatility, supplier concentration, and the pace at which new mission requirements translate into commercial demand. In that context, decisions made in 2026 will influence cost structures, supply resilience, and competitive positioning well into the late 2020s and beyond.
This report is therefore designed as a decision-support instrument, not simply a data presentation. It helps readers interpret the market through a strategic lens: where value is concentrating, which capabilities matter most, how cost exposure is evolving, and what the forecast period implies for planning assumptions. The intent is to give leadership teams a credible, evidence-based foundation for evaluating sourcing strategies, supplier relationships, investment timing, and long-term market participation.
Conclusion: From Market Visibility to Strategic Advantage
Silver coated FEP film occupies a specialized but strategically vital position within the broader aerospace and space-technology ecosystem. Its performance characteristics make it indispensable for thermal control and insulation applications, while its manufacturing complexity and supplier concentration make the market a demanding environment for both buyers and competitors. Understanding that market requires more than tracking headline revenue figures; it requires analyzing the interaction of program demand, technical barriers, raw material dynamics, and competitive structure over a multi-year horizon.
Our Worldwide Silver Coated FEP Film Market study provides that analytical depth. It offers a comprehensive view of how the market has evolved, how it is expected to develop through 2032, and what those developments mean for enterprise decisions in 2026 and beyond. For organizations seeking to strengthen procurement resilience, evaluate competitive positioning, or assess strategic opportunities in this high-performance materials segment, the full report delivers the detailed segmentation, regional and application-level intelligence, and competitively focused insight needed to move from market awareness to informed action.
For detailed analysis of this topic, please visit the official page: Worldwide Silver Coated FEP Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laxative Prune Juice Market Hits $520M in 2025, 3.5% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Laxative Prune Juice Market: Navigating Growth and Volatility Through 2032
The global landscape for functional beverages is undergoing a profound transformation, driven by an aging demographic, heightened consumer awareness of digestive health, and a shifting preference toward natural remedies over synthetic alternatives. Within this broader health and wellness sector, the laxative prune juice market stands out as a niche yet resilient category. For executives, investors, and supply chain strategists, understanding the nuanced trajectory of this market is no longer optional—it is a critical component of risk management and revenue forecasting.
PW Consulting is pleased to introduce our comprehensive market research study on the Laxative Prune Juice Market. This report is designed to serve as a strategic compass for stakeholders navigating the complex dynamics between agricultural supply constraints, evolving regulatory environments, and consumer demand shifts. By synthesizing historical performance data with forward-looking projections, this analysis provides the depth required to make informed decisions in 2026 and beyond.
As we move through the forecast period extending to 2032, the market presents a story of steady expansion tempered by periodic volatility. This article outlines the macro-economic framework of the industry, highlights the competitive forces at play, and details the operational insights contained within our full report. It is an invitation to look deeper into the data that will define your strategic posture in the coming years.
Macro-Economic Trajectory and Market Valuation
The historical performance of the laxative prune juice market demonstrates a consistent upward trend, reflecting the product's established position as a staple in digestive health management. Our analysis covers historical data from 2020 through 2025, providing a robust baseline for understanding growth patterns. During this period, the market transitioned from a valuation of approximately 437.84 million USD in 2020 to an estimated 520.0 million USD in 2025. This growth underscores the resilience of the category even amidst broader economic fluctuations and supply chain disruptions that characterized the early 2020s.
Looking forward, the forecast period from 2026 to 2032 suggests a continuation of this positive momentum, albeit at a moderated pace. The market is projected to reach approximately 538.74 million USD in 2026, climbing steadily toward a peak valuation near 663.77 million USD by 2031. It is important for strategists to note the compound annual growth rate (CAGR) estimated at 3.5 percent over the forecast period. While this indicates stable growth, it also signals a maturing market where volume gains may be offset by price stabilization or competitive pricing pressures.
The trajectory is not without its nuances. The forecast data indicates minor fluctuations in specific years, such as the slight dip projected in 2028 before resuming growth. These variations are often tied to external factors such as raw material availability and regulatory changes, which are explored in depth within the full study. Understanding these inflection points is vital for capacity planning and inventory management. Investors should view the 2032 endpoint not just as a number, but as a culmination of decade-long shifts in consumer behavior and agricultural output.
Supply Chain Dynamics and Raw Material Considerations
A critical component of strategic planning in the prune juice sector is the understanding of upstream agricultural dynamics. The market is heavily dependent on prune production, which is subject to climatic conditions and harvest cycles. Recent industry data highlights significant factors that influence cost structures and supply stability. For the 2025/26 production cycle, global prune production is estimated at 193,000 metric tons. This represents a 6 percent decrease compared to the previous cycle, a contraction that warrants attention from procurement and supply chain leaders.
Laxative Prune Juice Market
Lactulose Market
Within this global context, California remains a pivotal region. The 2025 prune crop in California is estimated at approximately 64,000 to 65,000 metric tons, noted for outstanding quality. However, quantity alone does not dictate market dynamics; cost structures are equally important. Data from mid-2025 shows the Producer Price Index for plums and fresh prunes hovering around 420 to 450 (with December 1991 as the base of 100). These cost indicators suggest that input costs remain elevated, which may pressure margins unless passed through to consumers or mitigated through operational efficiency.
Regulatory environments also play a decisive role in shaping market access and cost. Recent developments include the UK Government's suspension of import tariffs on California prune juice and concentrate, previously set at 16 percent. This adjustment is welcomed by industry stakeholders as it potentially lowers barriers to entry in key export markets. Conversely, US import regulations require strict inspection and compliance with grade and size standards under 7 CFR 999.200. Navigating these regulatory frameworks requires precise knowledge, which our report details to help firms avoid compliance pitfalls and optimize trade strategies.
Competitive Landscape and Strategic Positioning
The competitive environment in the laxative prune juice market is characterized by a mix of vertically integrated growers, large multinational food corporations, and specialized fruit juice processors. Our analysis identifies a moderately concentrated market structure, where the top three companies hold a combined market share of approximately 35 percent, and the top five account for around 45 percent. This concentration suggests that while there is room for niche players, scale and brand equity remain significant advantages.
Leading the field is Sunsweet Growers Inc., a grower-owned cooperative based in Yuba City, California. Sunsweet is a vertically integrated powerhouse, managing operations from California prune orchards directly to consumer beverages and concentrates. Their recent activities underscore a dual focus on product innovation and sustainability. In May 2025, Sunsweet unveiled PlumGood plum juice, a new product emphasizing taste and nutrition, signaling a strategy to refresh brand appeal. Simultaneously, they implemented equipment replacements at their headquarters to reduce energy use and greenhouse gas emissions, aligning with broader ESG goals. Furthermore, in March 2026, Sunsweet issued a global prune crop and market update, highlighting their role as an information hub for supply balance and production estimates.
Other key players contribute to the market's diversity and stability. Del Monte Foods, Inc., based in Walnut Creek, leverages established brand equity in the consumer juice category to maintain a strong presence. Dole Food Company, Inc., from Westlake Village, integrates prune juice into a broader fruit juice and beverage portfolio, utilizing robust retail distribution networks. Welch's, headquartered in Concord, Massachusetts, has shown recent activity in zero-sugar and functional juice innovations, adapting to health-conscious trends. Ocean Spray Cranberries, Inc., also based in Massachusetts, produces prune juice alongside cranberry products for retail and ingredient use.
Regional specialists also play a crucial role. Rauch Fruchtsäfte GmbH & Co OG in Austria specializes in fruit juice concentrates, including prune juice concentrate for industrial and beverage applications. Valley View Foods, Inc., located in Yuba City, produces prune juice and concentrates with custom specifications for foodservice and industrial clients. California Prune Packing Inc. focuses on domestic U.S. production and industrial supply. Sun-Maid Growers of California offers prune-related products as part of its dried fruit and juice operations. These companies collectively form a resilient supply network that supports the market's overall volume.
Recent developments among these key companies illustrate the dynamic nature of the industry. Product launches, facility upgrades, and market updates are not merely operational news; they are strategic signals. For instance, Sunsweet's focus on energy efficiency reduces long-term operational costs, while their product innovation seeks to capture shifting consumer preferences. Understanding the strategic intent behind these moves is essential for competitors and partners alike.
Report Scope and Actionable Insights
To support executive decision-making, our full report goes beyond high-level market size estimates. It provides a granular breakdown of the market across multiple dimensions, enabling stakeholders to identify specific opportunities and threats. The segmentation analysis covers regions, product types, and distribution channels, offering a multi-faceted view of where value is being created and captured.
Readers of the full study will find detailed analysis on the following key areas:
- Regional Performance: A comprehensive look at market performance across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. This section helps identify which geographic markets are driving growth and which are experiencing saturation or contraction.
- Product Types: An examination of the split between Organic and Conventional prune juice. This distinction is vital as consumer preference shifts toward clean label and organic options, impacting pricing strategies and sourcing requirements.
- Distribution Channels: Insights into how products reach consumers, covering Supermarkets and Hypermarkets, Online Retail, and Convenience Stores. With the rise of e-commerce, understanding the share and growth potential of online retail versus traditional brick-and-mortar channels is crucial for go-to-market strategies.
In addition to segmentation, the report delves into industry dynamics, including the impact of raw material availability, regulatory changes, and technological advancements in processing. The competitive landscape section provides detailed profiles of key companies, analyzing their strengths, weaknesses, and recent strategic moves. This allows businesses to benchmark themselves against peers and identify potential partnership or acquisition targets.
The forecast model included in the study is built on rigorous methodology, incorporating historical data trends and forward-looking indicators. It accounts for variables such as population growth, health awareness campaigns, and agricultural yield forecasts. By accessing the full intelligence, stakeholders can stress-test their own assumptions against our proprietary models.
Conclusion: The Value of Informed Strategy
The laxative prune juice market offers a stable growth opportunity within the functional beverage sector, but it is not without its complexities. The interplay between supply constraints, such as the projected decrease in global prune production, and demand drivers like aging populations and health consciousness, creates a dynamic environment. Regulatory shifts, such as tariff suspensions and import standards, further add layers of complexity that require expert navigation.
For organizations operating in or entering this market, the difference between success and stagnation lies in the quality of intelligence guiding their actions. General market knowledge is insufficient when specific segmentation data, competitive motions, and supply chain nuances dictate profitability. Our report is designed to bridge this gap, providing the detailed intelligence necessary to formulate robust strategies.
We invite industry leaders, investors, and analysts to explore the full findings of our Laxative Prune Juice Market research. The complete study offers the depth required to anticipate market shifts, optimize supply chains, and capitalize on emerging opportunities through 2032. To access the detailed segmentation data, comprehensive company profiles, and the full forecast model, please visit the PW Consulting source page. Equip your organization with the insights needed to thrive in this evolving market.
For detailed analysis of this topic, please visit the official page: Laxative Prune Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com