

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Photosensitive Resin Market Hits $6.75B in 2025, Expands at 12.45% CAGR to 2032

Strategic Horizons in the Photosensitive Resin Market: Navigating the 2026–2032 Growth Cycle
The global photosensitive resin market is entering a pivotal phase of expansion, driven by converging forces in advanced manufacturing, electronics miniaturization, and stringent sustainability mandates. For corporate decision-makers, capital allocators, and product strategists operating in 2026, understanding this trajectory is no longer optional—it is a prerequisite for competitive positioning. Our newly released Worldwide Photosensitive Resin Market research provides a structured, data-grounded framework for translating macroeconomic momentum into actionable commercial strategy. This introduction outlines the market's architectural shifts, highlights the operational intelligence embedded in the full report, and demonstrates why timing and precision matter as the industry moves through its next growth cycle.
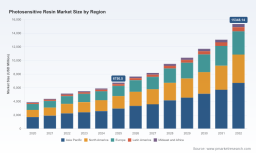
Between 2020 and 2025, the sector demonstrated consistent upward momentum, expanding from approximately 3,885 million USD to 6,750 million USD. That historical arc establishes a clear baseline of demand intensification across multiple end-use verticals. Looking ahead, the forecast window from 2026 through 2032 projects a compound annual growth rate of 12.45 percent, with total revenue anticipated to surpass 15,000 million USD by the close of the period. These figures are not merely indicators of volume; they reflect structural upgrades in material performance, application diversification, and geographic redistribution of manufacturing capacity. For leadership teams, the implication is straightforward: strategies anchored to legacy demand profiles will rapidly lose relevance as performance-grade formulations and specialty chemical architectures capture disproportionate value.
Macro Trajectory and the 2026 Decision Window
The transition from historical expansion to forward-looking growth is characterized by a shift from commoditized photopolymer supply toward engineered resin systems that meet tighter tolerances in thermal stability, mechanical elongation, and regulatory compliance. The 2026–2032 forecast period coincides with a wave of product introductions, capacity expansions, and environmental standard adjustments that collectively reshape procurement economics. As production capacity for UV-curable resins continues to scale, particularly across Asia Pacific, the cost environment for critical inputs such as photoinitiators and oligomers has moderated. This moderation does not uniformly translate into margin expansion, however, because raw material volatility remains a persistent variable. Acrylate monomers, a foundational derivative in photocurable systems, experienced price swings of roughly forty percent in 2023 due to shelf-life constraints and supply chain disruptions. The lesson for procurement and R&D leadership is that cost optimization must be paired with formulation flexibility and supplier diversification.
Worldwide Water Washed Photosensitive Resin Market
At the same time, regulatory trajectories in the United States and European Union are accelerating the adoption of lower-toxicity and higher-recyclability resin formulations. Compliance is becoming a market-access requirement rather than a differentiator, and companies that anticipate certification pathways early will secure faster time-to-market for next-generation grades. Over the past year, resin developers introduced more than 120 new photopolymer grades, including heat-resistant variants rated above 150°C and flexible formulations with elongation reaching 25 percent. This pace of innovation signals that performance envelopes are widening rapidly, allowing photosensitive resins to penetrate applications previously dominated by thermoplastics or engineered elastomers. Decision-makers evaluating portfolio expansion or M&A targets should therefore weigh not only current volume but also the capability to iterate formulations at scale.
Structural Demand Drivers Across High-Growth Verticals
Market growth is being propelled by a cluster of application domains that share a common need for precision patterning, rapid curing, and material customization. Additive manufacturing continues to anchor demand, with 3D printing workflows increasingly relying on specialized photopolymer formulations for prototyping, tooling, and end-use part production. The electronics and printed circuit board segment represents another durable demand pillar, as miniaturization and high-density interconnect requirements push substrate and imaging materials toward finer resolution and improved adhesion characteristics. Dental and medical applications contribute a substantial and fast-evolving share of demand, driven by biocompatible grades, regulatory clearances, and the expansion of digital dentistry workflows. Automotive and aerospace applications, while currently representing a smaller revenue base, are gaining strategic importance as lightweighting initiatives and complex geometry requirements create new openings for stereolithography and high-resolution curing technologies.
Rather than treating these verticals in isolation, the full report maps cross-segment dependencies, substitution risks, and pricing sensitivities. This is critical because photosensitive resin demand is rarely linear; it responds to equipment adoption cycles, regulatory milestones, and downstream OEM specification changes. A formulation that performs well in laboratory conditions may face commercial friction if its curing profile is incompatible with production-line throughput, or if its material cost structure undermines total cost of ownership for the end customer. The research therefore emphasizes application-level economics, procurement seasonality, and the interplay between printer or exposure-system capabilities and resin chemistry.
Worldwide Photosensitive Resin Market
Competitive Dynamics and Strategic Positioning
The competitive landscape reflects a broad geographic and technological spread, with active participants spanning China, Japan, the United States, Austria, and the Netherlands. Several manufacturers have concentrated their efforts on LCD, MSLA, and DLP 3D printing ecosystems, engineering resin grades optimized for resolution, surface finish, and mechanical reliability. Others are building portfolios around UV curing chemistry for broader industrial use, while a distinct group of Japanese and global materials specialists continues to dominate photoresist and electronics patterning applications for semiconductor and display manufacturing. This dual-track structure—additive manufacturing resins on one side and semiconductor-grade photosensitive materials on the other—creates both competitive tension and partnership opportunities, especially as additive processes move closer to production-grade certification.
Recent corporate activity illustrates how rapidly the field is evolving. In mid-2025, one materials company expanded its UV-curable resin sales channels while reporting growth in its specialty and performance materials segment, underscoring the shift toward higher-margin formulations. More recently, another supplier disclosed a significant year-over-year increase in post-consumer recycled resin sales within photoresist and related materials activities, reflecting the growing commercial relevance of circular-content strategies. In product development, a major paper and materials group advanced a biomass-derived photoresist intended for advanced semiconductor patterning, signaling that sustainability-driven chemistry is moving from concept to tangible R&D pipelines. Meanwhile, a leading dental resin supplier secured regulatory clearance for a next-generation clear dental material, reinforcing the importance of compliance milestones in unlocking clinical and commercial adoption. These events are not isolated; they form a pattern in which channel expansion, recycled-content integration, biomass chemistry, and regulatory certification are becoming central levers of competitive advantage.
Market concentration data further contextualizes strategic choices. The three largest participants collectively account for approximately 38.4 percent of revenue, while the top five firms represent roughly 52.15 percent. This level of concentration suggests that scale, distribution reach, and formulation IP remain decisive, but it also leaves meaningful space for specialized players to compete through performance differentiation, regional partnerships, or application-specific certification. The strategic question for 2026 is not whether to participate, but how to position a product roadmap that can withstand raw material volatility, meet evolving compliance expectations, and align with the technical requirements of high-growth end markets.
What the Full Report Delivers for 2026 Strategy Teams
The complete Worldwide Photosensitive Resin Market study is designed to support concrete decisions rather than abstract trend-watching. It consolidates historical performance data, forward forecasts, and segmentation insights into a usable strategic structure. Readers will find a detailed examination of resin types, application categories, and regional demand patterns, with emphasis on the factors that determine where value is created and where margin pressure intensifies. The report also integrates supply-side dynamics, including capacity trends, raw material input sensitivity, and the impact of environmental and safety standards on formulation adoption.
In addition to quantitative modeling, the research provides a structured competitive scan that profiles companies across the additive manufacturing and electronics materials spectrum. Each profile is evaluated in the context of product specialization, application coverage, and recent commercial or regulatory developments, allowing strategy teams to benchmark capabilities, identify potential partnership candidates, and assess vulnerability to substitution. The study further incorporates industry-context intelligence on raw material volatility, capacity expansion, new grade introductions, and sustainability-oriented product development, ensuring that forecasts are anchored in operational realities rather than idealized assumptions.
For teams planning capacity investments, formulation roadmaps, sales-channel expansion, or market-entry assessments, the report offers a consolidated view of where growth is most concentrated and where competitive intensity is likely to rise. It is structured to support scenario comparison, procurement planning, and product positioning discussions without requiring readers to reconcile disconnected data sources or reconcile conflicting market narratives.
Why the 2026–2032 Window Demands Precision Intelligence
The photosensitive resin market is expanding, but expansion alone does not guarantee profitability or market share gains. The sectors capturing the strongest momentum are those where material performance, regulatory readiness, and application integration align. Companies that treat resin selection as a commodity decision will face increasing pressure from suppliers offering differentiated grades with clearer certification pathways, more stable curing behavior, and better alignment with downstream manufacturing constraints. Conversely, organizations that invest early in application-specific formulations, supplier redundancy, and compliance foresight will be better positioned to convert market growth into sustainable margin.
This research was built to reduce uncertainty in exactly those areas. It connects the macro growth trajectory with the operational details that determine commercial outcomes: which resin categories are gaining traction, which applications are driving specification changes, which competitive moves are reshaping channel dynamics, and how raw material and regulatory shifts are altering the cost and risk environment. By consolidating these layers into a single analytical framework, the study enables leadership teams to make more informed choices about R&D prioritization, capital deployment, and market focus.
For a complete view of segmentation detail, competitive profiling, regional momentum, and forward forecasts, the full Worldwide Photosensitive Resin Market report is available through our research portal. The document is intended for strategy, product, and procurement teams that need a reliable basis for 2026 decision-making and for planning across the remainder of the decade.
For detailed analysis of this topic, please visit the official page: Worldwide Photosensitive Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com