

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
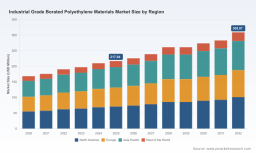
PW Consulting: Industrial Borated Polyethylene Market Hits USD 217.04M in 2025, Projected 5.18% CAGR to 2032

Strategic Imperatives in Industrial Grade Borated Polyethylene Materials: A 2026 Market Intelligence Preview
The industrial grade borated polyethylene market stands at a critical inflection point as of 2026. With global revenue projections indicating steady expansion from approximately 217 million USD in the base year of 2025 toward over 309 million USD by the end of the forecast window in 2032, the sector demonstrates a compound annual growth rate that underscores sustained demand for neutron shielding solutions across nuclear, medical, and defense verticals. For strategic planners, procurement leaders, and competitive intelligence teams, navigating this landscape requires more than top-line figures. It demands a granular understanding of material formulations, regulatory compliance pathways, regional supply dynamics, and the evolving positioning of key manufacturers. This preview outlines the strategic architecture of our newly released market research study and explains why access to its full analytical framework will be indispensable for enterprise decision-making throughout 2026 and beyond.
Worldwide Industrial Grade Ammonium Pentaborate Market
The Macro Trajectory: Reading Growth Beyond the Headline
Historical revenue patterns from 2020 through 2025 reveal a market that has consistently navigated raw material volatility, shifting nuclear energy policies, and evolving medical radiation protection standards. The transition into the 2026-2032 forecast period suggests that growth will not be linear. Instead, it will be shaped by uneven adoption cycles across applications, divergent regional procurement rhythms, and material substitution pressures that reward manufacturers capable of balancing cost efficiency with certified shielding performance. The study maps these inflection points without relying on surface-level percentage breakdowns. Instead, it contextualizes how revenue concentration, formulation preferences, and application-specific procurement behaviors interact to create pockets of margin expansion and competitive vulnerability. Readers who engage with the complete report will gain a structured view of where volume growth converges with pricing resilience, and where commoditization risks threaten undifferentiated producers.
Segmentation Dynamics: Boron Loading, Applications, and Regional Realities
The commercial architecture of borated polyethylene is fundamentally defined by boron concentration, application criticality, and geographic supply chain maturity. Formulations ranging from lighter boron loadings to high-concentration variants serve distinct shielding requirements, with procurement decisions often dictated by neutron flux profiles, spatial constraints, and regulatory specifications. Similarly, end-use environments span from nuclear power reactors and medical radiotherapy facilities to research accelerators, nuclear propulsion systems, and radioactive waste containment. Each vertical imposes unique certification demands, thickness tolerances, and fabrication expectations that directly influence supplier selection.
Regional supply and demand patterns further complicate the competitive picture. Manufacturing footprints, logistics infrastructure, and local regulatory frameworks create divergent cost structures and delivery timelines. The study disentangles these regional dynamics by examining how procurement hubs interface with production clusters, how import-export flows respond to certification bottlenecks, and how localized content requirements shape sourcing strategies. Rather than presenting static regional revenue splits, the analysis focuses on the operational mechanisms that determine which suppliers can reliably serve which markets, under what compliance conditions, and at what total cost of ownership.
Competitive Landscape: Strategic Positioning Among Core Players
The industry features a concentrated but differentiated supplier base, with leading manufacturers distinguished by proprietary processing methods, certification portfolios, customization capabilities, and vertical market focus. Several organizations have built recognizable identities around specific product architectures and application specializations, creating defensible niches within a market that increasingly rewards technical reliability and supply chain consistency.
-
King Plastic Corporation has reinforced its market presence through targeted exhibition participation, including appearances at the International Sign Expo and the NRPA Annual Conference, signaling continued engagement with both industrial and specialized material buyers. Its product positioning emphasizes trademarked shielding formulations and proprietary processing techniques designed to deliver flatness and dimensional consistency in large-format sheets and custom configurations.
Industrial Grade Borated Polyethylene Materials Market -
MarShield Custom Radiation Products has expanded its strategic alignment with nuclear energy initiatives by joining Canadians for CANDU, while maintaining a broad offering of borated polyethylene sheets, pellets, and custom shapes. Its certification ratings and fabrication services position it as a solutions-oriented supplier for nuclear, medical, and industrial neutron shielding requirements.
-
Emco Plastics maintains a strong compliance-oriented profile, offering borated HDPE sheets with multiple boron content options and adherence to military and ASTM specifications. Its ITAR registration and thickness/size versatility support demand from nuclear power plants, medical facilities, aerospace, and radioactive material storage and transport applications.
-
A&L Shielding focuses on cost-effective, lightweight neutron and gamma shielding solutions, emphasizing standard large-format sheet configurations for medical and industrial environments where installation efficiency and material economy are priorities.
-
Radiation Protection Products, Inc. supplies a recognizable purple-hued borated polyethylene line in standard and custom formats, serving nuclear reactors, medical vaults, linear accelerators, and research facilities with an emphasis on accessible standard inventory and custom fabrication flexibility.
-
NELCO Worldwide addresses security and propulsion-adjacent applications with both standard and higher boron content options, supporting cargo screening, border protection, and nuclear submarine-related shielding needs through configurable sheet formats and machining services.
-
Shandong Yasu New Material Co., Ltd. stands out for its highly customizable boron content range and broad product formats, including sheets, rods, and pellets, targeting nuclear power, medical therapy rooms, particle accelerators, and aerospace/defense applications. Its formulation flexibility positions it as a responsive supplier in markets where shielding specifications vary significantly across projects.
The full study evaluates these players through a structured competitive assessment framework, examining product differentiation, certification coverage, regional service reach, fabrication capabilities, and recent strategic moves. Rather than simply cataloging company profiles, the analysis identifies where competitive advantages are likely to persist, where price competition may intensify, and how recent partnerships and trade show engagements signal shifting commercial priorities.
Market Dynamics and Strategic Variables
Several operational and regulatory forces continue to shape procurement behavior and supplier competitiveness. Material pricing illustrates the premium associated with higher boron loadings, with standard 5% boron sheets carrying materially different cost profiles than 30% boron variants. This pricing gradient influences application selection, especially in projects where shielding performance requirements can be met through formulation optimization rather than blanket upsizing. Understanding these cost-performance tradeoffs is essential for buyers seeking to balance compliance, weight, spatial constraints, and budget.
Regulatory compliance remains a decisive filter in competitive access. Military specifications such as MIL-P-23536A and EB2562E continue to govern neutron shielding expectations for naval and defense-related deployments, while nuclear sector standards impose additional requirements on hydrogen density, aging effects, and spent fuel storage system compositions. Suppliers that can demonstrate consistent certification adherence, documentation rigor, and test-backed performance claims gain preferential access to high-assurance procurement channels. The study examines how these regulatory layers affect market entry barriers, customer retention, and the economics of qualification-led selling.
Supply chain resilience also warrants close attention. Fabrication services, custom machining, stocking strategies, and cut-to-size capabilities increasingly differentiate suppliers in contexts where end users prioritize project-ready materials over commodity sheet purchases. Companies that combine certified material supply with CNC or waterjet cutting, custom block and slab production, and responsive inventory positioning are better equipped to capture value in complex procurement environments. These capabilities are not merely service add-ons; they are increasingly central to supplier selection in medical, nuclear, and defense applications where installation precision and lead-time reliability carry substantial operational weight.
What the Study Delivers: Operational Intelligence for Decision-Makers
This market research is structured to translate market complexity into actionable strategic guidance. Beyond baseline sizing and trend mapping, the report provides a working view of how material technology, regulatory expectations, and procurement behavior intersect across the forecast period. It is designed for teams that need to evaluate supplier risk, prioritize market entry or expansion, calibrate product development roadmaps, and align sourcing strategies with evolving shielding requirements.
Key components of the study include:
-
A detailed segment architecture that explains how boron loading choices, application criticality, and regional procurement habits shape demand trajectories and margin dynamics.
-
A competitive positioning map that evaluates core manufacturers on formulation range, certification coverage, fabrication capabilities, and strategic signaling through partnerships and exhibition activity.
-
An analysis of pricing structure logic, showing how standard and high-concentration formulations create differentiated procurement economics across use cases.
-
A regulatory and compliance overlay that clarifies the role of military specifications, nuclear standards, and documentation requirements in shaping buyer preference and supplier eligibility.
-
Forward-looking scenario framing for the 2026-2032 period, highlighting where volume growth, application diversification, and supply chain maturity are likely to reshape competitive access.
The full report is built to support both strategic planning and execution-level decisions. It provides the contextual depth needed to interpret market movements, assess supplier capabilities, and anticipate where procurement standards and material specifications will tighten or evolve.
Why Strategic Access Matters in 2026
As enterprises navigate a market defined by steady growth, concentrated competition, and rising technical expectations, the cost of incomplete intelligence is increasingly measurable. Procurement teams that lack visibility into formulation economics may overspend on over-specified materials or under-specify shielding performance. Market expansion teams that rely on generic segmentation may misjudge regional readiness or overestimate the transferability of product offerings. Competitive analysts who overlook certification pathways and fabrication capabilities may misread which suppliers are truly positioned to win high-assurance contracts.
The study addresses these blind spots by connecting market structure to decision quality. It offers a disciplined framework for interpreting growth signals, assessing supplier reliability, and anticipating where regulatory or application-specific demands will alter purchasing behavior. For organizations operating in nuclear energy, medical radiation protection, research infrastructure, defense, or radioactive material handling, this intelligence provides a practical foundation for sourcing strategy, product planning, and competitive positioning.
Conclusion: Moving from Market Awareness to Strategic Action
The industrial grade borated polyethylene market is not simply expanding; it is maturing in ways that reward technical precision, compliance readiness, and supply chain flexibility. The trajectory through 2032 suggests continued demand growth, but the distribution of that growth will favor participants who can align formulation choices, certification strength, fabrication capability, and regional service capacity with the specific requirements of each application. Our full market research unpacks these dynamics with the depth required for confident strategic action. For decision-makers who need more than headline sizing and broad trend statements, the complete study offers the structured intelligence necessary to convert market momentum into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Industrial Grade Borated Polyethylene Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com