

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 2D Ablation Catheter Market Hits $552.48M in 2025, Projects 4.58% CAGR to 2032

Global 2D Ablation Catheter Market 2026: Strategic Imperatives in a Consolidating Electrophysiology Landscape
The worldwide market for 2D ablation catheters is entering a decisive growth phase, shaped by epidemiological demand, technological evolution, and a highly concentrated competitive field. As cardiac arrhythmias continue to drive procedural volumes across healthcare systems, manufacturers and investors must navigate a landscape where precise segmentation intelligence determines capital allocation, partnership strategy, and commercialization timing. This analysis previews the strategic value of our latest Worldwide 2D Ablation Catheter Market research, a comprehensive assessment designed to equip executive teams with the operational clarity required for 2026 planning cycles.
Market Trajectory and Structural Growth Drivers
The sector has demonstrated resilient expansion over the past half-decade, with total market revenue climbing from approximately 442.15 million USD in 2020 to an estimated 552.48 million USD in 2025. Forward projections indicate sustained momentum, with the market expected to reach 558.58 million USD in 2026 and advance toward 755.93 million USD by 2032. This trajectory translates to a compound annual growth rate of 4.58 percent across the 2026 to 2032 forecast window, reflecting a market that is neither hyper-aggressive nor stagnant, but steadily compounding through procedural volume growth, device iteration, and geographic penetration.
Several structural forces underpin this expansion. The rising prevalence of atrial fibrillation and other tachyarrhythmias continues to expand the addressable patient pool, while electrophysiology laboratories seek standardized, cost-effective workflows that integrate mapping and ablation capabilities. Energy-source diversification has also intensified, with radiofrequency platforms maintaining a dominant share of clinical practice, cryoablation systems sustaining a strong niche in pulmonary vein isolation protocols, and laser and microwave catheters capturing incremental adoption for specialized lesion sets. Competitive positioning increasingly hinges on how effectively manufacturers align catheter geometry, contact assessment, and irrigation design with operator preferences and institutional procurement frameworks.
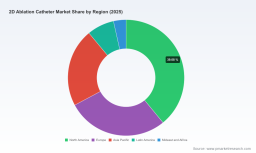
Regional deployment patterns reveal a mature core alongside high-growth frontier markets. North America and Europe anchor absolute revenue due to established reimbursement structures, dense electrophysiology center networks, and early adoption of advanced mapping integration. Asia Pacific, Latin America, and the Middle East and Africa collectively represent accelerating procedural uptake, driven by expanding cardiac care infrastructure and localized commercialization efforts. The report dissects these geographic gradients without reducing them to static snapshots, instead mapping how pricing dynamics, tendering cycles, and regulatory timelines shape revenue realization over the forecast horizon.
Competitive Architecture and Strategic Positioning
Market concentration remains pronounced, with the top three participants commanding approximately 62.45 percent of total revenue and the top five firms consolidating around 78.12 percent. This concentration does not imply immobility; rather, it highlights a field where differentiation is earned through product integration, clinical evidence generation, and regulatory execution. The incumbents have built formidable moats by coupling ablation catheters with mapping ecosystems, imaging modalities, and navigation workflows, creating sticky purchasing patterns within hospital procurement and physician preference structures.
Biosense Webster, operating under Johnson and Johnson MedTech, continues to leverage its THERMOCOOL SMARTTOUCH SF radiofrequency portfolio alongside CARTO 3D mapping integration, while reinforcing procedural visualization through the SOUNDSTAR CRYSTAL 2D ICE ultrasound catheter. This dual emphasis on lesion formation and real-time imaging reflects a broader industry trend: catheters are no longer evaluated solely by energy delivery, but by how seamlessly they fit into image-guided, efficiency-oriented operating workflows.
Worldwide Cardiac Radiofrequency Catheter Market
Boston Scientific maintains a strong electrophysiology footprint through the BLAZER and INTELLATIP MIFI families, emphasizing open-irrigated designs and contact force sensing, while also participating in pulsed field ablation development with the Farapoint catheter. Abbott has advanced sensor-enabled contact force technology through its TactiFlex Duo and Volt platforms, with recent CE Mark approval for the TactiFlex Duo ablation catheter in atrial fibrillation and complex arrhythmia treatment, signaling continued expansion of its multi-energy strategy. Medtronic continues to balance radiofrequency and pulsed field approaches via the Sphere-9 mapping and ablation catheter within the Affera system, complemented by its Arctic Front family of cryoablation catheters for pulmonary vein isolation.
Emerging and regionally focused players are reshaping competitive pressure through targeted innovation and cost-competitive manufacturing. Shanghai MicroPort EP MedTech has expanded its multi-energy portfolio with the FireMagic and PulseMagic TrueForce ablation catheters, integrating pressure sensing and saline irrigation, alongside the Columbus 3D mapping system and robotic navigation collaborations. Its recent NMPA approval and launch of the PulseMagic TrueForce pulsed field ablation catheter demonstrates how rapid regulatory execution can accelerate platform relevance. Biotronik contributes the AlCath family of steerable irrigated and non-irrigated radiofrequency catheters with gold-tip technology, reinforcing reliability-focused value propositions. Japan Lifeline supplies disposable electrode catheters for diagnosis and radiofrequency ablation, reflecting enduring demand for standardized single-use solutions in high-throughput environments.
Specialized navigation and robotic approaches also shape competitive differentiation. Stereotaxis has secured FDA approval for the MAGiC Magnetic Interventional Ablation Catheter, enabling robotically navigated radiofrequency ablation for complex cases including supraventricular tachycardia in congenital heart disease patients where conventional navigation is constrained. Osypka Medical and APT Medical continue to serve electrophysiology programs with specialized ablation catheters and steerable irrigated designs, respectively, underscoring the importance of tailored form factors and procedural flexibility. CardioFocus rounds out the field with focal and balloon pulsed field ablation catheters such as QuickShot Nav and OptiShot, targeting pulmonary vein isolation in atrial fibrillation and illustrating how energy modality innovation can open new adoption pathways.
Report Scope: Operational Intelligence for Commercial and Clinical Strategy
The study is structured to convert market complexity into actionable planning inputs. It begins with a quantitative baseline and forecast model that tracks revenue evolution across the 2020 to 2032 period, anchoring decision-makers in a defensible trajectory rather than isolated data points. This framework is paired with segmentation analysis that examines product type, clinical application, and regional deployment in a manner designed to inform portfolio prioritization and go-to-market sequencing.
The report also delivers a detailed competitive benchmarking module that evaluates product architecture, mapping and imaging integration, energy modality coverage, and geographic execution capability. Rather than reducing competitors to headline metrics, the analysis examines how product families align with procedural workflows, how innovation pipelines intersect with regulatory roadmaps, and where partnership or acquisition opportunities may arise for firms seeking to broaden their electrophysiology footprint.
Worldwide 2D Ablation Catheter Market
Clinical and operational context is embedded throughout. The assessment integrates reimbursement dynamics, including how procedure coding structures influence lab economics and how mapping billing practices interact with catheter selection. It also addresses regulatory realities, including the role of clearance pathways in shaping U.S. market entry and product iteration cycles. These elements are presented as strategic variables, not background noise, enabling teams to anticipate margin pressure, procurement friction, and adoption barriers before they affect execution timelines.
In addition, the study includes a technology and workflow lens that explores how catheter design, contact assessment, irrigation strategies, and visualization tools influence procedural efficiency and operator confidence. This section is particularly relevant for organizations evaluating next-generation platform development, clinical evidence generation, or cross-selling strategies within hospital systems. By linking device characteristics to practical adoption drivers, the report supports more precise positioning and more realistic commercialization assumptions.
Regulatory, Reimbursement, and Workflow Dynamics
The market does not evolve in a vacuum. Regulatory frameworks, reimbursement architecture, and institutional workflow expectations collectively determine how quickly innovation translates into revenue. In the United States, the FDA 510(k) clearance process remains the primary pathway for most 2D ablation and related ICE catheters, with recent activity reflecting ongoing enhancements to mapping system compatibility and ultrasound-guided ablation workflows. These regulatory nuances matter because they influence time-to-market, labeling scope, and the pace at which manufacturers can introduce incremental improvements that strengthen competitive positioning.
Reimbursement conditions further shape adoption economics. Current procedural coding for intracardiac catheter ablation does not differentiate by energy source or by 2D versus 3D mapping, and 2D mapping remains separately billable only when no 3D mapping is performed. This structure has direct implications for how manufacturers frame value propositions, particularly in settings where institutions balance clinical outcomes against resource utilization. Meanwhile, CMS maintains MS-DRG classifications for inpatient cardiac ablation procedures, with periodic updates to practice expense inputs affecting physician payments and electrophysiology lab economics. These reimbursement dynamics are not static; they require continuous monitoring, especially for organizations planning pricing strategies, volume forecasts, or multi-market rollout plans.
Workflow integration remains a decisive adoption factor. Electrophysiology teams increasingly prioritize devices that reduce setup complexity, improve lesion consistency, and align with existing mapping or imaging infrastructure. As a result, competitive advantage often derives from the coherence of the overall solution rather than isolated catheter performance. The report examines these dynamics to help teams anticipate where procurement decisions will be won or lost, particularly in cost-sensitive environments or regions with developing electrophysiology capacity.
Strategic Takeaways for 2026 Decision-Making
For organizations operating in or entering this market, the 2026 outlook calls for disciplined prioritization. Growth is real, but it is distributed unevenly across regions, indications, and product categories. Firms that treat the market as a single block risk misallocating resources, while those that understand where procedural volume, reimbursement stability, and adoption readiness intersect can deploy capital with greater precision. The concentration of revenue among leading players also means that competitive responses can move quickly; product launches, regulatory approvals, and mapping integration enhancements can shift purchasing patterns faster than traditional forecasting cycles anticipate.
The study is designed to support that discipline. It provides a structured view of where demand is expanding, which technologies are gaining procedural traction, how incumbents and challengers are differentiating, and what regulatory and reimbursement variables may alter execution timelines. By grounding these insights in a consistent forecast framework and competitive analysis, the report enables teams to stress-test assumptions, refine pipeline priorities, and align commercial strategy with the realities of electrophysiology procurement and clinical adoption.
To access the full segmentation detail, regional breakdowns, application-level analysis, and company-specific strategic profiles that underpin these conclusions, we invite stakeholders to explore the complete Worldwide 2D Ablation Catheter Market report. The full intelligence package is intended for teams that require granular, decision-grade data to guide product planning, market entry, partnership evaluation, and investment allocation through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Ablation Catheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com