

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glufosinate Ammonium Market Hits $621.88M in 2025, 14.02% CAGR to $1.56B by 2032

Strategic Intelligence in a High-Concentration Herbicide Market: Why the 2026–2032 Outlook Matters Now
The global high concentration glufosinate ammonium market is entering a phase of structural acceleration that will separate the prepared from the reactive. From a base year of 2025, the sector is projected to expand from a 2020 baseline of USD 310.5 million to USD 1556.11 million by 2032, reflecting a compound annual growth rate of 14.02 percent over the 2026–2032 forecast period. This trajectory is not merely a function of volume growth. It represents the intersection of trait-driven demand, regulatory recalibration, geographic supply realignments, and a market structure in which competitive intensity is heavily concentrated. For executives evaluating procurement strategies, formulation roadmaps, and regional entry or exit decisions, the period ahead will reward those who can decode the market’s layered dynamics well before they become visible in quarterly results.
Our newly released Worldwide High Concentration Glufosinate Ammonium Market research translates these signals into operational clarity. The study is designed as a decision-grade platform, not a static snapshot. It maps the market’s evolution from 2020 through 2025, then projects forward across 2026 to 2032, with a particular emphasis on where concentration, pricing power, and regulatory exposure will shape margin profiles. In this preview, we outline the strategic contours of the report and explain why the coming years will demand a sharper reading of the market than historical trend extrapolation can provide.
A Market Defined by Concentrated Supply and Expanding Demand Architecture
High concentration glufosinate ammonium is increasingly positioned as a strategic herbicide active within the broader crop protection portfolio. Its growth appeal stems from its role in managing weed resistance, supporting trait-integrated cropping systems, and serving non-agricultural and specialty applications. Yet what makes this market especially consequential for 2026 decision-making is the way demand is distributed across use cases and geographies, while supply remains tightly held among a limited set of producers.
The overall revenue expansion observed over the historical window underscores a durable upward path rather than a temporary cycle. Revenue scaled from the 2020 level of USD 310.5 million to USD 621.88 million in 2025, and the forecast continues that ascent, reaching USD 706.6 million in 2026, USD 1188.37 million in 2030, and USD 1556.11 million in 2032. This slope implies that the market will not simply continue to grow; it will accelerate in strategic importance as integrated cropping systems and resistance management practices become more entrenched in major production regions.
That said, aggregate growth can obscure the operational realities that determine who captures value. The report therefore examines the market through a concentration lens, recognizing that competitive behavior, pricing, and availability are shaped by a limited number of dominant participants. With a CR3 of 58.4 percent and a CR5 of 72.15 percent, the landscape is not fragmented in the conventional sense. This degree of concentration creates both opportunity and vulnerability: it enables coordinated product stewardship, brand-led differentiation, and technical formulation leadership, but it also heightens the impact of capacity decisions, trade policy shifts, and regulatory actions on downstream users.
Worldwide High Concentration Glufosinate Ammonium Market
Glufosinate Ammonium Market
The 2026 Decision Window: Why Timing Is Now a Strategic Variable
The 2026–2032 outlook is particularly instructive because it captures the market at the point where several structural forces converge. First, trait-validated usage is expected to remain a core demand anchor. Glufosinate ammonium has gained durable relevance in systems where selective weed control must complement resistant crop platforms, especially in broad-acre crops such as soybean, corn, cotton, and canola. As resistance pressure increases, herbicide programs that depend on multiple modes of action are more likely to be standardized, and glufosinate’s role as a broad-spectrum partner is strengthened in that context.
Second, the report’s forecast period is shaped by policy and regulatory developments that directly influence sourcing economics and competitive positioning. In the near term, Chinese export incentives for glufosinate ammonium technical have been removed, effective April 1, 2026. This policy change altered immediate price dynamics and encouraged suppliers to re-evaluate channel strategies, contract structures, and destination-market focus. At roughly the same time, technical quotations have moved into a tighter supply posture, reflecting constraints on effective availability and upstream cost pressures. These conditions make it increasingly difficult to treat technical pricing as a stable input variable. Instead, procurement and planning functions need a forward-looking framework that accounts for volatility rather than assuming continuity.
Third, regulatory calibration continues to determine which use patterns can scale and which require reformulation or regional adaptation. Recent regulatory actions in the United States, including updated tolerance levels for glufosinate residues in rice and tea, and the registration of L-glufosinate as a distinct active ingredient for use in major crops, create new commercial pathways while also redefining compliance obligations. The emergence of L-glufosinate, or glufosinate-P, adds another layer of strategic complexity because it blurs the line between commodity active supply and differentiated technical offerings. Companies that can align product architecture with these regulatory and trait-related shifts will be better positioned to defend margin and expand share.
Inside the Report: What Decision-Makers Can Put to Work Immediately
Our Worldwide High Concentration Glufosinate Ammonium Market study is built as an operational reference for market entry, competitive response, supply chain design, and portfolio planning. Instead of offering only top-line projections, the report decomposes the market into the dimensions that determine where dollars are made and where exposure accumulates. The following elements are covered in detail:
- A full historical reconstruction from 2020 through 2025, paired with a forward forecast from 2026 to 2032, enabling users to compare realized performance with projected momentum and to test scenario assumptions against a consistent baseline.
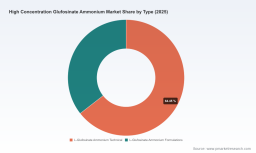
- Segment-level mapping across region, product type, and application, so that buyers and suppliers can see where high concentration glufosinate ammonium is being deployed, where demand is most concentrated, and where growth is likely to be disproportionately driven by specific end uses and geographies.
- Competitive landscape analysis focused on the companies that shape pricing, availability, and product direction, with attention to their product families, geographic footprints, and strategic positioning in both technical and formulated supply chains.
- Market concentration assessment, including the implications of a highly consolidated supply structure for negotiation power, supply security, and new entry difficulty.
- Recent industry developments, from policy changes affecting trade economics to regulatory decisions that influence residue tolerances and active-ingredient registrations, with an emphasis on what these events mean for sourcing and product strategy.
- Supply-side context, including production capacity trends, conversion dynamics, and the relationship between technical availability and formulated product access across markets.
- Actionable diagnostic frameworks that enable executives to link market structure to commercial outcomes, such as pricing behavior, regional demand elasticity, and the strategic value of trait-compatible offers.
The report is structured so that strategy, R&D, procurement, and commercial teams can work from the same evidence base. Rather than isolating data into separate appendices, the analysis connects market size, segmentation patterns, and regulatory events to the practical questions that managers face: where to invest, what to source, which partnerships matter, and how to prepare for volatility in a market where effective supply and trade conditions can shift quickly.
Competitive Landscape: Who Shapes the Market and How
In a market with this level of concentration, competitive intelligence cannot be reduced to revenue comparison alone. The players that matter are those with the ability to influence technical supply, formulation quality, trait-linked commercialization, and channel reach. The report profiles the companies whose strategic conduct is most consequential to the high concentration glufosinate ammonium market.
BASF SE remains a central force in the global landscape, with deep-rooted herbicide brands and a strong emphasis on both broad-spectrum weed control and trait-compatible solutions. Its product heritage and integrated capabilities give it a prominent role in shaping how glufosinate ammonium is positioned across agricultural and non-crop applications. Bayer AG, through its crop science division, brings a similarly strong global footprint and an emphasis on high-efficacy formulations tied to resistance management in major row crops. The company’s presentation of glufosinate-based offerings alongside trait-integrated systems illustrates how the active has moved from a standalone chemistry story to part of a broader agronomic package.
On the supply side, several Chinese manufacturers are especially important because they combine technical-grade production scale with growing export presence. Lier Chemical Co., Ltd. and Zhejiang YongNong Chemical Co., Ltd. stand out as major producers of technical and high-concentration formulations, with capacity and commercial strategies that affect global availability. Jiangsu Huangma Agrochemicals Co., Ltd. also contributes actively to domestic and export supply through compliant technical and formulated products. Shandong Weifang Rainbow Chemical Co., Ltd. and Zhejiang Wynca Chemical Industry Group further add to the technical-grade production base, reinforcing the importance of China as a center of manufacturing gravity for this active.
International formulators and distributors also play a decisive role in translating technical supply into regional market access. UPL Limited operates global generic formulator and marketer channels that broaden distribution reach across multiple geographies. Adama Agricultural Solutions Ltd. focuses on tailored, more sustainable crop protection solutions and regionalized formulation strategies. Nufarm Limited supplies glufosinate-based products into agricultural, turf, and ornamental applications, with a market emphasis that includes Australia, New Zealand, and Europe. FMC Corporation participates through its broader crop protection portfolio, reinforcing the active’s relevance across multiple weed control contexts.
What ties these companies together in the report’s analysis is not merely their presence, but the way their strategies influence market outcomes. Recent developments highlight how fast this can happen. Lier Chemical’s 2025 financial forecast pointed to a substantial increase in net profit associated with L-glufosinate scale-up and strengthened multinational partnerships, signaling that technical differentiation and partnership architecture can generate disproportionate benefits when aligned with demand momentum. At the same time, policy changes such as the elimination of the export tax rebate in China have created immediate price and supply chain responses that ripple through global sourcing. Meanwhile, regulatory updates in the United States and trade measures in other markets continue to reshape the boundaries within which competitors can scale.
Market Dynamics That Will Define 2026 and Beyond
Several dynamic forces will determine whether companies navigate this market with advantage or expose themselves to avoidable risk. One is the relationship between technical availability and formulation access. Capacity growth in technical-grade production, including the scale of national technical capacity reached in China by late 2025, has expanded the underlying supply base, but that does not automatically translate into stable pricing or predictable distribution. Tight order schedules and upward price pressure in technical quotations show that effective supply can remain constrained even when headline capacity appears substantial. For buyers, this means that contract design, inventory strategy, and supplier selection must account for both physical availability and the commercial behavior of concentrated producers.
Another dynamic is the interaction between trait systems and herbicide demand. As resistance management becomes more central to cropping economics, glufosinate ammonium’s broad-spectrum utility supports its continued presence in integrated programs. However, the strategic value of the active increasingly depends on whether it is positioned as a standard chemical input or as part of a trait-compatible, high-efficacy package. Companies that can align product strength, formulation quality, and agronomic messaging with the needs of resistance-prone systems are more likely to capture premium positioning.
Trade and regulatory conditions add another layer of complexity. The removal of export tax incentives for certain glufosinate technicals has reshaped the economics of international supply, affecting price discovery and destination-market competitiveness. At the same time, minimum import price conditions and residue tolerance decisions influence which materials can enter specific channels and at what cost. The registration of L-glufosinate as a new active ingredient introduces both opportunity and differentiation risk. It opens space for more targeted product narratives while also raising expectations around technical purity, compliance, and crop-specific performance.
Taken together, these dynamics point to a market in which reactive planning is costly. The companies that perform best through 2032 will likely be those that treat volatility as a design parameter rather than a disruption to be absorbed after the fact. That means stress-testing sourcing strategies against regulatory change, monitoring how concentrated suppliers adjust output and pricing, and evaluating where formulation, registration, and partnership decisions can create defensible advantage.
What This Report Enables: From Intelligence to Execution
The value of this study lies in its ability to convert market structure into commercial choices. For procurement and supply chain leaders, the report provides a framework for understanding where technical price risk originates, how concentration affects negotiation leverage, and which supply relationships matter most under shifting trade and production conditions. For commercial and portfolio teams, it clarifies where demand is developing most strongly across applications and geographies, and where trait-linked use cases create more durable demand than price-sensitive volume plays. For strategy and corporate development functions, it maps the competitive field in a way that exposes not only who is present, but how value is created and defended through formulation, registration, and channel strategy.
Equally important, the report helps organizations prioritize what to watch. In a market where policy actions, tolerance updates, capacity expansions, and active-ingredient registrations can alter competitive conditions quickly, the difference between strong and weak positioning often comes down to early awareness and the ability to convert that awareness into action. By connecting historical performance, forward forecasts, competitive behavior, and recent market events, the study gives decision-makers a shared basis for scenario planning, sourcing strategy, and product roadmap decisions.
The Worldwide High Concentration Glufosinate Ammonium Market research is intended to support that process from the first wave of strategic review through ongoing execution. The macro trajectory suggests a market with strong growth momentum, but the operational reality is more nuanced. Concentration, trade policy, regulatory calibration, and trait-driven demand will determine how that growth is distributed. Understanding those forces now is the difference between following the market and shaping your position within it.
Conclusion: Why the 2026–2032 Outlook Deserves Disciplined Attention
The worldwide high concentration glufosinate ammonium market is moving into a period where growth is not the only question that matters. The more consequential issues are where value will accrue, which supply relationships will hold under pressure, how regulatory and trade shifts will alter cost structures, and which competitive strategies will be durable as technical and formulated markets continue to evolve. With revenue projected to expand from USD 706.6 million in 2026 to USD 1556.11 million in 2032 at a 14.02 percent CAGR, the stakes are high, and the margin for delayed action is shrinking.
This report is designed to help leaders act with precision. It provides the segmentation structure, competitive context, and market dynamics needed to make sourcing, product, and geographic decisions with greater confidence. For organizations that need to move beyond surface-level market descriptions and into the logic of pricing, concentration, regulation, and demand architecture, the full study offers the depth required to support 2026 planning and the years that follow.
For detailed analysis of this topic, please visit the official page: Worldwide High Concentration Glufosinate Ammonium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com