

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Absorbable Antibacterial Envelope Market to Hit $338.18M by 2032, 9.0% CAGR
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Absorbable Antibacterial Envelope Market: Navigating Growth and Infection Control Through 2032
The global healthcare landscape is undergoing a profound transformation driven by an aging demographic, the rising prevalence of cardiovascular conditions, and an intensified focus on reducing hospital-acquired infections. Within this context, cardiac implantable electronic devices (CIEDs) have become indispensable for managing arrhythmias and heart failure. However, the associated risk of device-related infections remains a critical challenge, impacting patient outcomes, increasing readmission rates, and imposing significant economic burdens on healthcare systems. As the industry seeks advanced solutions to mitigate these risks, the absorbable antibacterial envelope market has emerged as a vital segment, offering innovative technologies designed to protect implanted devices while eliminating the need for permanent foreign materials.
For executives, investors, and strategic planners operating in the medical device and healthcare sectors, understanding the trajectory of this specialized market is no longer optional; it is a strategic necessity. Our latest comprehensive research, Worldwide Absorbable Antibacterial Envelope Market , provides an in-depth analysis of this evolving landscape, offering the granular intelligence and forward-looking insights required to navigate the complexities of 2026 and beyond. This article serves as a strategic preamble, highlighting the key dynamics, growth catalysts, and competitive forces that define the market, while underscoring the indispensable value of our full research report for data-driven decision-making.
Market Trajectory: From Resilience to Sustained Expansion
The absorbable antibacterial envelope market has demonstrated remarkable resilience and consistent growth over the past half-decade, reflecting the increasing adoption of infection prevention protocols in electrophysiology and cardiac surgery. Our analysis tracks a clear upward trajectory, with the global market valuation rising from 110.0 million USD in 2020 to an estimated 185.0 million USD by 2025. This growth underscores the market's transition from a niche application to a mainstream component of CIED implantation procedures, fueled by heightened awareness of infection-related complications and the clinical efficacy of absorbable drug-eluting technologies.
Looking ahead, the forecast period from 2026 to 2032 projects a compelling expansion path. The market is anticipated to reach approximately 203.23 million USD in 2026, accelerating toward a peak valuation of 338.18 million USD by 2032. This long-term outlook is anchored by a compound annual growth rate (CAGR) of 9.0 percent, signaling robust demand drivers that extend well beyond short-term fluctuations. Such sustained growth indicates a maturing ecosystem where absorbable envelopes are increasingly integrated into standard care pathways, supported by favorable clinical evidence, regulatory validations, and evolving reimbursement frameworks. For stakeholders, this trajectory represents both a significant revenue opportunity and a call to action for strategic positioning in a rapidly consolidating space.
Segmentation Dynamics: Unpacking Value Across Types, Applications, and Regions
The structural composition of the absorbable antibacterial envelope market reveals distinct value pools that warrant careful strategic consideration. Our research dissects the market across multiple dimensions, providing a granular view of how different segments contribute to overall performance and where future growth vectors are likely to concentrate.
In terms of product architecture, the market is delineated by the distinction between drug-eluting and non-drug-eluting envelopes. The drug-eluting category, which incorporates antimicrobial agents directly into the bioabsorbable matrix, has established itself as the dominant paradigm, reflecting the clinical preference for active infection prophylaxis over passive barrier methods. This segment captures the lion's share of market value, driven by the widespread utilization of envelopes that release rifampin and minocycline to combat a broad spectrum of pathogens. The non-drug-eluting segment, while smaller in comparison, serves specific clinical niches and continues to evolve as material science advances. Understanding the relative performance, adoption rates, and pricing dynamics of these categories is essential for manufacturers and distributors aiming to align their portfolios with clinical demand.
Worldwide Absorbable Antibacterial Envelope Market
Application-wise, the market is heavily influenced by the underlying volume and complexity of CIED procedures. Pacemaker implantation remains the cornerstone application, accounting for a substantial portion of envelope utilization due to the high global volume of pacemaker placements and the established protocols for infection reduction in these procedures. Implantable cardioverter-defibrillator (ICD) implantation represents another major application segment, where the higher energy requirements and complex lead configurations often necessitate additional protection against pocket infections. Beyond these primary uses, the category of other CIED implantations, including cardiac resynchronization therapy devices, contributes to the broader demand landscape. Each application presents unique clinical requirements, reimbursement considerations, and growth potentials that our report analyzes in detail.
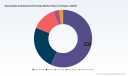
Geographically, the market exhibits a pronounced concentration in developed regions, with North America commanding a leading position in terms of revenue generation and adoption maturity. This dominance is supported by advanced healthcare infrastructure, high rates of CIED implantation, favorable reimbursement policies, and the early availability of innovative technologies. Europe follows as a significant market, characterized by robust clinical standards and a growing emphasis on infection control mandates across national health systems. Meanwhile, the Asia Pacific region represents an emerging frontier with substantial untapped potential, driven by expanding access to cardiac care, rising healthcare expenditures, and a growing patient population. Latin America and the Middle East and Africa, though currently smaller in absolute terms, are beginning to show incremental growth as awareness of advanced infection prevention technologies permeates these markets. Our full analysis explores the regional nuances, including regulatory environments, competitive intensity, and local demand drivers, without relying on superficial breakdowns, enabling stakeholders to identify the most promising geographic avenues for expansion.
Competitive Landscape: Concentration, Innovation, and the Medtronic Benchmark
The absorbable antibacterial envelope market is defined by a high degree of competitive concentration, a characteristic that shapes pricing strategies, innovation cycles, and market entry barriers. Our research highlights that the top three companies collectively command an estimated 88.5 percent of the market, while the top five firms account for approximately 95.2 percent. This oligopolistic structure reflects the significant clinical validation, regulatory expertise, and distribution networks required to succeed in a specialized medical device segment. For new entrants, the barriers are formidable; for incumbents, the challenge lies in defending market share while driving continuous product improvement and expanding into adjacent therapeutic areas.
At the forefront of this competitive arena stands Medtronic, a company whose TYRX Absorbable Antibacterial Envelope has become synonymous with innovation in CIED infection prevention. Headquartered in Dublin, Ireland, Medtronic has leveraged its global scale and clinical research capabilities to establish TYRX Absorb as a leading solution. The device is a fully absorbable envelope that incorporates the antimicrobial agents rifampin and minocycline within a bioabsorbable polymer matrix, designed to reduce the risk of clinical infection when used with CIEDs in patients at higher infection risk. A key feature of the envelope is its complete resorption profile, with the material fully absorbed within approximately nine months, eliminating the long-term presence of a foreign body while providing sustained antimicrobial protection during the critical healing period.
Medtronic's strategic momentum in this space has been reinforced by recent regulatory and clinical milestones that carry significant implications for the broader market. In October 2024, the company received FDA approval for the TYRX Absorb fully absorbable antibacterial envelope for use with cardiac implantable electronic devices, a clearance that validated the device's safety and efficacy profile and expanded its addressable patient population. This regulatory achievement was complemented by clinical evidence presented in March 2025 at the American College of Cardiology Annual Scientific Session, where Medtronic shared five-year data from the ABSORB registry demonstrating low infection rates associated with the TYRX Absorb envelope. Such long-term real-world evidence not only strengthens the clinical value proposition but also serves as a powerful differentiator in a market where payer and provider confidence hinges on robust outcomes data.
The competitive dynamics are further influenced by evolving reimbursement frameworks that directly impact market accessibility and adoption velocities. Notably, the Centers for Medicare and Medicaid Services (CMS) assigned HCPCS code C1831 for the absorbable antibacterial envelope used with implantable devices, a development that streamlines billing processes and enhances the financial viability of envelope utilization in clinical practice. For stakeholders, reimbursement clarity is a critical enabler of market growth, reducing administrative friction and encouraging broader implementation. However, it also raises the stakes for competitive positioning, as manufacturers must demonstrate not only clinical efficacy but also value-based benefits that align with payer priorities.
Beyond the dominant players, the market landscape includes a constellation of smaller firms and regional players that pursue differentiated strategies, such as specialized materials, niche applications, or cost-effective alternatives. Our report provides a comprehensive competitive profiling of key companies, examining their product pipelines, strategic partnerships, manufacturing capabilities, and market share trajectories. This analysis enables readers to assess the relative strengths and vulnerabilities of competitors, identify potential consolidation targets, and anticipate shifts in market leadership. For investors, this intelligence is invaluable for evaluating the sustainability of margins and the risk-return profiles of companies operating in this concentrated environment.
Industry Dynamics: Regulatory, Clinical, and Reimbursement Forces Shaping the Future
The trajectory of the absorbable antibacterial envelope market is inextricably linked to a complex interplay of regulatory, clinical, and reimbursement dynamics. Our research delves into these forces, unraveling how they interact to create both opportunities and constraints for market participants.
On the regulatory front, the landscape is evolving as health authorities increasingly recognize the importance of infection prevention technologies in reducing healthcare costs and improving patient safety. The FDA's recent clearance of TYRX Absorb under the 510(k) pathway, with specific indications for reducing clinical infection risk in higher-risk CIED patients, exemplifies the regulatory trend toward evidence-based approvals that reflect real-world clinical utility. Such clearances not only validate the technology but also set precedents for the types of clinical data required for market authorization, influencing the development strategies of other manufacturers. Our report analyzes the regulatory pathways, submission requirements, and approval trends across key markets, providing guidance for companies navigating the complexities of global regulatory compliance.
Clinical considerations also play a pivotal role in market adoption and expansion. The contraindications associated with absorbable antibacterial envelopes, such as known hypersensitivity to rifampin, minocycline, or absorbable polymers, highlight the importance of patient selection and clinical judgment in optimizing outcomes. As the body of clinical evidence grows, including long-term registry data and comparative studies, the understanding of which patient populations derive the greatest benefit will continue to refine. This evolution has direct implications for market sizing, as the definition of the addressable patient base expands or contracts based on clinical guidelines and practitioner behavior. Our research incorporates a thorough review of clinical literature, registry data, and expert insights to map the current state of evidence and project future shifts in clinical practice patterns.
Reimbursement dynamics represent another critical axis of market influence. The assignment of specific HCPCS codes, such as C1831 for absorbable antibacterial envelopes, facilitates reimbursement for procedural use, but the broader reimbursement ecosystem is subject to ongoing negotiations, policy changes, and value-based care initiatives. Hospitals and healthcare systems are increasingly scrutinizing the cost-effectiveness of infection prevention technologies, weighing the upfront cost of envelopes against the potential savings from reduced infection-related complications, shorter hospital stays, and fewer readmissions. Our analysis explores the reimbursement landscape across major markets, identifying the key payers, coding structures, and coverage policies that affect market penetration. For manufacturers, understanding these dynamics is essential for developing effective market access strategies and for communicating value propositions that resonate with economic decision-makers.
Why This Research Is Indispensable for 2026 Decision-Making
As we enter 2026, the absorbable antibacterial envelope market stands at a inflection point where historical growth is giving way to a more complex, competitive, and regulated future. The decisions made today by market participants will determine their ability to capture value, mitigate risks, and capitalize on emerging opportunities over the next decade. Our Worldwide Absorbable Antibacterial Envelope Market report is designed to be the definitive strategic tool for navigating this environment, offering a depth of analysis that goes far beyond high-level market summaries.
The full report provides an exhaustive dissection of market sizing and forecasting, with detailed projections across multiple scenarios that account for varying assumptions about clinical adoption, regulatory changes, and economic conditions. It delivers a granular segmentation analysis that breaks down the market by type, application, and region, revealing the specific growth rates, revenue contributions, and strategic implications of each segment. This level of detail is crucial for companies seeking to allocate resources effectively, tailor their marketing and sales efforts, and identify underserved niches where competitive advantage can be gained.
Antimicrobial Suture Market
Furthermore, the report includes an in-depth competitive landscape assessment that profiles the key players, analyzes their strategic moves, and evaluates the overall market structure. It examines recent developments, such as Medtronic's FDA approval and clinical data presentations, to illustrate the types of events that can shift market dynamics and to provide lessons for competitive positioning. The analysis also considers the potential impact of industry consolidation, technological innovation, and emerging market entry strategies, helping stakeholders anticipate disruptions and adapt their plans accordingly.
In addition to quantitative analysis, the report offers qualitative insights into the industry dynamics that drive market behavior. It explores the regulatory, reimbursement, and clinical factors that influence adoption, providing a holistic view of the ecosystem in which companies operate. The inclusion of frequently asked questions (FAQs) addresses common uncertainties, such as contraindications, material properties, and procedural considerations, offering practical guidance for both commercial and clinical audiences. This combination of data-driven rigor and actionable insight makes the report a versatile resource for a wide range of stakeholders, including medical device manufacturers, strategic investors, healthcare providers, and policy analysts.
Positioning for Success in a High-Growth, High-Stakes Market
The absorbable antibacterial envelope market is not merely a segment of the medical device industry; it is a critical component of the broader effort to enhance the safety and efficacy of cardiac implantable electronic devices. As the global burden of cardiovascular disease continues to rise and the demand for CIEDs expands, the role of infection prevention technologies will become increasingly central to clinical practice and healthcare economics. Companies that can navigate the complexities of this market with agility, evidence-based confidence, and strategic foresight will be well-positioned to achieve sustainable growth and market leadership.
However, success in this environment requires more than intuition; it demands comprehensive, accurate, and forward-looking intelligence. Our research provides the foundation for such intelligence, equipping decision-makers with the knowledge they need to assess market opportunities, benchmark competitive performance, evaluate regulatory and reimbursement risks, and develop robust strategies for 2026 and beyond. Whether you are considering a market entry, expanding an existing portfolio, investing in a competitor, or formulating a market access strategy, the insights contained in this report are tailored to inform your choices and sharpen your competitive edge.
We invite you to access the full Worldwide Absorbable Antibacterial Envelope Market research to gain a complete understanding of the market's size, structure, dynamics, and future trajectory. The detailed segmentation data, competitive profiles, regional analyses, and scenario-based forecasts contained in the report are essential for making informed, high-impact decisions in a market that is poised for significant transformation. In an environment where information is the currency of advantage, this research offers the clarity and depth required to navigate the absorbable antibacterial envelope market with confidence and precision.
For detailed analysis of this topic, please visit the official page: Worldwide Absorbable Antibacterial Envelope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Expectoration Machine Market to Reach $792.27 Million by 2032 at 8.12% CAGR
By pmarketresearch, 2026-09-17
Navigating the Respiratory Critical Care Frontier: Strategic Insights into the 2026 Global Expectoration Machine Market
The global healthcare landscape is undergoing a structural transformation driven by an aging population, the rising prevalence of neuromuscular and chronic respiratory conditions, and an accelerated shift toward value-based care. At the intersection of these macro trends lies a highly specialized yet increasingly vital segment: the Worldwide Expectoration Machine Market. As medical institutions and home care providers confront the clinical imperative of effective airway clearance, expectoration machines have evolved from niche therapeutic tools into essential components of respiratory management protocols. This industry is no longer defined solely by incremental engineering improvements; it is being reshaped by reimbursement policy realignment, regulatory classification frameworks, and intensifying competitive consolidation.
Our recently released Worldwide Expectoration Machine Market research delivers a comprehensive, decision-grade examination of this sector, spanning historical performance from 2020 through 2025 and projecting forward across the 2026 to 2032 forecast window. The analysis is engineered specifically for executive teams, product strategists, clinical procurement leaders, and investment professionals who require granular operational intelligence rather than surface-level market summaries. By mapping demand elasticity across care environments, dissecting product architecture shifts, and evaluating the evolving regulatory and reimbursement terrain, this report provides a strategic blueprint for navigating a market characterized by both robust growth and complex stakeholder dynamics.
Macro Trajectory and Growth Architecture
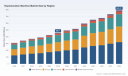
The foundation of any forward-looking strategy begins with a clear understanding of market momentum. Over the past half-decade, the expectoration machine sector has demonstrated consistent expansion, moving from a 2020 baseline of $310.45 million to a 2025 valuation of $458.70 million. This trajectory reflects sustained adoption of mechanical insufflation-exsufflation (MIE) technologies, broader clinical recognition of airway clearance as a critical intervention for patients with impaired cough reflexes, and ongoing procurement modernization across acute and post-acute care facilities. The momentum is projected to continue through the end of the decade, with the market advancing to $494.23 million in 2026 and approaching $792.27 million by 2032.
Worldwide Expectoration Machine Market
This expansion is underpinned by a compound annual growth rate of 8.12 percent across the forecast horizon, signaling a market that is not merely recovering from historical disruptions but entering a structurally elevated growth phase. Several forces are converging to sustain this trajectory. First, clinical protocols are increasingly standardizing airway clearance interventions for neuromuscular diseases, bronchiectasis, and post-surgical pulmonary complications, expanding the addressable patient population. Second, healthcare delivery models are shifting toward decentralized and home-based care, creating demand for compact, user-friendly, and remotely manageable expectoration systems. Third, manufacturers are investing in integrated device ecosystems that combine cough assistance with broader respiratory support functionalities, thereby increasing clinical utility and procurement stickiness. The strategic implication for market participants is unambiguous: growth will increasingly favor organizations that align product development with care-pathway integration, reimbursement navigability, and real-world usability.
Strategic Segmentation: Where Value Is Being Created
A high-level revenue curve tells only part of the story. The true strategic value of this research lies in its dissection of how demand is distributed across product architectures, end-user environments, and geographic markets. Understanding these allocation patterns enables executives to optimize R&D pipelines, refine pricing architectures, and design targeted commercial strategies.
Product Architecture and Engineering Differentiation
The market divides into two primary mechanical paradigms: automatic mechanical in-exsufflation devices and manual mechanical in-exsufflation devices. Automatic systems dominate the revenue conversation by a considerable margin, reflecting their integration into hospital-grade respiratory workflows, their ability to deliver repeatable and programmable cough simulations, and their alignment with clinical staffing constraints. Manual devices, while generating lower aggregate revenue, maintain a distinct presence in settings where portability, cost sensitivity, and clinician-directed control are prioritized. The engineering frontier is shifting toward hybrid capabilities, improved pressure regulation algorithms, and interfaces that reduce clinician training burden. Companies that can demonstrate superior outcomes in secretion clearance efficiency, patient tolerance, and interface ergonomics are positioning themselves for durable share gains.
End-User ecosystems and Procurement Realities
Demand is not evenly distributed across care settings. Hospitals and clinics represent a substantial share of current procurement, driven by acute-care utilization, in-patient respiratory management, and the availability of specialized clinical staff. Home care settings constitute an equally critical and rapidly expanding demand pool, reflecting the broader migration of chronic respiratory management outside institutional walls. In home environments, device selection is heavily influenced by usability, patient and caregiver training requirements, service coverage, and reimbursement eligibility. Rehabilitation centers, while smaller in relative scale, represent a high-value niche where repeated therapeutic sessions and specialized respiratory programs create steady utilization cycles. Each end-user segment demands a different commercial playbook: hospital sales require clinical evidence packages, group purchasing organization engagement, and service-level agreements; home care distribution depends on durable medical equipment channels, patient support infrastructure, and reimbursement clarity; rehabilitation procurement emphasizes therapy integration and operational durability.
Geographic allocation and regional maturity curves
Regional demand patterns reveal a mature, high-capacity market in North America, where established clinical adoption, reimbursement infrastructure, and a dense concentration of respiratory therapy provider networks support sustained utilization. Europe follows as a substantial market, characterized by diversified national procurement systems, varying reimbursement environments, and strong clinical advocacy for airway clearance standardization. Asia Pacific represents a growth-intensive region where expanding healthcare access, rising chronic disease awareness, and local manufacturing capabilities are accelerating adoption curves. Latin America and the Middle East and Africa, while smaller in current scale, are emerging as incremental growth zones where targeted clinical education, distributor partnerships, and adjusted pricing architectures can unlock meaningful demand over time. The strategic takeaway is that geographic expansion cannot rely on uniform playbooks; each region requires tailored engagement models that account for procurement governance, reimbursement pathways, and clinical ecosystem maturity.
Competitive Landscape and Enterprise Positioning
The expectoration machine market is marked by a concentrated yet dynamically contested competitive field. Our analysis indicates that the top three players command approximately 64.85 percent of market revenue, while the top five extend their collective footprint to roughly 81.4 percent. This concentration signals mature competitive dynamics in the core revenue tiers, but it does not imply stagnation. Instead, it highlights a landscape where incumbents defend share through clinical reputation, regulatory clearances, and broad respiratory portfolios, while challengers and regional specialists compete through product differentiation, targeted usability improvements, and strategic distribution partnerships.
Several enterprise profiles illustrate the competitive archetypes shaping the market. Baxter, operating through its Hillrom platform, brings established clinical brand equity and integrates airway clearance technologies such as the Vest Airway Clearance System and Synclara Cough System into broader hospital respiratory ecosystems. ABM Respiratory Care competes with the BiWaze Cough System, emphasizing dual-airway pathway engineering designed to simulate natural cough mechanics for patients with neuromuscular and respiratory compromise. Koninklijke Philips N.V., through its Respironics lineage, offers the CoughAssist T70 and related MIE devices, leveraging a global respiratory brand and extensive clinical service networks. United Hayek Industries and Hayek Medical maintain a specialized footprint around high-frequency chest wall oscillation and insufflation-exsufflation solutions, including the Hayek RTX oscillator. Dima Italia Srl contributes the PEGASO series, targeting mechanical insufflation-exsufflation bronchial drainage and expectoration support with regional clinical credibility.
The competitive field also includes manufacturers expanding airway clearance through complementary modalities. Electromed promotes the SmartVest Airway Clearance System as a high-frequency chest wall oscillation platform for secretion mobilization. Jinan Qijia Medical Equipment produces airway clearance systems and vest-type sputum expectoration machines for non-invasive respiratory therapy, reflecting the growing capabilities of regional manufacturing hubs. Trudell Medical International offers the AEROBIKA OPEP device, addressing mucus clearance through oscillating positive expiratory pressure. ICU Medical, formerly Smiths Medical, supplies Acapella vibratory PEP therapy systems for patients with secretory management needs. Breas Medical incorporates cough assist and airway clearance devices into a broader respiratory support portfolio, while Air Liquide Medical Systems, through its EOVE offering, delivers mechanical insufflation-exsufflation and related airway clearance solutions. Ventec Life Systems adds another strategic dimension with the VOCSN multi-function ventilator, integrating cough assistance via embedded MIE functionality and illustrating the industry trend toward consolidated respiratory platforms.
Worldwide Phlegm Suction Tube Market
This competitive diversity creates both opportunity and risk. Incumbents with multi-product respiratory portfolios can cross-sell and bundle airway clearance into broader care contracts, but they also face higher expectations for clinical integration and service reliability. Smaller or regionally focused manufacturers can move faster on specialized design and localized service, but they must navigate reimbursement complexity and scale constraints. The 2026 decision-maker must therefore evaluate competitors not only by current revenue share but by their ability to combine regulatory agility, reimbursement navigation, clinical evidence generation, and service coverage into a durable competitive moat.
Regulatory and Reimbursement Dynamics as Strategic Multipliers
Market growth in the expectoration machine sector is deeply intertwined with regulatory classification and reimbursement architecture. In the United States, mechanical insufflation-exsufflation devices are generally classified as Class II medical devices with a 510(k) clearance pathway for airway secretion clearance. This classification framework shapes time-to-market timelines, product documentation expectations, and the competitive barrier to entry for new designs. Organizations that build robust regulatory strategy early can convert clearance velocity into commercial first-mover advantages, particularly when paired with clinical evidence that supports differentiated claims.
Reimbursement policy is equally decisive. Medicare coverage exists for mechanical in-exsufflation devices under HCPCS E0482 for beneficiaries with neuromuscular diseases that cause significant impairment of chest wall and/or diaphragmatic movement resulting in inability to clear retained secretions. This coverage pathway is a critical demand enabler for home and outpatient use, but it also imposes documentation and eligibility requirements that shape procurement behavior. In parallel, HCPCS code A7020 addresses interfaces for cough stimulating devices, with reimbursement possible when the beneficiary owns or is purchasing the mechanical in-exsufflation device. These reimbursement nuances matter because they directly affect patient access, durable medical equipment channel economics, and the commercial viability of home-care device programs. Recent regulatory and market developments continue to reinforce the importance of compliance-forward product strategies. For example, in March 2024, BOC Limited secured ARTG inclusion for a cough assist device designed for in-exsufflation and lung-oscillation airway secretion clearance, classified as Class IIa. Such events highlight how regulatory approvals can unlock regional access and validate clinical positioning, especially in markets where reimbursement eligibility depends on formal device recognition.
For corporate strategy teams, the lesson is clear: reimbursement and regulatory landscapes are not peripheral concerns. They are core pricing and adoption drivers. Product roadmaps should be evaluated through the lens of coverage eligibility, documentation readiness, and the ability to support clinicians and patients in meeting coverage criteria. Commercial teams should align channel incentives with reimbursement navigability, while market access strategies should anticipate policy updates that can expand or contract eligible patient populations.
What the Research Delivers for Executive Decision-Making
This report is structured to convert complex market intelligence into actionable strategic direction. It provides a detailed historical baseline and forward forecast architecture that allows leadership teams to model demand scenarios, calibrate capacity plans, and set realistic revenue expectations across the 2026 to 2032 window. The analysis goes beyond macro totals to examine how product types, end-user settings, and regional markets allocate value, enabling sharper segmentation strategy and resource allocation.
The competitive assessment component delivers more than a company directory. It contextualizes each major participant within broader portfolio strategies, clinical positioning, geographic strengths, and likely strategic moves. This enables benchmarking exercises, partnership evaluations, and competitive response planning. The report also integrates market dynamics analysis that maps regulatory pathways, reimbursement mechanisms, and procurement behaviors into a coherent framework, allowing executives to anticipate structural shifts rather than react to them.
In addition, the research is designed to support practical operational decisions. Product managers can use segmentation insights to prioritize feature development and interface engineering. Commercial leaders can align sales motions with end-user procurement realities and reimbursement conditions. Strategy and corporate development teams can identify consolidation opportunities, partnership targets, and regional entry pathways. Investors and financial analysts can use the growth trajectory, concentration metrics, and market-access dynamics to stress-test assumptions and refine valuation models. By maintaining a disciplined focus on decision-useful intelligence, the report avoids generic commentary and instead delivers the kind of structure that executive teams can immediately apply.
Strategic Imperatives for 2026 and Beyond
Entering 2026, market participants face a set of interconnected imperatives. First, product strategy must increasingly account for care-environment fluidity. Devices that perform well in hospitals but fail in home-care usability or service coverage will face growing resistance as procurement decisions broaden beyond institutional buyers. Second, reimbursement alignment must be treated as a product requirement, not a post-launch afterthought. Coverage eligibility, interface reimbursement pathways, and documentation feasibility will influence adoption speed and channel economics. Third, competitive positioning should be evaluated in terms of ecosystem strength. Manufacturers that can integrate cough assistance into broader respiratory platforms, provide dependable clinical support, and build evidence-based credibility will be better positioned to defend share in a concentrated market. Fourth, regional expansion requires localized realism. High-growth regions will not automatically convert into high-margin opportunities without distributor capability, clinical education, pricing discipline, and regulatory readiness.
The broader implication is that the expectoration machine market is maturing into a strategic domain where engineering excellence, regulatory discipline, reimbursement literacy, and go-to-market precision must operate in concert. Organizations that treat airway clearance as a standalone hardware category will miss the structural forces shaping demand. Those that view it as a care-pathway-enabled solution category will be better equipped to capture durable value.
Conclusion
The Worldwide Expectoration Machine Market is entering a phase where growth is real, competition is structured, and strategic differentiation depends on operational precision. With a forecast compound annual growth rate of 8.12 percent and a market trajectory advancing from $494.23 million in 2026 toward $792.27 million by 2032, the sector offers meaningful expansion potential. Yet the distribution of that opportunity across product types, end-user environments, regions, and competitive tiers is highly nuanced. Success in 2026 and beyond will belong to organizations that can translate macro momentum into targeted segmentation strategy, reimbursement-aware product design, region-specific commercial execution, and defensible competitive positioning.
This research was built to support that decision-making process with depth, clarity, and operational relevance. The full report contains the detailed segmentation breakdowns, competitor benchmarking frameworks, regional demand allocations, reimbursement and regulatory analyses, and forward scenario structures required to guide enterprise strategy with confidence. To access the complete intelligence set and apply it directly to your planning cycle, we invite you to review the full market study and accompanying executive materials.
For detailed analysis of this topic, please visit the official page: Worldwide Expectoration Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ocular Inflammation Market to Hit $17.87 Billion by 2032 at 6.5% CAGR
By pmarketresearch, 2026-09-17
Strategic Foresight in Ocular Inflammation Treatment: Navigating the 2026 Market Landscape
As we enter 2026, the global landscape for treating ocular inflammation stands at a critical inflection point. Driven by an aging population, increased prevalence of chronic eye conditions, and a evolving therapeutic pipeline, stakeholders across the pharmaceutical and medical device value chain must recalibrate their strategies. The recently published Ocular Inflammation Treatment Market research report serves as an indispensable compass for navigating this complex terrain. This analysis is not merely a collection of statistics; it is a strategic asset designed to inform capital allocation, product development, and competitive positioning for the remainder of the decade.
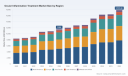
Understanding the magnitude of this opportunity requires a clear view of the historical trajectory and future projections. Over the past five years, the market has demonstrated resilience and steady growth, overcoming supply chain disruptions and evolving regulatory frameworks. From a base valuation in the early 2020s, the sector has expanded robustly, reaching an estimated 11,500 million USD in 2025. Looking ahead, the momentum is expected to sustain itself, with projections indicating a climb toward 17,870.86 million USD by 2032. This growth trajectory is underpinned by a compound annual growth rate that signals healthy expansion, suggesting that demand for ocular anti-inflammatory therapies will continue to outpace many traditional pharmaceutical segments. For executives and investors, these figures represent more than top-line revenue; they indicate the overall health of the sector and the viability of long-term investments in ophthalmic innovation.
Defining the Scope of Opportunity
To fully leverage this market intelligence, one must understand the depth of the data covered in the comprehensive study. The report dissects the industry through multiple lenses, ensuring that no strategic blind spots remain. It provides a granular look at the forces shaping the industry, moving beyond high-level estimates to offer actionable intelligence.
The core of the analysis rests on several pivotal pillars:
- Historical and Forecast Data: The study offers a detailed retrospective from 2020 to 2025, establishing a robust baseline, alongside a forward-looking forecast period extending through 2032. This dual perspective allows companies to benchmark past performance against future expectations.
- Segmentation Analysis: The market is broken down by drug class, indication, and region. This allows stakeholders to identify high-growth pockets within the broader ecosystem. Whether the interest lies in corticosteroids, NSAIDs, immunomodulators, or anti-infectives, the data isolates performance drivers for each category.
- Competitive Benchmarking: Profiles of key industry players are included, offering insights into their product portfolios, geographic footprints, and strategic moves. This section is crucial for understanding relative market strength and potential partnership opportunities.
- Regulatory and Reimbursement Dynamics: Given the highly regulated nature of ophthalmic products, the report integrates critical information regarding FDA approvals, patent protections, and reimbursement pathways such as J-codes for intravitreal implants.
Regulatory Catalysts and Innovation Trends
The environment for ocular inflammation treatment is being reshaped by recent regulatory milestones and technological advancements. For strategic planners, staying ahead of these curves is essential to maintaining competitiveness. The report captures these dynamics in real-time, ensuring that decision-makers are not operating on outdated assumptions.
Recent FDA Approvals and Clinical Clearances
In mid-2025, the regulatory landscape saw significant activity. Amneal Pharmaceuticals secured FDA approval for generic prednisolone acetate ophthalmic suspension 1%, with a launch planned for the third quarter of 2025. This move increases accessibility for steroid-responsive ocular inflammation treatments, potentially shifting pricing dynamics and market share among generic manufacturers. Simultaneously, Alcon achieved FDA approval for TRYPTYR (acoltremon ophthalmic solution) for signs and symptoms of dry eye disease, a condition intimately linked with ocular surface inflammation. These approvals highlight a trend toward both cost-effective generics and novel mechanisms of action.
Looking toward early 2026, the pipeline shows promise for steroid-sparing options. Novaliq received FDA IND clearance for NOV05 (tacrolimus ophthalmic solution) for a Phase 2 trial in non-infectious anterior uveitis. This development is particularly noteworthy for strategists monitoring the shift away from long-term steroid use due to side effect profiles. Such innovations suggest a diversifying treatment arsenal that could disrupt incumbent franchises relying heavily on traditional corticosteroids.
Supply Chain and Intellectual Property Considerations
Beyond approvals, operational realities play a significant role in market dynamics. Tariffs on imported pharmaceutical ingredients remain a concern, potentially increasing production costs for treatments reliant on global supply chains. Consequently, pricing strategies and margin management require careful scrutiny. Furthermore, intellectual property continues to be a moat for sustained-release technologies. Multiple patents protect formulations such as DEXTENZA and YUTIQ, securing revenue streams for innovators while setting barriers for entrants. Understanding the patent cliff scenarios and the protection lifecycle of these devices is vital for risk assessment.
Competitive Landscape and Strategic Positioning
The market concentration indicates a moderately consolidated environment where strategic partnerships and portfolio diversification are key. The top three companies hold a significant portion of the market share, while the top five control more than half of the total revenue. This structure suggests that while there is room for niche players, scale and broad product portfolios offer distinct advantages.
Several key corporations define the current competitive arena. AbbVie Inc., based in North Chicago, remains a powerhouse with offerings like prednisolone acetate (Pred Forte) for steroid-responsive conditions. Their established presence underscores the enduring importance of classic corticosteroids. In the realm of sustained-release implants, Alimera Sciences and EyePoint Pharmaceuticals, Inc. are critical players. Alimera markets ILUVIEN (fluocinolone acetonide intravitreal implant) for diabetic macular edema and related conditions, while EyePoint commercializes YUTIQ for chronic non-infectious uveitis and DEXYCU for postoperative inflammation. These intravitreal implants represent a high-value segment where reimbursement pathways including J-codes have been established, stabilizing revenue models for these therapies.
Worldwide Conjunctivitis Ophthalmic Drugs Market
Bausch Health Companies Inc. continues to market a range of ophthalmic steroids, including Lotemax, catering to inflammation and pain management. Novartis AG supplies anti-inflammatory products through its broader ophthalmology portfolio, leveraging global scale. In the generic space, Amneal Pharmaceuticals is expanding its footprint, challenging branded formulations on price. Pfizer Inc. provides various corticosteroid and NSAID formulations, while Santen Pharmaceutical Co., Ltd. maintains a strong global focus on ophthalmic therapeutics from its base in Osaka. Ocular Therapeutix, Inc. offers DEXTENZA, a dexamethasone ophthalmic insert for postoperative inflammation and allergic conjunctivitis itching, showcasing innovation in delivery mechanisms.
Ocular Inflammation Treatment Market
Segmentation Insights for Targeted Strategy
Strategic success in this market requires understanding where the value is created. The report provides segmentation data that allows companies to tailor their approaches. By drug class, the market is diversified. Corticosteroids continue to hold substantial ground, reflecting their status as a standard of care. However, immunomodulators and NSAIDs also command significant market presence, indicating a balanced therapeutic mix. Anti-infectives represent another crucial segment, particularly for inflammation with an infectious etiology. Companies must decide whether to compete on volume in mature classes or innovate in expanding categories.
By indication, the demand drivers are varied. Dry Eye Syndrome represents a large portion of the market, driven by high prevalence and ongoing innovation in managing ocular surface disease. Allergic Conjunctivitis remains a consistent driver, often seasonal but broadly impactful. Uveitis, while less prevalent, represents a high-value specialty segment where advanced therapies and implants are often required. Post-operative inflammation is another critical area, directly linked to the volume of ophthalmic surgeries performed globally. Understanding the specific growth rates and revenue contributions of each indication helps companies prioritize R&D and marketing resources effectively.
Regionally, the market exhibits distinct characteristics. North America continues to be a dominant force, reflecting high healthcare spending and adoption rates. Europe remains a substantial market with its own regulatory nuances. The Asia Pacific region represents a high-growth opportunity, driven by improving access and increasing awareness. Latin America and the Middle East and Africa offer emerging potential, though they come with unique reimbursement and access challenges. A one-size-fits-all strategy is rarely effective; regional customization is key to capturing value across these geographies.
Why This Research Matters for 2026 Decisions
As the market moves through the forecast period, the cost of uncertainty is high. Misjudging the impact of a new generic entrant, misinterpreting regulatory signals, or overlooking a shift in reimbursement policy can lead to significant strategic errors. This report mitigates those risks by providing a consolidated view of the forces at play.
For business development teams, the competitive profiles and recent developments sections offer leads for potential collaborations or acquisition targets. For marketing leaders, the segmentation data informs messaging and territory planning. For C-suite executives, the macro trends and financial projections support budgeting and long-term visioning. The inclusion of supply chain risks and patent landscapes adds a layer of operational realism that is often missing from broader industry overviews.
The data suggests that the path to 2032 is not linear. While the overall trajectory is positive, there will be fluctuations based on drug launches, patent expirations, and regulatory changes. Companies that possess granular intelligence will be better positioned to pivot when necessary. For instance, the rise of steroid-sparing therapies could alter the demand curve for traditional corticosteroids over the next few years. Similarly, changes in reimbursement codes for intravitreal implants could impact the economics of sustained-release products.
Accessing the Full Intelligence
This overview provides a glimpse into the depth and breadth of the analysis available. However, the true value lies in the detailed data tables, comprehensive company profiles, and scenario-based forecasts that form the core of the full report. The macro figures and trends mentioned here are derived from a sophisticated modeling process that accounts for multiple variables influencing the market.
To make fully informed decisions, stakeholders need access to the complete dataset. This includes specific revenue breakdowns by segment, detailed historical comparisons, and the nuanced analysis of competitive moves that cannot be fully captured in a summary. The interplay between drug classes, indications, and regions creates a complex matrix where specific insights can reveal hidden opportunities or threats.
Investing in this knowledge asset is an investment in strategic clarity. As the ocular inflammation treatment market continues to evolve through 2026 and beyond, those equipped with the most accurate and comprehensive data will lead the sector. We invite you to explore the full report to gain the detailed intelligence necessary to navigate this dynamic market with confidence. The complete analysis offers the granularity required to transform high-level trends into actionable business strategies.
For detailed analysis of this topic, please visit the official page: Ocular Inflammation Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dual Mode Automated Forklifts Market Hits $685.4M in 2025, Set for 14.25% CAGR to 2032
By pmarketresearch, 2026-09-17
Navigating the Dual Mode Automated Forklifts Market: A Strategic Forecast for 2026 and Beyond
The material handling landscape is undergoing a seismic shift. As we move past the historical trajectory of the early 2020s, the industry is no longer asking whether automation is inevitable. The question has evolved to how organizations can seamlessly integrate autonomous capabilities with existing manual workflows without disrupting operations or inflating capital expenditure.
PW Consulting's latest Dual Mode Automated Forklifts Market Report provides a comprehensive strategic roadmap for this transition. Grounded in extensive primary research and validated market modeling, this study is designed for executives who require actionable intelligence to navigate the 2026-2032 forecast period. This article serves as a strategic preview of the market forces, competitive dynamics, and operational imperatives that define the current era of material handling innovation.
The Macro Trajectory: Sustained Valuation Expansion
The scale of the opportunity is underscored by the consistent expansion observed over the historical cycle. The overall market revenue has demonstrated robust growth, climbing from USD 245.67 Million in 2020 to USD 535.11 Million by 2024. This acceleration reflects a fundamental reordering of priorities within warehousing, distribution, and manufacturing sectors, driven by the need for resilience in supply chains and the imperative to optimize labor-intensive processes.
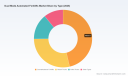
Forecasting models project a continued upward trajectory, with the market expected to reach USD 786.64 Million in 2026 and expand further to USD 1,742.18 Million by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 14.25% throughout the forecast period. For strategic planners, this rate signals more than just volume expansion; it indicates a maturing ecosystem where dual-mode technology is transitioning from a niche novelty to a standard operational requirement across diverse industrial verticals.
Such a trajectory suggests that early movers who align their capital procurement cycles with these adoption curves will secure significant operational leverage. The report dissects the drivers behind this valuation surge, offering granular insights into the economic variables that will dictate procurement cycles through 2032.
Defining the Dual Mode Advantage
Dual mode automated forklifts represent a critical intersection of flexibility and efficiency. Unlike fully autonomous or fully manual assets, these machines are engineered to switch between autonomous operation and manual control, often via a simple interface mechanism. This hybrid capability addresses one of the most persistent pain points in warehouse automation: the rigidity of single-mode solutions.
In environments characterized by fluctuating throughput, mixed traffic, or seasonal peaks, the ability to deploy a single asset class for both high-volume automated runs and flexible manual interventions reduces fleet complexity. It mitigates the risk of stranded assets during low-volume periods while preserving the throughput benefits of automation during high-demand cycles. Our analysis highlights how this operational elasticity is reshaping total cost of ownership (TCO) calculations, moving the conversation beyond upfront sticker prices to lifecycle value.
Regulatory and Operational Dynamics
The deployment of dual-mode and automated forklifts does not occur in a vacuum. A complex web of regulatory standards and operational constraints is shaping the adoption landscape. As of late 2025 and into 2026, compliance has become a central pillar of procurement strategy.
Key industry standards such as ANSI/ITSDF B56.5-2024 are defining rigorous safety requirements for driverless automatic guided industrial vehicles and the automated functions of manned industrial vehicles. With effective requirements rolling out, organizations must ensure that their fleet selections align with these updated protocols to mitigate liability and ensure worker safety. Similarly, ISO 3691-4 continues to set the benchmark for the safety of driverless industrial trucks, mandating robust obstacle detection and emergency stop functionalities.
Dual Mode Automated Forklifts Market
Beyond compliance, the macroeconomic backdrop of labor dynamics is a potent catalyst. Rising operator wages and persistent labor shortages have intensified the need for solutions that can reduce dependency on skilled manual operators while enabling 24/7 operation capabilities. Dual-mode forklifts address this by automating repetitive, high-fatigue tasks while retaining the flexibility to utilize human operators for complex decision-making or case picking scenarios. The report details how these factors are influencing segment preferences and capital allocation strategies across different operational contexts.
Competitive Landscape and Innovation Velocity
The market is characterized by a concentrated yet dynamic competitive environment. The top three companies command a significant share of the market, while the top five firms collectively hold a substantial portion of market revenue. This concentration indicates a market where established players leverage extensive distribution networks and deep engineering expertise to maintain leadership, yet it also suggests room for disruptive innovation as technology barriers evolve.
Several key players are actively defining the competitive frontier through product innovation and strategic expansion. Crown Equipment Corporation has been pivotal in offering DualMode automated solutions, including the R 1000 Series reach trucks and T 1000 Series tow tractors. These assets are designed to switch between autonomous and manual operation seamlessly, catering to facilities that require versatile fleet management.
Hyster-Yale Materials Handling and Yale Materials Handling are pushing the boundaries of reach and functionality. Hyster provides dual-mode pantograph robotic reach trucks capable of autonomous operation at heights exceeding 400 inches, with the option to switch to manual mode. Yale offers dual-mode pantograph automated reach trucks, noted as first-of-their-kind solutions for high-rack storage, providing an easy switch between autonomous and manual modes. Recent developments underscore this velocity: in September 2025, Hyster launched the new Hyster Atlas automated lift truck platform, featuring drag-and-drop setup for tow tractors and enhanced usability.
Linde Material Handling, part of the KION Group, continues to expand its automated portfolio. In June 2025, Linde added new models to its automated forklift range, including the K MATIC k VNA turret truck, R-MATIC k reach truck, and L MATIC AC k pallet stacker. Furthermore, in November 2025, Linde unveiled a new automated counterbalance forklift, the E-Matic, with pre-series projects planned for 2026 and a series release anticipated in 2027. These timelines signal a tightening product cadence that procurement teams must monitor to avoid obsolescence risks.
The Raymond Corporation also contributes to the diversity of the market with its Automated Transtacker (TRT), which features dual-mode functionality for automated full pallet handling or manual case picking. This variety of solutions highlights that dual-mode is not a monolithic technology but a spectrum of applications tailored to specific warehouse geometries and workflow requirements.
Segmentation Trends and Deployment Realities
While the overall market growth is compelling, the value of this report lies in its dissection of how demand is distributed across types, applications, and regions. The data reveals distinct preferences that should inform fleet planning. Forklift types such as Counterbalance Forklifts and Reach Trucks represent significant portions of market activity, reflecting their ubiquity in standard warehouse operations. Pallet Trucks and other specialized types further diversify the mix, addressing niche handling requirements.
In terms of application, Warehousing and Distribution stands out as a primary driver of demand, followed by Manufacturing, Logistics and Freight, and Cold Storage. Each application presents unique challenges: cold storage environments demand ruggedized solutions capable of operating in sub-zero temperatures, while manufacturing floors often require equipment that can navigate mixed traffic with high precision. The report explores how dual-mode capabilities are being tailored to these specific verticals, helping decision-makers match asset capabilities to environmental constraints.
Regional dynamics also play a crucial role. North America, Europe, and Asia Pacific represent substantial market bases, while Latin America and the Middle East and Africa are emerging zones of activity. The report provides high-level directional insights into these regional footprints, enabling global operators to prioritize deployment strategies based on localized adoption rates and infrastructure readiness. However, to truly capitalize on these trends, executives need the detailed segmentation data that maps revenue splits and growth nuances across every category and geography.
Strategic Value of the Full Analysis
The preview provided here outlines the structural forces shaping the Dual Mode Automated Forklifts Market. Yet, the strategic depth required to make high-stakes procurement and investment decisions demands a more granular examination. PW Consulting's full report delivers this by providing a comprehensive toolkit for market intelligence.
The report includes detailed profiles of key companies, dissecting their product pipelines, strategic positioning, and recent developments that may impact competitive dynamics. It offers a thorough analysis of market drivers, restraints, and opportunities, allowing stakeholders to stress-test their assumptions against evolving industry conditions. Furthermore, the study incorporates a robust competitive benchmarking framework, enabling organizations to evaluate their positioning relative to market leaders and identify potential partnership or acquisition targets.
For supply chain directors, operations managers, and strategic planners, the report serves as a decision-support artifact. It moves beyond descriptive analysis to offer prescriptive insights. By understanding the interplay between regulatory shifts, labor economics, and technological advancements, organizations can build agile fleets that are resilient to disruption and optimized for efficiency.
Conclusion
The era of rigid, single-mode material handling is giving way to a more flexible, responsive, and automated future. The projected market expansion to USD 1,742.18 Million by 2032 underscores the magnitude of this transformation. Success in this landscape will depend on the ability to interpret complex market signals, anticipate regulatory requirements, and select technologies that offer genuine operational flexibility.
Forklift Trucks Market
This article has highlighted the broad strokes of the market trajectory, the competitive intensity among major players, and the critical role of regulatory and labor dynamics. However, the full strategic picture requires access to the complete dataset, segment-level analysis, and forward-looking scenario modeling contained within PW Consulting's Dual Mode Automated Forklifts Market Report. We invite industry leaders to explore the full publication to secure the comprehensive intelligence necessary to drive informed decisions for the 2026-2032 horizon and beyond.
For detailed analysis of this topic, please visit the official page: Dual Mode Automated Forklifts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trigger Point Injection Market to Reach $320.2M by 2032, CAGR 5.85%
By pmarketresearch, 2026-09-17
Beyond the Pain Point: Strategic Intelligence for the Trigger Point Injection Treatment Market in 2026 and Beyond
The global landscape for pain management is undergoing a structural shift, driven by an aging population, the rising prevalence of musculoskeletal disorders, and a persistent move toward minimally invasive therapeutic interventions. Within this broader ecosystem, the trigger point injection treatment market stands out as a critical segment for investors, service providers, and pharmaceutical manufacturers seeking sustainable growth in the chronic pain sector. At PW Consulting, we have just published a comprehensive market research study designed to cut through the noise of general industry forecasts and deliver actionable intelligence for the 2026 decision-making cycle.
This study is not merely a collection of historical data points. It is a strategic roadmap built to help organizations anticipate the regulatory, clinical, and competitive shifts that will define the market through the end of the decade. As healthcare systems increasingly prioritize cost-effective outpatient solutions, understanding the precise trajectory of trigger point injections is essential for allocating capital, refining service portfolios, and securing competitive advantage.
Market Trajectory and Growth Dynamics
Our analysis captures a market that has demonstrated consistent resilience and expansion over the past half-decade. Tracking revenue figures from 2020 through the base year of 2025, the data reveals a steady upward climb from approximately 165.2 million USD to a projected 215.0 million USD in the current year. This historical performance sets a robust foundation for the forecast period extending from 2026 to 2032.
Looking ahead, we project the market to reach a valuation of 320.2 million USD by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.85 percent. For strategic planners, this figure represents more than aggregate expansion; it signals a maturing market where volume increases are complemented by evolving clinical standards and reimbursement scrutiny. The transition from 2025 to 2026 alone marks a notable inflection point, with revenue expected to jump to 233.37 million USD, reflecting pent-up demand and the gradual normalization of procedural volumes post-pandemic.
It is crucial for stakeholders to recognize that this growth is not uniform across all vectors. The total market size is the sum of distinct drivers involving specific agent types, clinical indications, and geographic regions. While our full report deconstructs these segments in granular detail, the aggregate trend confirms that demand is being fueled by a combination of established clinical protocols and emerging procedural training initiatives. Organizations that understand how these specific vectors interact will be best positioned to capture value.
Competitive Landscape and Key Participants
The competitive environment in the trigger point injection space is characterized by a mix of specialized pain management clinics, multidisciplinary health groups, and medical device manufacturers. Our report profiles key players who are actively shaping the market through service delivery, equipment supply, and clinical standardization.
On the service delivery side, organizations such as Paragon Health Group, Encore Health Group, Premier Pain & Spine, Synergy Health Partners, and the Cleveland Clinic are central to the ecosystem. These entities provide trigger point injections as part of broader pain management services, often focusing on myofascial pain relief, symptomatic pain relief in musculoskeletal conditions, or comprehensive non-surgical pain management. Their operational models and patient volumes contribute significantly to the market's service-based revenue streams.
Complementing these service providers is a critical component of the supply chain represented by manufacturers like B. Braun Melsungen AG. Companies in this tier supply the essential needles and injection equipment, such as ultrasound-guided systems, that enable precise and effective procedures. The interplay between procedural providers and equipment suppliers creates a dynamic where innovation in delivery tools often precedes or enables wider adoption of specific injection techniques.
Trigger Point Injection Treatment Market
Market concentration analysis indicates a fragmented yet structured competitive field. The top three companies hold a combined market share of 22.5 percent, while the top five account for 31.8 percent. This concentration level suggests that while no single entity dominates the entire spectrum, there is room for strategic consolidation or targeted market penetration by agile competitors. For new entrants or existing players looking to expand, identifying the gaps between these key players and leveraging specialized niches in agent delivery or regional service coverage is a viable path to growth.
Operational Opportunities and Service Expansion
For healthcare administrators and investors, the operational value of this market lies in its integration potential and the alignment with non-surgical care pathways. Trigger point injection procedures are frequently bundled with physical therapy, medication management, and patient education programs. Our research explores how service providers are maximizing revenue cycles by positioning these injections within comprehensive care plans.
Several strategic opportunities emerge from our analysis:
- Service Line Optimization: Clinics are refining their protocols to align with the most frequently treated indications, ensuring that patient flow and inventory management for injection agents are tightly synchronized with demand patterns.
- Provider Training and Credentialing: As procedural techniques evolve, there is a growing emphasis on formal training and certification for providers. Organizations that support or participate in accredited training programs can enhance their reputation, ensure compliance, and capture referrals from a broader network of referring physicians.
- Equipment and Supply Chain Alignment: Facilities performing high volumes of trigger point injections require reliable access to specialized needles and imaging guidance tools. Strategic partnerships with equipment suppliers or bulk procurement agreements can significantly impact cost structures and operational throughput.
- Post-Procedure Care Integration: Extending the value proposition beyond the injection itself by offering structured follow-up and rehabilitation services helps improve patient outcomes and enhances the overall attractiveness of the service to payers and referral sources.
Our full report provides detailed breakdowns of how these operational levers are being applied across different segments of the market, including specific insights into agent utilization patterns and indication-based service frequency.
Industry Dynamics: Regulatory, Reimbursement, and Clinical Guidelines
No strategic assessment of the trigger point injection market would be complete without a deep dive into the regulatory and reimbursement environment. Market participants must navigate a landscape defined by evolving coverage policies, clinical consensus statements, and procedural billing requirements. Our study maps out the critical developments that are directly influencing patient access and provider behavior.
A significant recent development is the publication of multi-society guidelines by the American Society of Regional Anesthesia and Pain Medicine (ASRA) in March 2025. These guidelines address the use of corticosteroids in trigger point injections for adult chronic pain interventions, with specific attention to dosing strategies. Notably, the guidance highlights that lower doses of corticosteroids may provide similar benefits to higher doses, a finding that has profound implications for inventory planning, cost management, and clinical protocol design. Following this, in May 2025, major payer Anthem updated its medical policy (CG-SURG-17) to reference these 2025 multi-society guidelines, signaling a swift alignment between clinical standards and coverage criteria.
Reimbursement dynamics also play a pivotal role in shaping market behavior. Trigger point injection procedures billed under CPT codes 20552 and 20553 are covered when criteria for myofascial pain are met, but there are strict limits on frequency and number of sessions. More specifically, Medicare Local Coverage Determinations (LCDs) limit trigger point injections to no more than three sessions per rolling 12 months for medically necessary myofascial pain treatment. These constraints force providers to optimize the timing and composition of their interventions, balancing clinical need with compliance requirements. The coding and billing landscape requires meticulous documentation and adherence to medical necessity standards, making operational excellence in revenue cycle management a key differentiator.
On the education and workforce front, the American Academy of Procedural Medicine (AAOPM) announced ongoing trigger point injection training courses and certification for providers as of March 2026. This institutional investment in provider competency is likely to drive broader adoption of standardized, high-quality procedures and may influence payer perceptions regarding the appropriateness and consistency of trigger point injection services.
These dynamics interact in complex ways. For example, the interplay between clinical guideline recommendations on dose reduction and reimbursement limits on session frequency requires providers to carefully sequence treatments and potentially explore alternative agent combinations. Our report dissects these interactions to provide a clear picture of how market participants can adapt their strategies to remain both clinically effective and financially viable.
Strategic Imperatives for 2026 Executives
As we move deeper into the forecast period, executives across the value chain must make decisions that align with the market's underlying structural trends. The 5.85 percent CAGR and the projected expansion to 320.2 million USD by 2032 present clear growth opportunities, but realizing these opportunities requires more than passive participation in a rising tide.
Worldwide Intra-Articular Injection Market
For pharmaceutical and device companies, the data underscores the need for targeted engagement with clinical guidelines and payer policies. Understanding how corticosteroid dosing recommendations and session limits affect product utilization can inform marketing strategies, clinical education programs, and inventory forecasting. For service providers, the competitive landscape analysis highlights the importance of differentiation. With a CR3 of 22.5 percent, the market supports multiple players, but success will depend on demonstrating superior outcomes, efficient workflows, and compliance with the latest policy and guideline frameworks.
Additionally, the growing emphasis on provider training and certification points to an emerging ecosystem where quality metrics and professional credentials may increasingly influence referral patterns and payer contracting. Organizations that invest early in staff development and align their protocols with the most current multi-society guidance will likely secure a more resilient position as the market matures.
Our full Trigger Point Injection Treatment Market research study goes much further than the summary presented here. It contains detailed breakdowns of regional revenue distributions, agent type adoption rates, and indication-specific demand patterns that are essential for precise market entry, partnership evaluation, or investment due diligence. The analysis includes comprehensive competitor profiles, an exhaustive review of regulatory and reimbursement updates, and a forward-looking assessment of how clinical guideline shifts will reshape operational economics over the next several years.
In a market where clinical nuance, policy compliance, and competitive positioning converge, generic data is insufficient. Decision-makers need a granular, verified, and strategically contextualized view of the trigger point injection landscape. The PW Consulting report is designed to deliver exactly that level of insight.
We invite you to access the complete report for a full exploration of the data, the competitive profiles, and the strategic recommendations tailored to your specific role in the market. The full intelligence necessary to navigate 2026 and the forecast period through 2032 awaits.
For detailed analysis of this topic, please visit the official page: Trigger Point Injection Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Push-up Paperboard Tube Market to Hit $261.96M by 2032 with 7.36% CAGR
By pmarketresearch, 2026-09-17
Strategic Intelligence for Sustainable Packaging: Inside the Global Push-up Paperboard Tube Market Forecast 2026-2032
The packaging industry is currently witnessing one of the most significant structural shifts in decades, driven largely by regulatory pressure and consumer sentiment regarding plastic elimination. At the center of this transformation is the push-up paperboard tube, a format that has evolved rapidly from niche alternatives in personal care to a mainstream standard for cosmetics, food, and pharmaceuticals. For executives and supply chain strategists, the 2026 fiscal year represents a critical consolidation point. Whether optimizing procurement or assessing entry into sustainable packaging, understanding the trajectory of push-up paperboard tubes is essential for competitive positioning.
The latest market research released by PW Consulting provides a comprehensive view of this evolving landscape. Drawing on historical data from 2020 through 2025 and projecting forward to 2032, this analysis offers more than surface-level observations. It delivers the analytical rigor required to navigate a market defined by volatility in raw material costs and an increasingly complex regulatory environment. This article outlines the strategic value embedded within the full report, highlighting why immediate access to these insights is necessary for informed 2026 decision-making.
Macro Market Trajectory: Momentum and Valuation
Understanding the scale of opportunity is the first step in strategic planning. The global push-up paperboard tube market has demonstrated a consistent and robust upward trajectory. Over the historical period from 2020 to 2025, the market moved from a valuation of approximately 111.45 million USD to 159.34 million USD. This growth signals more than just a temporary trend; it indicates a structural adoption of paperboard over plastic alternatives across multiple verticals.
Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion. The market is projected to cross 175 million USD in 2026, accelerating toward a valuation of over 261 million USD by 2032. This translates to a compound annual growth rate (CAGR) of 7.36 percent. For strategic planners, this rate underscores the speed at which demand is scaling. It is not merely a linear increase but a momentum driven by fundamental shifts in material preference. The revenue unit remains in millions of USD, providing a clear benchmark for ROI calculations and market entry assessments.
However, raw growth numbers only tell part of the story. The real strategic value lies in understanding where the growth is concentrated and who is capturing value. The full report deconstructs these revenue streams without leaving decision-makers to guess at the drivers behind the headlines.
Segmenting the Opportunity: Material, Application, and Region
Strategic success in the packaging sector depends on precise segmentation. The report provides a granular breakdown of the market by material type, end-use application, and geographic region, allowing firms to identify their specific niche within the broader ecosystem.
Material type analysis reveals a clear preference hierarchy that dictates supplier selection and procurement strategy. Recycled kraft paper continues to dominate the landscape, reflecting the industry-wide push toward circularity and waste reduction. Virgin paperboard maintains a significant presence, particularly where structural integrity or specific cosmetic finishes are required. Specialty laminated paper rounds out the options, often serving high-performance needs where moisture resistance or barrier properties are critical. Each material type carries different cost implications and sustainability credentials, and the report details the revenue share and dynamics for each, enabling buyers to align material choices with corporate sustainability goals.
End-use application segmentation highlights where the demand is most intense. The cosmetics and personal care sector remains the primary driver of demand for push-up tubes, leveraging the format for lip balms, deodorants, and solid cosmetics. Food and beverage applications represent a distinct and growing segment, often driven by regulatory bans on single-use plastics. Pharmaceuticals and health applications add another layer of complexity, requiring specific certifications and barrier properties. By isolating these application streams, the report helps businesses pinpoint which verticals offer the highest growth potential relative to their existing capabilities.
Regional analysis further refines the strategic picture. The market is distributed across Europe, North America, Asia Pacific, Latin America, and the Middle East and Africa. While aggregate regional figures are available in the full dataset, the key takeaway for planners is the variation in maturity and regulatory pressure across these zones. Europe's strong position reflects its early adoption of extended producer responsibility laws, while North America shows dynamic growth linked to state-level EPR expansions. Asia Pacific presents both a manufacturing hub and a growing consumption market. The full report provides the detailed regional revenue splits necessary to model supply chain logistics, tariff exposures, and local market entry strategies.
Worldwide Push-up Paperboard Tube Market
Competitive Landscape: Navigating a Fragmented Ecosystem
The push-up paperboard tube market is characterized by a moderately concentrated competitive landscape. With a CR3 of 18.45 percent and a CR5 of 27.12 percent, no single entity dominates the entire value chain, suggesting ample opportunity for specialized players and regional leaders to thrive. This fragmentation also means that procurement strategies must be sophisticated, balancing quality, customization, and geographic proximity.
Several key companies define the current competitive dynamics, each bringing distinct strengths to the table. Premier Paper Tube, based in Chicago, USA, has carved out a position by offering 100 percent fiber tubes that are PFAS-free and compostable, with a strong focus on customization for cosmetic applications. Similarly, Visican in the UK provides custom eco-friendly cardboard tubes with brandable finishes, catering to brands seeking aesthetic differentiation alongside sustainability. The Packaging Company and GreenWay Containers in the USA both emphasize biodegradable and plastic-free kraft paper solutions, appealing to the zero-waste consumer segment.
Cross-border players add complexity to the sourcing landscape. UCPACK, operating with UK and China capabilities, offers FDA greaseproof and food-grade options with FSC and ISO 9001 certifications, bridging the gap between compliance and customization. In the manufacturing hub of China, companies like All Paper Tube in Shenzhen, MC Packagings, and Fortress Packaging represent the scale and variety available from Asian suppliers, offering wholesale volumes and extensive custom printing options. Fortress Packaging, in particular, highlights the capacity for large-scale biodegradable kraft paper production. Meanwhile, US-based suppliers like SKS Bottle and Packaging and Paper Tube Co. continue to serve the domestic market with ready-made and flush-fit solutions designed to remove plastic from the supply chain.
The full report goes beyond company profiles to analyze how these players are positioning themselves, their capacity constraints, and the strategic implications of sourcing from different regions. For procurement officers, this competitive intelligence is vital for mitigating supply risk and negotiating favorable terms.
Market Dynamics: Regulations, Costs, and Raw Material Volatility
No strategic forecast is complete without addressing the external forces that can disrupt margins and timelines. The 2026 outlook is heavily influenced by regulatory shifts and raw material price fluctuations, both of which are covered in depth within the research.
Worldwide Skin Care Products Tubes Market
Regulation is perhaps the most powerful driver in this market. In the United States, EPR laws have already been enacted in seven states, including California, Colorado, Maryland, Maine, Minnesota, Oregon, and Washington. These laws require producers to manage the collection, recycling, and end-of-life of packaging materials, with fee schedules and implementation details evolving throughout 2026. Furthermore, additional states such as Wisconsin and New Hampshire have introduced packaging EPR bills in late 2025 and early 2026. This patchwork of legislation creates a complex compliance environment that varies by jurisdiction, directly impacting the cost and feasibility of packaging choices. The report analyzes how these regulations are reshaping demand for paperboard tubes as brands seek to minimize EPR fees and liabilities.
Raw material costs present another layer of uncertainty. Data from the Federal Reserve Economic Data indicates that the US Producer Price Index for folding paperboard boxes and packaging components reached 143.503 in March 2026, signaling persistent inflationary pressure in the packaging sector. Regional price disparities also exist; paper board prices in Northeast Asia were observed at 0.22 USD/Kg, while European prices stood at 0.24 USD/Kg in early 2026. Additionally, packaging paper prices in 2025 rose on average by 2.6 percent compared to 2024 levels, with recovered paper prices up by 4.5 percent in the recent period. These fluctuations affect the bottom line for manufacturers and consumers alike. The full report integrates these cost dynamics into the market valuation, helping buyers forecast procurement budgets and hedge against price volatility.
Report Content and Methodology: Actionable Intelligence for 2026
The Worldwide Push-up Paperboard Tube Market report is designed to be a practical tool for strategic planning, not just a data repository. The document covers the base year of 2025 and historical years from 2020 to 2025, providing a solid foundation for trend analysis. The forecast period extends through 2032, allowing for long-term capital allocation and product lifecycle planning.
Readers of the full report will find detailed breakdowns that are essential for building business cases. This includes precise revenue valuations for each segment, allowing for accurate market sizing and share analysis. The segmentation data covers region, material type, and end-use application, providing the granularity needed to identify high-growth niches. The competitive landscape section offers profiles of key players, their headquarters, and their operational focus, giving context to the CR3 and CR5 concentration metrics.
Moreover, the report contextualizes the data within the broader industry environment. By incorporating recent developments in raw material costs and regulatory frameworks, the analysis helps stakeholders stress-test their strategies. Whether a company is evaluating a supplier switch, launching a new eco-friendly product line, or entering a new geographic market, the report provides the evidence base required to support these initiatives. The methodology ensures that all figures are consistent and comparable, reducing the risk of misinformed decisions based on fragmented data sources.
Strategic Takeaways for Decision Makers
As the market moves toward a valuation exceeding 261 million USD by 2032, the window for strategic positioning is open but narrowing. The combination of a 7.36 percent CAGR, evolving EPR regulations, and raw material inflation means that indecision carries a cost. Brands that lock in sustainable packaging solutions early may benefit from supply security and regulatory compliance, while late movers may face higher costs and capacity constraints.
The insights within this market research enable leaders to answer critical questions: Which material type offers the best balance of cost and sustainability for your specific application? How do regional regulations in the US and Europe impact your total cost of ownership? What is the competitive capacity landscape, and where are the bottlenecks likely to emerge? By accessing the full report, stakeholders gain the granular data necessary to transform these macro trends into micro-level actions.
The push-up paperboard tube market is not just about packaging; it is about aligning product delivery with a rapidly changing expectations of environmental stewardship and regulatory compliance. For those ready to move beyond general market awareness into precise strategic execution, the detailed intelligence contained in this report is indispensable. Accessing the full analysis ensures that your 2026 planning is grounded in the most current and comprehensive data available.
For the complete dataset, including all regional revenue splits, segment valuations, and competitive profiles, we invite you to explore the full Worldwide Push-up Paperboard Tube Market report. Equip your organization with the intelligence needed to lead in the sustainable packaging era.
For detailed analysis of this topic, please visit the official page: Worldwide Push-up Paperboard Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cell Fenders Market to Hit $225.39M in 2025, Projects 4.85% CAGR to 2032
By pmarketresearch, 2026-09-17
Navigating the Next Wave: Strategic Insights into the Global Cell Fenders Market (2026–2032)
The marine infrastructure sector is at a critical inflection point. As global trade volumes stabilize and offshore energy projects accelerate, the demand for reliable vessel protection systems has never been more pronounced. At PW Consulting, we understand that navigating this landscape requires more than just top-line numbers; it demands a granular understanding of operational shifts, regulatory pressures, and competitive maneuvering. Our latest market research report on the Cell Fenders Market is designed to equip stakeholders with the intelligence needed to make informed decisions throughout the forecast period ending in 2032.
This report serves as a comprehensive navigational chart for industry participants, ranging from port authorities and shipyards to manufacturing leaders and investment analysts. By dissecting the market dynamics between the base year of 2025 and the forecast horizon, we provide a clear picture of where value is being created and where risks are lurking. The following analysis highlights the strategic value proposition of our research, offering a glimpse into the depth of data and qualitative insight available in the full publication.
Market Trajectory and Macro Growth Indicators
Understanding the historical trajectory is essential for validating future projections. Our analysis tracks revenue trends from 2020 through the base year of 2025, establishing a robust baseline for predicting performance over the next seven years. The market has demonstrated resilience, recovering from fluctuations observed in the early 2020s to reach significant momentum by 2025. This historical context allows us to model a compound annual growth rate (CAGR) of 4.85% throughout the forecast period extending to 2032.
Such growth is not merely linear; it reflects underlying shifts in maritime activity and infrastructure investment. The valuation landscape shows a clear upward trend, with market size expanding steadily as operators prioritize asset protection against increasingly larger vessels. Our report details these projections without exposing the specific revenue figures for each year, encouraging stakeholders to access the full dataset for precise budgeting and forecasting models. However, the direction is clear: the sector is poised for sustained expansion, driven by replacement cycles in aging port infrastructure and new installations in emerging maritime hubs.
For strategic planners, this growth rate suggests a compounding opportunity. Companies that position themselves now to capture market share during this growth phase will likely secure stronger footholds before the market matures further towards the end of the decade. The report quantifies this opportunity, helping clients assess whether their current capacity aligns with the projected demand surge.
Worldwide Cell Controller Market
Segmentation Dynamics: Type and Application
The Cell Fenders Market is not monolithic. It is divided by product typology and application environment, each carrying distinct profit margins and growth drivers. Our research breaks down the market into key segments including Standard Cell Fenders, Super Cell Fenders, and other specialized variants. Each segment serves different vessel sizes and operational stresses. For instance, the Super Cell category has gained prominence in high-performance marine applications where energy absorption is critical, while standard variants remain prevalent in routine port operations.
Similarly, the application landscape is diverse. Commercial ports represent a significant portion of demand, but adjacent sectors such as shipyards, docks, and offshore oil and gas platforms contribute substantially to the total revenue pool. Our analysis explores how demand variability across these applications affects manufacturers. For example, while commercial ports may offer volume stability, offshore platforms often command higher specifications and pricing power. Understanding the balance between these segments is crucial for companies deciding where to allocate R&D resources.
We avoid publishing specific percentage splits or revenue amounts for these segments in this summary to protect the proprietary nature of our modeling. Instead, we highlight that the interplay between standard and high-performance fenders is shifting. As vessels grow larger, the mix is tilting toward higher-capacity solutions. Clients accessing the full report will gain access to the specific volume and value breakdowns necessary to identify their most lucrative niche within this segmentation matrix.
Regional Landscape and Market Concentration
Geographically, the market is distributed across key regions including Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities. Asia Pacific continues to be a dominant force due to intense port construction and trade activity, while Europe and North America focus heavily on upgrading existing infrastructure to meet higher safety and environmental standards.
Our report examines the regional revenue distribution to highlight where growth is most concentrated. We analyze how local manufacturing capabilities versus import dependencies shape the competitive environment in each geography. For instance, regions with strong local manufacturing bases may see different pricing dynamics compared to those reliant on imported marine infrastructure solutions.
Furthermore, the market exhibits a moderate to high level of concentration among top competitors. Our data indicates that a small group of leading manufacturers controls a significant share of the global revenue stream. This concentration influences pricing power, supply chain stability, and technology adoption rates. Understanding the competitive density in specific regions helps logistics managers and procurement officers anticipate supply constraints or negotiate better terms. The full report provides detailed regional analysis that allows clients to pinpoint growth hotspots without relying on generalized global averages.
Competitive Landscape: Key Players and Strategic Moves
The competitive arena is defined by established marine engineering firms and specialized rubber manufacturers. Our report profiles key companies that are shaping the industry, including ShibataFenderTeam, Trelleborg Marine and Infrastructure, ESC Marine Systems, Lion Rubber Industries, Nanjing Deers Industrial, SunHelm Marine, Qingdao Jier Engineering Rubber, and The Rubber Company.
Each of these players brings distinct capabilities to the table. For example, ShibataFenderTeam is known for its CSS Cell Fenders with hollow cylindrical body designs, catering to high-performance needs with models reaching significant heights. Trelleborg focuses on SCK Cell Fenders, emphasizing simplicity and a long track record in protection infrastructure. ESC Marine Systems offers comprehensive systems manufactured to PIANC guidelines, while manufacturers like Nanjing Deers and SunHelm Marine are prominent in the Asia-Pacific supply chain, with SunHelm recently notable for compliance advancements.
Cell Fenders Market
Strategic moves among these entities are indicative of broader market trends. Recent industry developments highlight this dynamic. In late 2025, ShibataFenderTeam secured a major supply contract for the largest CSS3000 Cell Fenders to an FLNG facility in Malaysia, signaling confidence in large-scale offshore projects. Meanwhile, SunHelm Marine commenced production of EUDR-compliant Fixed Rubber Fenders, marking a first for the industry in China and addressing emerging regulatory requirements. Additionally, Nanjing Deers Industrial successfully delivered fender systems for replacement projects in Southeast Asia, underscoring the ongoing maintenance and upgrade cycle in established ports.
Our analysis goes beyond profiling; it evaluates how these companies are positioning themselves relative to one another. Are they competing on price, quality, or compliance? The report assesses their product portfolios, geographic reach, and recent project wins to help clients identify potential partners or competitors they may face in the marketplace.
Industry Dynamics: Regulation, Materials, and Standards
External factors are exerting significant pressure on the Cell Fenders Market. Three critical dynamics stand out in our analysis: regulatory compliance, raw material volatility, and evolving technical standards.
Regulatory Compliance: The EU Deforestation Regulation (EUDR) is a pivotal development. It requires due diligence for natural rubber products, including marine fenders, to ensure they are deforestation-free. With enforcement scheduled to begin in December 2026, manufacturers and suppliers must adapt their supply chains immediately. This regulation affects not only European operators but also global suppliers wishing to access the EU market. Our report discusses the implications of EUDR compliance costs and the potential for market exclusion for non-compliant entities.
Raw Material Costs: Natural rubber prices have experienced fluctuations, trading approximately between USD 1.40 and 1.70 per kg recently. These movements impact production costs directly. Industry data suggests that manufacturers may pass on potential price increases of around 10% to end-users. For procurement managers, understanding these cost drivers is vital for contract negotiation and budget forecasting. Our research integrates these cost pressures into the financial outlook, helping clients model sensitivity scenarios.
Technical Standards: The PIANC Fender Guidelines 2024 (WG211) update supersedes previous 2002 guidelines, introducing new design approaches. A transition period was allowed until November 2025 for supplier catalogs to adjust. This shift impacts how fenders are specified and tested. Companies that fail to align with the new standards risk obsolescence or liability issues. Our report details the scope of these changes and their impact on product design and certification requirements.
By weaving these dynamics into the market forecast, we provide a realistic view of the headwinds and tailwinds facing the industry. Ignoring these factors can lead to strategic missteps, which is why our report places them at the center of the analysis rather than treating them as footnotes.
Operational Content and Strategic Utility
Beyond market sizing and trend identification, this report is built for operational utility. It contains actionable content designed to support decision-making at various levels of an organization.
- Supplier Evaluation Frameworks: We provide criteria for assessing fender manufacturers based on capacity, compliance, and technical capability. This helps procurement teams shortlist partners who can meet both current specifications and future regulatory requirements.
- Risk Assessment Models: The report includes analysis of supply chain vulnerabilities related to raw material sourcing and geopolitical factors in key manufacturing regions. This enables risk managers to diversify sourcing strategies effectively.
- Investment Guidance: For investors looking at the marine infrastructure sector, the report delineates growth pockets and potential saturation points. It helps in identifying which sub-segments offer the best risk-adjusted returns over the forecast period.
- Strategic Planning Inputs: Executives can use the trend analysis to plan capacity expansions, R&D focus areas, and market entry strategies. The data supports scenario planning for different growth trajectories and regulatory outcomes.
We understand that data without context is merely noise. Therefore, our report integrates qualitative insights with quantitative data to tell a coherent story about the market's evolution. Whether you are a port operator planning a quay replacement or a manufacturer considering a new product line, the insights herein are tailored to reduce uncertainty.
Conclusion: The Value of Complete Intelligence
The Cell Fenders Market is evolving under the influence of stricter regulations, material cost pressures, and shifting maritime traffic patterns. Success in this environment depends on access to accurate, timely, and deep market intelligence. While this overview highlights the scope and strategic relevance of our findings, the true value lies in the specific data points, regional breakdowns, and competitive assessments contained within the full report.
Decisions made in 2026 will set the course for the remainder of the decade. Relying on outdated models or generalized industry knowledge introduces unnecessary risk. PW Consulting's Cell Fenders Market Report offers the granularity required to navigate these complexities with confidence. We invite industry leaders, investors, and strategic planners to access the complete study to unlock the full potential of these insights. The detailed segmentation data, proprietary forecasts, and comprehensive company profiles available in the full document provide the definitive guide for capitalizing on the opportunities ahead.
For detailed analysis of this topic, please visit the official page: Cell Fenders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Synthetic Amino Acids Market Eyes USD 35,013.75 Million by 2032, 6.55% CAGR
By pmarketresearch, 2026-09-17
Navigating the Synthetic Amino Acids Market: Strategic Intelligence for 2026 and Beyond
The global synthetic amino acids market stands at a critical inflection point as the decade progresses. Over the historical period from 2020 to 2025, the industry has demonstrated remarkable resilience and sustained expansion, with total market revenue climbing from approximately USD 16.4 billion to over USD 22.4 billion. Looking ahead through the forecast horizon of 2026 to 2032, the trajectory points toward a robust compound annual growth rate of 6.55 percent, ultimately positioning the market to surpass USD 35 billion by the close of the period. For executive leadership teams, procurement strategists, and R&D directors, this is not merely a macroeconomic statistic. It represents a complex landscape of shifting feedstock economics, evolving regulatory frameworks, and intensifying competitive dynamics that will directly impact margin structures, supply chain resilience, and long-term portfolio positioning.
As organizations prepare their 2026 strategic roadmaps, the ability to discern signal from noise in this sector has never been more vital. Market participants are operating in an environment where raw material price volatility intersects with regional production cost disparities, where consolidation pressure coexists with niche specialization opportunities, and where the balance between synthetic and fermentation-derived pathways continues to reshape competitive advantages. The latest comprehensive market intelligence, synthesized by PW Consulting, is designed to equip decision-makers with the granular analysis, actionable frameworks, and forward-looking scenarios required to navigate these complexities with confidence.
Macro Trajectory and the Imperative for Precision Intelligence
The eight-year forecast window reveals a market defined by steady, compounding growth rather than abrupt disruption. From a baseline of USD 24.34 billion in 2026, the sector is projected to scale progressively, crossing USD 26.60 billion in 2028, exceeding USD 29.85 billion by 2030, and reaching USD 35.01 billion in 2032. This expansion is underpinned by accelerating demand across industrial nutrition, clinical applications, and specialized chemical formulations, yet the underlying drivers vary significantly by region and end-use vertical. Understanding which segments will capture disproportionate value requires more than high-level trend extrapolation. It demands a structured dissection of production economics, pricing mechanisms, capacity utilization patterns, and the strategic responses of incumbent manufacturers.
Synthetic Vitamin E Market
Recent quarters have already highlighted the sensitivity of this market to upstream variables. Raw material inputs, including soybean oilseeds, wheat, and corn, have experienced pronounced price fluctuations driven by competing agricultural demand and logistical bottlenecks. In chemical synthesis pathways, ammonia constitutes an estimated sixty to seventy percent of operating costs for hydrogen cyanide production, making feedstock procurement a decisive factor in overall cost competitiveness. Regional pricing divergences further complicate procurement strategies, with benchmark prices in the United States, China, and Germany reflecting distinct local supply-demand balances and infrastructure constraints. Organizations that lack detailed visibility into these cost architectures risk suboptimal sourcing decisions, squeezed gross margins, and vulnerability to sudden market shifts.
Worldwide Synthetic Amino Acids Market
Regulatory scrutiny adds another layer of complexity. While synthetic amino acids remain indispensable to numerous high-value applications, certain jurisdictions are intensifying evaluations of chemically derived variants, alongside growing consumer and institutional preferences for fermentation-based or plant-sourced alternatives. Navigating this regulatory mosaic requires a nuanced grasp of compliance timelines, certification pathways, and the commercial implications of shifting procurement mandates across different territories. Strategic planning that ignores these dynamics will inevitably fall short.
Competitive Architecture: Consolidation, Specialization, and Strategic Realignment
The competitive landscape is characterized by a concentrated core of globally integrated producers alongside a diverse cohort of regional specialists and emerging capacity players. The top three firms command approximately forty-two percent of total market revenue, while the top five collectively account for just over fifty-eight percent. This concentration reflects the capital intensity of large-scale synthesis and fermentation operations, the importance of established quality certifications, and the value of entrenched customer relationships across feed, food, pharmaceutical, and nutraceutical channels. Yet concentration does not equate to stagnation. The market is actively reshaping itself through portfolio adjustments, targeted partnerships, and strategic divestitures that redefine competitive positioning.
Leading global players such as Ajinomoto Co., Inc. and Evonik Industries AG continue to anchor the industry through extensive production networks and diversified product portfolios. Ajinomoto leverages decades of fermentation and chemical synthesis expertise to supply high-purity synthetic and feed-grade amino acids, including methionine, lysine, threonine, and tryptophan, across animal nutrition, food, and pharmaceutical applications. Evonik, meanwhile, has sharpened its strategic focus on specialty chemicals for precision animal nutrition, offering flagship products like MetAMINO, Biolys, and ThreAMINO while integrating sustainability metrics into its operational framework. Notably, Evonik has recently undertaken a restructuring of its keto and pharmaceutical amino acid business, discontinuing certain legacy operations while simultaneously expanding its GMP-certified portfolio for clinical and pharmaceutical customers in Europe and North America. This dual move illustrates how incumbents are actively pruning legacy exposures to double down on higher-margin, compliance-intensive segments.
In Asia, major integrated producers are scaling capacity to meet both domestic and export demand. CJ CheilJedang Corporation and Daesang Corporation from South Korea, alongside large-scale Chinese manufacturers such as Fufeng Group Limited and Meihua Holdings Group Co., Ltd., have built substantial production footprints for lysine and other feed-grade amino acids. These organizations benefit from proximity to key agricultural feedstocks and increasingly sophisticated manufacturing capabilities. Their growth strategies often hinge on balancing volume-driven feed applications with higher-value food and nutraceutical segments, requiring careful calibration of production allocation and pricing architecture.
Parallel to these volume-oriented players, a distinct tier of high-purity specialists is carving out defensible niches. Amino GmbH, Kyowa Hakko Bio Co., Ltd., and Wacker Chemie AG focus on pharmaceutical, biotech, and specialty-grade synthetic amino acids, where regulatory compliance, batch consistency, and customized formulation capabilities command premium positioning. The strategic alignment between Croda International and Amino GmbH, announced in late 2025, exemplifies the trend toward collaboration between specialty suppliers and broader life sciences portfolios, reinforcing the value of targeted manufacturing partnerships for pharmaceutical-grade supply chains. Sumitomo Chemical Co., Ltd. further contributes to this ecosystem through its chemical synthesis capabilities, supporting industrial and pharmaceutical applications that demand precise intermediate and derivative production. ADM, as a diversified agribusiness, integrates amino acid production into a broader nutrition portfolio, leveraging scale and cross-segment synergies to serve feed and food customers.
For 2026 planning, the critical takeaway is that competitive advantage will not be determined solely by capacity size. It will increasingly depend on portfolio flexibility, regulatory readiness, sourcing resilience in the face of feedstock volatility, and the ability to align product grades with the most attractive margin pools. Organizations that attempt to compete across all segments without clear differentiation risk compression from both consolidated incumbents and agile specialists.
Inside Our Worldwide Synthetic Amino Acids Market Research
The newly released PW Consulting market research report is built to translate these macroeconomic signals and competitive shifts into actionable corporate strategy. Rather than offering surface-level trend summaries, the study provides a comprehensive operational playbook structured around the decision points that matter most to 2026 planning cycles. The analysis begins with a rigorous reconstructed historical baseline spanning 2020 through 2025, establishing a transparent foundation for the forecast model that extends through 2032. This historical reconstruction is not merely a retrospective exercise. It serves as a diagnostic tool to identify inflection points, validate growth assumptions, and isolate the structural factors that have consistently influenced revenue generation across different product grades and end-use channels.
A core strength of the report is its detailed segmentation architecture, which dissects the market across product types, application verticals, and regional demand centers without sacrificing analytical depth. Decision-makers will find focused assessments of methionine, lysine, threonine, glutamic acid, and other amino acid categories, each evaluated through the lens of demand drivers, production technology pathways, pricing behavior, and margin dynamics. The application-side analysis examines how animal feed, food and beverages, pharmaceuticals, and nutraceuticals and cosmetics utilize synthetic amino acids, highlighting the distinct procurement criteria, regulatory hurdles, and value proposition thresholds that define each vertical. By mapping these segments against the broader forecast trajectory, the report enables users to pinpoint where volume growth, value growth, and margin expansion are most likely to converge, and where commoditization pressures may erode returns.
Regional analysis is presented with an emphasis on competitive intensity, production cost structures, and demand localization rather than simplistic market share rankings. The study explores how Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa differ in terms of feedstock access, manufacturing maturity, regulatory environments, and downstream consumption patterns. This geographic granularity is essential for organizations evaluating capacity expansion, export strategies, or supply chain diversification, as it surfaces the relative attractiveness of different operating environments under varying commodity price and trade policy scenarios.
Beyond segmentation, the report delivers a thorough competitive profiling exercise that maps the strategic postures, technological capabilities, and recent operational moves of the leading participants shaping the market. Each profiled company is assessed for its production methodology focus, product grade coverage, geographic reach, and recent portfolio or restructuring actions. This competitive intelligence is contextualized within broader industry dynamics, including capacity utilization trends, innovation pipelines, and alliance activity, enabling readers to anticipate how rival strategies may alter pricing power, channel access, or customer loyalty in the near term. The inclusion of recent developments, such as GMP portfolio expansions, specialized manufacturing partnerships, and targeted business line restructurings, ensures that the analysis reflects the market as it is actively evolving, not as it existed in prior cycles.
The report also tackles the operational and financial variables that frequently determine whether strategic initiatives succeed or stall. Dedicated sections examine the impact of raw material price volatility, ammonia cost exposure in chemical synthesis routes, and regional pricing differentials on procurement optimization and cost management. These insights are paired with practical frameworks for evaluating make-versus-buy decisions, qualifying alternative suppliers, and structuring hedging or long-term contracting strategies that mitigate exposure to unpredictable input markets. Regulatory considerations are addressed with equal rigor, outlining the implications of compliance scrutiny on synthetic variants, the growing relevance of certification standards across pharma and nutraceutical applications, and the strategic trade-offs involved in balancing synthetic efficiency against shifting preferences for fermentation-derived alternatives in certain customer segments.
Finally, the study is designed with scenario flexibility in mind. Recognizing that macroeconomic conditions, trade flows, and regulatory timelines can shift rapidly, the analytical framework supports multiple planning assumptions. Users can stress-test their strategies against variations in feedstock pricing, regional demand acceleration or deceleration, and changes in competitive concentration. This scenario-oriented approach ensures that the intelligence is not static but functions as a living decision-support tool throughout the 2026 planning and execution cycle.
Strategic Imperatives for 2026 Decision-Makers
Translating market intelligence into competitive advantage requires disciplined prioritization. The following strategic considerations emerge as central for organizations positioning themselves in the synthetic amino acids market over the coming year:
- Align product grade portfolios with margin pools rather than volume alone. High-purity pharmaceutical, nutraceutical, and specialty-grade applications increasingly reward compliance readiness, batch consistency, and customization capabilities, while bulk feed-grade segments remain highly price-sensitive and structurally competitive. Evaluating where your organization can credibly compete on quality and where it must compete on cost is essential for resource allocation.
- Build feedstock resilience into procurement and production planning. Given the sensitivity of operating costs to agricultural commodity fluctuations and ammonia price exposure in certain synthesis routes, companies should evaluate diversified sourcing options, regional cost arbitrage opportunities, and contractual structures that reduce vulnerability to sudden input shocks.
- Anticipate regulatory divergence across territories. As scrutiny of synthetic variants and preferences for fermentation-based alternatives continue to evolve, market participants must monitor compliance requirements, certification timelines, and customer procurement mandates by region. Early alignment with regulatory trends can safeguard market access while late reactions risk stranded capacity or lost contracts.
- Assess competitive moves as strategic signals, not just operational events. Portfolio expansions into GMP-certified applications, divestitures of low-margin legacy lines, and targeted partnerships for pharmaceutical-grade manufacturing all indicate where value is migrating within the industry. Tracking these moves enables proactive positioning rather than reactive catch-up.
- Use regionally nuanced analysis to guide capacity and distribution decisions. Demand density, logistics costs, local feedstock advantages, and regulatory climates vary substantially across markets. A one-size-fits-all expansion or sourcing strategy will underperform relative to a geographically calibrated approach that accounts for these differences.
Accessing the Complete Intelligence Architecture
The synthetic amino acids market in 2026 will reward organizations that combine strategic clarity with operational precision. Sustained growth, competitive concentration, feedstock complexity, and evolving regulatory expectations create an environment where high-level summaries are insufficient, and boutique intuition is too risky. Decision-makers require a structured, data-anchored analysis that connects macro forecasts to segment-level dynamics, competitive behavior, and actionable planning frameworks.
This article has provided a strategic preview of the themes, structural forces, and competitive shifts that define the current market landscape. The full dataset, detailed segment assessments, regional breakdowns, competitive profiles, pricing and cost analyses, and scenario-based planning tools are available in the complete PW Consulting Worldwide Synthetic Amino Acids Market research report. Readers seeking to translate these insights into concrete 2026 decisions, including capacity planning, sourcing optimization, portfolio rebalancing, and competitive positioning, are encouraged to access the full study for comprehensive intelligence and granular market data.
For detailed analysis of this topic, please visit the official page: Worldwide Synthetic Amino Acids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com