

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dual Mode Automated Forklifts Market Hits $685.4M in 2025, Set for 14.25% CAGR to 2032

Navigating the Dual Mode Automated Forklifts Market: A Strategic Forecast for 2026 and Beyond
The material handling landscape is undergoing a seismic shift. As we move past the historical trajectory of the early 2020s, the industry is no longer asking whether automation is inevitable. The question has evolved to how organizations can seamlessly integrate autonomous capabilities with existing manual workflows without disrupting operations or inflating capital expenditure.
PW Consulting's latest Dual Mode Automated Forklifts Market Report provides a comprehensive strategic roadmap for this transition. Grounded in extensive primary research and validated market modeling, this study is designed for executives who require actionable intelligence to navigate the 2026-2032 forecast period. This article serves as a strategic preview of the market forces, competitive dynamics, and operational imperatives that define the current era of material handling innovation.
The Macro Trajectory: Sustained Valuation Expansion
The scale of the opportunity is underscored by the consistent expansion observed over the historical cycle. The overall market revenue has demonstrated robust growth, climbing from USD 245.67 Million in 2020 to USD 535.11 Million by 2024. This acceleration reflects a fundamental reordering of priorities within warehousing, distribution, and manufacturing sectors, driven by the need for resilience in supply chains and the imperative to optimize labor-intensive processes.
Forecasting models project a continued upward trajectory, with the market expected to reach USD 786.64 Million in 2026 and expand further to USD 1,742.18 Million by 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 14.25% throughout the forecast period. For strategic planners, this rate signals more than just volume expansion; it indicates a maturing ecosystem where dual-mode technology is transitioning from a niche novelty to a standard operational requirement across diverse industrial verticals.
Such a trajectory suggests that early movers who align their capital procurement cycles with these adoption curves will secure significant operational leverage. The report dissects the drivers behind this valuation surge, offering granular insights into the economic variables that will dictate procurement cycles through 2032.
Defining the Dual Mode Advantage
Dual mode automated forklifts represent a critical intersection of flexibility and efficiency. Unlike fully autonomous or fully manual assets, these machines are engineered to switch between autonomous operation and manual control, often via a simple interface mechanism. This hybrid capability addresses one of the most persistent pain points in warehouse automation: the rigidity of single-mode solutions.
In environments characterized by fluctuating throughput, mixed traffic, or seasonal peaks, the ability to deploy a single asset class for both high-volume automated runs and flexible manual interventions reduces fleet complexity. It mitigates the risk of stranded assets during low-volume periods while preserving the throughput benefits of automation during high-demand cycles. Our analysis highlights how this operational elasticity is reshaping total cost of ownership (TCO) calculations, moving the conversation beyond upfront sticker prices to lifecycle value.
Regulatory and Operational Dynamics
The deployment of dual-mode and automated forklifts does not occur in a vacuum. A complex web of regulatory standards and operational constraints is shaping the adoption landscape. As of late 2025 and into 2026, compliance has become a central pillar of procurement strategy.
Key industry standards such as ANSI/ITSDF B56.5-2024 are defining rigorous safety requirements for driverless automatic guided industrial vehicles and the automated functions of manned industrial vehicles. With effective requirements rolling out, organizations must ensure that their fleet selections align with these updated protocols to mitigate liability and ensure worker safety. Similarly, ISO 3691-4 continues to set the benchmark for the safety of driverless industrial trucks, mandating robust obstacle detection and emergency stop functionalities.
Dual Mode Automated Forklifts Market
Beyond compliance, the macroeconomic backdrop of labor dynamics is a potent catalyst. Rising operator wages and persistent labor shortages have intensified the need for solutions that can reduce dependency on skilled manual operators while enabling 24/7 operation capabilities. Dual-mode forklifts address this by automating repetitive, high-fatigue tasks while retaining the flexibility to utilize human operators for complex decision-making or case picking scenarios. The report details how these factors are influencing segment preferences and capital allocation strategies across different operational contexts.
Competitive Landscape and Innovation Velocity
The market is characterized by a concentrated yet dynamic competitive environment. The top three companies command a significant share of the market, while the top five firms collectively hold a substantial portion of market revenue. This concentration indicates a market where established players leverage extensive distribution networks and deep engineering expertise to maintain leadership, yet it also suggests room for disruptive innovation as technology barriers evolve.
Several key players are actively defining the competitive frontier through product innovation and strategic expansion. Crown Equipment Corporation has been pivotal in offering DualMode automated solutions, including the R 1000 Series reach trucks and T 1000 Series tow tractors. These assets are designed to switch between autonomous and manual operation seamlessly, catering to facilities that require versatile fleet management.
Hyster-Yale Materials Handling and Yale Materials Handling are pushing the boundaries of reach and functionality. Hyster provides dual-mode pantograph robotic reach trucks capable of autonomous operation at heights exceeding 400 inches, with the option to switch to manual mode. Yale offers dual-mode pantograph automated reach trucks, noted as first-of-their-kind solutions for high-rack storage, providing an easy switch between autonomous and manual modes. Recent developments underscore this velocity: in September 2025, Hyster launched the new Hyster Atlas automated lift truck platform, featuring drag-and-drop setup for tow tractors and enhanced usability.
Linde Material Handling, part of the KION Group, continues to expand its automated portfolio. In June 2025, Linde added new models to its automated forklift range, including the K MATIC k VNA turret truck, R-MATIC k reach truck, and L MATIC AC k pallet stacker. Furthermore, in November 2025, Linde unveiled a new automated counterbalance forklift, the E-Matic, with pre-series projects planned for 2026 and a series release anticipated in 2027. These timelines signal a tightening product cadence that procurement teams must monitor to avoid obsolescence risks.
The Raymond Corporation also contributes to the diversity of the market with its Automated Transtacker (TRT), which features dual-mode functionality for automated full pallet handling or manual case picking. This variety of solutions highlights that dual-mode is not a monolithic technology but a spectrum of applications tailored to specific warehouse geometries and workflow requirements.
Segmentation Trends and Deployment Realities
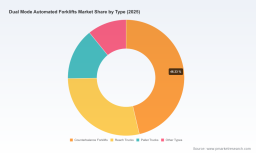
While the overall market growth is compelling, the value of this report lies in its dissection of how demand is distributed across types, applications, and regions. The data reveals distinct preferences that should inform fleet planning. Forklift types such as Counterbalance Forklifts and Reach Trucks represent significant portions of market activity, reflecting their ubiquity in standard warehouse operations. Pallet Trucks and other specialized types further diversify the mix, addressing niche handling requirements.
In terms of application, Warehousing and Distribution stands out as a primary driver of demand, followed by Manufacturing, Logistics and Freight, and Cold Storage. Each application presents unique challenges: cold storage environments demand ruggedized solutions capable of operating in sub-zero temperatures, while manufacturing floors often require equipment that can navigate mixed traffic with high precision. The report explores how dual-mode capabilities are being tailored to these specific verticals, helping decision-makers match asset capabilities to environmental constraints.
Regional dynamics also play a crucial role. North America, Europe, and Asia Pacific represent substantial market bases, while Latin America and the Middle East and Africa are emerging zones of activity. The report provides high-level directional insights into these regional footprints, enabling global operators to prioritize deployment strategies based on localized adoption rates and infrastructure readiness. However, to truly capitalize on these trends, executives need the detailed segmentation data that maps revenue splits and growth nuances across every category and geography.
Strategic Value of the Full Analysis
The preview provided here outlines the structural forces shaping the Dual Mode Automated Forklifts Market. Yet, the strategic depth required to make high-stakes procurement and investment decisions demands a more granular examination. PW Consulting's full report delivers this by providing a comprehensive toolkit for market intelligence.
The report includes detailed profiles of key companies, dissecting their product pipelines, strategic positioning, and recent developments that may impact competitive dynamics. It offers a thorough analysis of market drivers, restraints, and opportunities, allowing stakeholders to stress-test their assumptions against evolving industry conditions. Furthermore, the study incorporates a robust competitive benchmarking framework, enabling organizations to evaluate their positioning relative to market leaders and identify potential partnership or acquisition targets.
For supply chain directors, operations managers, and strategic planners, the report serves as a decision-support artifact. It moves beyond descriptive analysis to offer prescriptive insights. By understanding the interplay between regulatory shifts, labor economics, and technological advancements, organizations can build agile fleets that are resilient to disruption and optimized for efficiency.
Conclusion
The era of rigid, single-mode material handling is giving way to a more flexible, responsive, and automated future. The projected market expansion to USD 1,742.18 Million by 2032 underscores the magnitude of this transformation. Success in this landscape will depend on the ability to interpret complex market signals, anticipate regulatory requirements, and select technologies that offer genuine operational flexibility.
Forklift Trucks Market
This article has highlighted the broad strokes of the market trajectory, the competitive intensity among major players, and the critical role of regulatory and labor dynamics. However, the full strategic picture requires access to the complete dataset, segment-level analysis, and forward-looking scenario modeling contained within PW Consulting's Dual Mode Automated Forklifts Market Report. We invite industry leaders to explore the full publication to secure the comprehensive intelligence necessary to drive informed decisions for the 2026-2032 horizon and beyond.
For detailed analysis of this topic, please visit the official page: Dual Mode Automated Forklifts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com