

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Expectoration Machine Market to Reach $792.27 Million by 2032 at 8.12% CAGR

Navigating the Respiratory Critical Care Frontier: Strategic Insights into the 2026 Global Expectoration Machine Market
The global healthcare landscape is undergoing a structural transformation driven by an aging population, the rising prevalence of neuromuscular and chronic respiratory conditions, and an accelerated shift toward value-based care. At the intersection of these macro trends lies a highly specialized yet increasingly vital segment: the Worldwide Expectoration Machine Market. As medical institutions and home care providers confront the clinical imperative of effective airway clearance, expectoration machines have evolved from niche therapeutic tools into essential components of respiratory management protocols. This industry is no longer defined solely by incremental engineering improvements; it is being reshaped by reimbursement policy realignment, regulatory classification frameworks, and intensifying competitive consolidation.
Our recently released Worldwide Expectoration Machine Market research delivers a comprehensive, decision-grade examination of this sector, spanning historical performance from 2020 through 2025 and projecting forward across the 2026 to 2032 forecast window. The analysis is engineered specifically for executive teams, product strategists, clinical procurement leaders, and investment professionals who require granular operational intelligence rather than surface-level market summaries. By mapping demand elasticity across care environments, dissecting product architecture shifts, and evaluating the evolving regulatory and reimbursement terrain, this report provides a strategic blueprint for navigating a market characterized by both robust growth and complex stakeholder dynamics.
Macro Trajectory and Growth Architecture
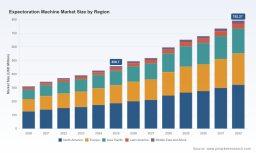
The foundation of any forward-looking strategy begins with a clear understanding of market momentum. Over the past half-decade, the expectoration machine sector has demonstrated consistent expansion, moving from a 2020 baseline of $310.45 million to a 2025 valuation of $458.70 million. This trajectory reflects sustained adoption of mechanical insufflation-exsufflation (MIE) technologies, broader clinical recognition of airway clearance as a critical intervention for patients with impaired cough reflexes, and ongoing procurement modernization across acute and post-acute care facilities. The momentum is projected to continue through the end of the decade, with the market advancing to $494.23 million in 2026 and approaching $792.27 million by 2032.
Worldwide Expectoration Machine Market
This expansion is underpinned by a compound annual growth rate of 8.12 percent across the forecast horizon, signaling a market that is not merely recovering from historical disruptions but entering a structurally elevated growth phase. Several forces are converging to sustain this trajectory. First, clinical protocols are increasingly standardizing airway clearance interventions for neuromuscular diseases, bronchiectasis, and post-surgical pulmonary complications, expanding the addressable patient population. Second, healthcare delivery models are shifting toward decentralized and home-based care, creating demand for compact, user-friendly, and remotely manageable expectoration systems. Third, manufacturers are investing in integrated device ecosystems that combine cough assistance with broader respiratory support functionalities, thereby increasing clinical utility and procurement stickiness. The strategic implication for market participants is unambiguous: growth will increasingly favor organizations that align product development with care-pathway integration, reimbursement navigability, and real-world usability.
Strategic Segmentation: Where Value Is Being Created
A high-level revenue curve tells only part of the story. The true strategic value of this research lies in its dissection of how demand is distributed across product architectures, end-user environments, and geographic markets. Understanding these allocation patterns enables executives to optimize R&D pipelines, refine pricing architectures, and design targeted commercial strategies.
Product Architecture and Engineering Differentiation
The market divides into two primary mechanical paradigms: automatic mechanical in-exsufflation devices and manual mechanical in-exsufflation devices. Automatic systems dominate the revenue conversation by a considerable margin, reflecting their integration into hospital-grade respiratory workflows, their ability to deliver repeatable and programmable cough simulations, and their alignment with clinical staffing constraints. Manual devices, while generating lower aggregate revenue, maintain a distinct presence in settings where portability, cost sensitivity, and clinician-directed control are prioritized. The engineering frontier is shifting toward hybrid capabilities, improved pressure regulation algorithms, and interfaces that reduce clinician training burden. Companies that can demonstrate superior outcomes in secretion clearance efficiency, patient tolerance, and interface ergonomics are positioning themselves for durable share gains.
End-User ecosystems and Procurement Realities
Demand is not evenly distributed across care settings. Hospitals and clinics represent a substantial share of current procurement, driven by acute-care utilization, in-patient respiratory management, and the availability of specialized clinical staff. Home care settings constitute an equally critical and rapidly expanding demand pool, reflecting the broader migration of chronic respiratory management outside institutional walls. In home environments, device selection is heavily influenced by usability, patient and caregiver training requirements, service coverage, and reimbursement eligibility. Rehabilitation centers, while smaller in relative scale, represent a high-value niche where repeated therapeutic sessions and specialized respiratory programs create steady utilization cycles. Each end-user segment demands a different commercial playbook: hospital sales require clinical evidence packages, group purchasing organization engagement, and service-level agreements; home care distribution depends on durable medical equipment channels, patient support infrastructure, and reimbursement clarity; rehabilitation procurement emphasizes therapy integration and operational durability.
Geographic allocation and regional maturity curves
Regional demand patterns reveal a mature, high-capacity market in North America, where established clinical adoption, reimbursement infrastructure, and a dense concentration of respiratory therapy provider networks support sustained utilization. Europe follows as a substantial market, characterized by diversified national procurement systems, varying reimbursement environments, and strong clinical advocacy for airway clearance standardization. Asia Pacific represents a growth-intensive region where expanding healthcare access, rising chronic disease awareness, and local manufacturing capabilities are accelerating adoption curves. Latin America and the Middle East and Africa, while smaller in current scale, are emerging as incremental growth zones where targeted clinical education, distributor partnerships, and adjusted pricing architectures can unlock meaningful demand over time. The strategic takeaway is that geographic expansion cannot rely on uniform playbooks; each region requires tailored engagement models that account for procurement governance, reimbursement pathways, and clinical ecosystem maturity.
Competitive Landscape and Enterprise Positioning
The expectoration machine market is marked by a concentrated yet dynamically contested competitive field. Our analysis indicates that the top three players command approximately 64.85 percent of market revenue, while the top five extend their collective footprint to roughly 81.4 percent. This concentration signals mature competitive dynamics in the core revenue tiers, but it does not imply stagnation. Instead, it highlights a landscape where incumbents defend share through clinical reputation, regulatory clearances, and broad respiratory portfolios, while challengers and regional specialists compete through product differentiation, targeted usability improvements, and strategic distribution partnerships.
Several enterprise profiles illustrate the competitive archetypes shaping the market. Baxter, operating through its Hillrom platform, brings established clinical brand equity and integrates airway clearance technologies such as the Vest Airway Clearance System and Synclara Cough System into broader hospital respiratory ecosystems. ABM Respiratory Care competes with the BiWaze Cough System, emphasizing dual-airway pathway engineering designed to simulate natural cough mechanics for patients with neuromuscular and respiratory compromise. Koninklijke Philips N.V., through its Respironics lineage, offers the CoughAssist T70 and related MIE devices, leveraging a global respiratory brand and extensive clinical service networks. United Hayek Industries and Hayek Medical maintain a specialized footprint around high-frequency chest wall oscillation and insufflation-exsufflation solutions, including the Hayek RTX oscillator. Dima Italia Srl contributes the PEGASO series, targeting mechanical insufflation-exsufflation bronchial drainage and expectoration support with regional clinical credibility.
The competitive field also includes manufacturers expanding airway clearance through complementary modalities. Electromed promotes the SmartVest Airway Clearance System as a high-frequency chest wall oscillation platform for secretion mobilization. Jinan Qijia Medical Equipment produces airway clearance systems and vest-type sputum expectoration machines for non-invasive respiratory therapy, reflecting the growing capabilities of regional manufacturing hubs. Trudell Medical International offers the AEROBIKA OPEP device, addressing mucus clearance through oscillating positive expiratory pressure. ICU Medical, formerly Smiths Medical, supplies Acapella vibratory PEP therapy systems for patients with secretory management needs. Breas Medical incorporates cough assist and airway clearance devices into a broader respiratory support portfolio, while Air Liquide Medical Systems, through its EOVE offering, delivers mechanical insufflation-exsufflation and related airway clearance solutions. Ventec Life Systems adds another strategic dimension with the VOCSN multi-function ventilator, integrating cough assistance via embedded MIE functionality and illustrating the industry trend toward consolidated respiratory platforms.
Worldwide Phlegm Suction Tube Market
This competitive diversity creates both opportunity and risk. Incumbents with multi-product respiratory portfolios can cross-sell and bundle airway clearance into broader care contracts, but they also face higher expectations for clinical integration and service reliability. Smaller or regionally focused manufacturers can move faster on specialized design and localized service, but they must navigate reimbursement complexity and scale constraints. The 2026 decision-maker must therefore evaluate competitors not only by current revenue share but by their ability to combine regulatory agility, reimbursement navigation, clinical evidence generation, and service coverage into a durable competitive moat.
Regulatory and Reimbursement Dynamics as Strategic Multipliers
Market growth in the expectoration machine sector is deeply intertwined with regulatory classification and reimbursement architecture. In the United States, mechanical insufflation-exsufflation devices are generally classified as Class II medical devices with a 510(k) clearance pathway for airway secretion clearance. This classification framework shapes time-to-market timelines, product documentation expectations, and the competitive barrier to entry for new designs. Organizations that build robust regulatory strategy early can convert clearance velocity into commercial first-mover advantages, particularly when paired with clinical evidence that supports differentiated claims.
Reimbursement policy is equally decisive. Medicare coverage exists for mechanical in-exsufflation devices under HCPCS E0482 for beneficiaries with neuromuscular diseases that cause significant impairment of chest wall and/or diaphragmatic movement resulting in inability to clear retained secretions. This coverage pathway is a critical demand enabler for home and outpatient use, but it also imposes documentation and eligibility requirements that shape procurement behavior. In parallel, HCPCS code A7020 addresses interfaces for cough stimulating devices, with reimbursement possible when the beneficiary owns or is purchasing the mechanical in-exsufflation device. These reimbursement nuances matter because they directly affect patient access, durable medical equipment channel economics, and the commercial viability of home-care device programs. Recent regulatory and market developments continue to reinforce the importance of compliance-forward product strategies. For example, in March 2024, BOC Limited secured ARTG inclusion for a cough assist device designed for in-exsufflation and lung-oscillation airway secretion clearance, classified as Class IIa. Such events highlight how regulatory approvals can unlock regional access and validate clinical positioning, especially in markets where reimbursement eligibility depends on formal device recognition.
For corporate strategy teams, the lesson is clear: reimbursement and regulatory landscapes are not peripheral concerns. They are core pricing and adoption drivers. Product roadmaps should be evaluated through the lens of coverage eligibility, documentation readiness, and the ability to support clinicians and patients in meeting coverage criteria. Commercial teams should align channel incentives with reimbursement navigability, while market access strategies should anticipate policy updates that can expand or contract eligible patient populations.
What the Research Delivers for Executive Decision-Making
This report is structured to convert complex market intelligence into actionable strategic direction. It provides a detailed historical baseline and forward forecast architecture that allows leadership teams to model demand scenarios, calibrate capacity plans, and set realistic revenue expectations across the 2026 to 2032 window. The analysis goes beyond macro totals to examine how product types, end-user settings, and regional markets allocate value, enabling sharper segmentation strategy and resource allocation.
The competitive assessment component delivers more than a company directory. It contextualizes each major participant within broader portfolio strategies, clinical positioning, geographic strengths, and likely strategic moves. This enables benchmarking exercises, partnership evaluations, and competitive response planning. The report also integrates market dynamics analysis that maps regulatory pathways, reimbursement mechanisms, and procurement behaviors into a coherent framework, allowing executives to anticipate structural shifts rather than react to them.
In addition, the research is designed to support practical operational decisions. Product managers can use segmentation insights to prioritize feature development and interface engineering. Commercial leaders can align sales motions with end-user procurement realities and reimbursement conditions. Strategy and corporate development teams can identify consolidation opportunities, partnership targets, and regional entry pathways. Investors and financial analysts can use the growth trajectory, concentration metrics, and market-access dynamics to stress-test assumptions and refine valuation models. By maintaining a disciplined focus on decision-useful intelligence, the report avoids generic commentary and instead delivers the kind of structure that executive teams can immediately apply.
Strategic Imperatives for 2026 and Beyond
Entering 2026, market participants face a set of interconnected imperatives. First, product strategy must increasingly account for care-environment fluidity. Devices that perform well in hospitals but fail in home-care usability or service coverage will face growing resistance as procurement decisions broaden beyond institutional buyers. Second, reimbursement alignment must be treated as a product requirement, not a post-launch afterthought. Coverage eligibility, interface reimbursement pathways, and documentation feasibility will influence adoption speed and channel economics. Third, competitive positioning should be evaluated in terms of ecosystem strength. Manufacturers that can integrate cough assistance into broader respiratory platforms, provide dependable clinical support, and build evidence-based credibility will be better positioned to defend share in a concentrated market. Fourth, regional expansion requires localized realism. High-growth regions will not automatically convert into high-margin opportunities without distributor capability, clinical education, pricing discipline, and regulatory readiness.
The broader implication is that the expectoration machine market is maturing into a strategic domain where engineering excellence, regulatory discipline, reimbursement literacy, and go-to-market precision must operate in concert. Organizations that treat airway clearance as a standalone hardware category will miss the structural forces shaping demand. Those that view it as a care-pathway-enabled solution category will be better equipped to capture durable value.
Conclusion
The Worldwide Expectoration Machine Market is entering a phase where growth is real, competition is structured, and strategic differentiation depends on operational precision. With a forecast compound annual growth rate of 8.12 percent and a market trajectory advancing from $494.23 million in 2026 toward $792.27 million by 2032, the sector offers meaningful expansion potential. Yet the distribution of that opportunity across product types, end-user environments, regions, and competitive tiers is highly nuanced. Success in 2026 and beyond will belong to organizations that can translate macro momentum into targeted segmentation strategy, reimbursement-aware product design, region-specific commercial execution, and defensible competitive positioning.
This research was built to support that decision-making process with depth, clarity, and operational relevance. The full report contains the detailed segmentation breakdowns, competitor benchmarking frameworks, regional demand allocations, reimbursement and regulatory analyses, and forward scenario structures required to guide enterprise strategy with confidence. To access the complete intelligence set and apply it directly to your planning cycle, we invite you to review the full market study and accompanying executive materials.
For detailed analysis of this topic, please visit the official page: Worldwide Expectoration Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com